
 Mobile Imaging Market | 2026-2036
Mobile Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Imaging Market Foresight
Buyer consolidation among hospital networks is repositioning procurement leverage toward integrated health systems that demand fleet-wide service contracts. DMS Health leverages its national logistics infrastructure to serve multi-state hospital chains with scheduled mobile MRI rotations. TridentCare anchors its position in post-acute care settings where skilled nursing facilities outsource imaging rather than capitalizing fixed equipment. Cobalt Health competes through same-day scheduling platforms that reduce patient transport costs for emergency departments.
Mobile imaging encompasses transportable diagnostic systems mounted on specialized vehicles or modular platforms, typically incorporating shielded enclosures, onboard power generation, and digital image transmission capabilities rated for clinical-grade resolution. These systems deliver radiology, cardiology, and orthopedic diagnostics directly to patient populations lacking proximate fixed-site infrastructure. X-ray systems and ultrasound systems occupy the largest installed base due to lower capital requirements and faster deployment cycles, while CT scanners command premium margins tied to trauma and stroke protocol demand. Digital and wireless technologies are displacing analog configurations as remote diagnostic networks require DICOM-compliant cloud integration and real-time specialist consultation.
FDA 510(k) premarket notification requirements govern device safety and efficacy for U.S. market entry, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE-marked mobile systems sold in Europe. HIPAA and GDPR frameworks constrain cross-border patient data flows from wireless imaging units, compelling vendors to architect region-specific cloud architectures. Stakeholders must weigh capital deployment against subscription-based service models as reimbursement policies shift toward value-based care metrics and episode-based payment bundles.
Market Dynamics
Hospital procurement consolidation across the United States is concentrating buying power into integrated delivery networks that negotiate fleet-wide service agreements rather than unit-by-unit purchases. This structural shift compresses vendor margins while demanding predictive maintenance platforms and guaranteed uptime clauses.
Growth Catalysts
- Rural Health Clinic Expansion:Federally qualified health centers in underserved counties are deploying mobile CT and MRI units to meet Medicare access standards without fixed-site capital expenditure.
- EU Medical Device Regulation streamlining:CE-marking harmonization for wireless-enabled systems is reducing redundant testing burdens for manufacturers seeking European market entry.
- Cloud-native DICOM architectures:Real-time image transmission to teleradiology networks enables stroke protocol coverage across multiple hospital systems from a single mobile unit rotation.
Market Restraints
- Lead-shielding material cost volatility:Fluctuations in lead and tungsten composite prices directly impact vehicle payload specifications and manufacturing margins.
- Generator and power electronics supply concentration:Onboard diesel and lithium-ion power systems rely on a concentrated supplier base in East Asian manufacturing clusters.
- HIPAA cross-border data friction:Patient image transmission from mobile units across state lines triggers complex compliance architectures that increase operational overhead.
Strategic Opportunities
- Skilled nursing facility outsourcing:Post-acute care operators are abandoning fixed-room X-ray capital in favor of per-scan service models delivered by scheduled mobile rotations.
- Artificial intelligence and edge computing convergence:Onboard inference engines enabling real-time image quality validation and automated protocol selection reduce specialist interpretation delays.
- Inflation Reduction Act equipment incentives:Tax credits for rural healthcare infrastructure are subsidizing mobile imaging fleet deployment in designated health professional shortage areas.
Industry Challenges
- Certified radiologic technologist shortage:Mobile operations require staff willing to travel between sites, competing with fixed-site hospitals for limited state-licensed personnel pools.
- Legacy PACS integration complexity:Hospital information systems built on decade-old architectures resist seamless API connection with cloud-native mobile platforms, requiring costly middleware development.
- Vehicle chassis and shielding certification timelines:DOT weight compliance and state radiological safety inspections extend deployment lead times beyond equipment manufacturing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Imaging Market |
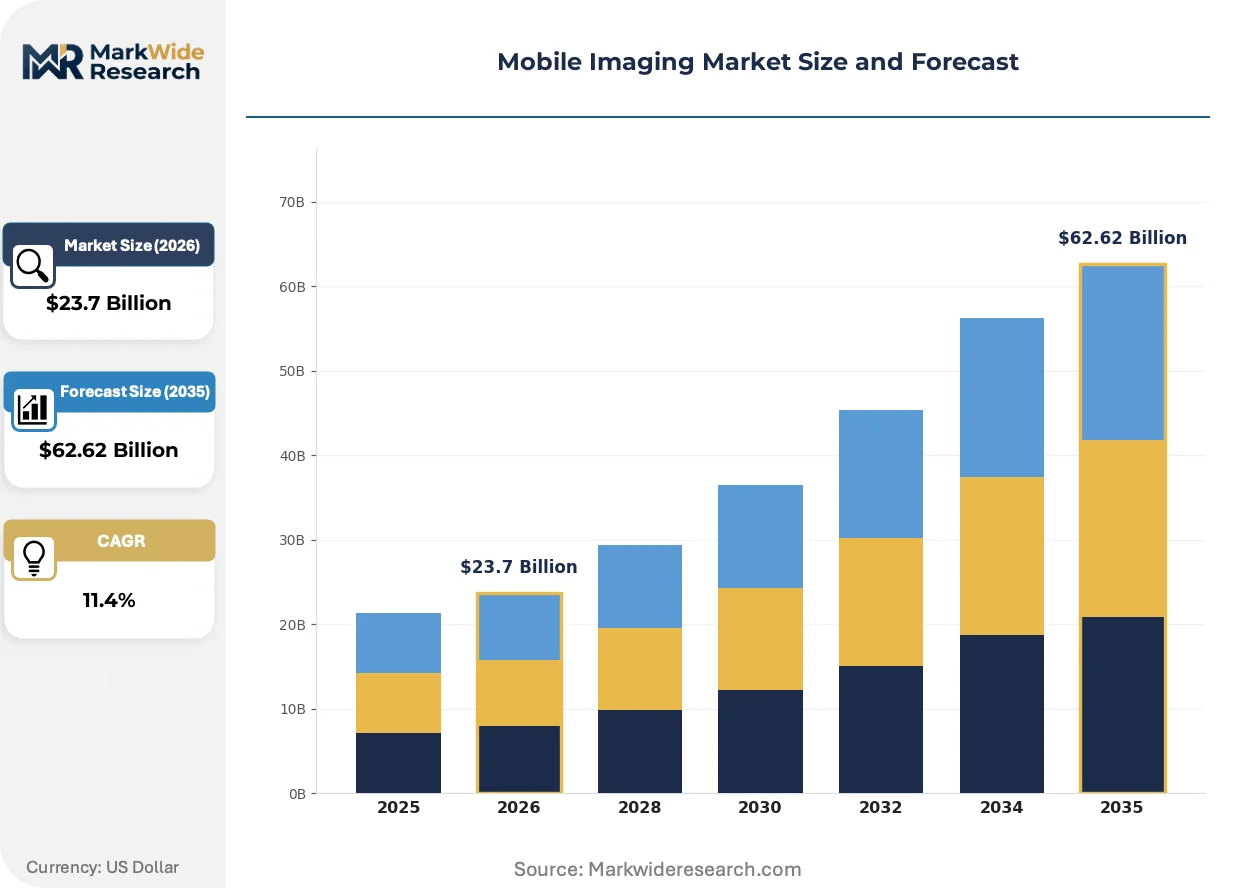
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Systems, Ultrasound Systems, MRI Scanners, CT Scanners End User: Hospitals, Clinics, Diagnostic Centers, Emergency Services Technology: Analog, Digital, Wireless, Hybrid Application: Radiology, Cardiology, Orthopedics, Emergency Care |
| Companies Covered | DMS Health, Akumin Inc., TridentCare, RAYUS Radiology, Cobalt Health, Shared Medical Services, Front Range Mobile Imaging, Accurate Imaging Diagnostics, Atlantic Mobile Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Imaging Market Shifts & Advancements
Wireless digital radiography is compressing deployment timelines while artificial intelligence and edge computing are embedding diagnostic capability directly into acquisition hardware. These forces are restructuring vendor value propositions around uptime guarantees rather than equipment sales.
Flat-panel detector technology with cesium iodide scintillation layers is overtaking computed radiography cassette systems in mobile X-ray configurations. Emergency departments and intensive care units within consolidated hospital networks are adopting wireless DR for bedside imaging at replacement cycles under five years. This transition is overtaking the installed base of CR readers and reducing per-exam processing time from minutes to seconds, compressing capital recovery timelines for fleet operators.
EU Medical Device Regulation clinical evidence requirements are tightening post-market surveillance obligations for CE-marked mobile CT and MRI systems sold in Europe. Manufacturers must now maintain active implant registries and periodic safety update reports across distributed device populations. Trauma-capable mobile CT units with stroke protocol certification face the steepest compliance burden, driving consolidation among vendors with established European notified body relationships.
Subscription-based per-scan pricing is displacing traditional equipment lease structures among independent diagnostic facilities and smaller hospital systems. Fleet operators are unbundling hardware, maintenance, and interpretation services into modular contracts that align cash outflows with patient volume. This model is most visible in the southeastern United States, where radiology group practices are outsourcing entire mobile operations to specialized logistics providers rather than managing vehicle fleets in-house.
Mobile Imaging Market Segmentation
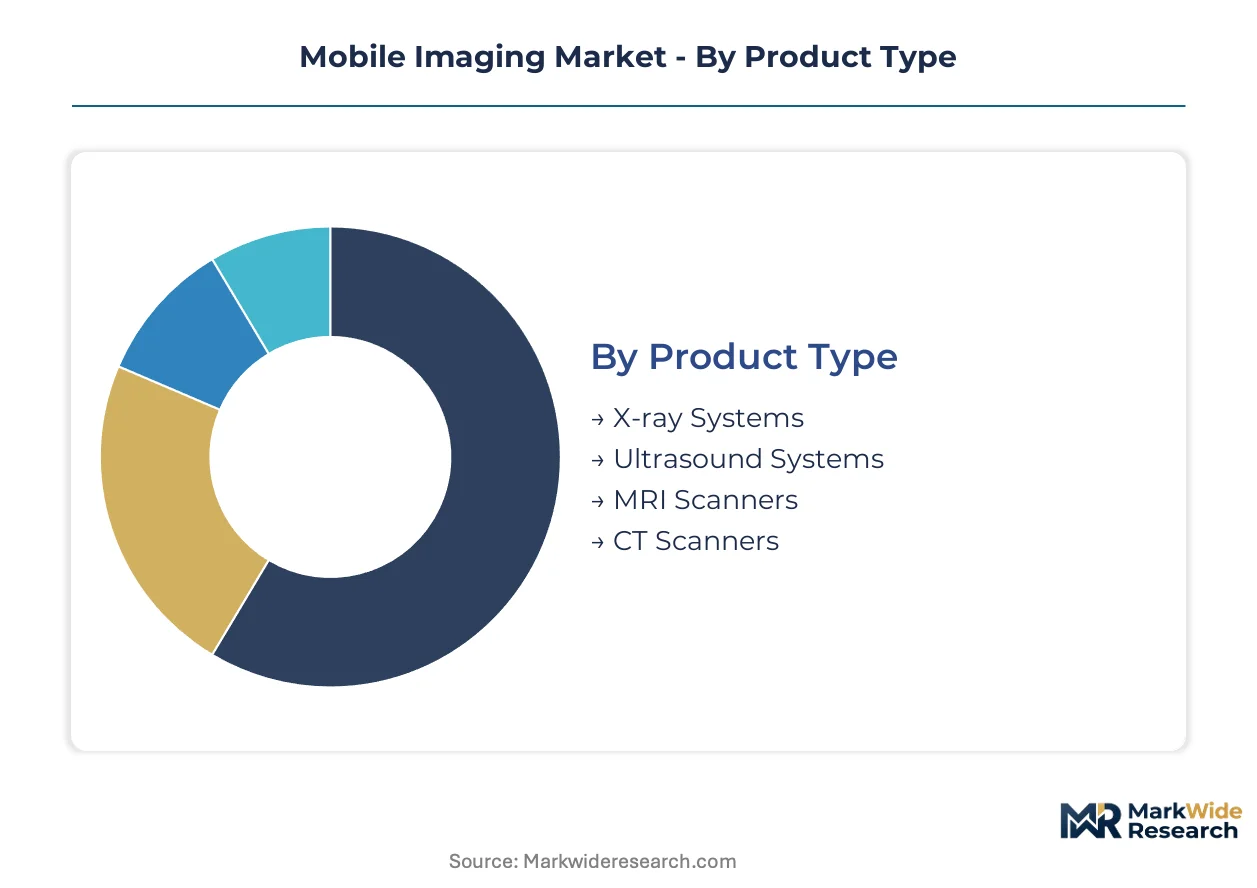
Mobile imaging market segmentation reveals distinct procurement patterns across equipment categories and care settings. Supply concentration in detector manufacturing and shielded vehicle fabrication creates divergent margin structures that reshape vendor positioning.
Product Type:
Detector fabrication and shielded vehicle assembly concentrate among specialized suppliers in Germany, Japan, and the United States, compressing margins for downstream fleet operators.
- X-ray Systems:Flat-panel detectors with cesium iodide scintillation layers deliver clinical-grade resolution in compact vehicle-mounted configurations. Hospital emergency departments in the United States drive replacement cycles under five years as wireless DR displaces computed radiography cassette systems.
- Ultrasound Systems:Phased-array transducers with portable cart-based or handheld form factors enable point-of-care cardiac and abdominal imaging. Federally qualified health centers deploy these units for obstetric and vascular screening in rural counties lacking fixed radiology suites.
- CT Scanners:Trauma-capable mobile units with stroke protocol certification command premium positioning.
- MRI Scanners:Superconducting magnet systems require specialized cryogen logistics and helium recovery infrastructure.
X-ray Systems absorb the bulk of installed capacity; CT Scanners are expanding most quickly.
End User:
Procurement authority concentrates within integrated delivery networks that negotiate fleet-wide service agreements rather than unit-by-unit purchases.
- Hospitals:Consolidated health systems in the United States demand predictive maintenance platforms and guaranteed uptime clauses for bedside imaging in emergency departments and intensive care units. Stroke protocol coverage requirements drive rotation scheduling across multi-hospital networks.
- Clinics:Federally qualified health centers leverage Inflation Reduction Act tax credits to deploy mobile CT and MRI units without fixed-site capital expenditure.
- Diagnostic Centers:Independent facilities favor subscription-based per-scan pricing over traditional equipment leases.
- Emergency Services:Mobile stroke units require teleradiology network integration for real-time specialist consultation.
Hospitals command the dominant share of fleet deployment; Clinics are climbing the fastest as rural access mandates intensify.
Technology:
Semiconductor supply concentration in East Asian manufacturing clusters constrains availability of CMOS and a-Si flat-panel detectors for digital configurations.
- Analog:Film-based cassette systems persist in cost-constrained settings with legacy processing infrastructure.
- Digital:Direct radiography with flat-panel detectors reduces per-exam processing time from minutes to seconds. Wireless DR configurations dominate replacement demand in United States hospital networks.
- Wireless:DICOM-compliant cloud integration enables real-time image transmission to teleradiology networks. HIPAA cross-border data friction triggers complex compliance architectures for interstate mobile operations.
- Hybrid:Configurations combine wired acquisition with wireless transmission for redundancy in critical care settings.
Digital technology holds the largest installed base; Wireless configurations are gaining share fastest as remote diagnostic networks expand.
Application:
Reimbursement policy differentiation across Medicare episode-based payment bundles creates divergent ROI timelines for procedure-specific fleet deployment.
- Radiology:General diagnostic imaging encompasses chest, abdominal, and skeletal protocols across all mobile product categories.
- Cardiology:Echocardiography and cardiac CT angiography demand specialized technologist training and rapid image interpretation turnaround. Mobile units serving skilled nursing facilities in the southeastern United States concentrate cardiology rotations where fixed echocardiography capacity is absent.
- Orthopedics:Weight-bearing extremity imaging and intraoperative C-arm configurations support surgical centers.
- Emergency Care:Trauma-capable CT with whole-body scanning protocols addresses stroke and trauma time-critical interventions.
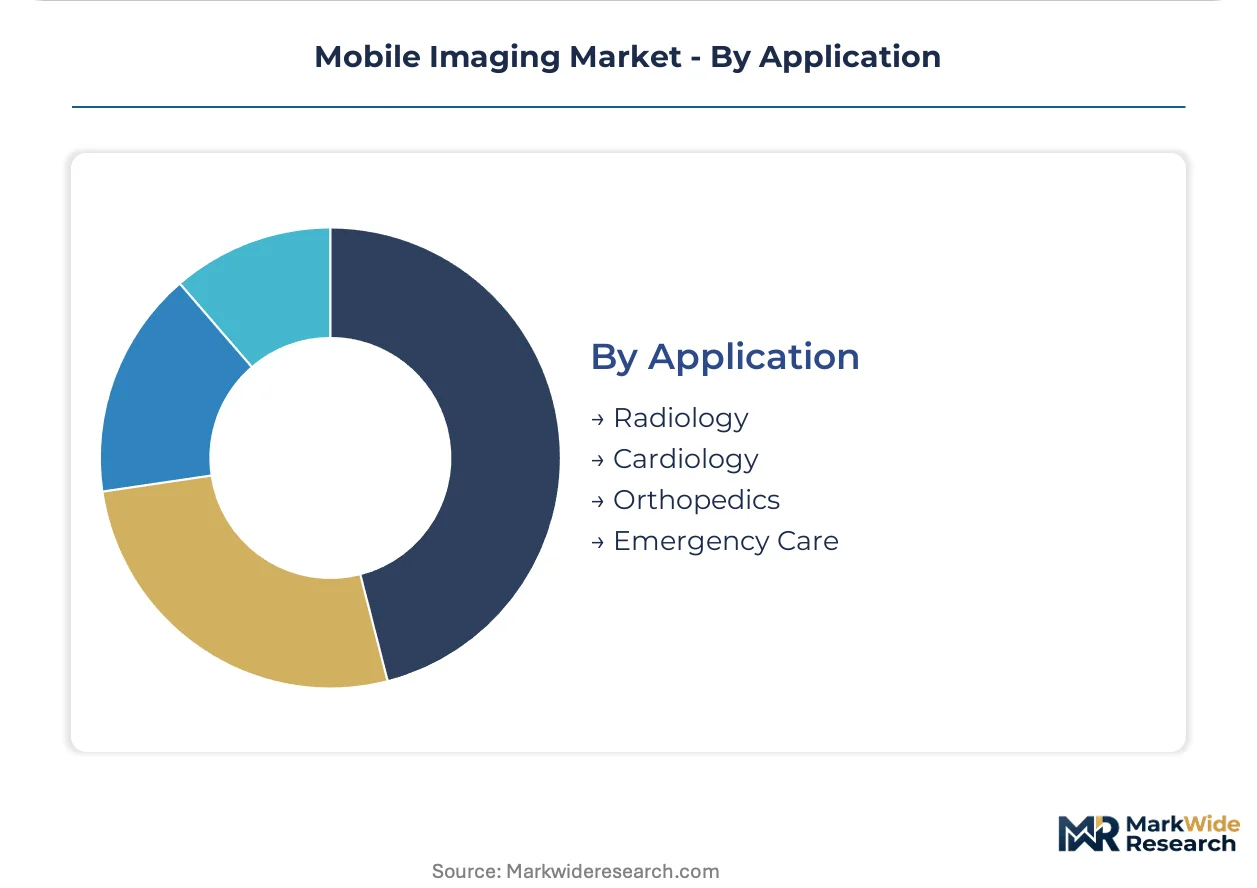
Radiology maintains the broadest fleet utilization; Emergency Care shows the steepest expansion trajectory as stroke protocol networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks concentrate fleet procurement leverage through integrated delivery networks that negotiate multi-state service contracts. Rural health clinic expansion across underserved counties drives deployment of mobile CT and MRI units. EU Medical Device Regulation harmonization and FDA 510(k) pathways create divergent compliance timelines for manufacturers.
United States
Federally qualified health centers in designated shortage areas deploy mobile MRI rotations to meet Medicare access standards without fixed-site capital. The Inflation Reduction Act provides tax credits for rural healthcare infrastructure investments. Cleveland Clinic and Mayo Clinic anchor multi-hospital networks in Ohio and Minnesota that demand predictive maintenance platforms and guaranteed uptime clauses.
Germany
EU Medical Device Regulation clinical evidence requirements tighten post-market surveillance for CE-marked mobile CT systems. Notified body relationships in Munich and Berlin determine market entry speed for trauma-capable units. Bavaria's medical technology cluster around Nuremberg hosts shielded vehicle fabricators supplying fleet operators across Central Europe.
Japan
Superconducting magnet manufacturers face concentrated helium logistics constraints for mobile MRI deployment. PMDA streamlined approval pathways for wireless-enabled digital radiography reduce time-to-market for cloud-integrated systems. Tokyo and Osaka metropolitan hospitals drive replacement demand for flat-panel detector configurations.
United Kingdom
NHS England procurement frameworks favor subscription-based per-scan pricing over equipment leases for diagnostic services. GDPR compliance architectures constrain cross-border patient data flows from mobile units operating across England and Scotland. London's teleradiology networks integrate real-time image transmission from mobile stroke units serving emergency departments.
Canada
Health Canada regulatory alignment with FDA 510(k) pathways accelerates market entry for wireless DR systems. Provincial health authorities in Ontario and British Columbia consolidate mobile imaging procurement through shared services organizations. Toronto's hospital networks demand fleet-wide service contracts covering CT and ultrasound rotations across urban and rural sites.
Mobile Imaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enabled edge computing and subscription-based service models. The vendor base separates into logistics-integrated fleet operators, post-acute care specialists, and same-day scheduling platform providers. Three archetypes dominate: national multi-state service networks, regional skilled nursing facility contractors, and technology-enabled emergency department suppliers. Competitive moves concentrate on fleet-wide service contract capture and predictive maintenance platform deployment.
Within the logistics-integrated tier, DMS Health exemplifies national infrastructure scale, while TridentCare occupies the post-acute care specialization vector. Cobalt Health represents the technology-enabled scheduling platform archetype. These three anchors illustrate divergent strategic positioning across procurement consolidation, skilled nursing outsourcing, and emergency department cost reduction.
| Leading Market Players |
|---|
| DMS Health |
| Akumin Inc. |
| TridentCare |
| RAYUS Radiology |
| Cobalt Health |
| Shared Medical Services |
| Front Range Mobile Imaging |
| Accurate Imaging Diagnostics |
| Atlantic Mobile Imaging |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between trauma-capable CT units with stroke protocol clearance and standard X-ray configurations manifests in both pricing stratification and supply chain sourcing patterns. Premium-tier mobile MRI systems draw from superconducting magnet fabricators in Germany and Japan, while economy-tier digital radiography units source flat-panel detectors from concentrated East Asian semiconductor foundries.
Pricing Analysis
Volume-margins split sharply across equipment tiers: X-ray systems absorb the bulk of fleet deployments at compressed per-unit margins, while CT and MRI units command premium positioning tied to clinical certification levels. Price differentiation rests on FDA 510(k) clearance tier and wireless DICOM integration depth. Pricing pressure stems from integrated delivery networks consolidating procurement leverage through fleet-wide service contracts. Federally qualified health centers exhibit highest price sensitivity, whereas consolidated hospital systems prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Reverse-logistics flows for helium recovery and cryogen recycling constrain mobile MRI deployment economics, with specialized handlers in Germany, Japan, and the United States managing superconducting magnet refurbishment cycles. Raw material dependencies center on lead-tungsten shielding composites, cesium iodide scintillation crystals, and lithium-ion power electronics. Single-source vulnerability concentrates in East Asian CMOS detector manufacturing. Distribution runs through national fleet operators with multi-state logistics infrastructure serving integrated hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over shielded vehicle fabrication and predictive maintenance platforms determines contract capture. Players are pursuing backward integration into detector manufacturing to defend margin structures against procurement consolidation.
For Market Incumbents: Acquire cryogen logistics networks and helium recovery infrastructure to lock in mobile MRI service capabilities. DMS Health and TridentCare demonstrate how captive shielded vehicle fabrication defends against lead-shielding cost volatility. Consolidate predictive maintenance platform development to meet guaranteed uptime clauses demanded by Cleveland Clinic and Mayo Clinic network archetypes. For New Entrants and Emerging Players: Launch via subscription-based per-scan pricing models targeting skilled nursing facility outsourcing demand in the southeastern United States. White-space concentration sits with AI-enabled edge computing platforms for real-time image validation at emergency departments. Federally qualified health centers in designated shortage areas offer the most penetrable entry vector given Inflation Reduction Act infrastructure subsidies. For Investors and Strategic Acquirers: Re-rating potential sits with logistics-integrated fleet operators given procurement consolidation into integrated delivery networks. Long-term viability hinges on multi-state service contract tenure and teleradiology network integration depth. Monitor HIPAA cross-border data friction resolution and EU MDR harmonization progress as inflection signals for compliance-cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Manufacturing | Captive CMOS flat-panel supply secures margins against East Asian semiconductor concentration risk. |
| Helium Recovery Infrastructure Deployment | Cryogen logistics control enables sustainable mobile MRI fleet economics across rural rotation schedules. |
| Predictive Maintenance Platform Development | Uptime guarantee fulfillment meets integrated delivery network procurement specifications from Cleveland Clinic archetypes. |
| AI Edge Computing Certification Pathway | FDA 510(k) clearance for onboard inference engines differentiates emergency department service offerings. |
| Multi-State Logistics Network Expansion | Fleet-wide service contract capture concentrates procurement leverage against unit-by-unit competitors. |
Research Methodology
SEC 10-K filings, FDA 510(k) premarket notification databases, and CMS Medicare cost report data formed the secondary backbone, cross-referenced against hospital procurement database extracts and GPO contract repositories. Primary fieldwork encompassed biomedical engineers at consolidated health systems, radiology group practice administrators, fleet operations directors at national mobile imaging providers, and GPO contracts managers. Bottom-up unit deployment estimates triangulated against top-down healthcare capital expenditure flows.
Bottom-up modeling tracked equipment category deployment rates, replacement cycle timing, and subscription pricing adoption curves across the projection horizon. Segmentation dimensions encompassed product type tier, end-user procurement authority level, technology configuration, and application-specific reimbursement pathway. CAGRs derived from installed base growth trajectories and revenue-per-unit trends calibrated against Medicare episode-based payment bundle evolution. Helium supply constraints and radiologic technologist labor pool dynamics factored as industry-specific forecast modifiers.
Lead-shielding commodity volatility, certified technologist shortage severity, and HIPAA interstate data architecture rulings are the dominant revision risks. Forecasts embed assumptions regarding EU MDR harmonization timelines and Inflation Reduction Act tax credit continuity. Practitioners should monitor CMS rural health clinic access standard enforcement and DOT vehicle weight compliance rulings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Europe Hyperspectral Imaging Market
Imaging
Cooled IR Camera Market
Imaging
Infrared Imaging Market
Imaging
CMOS X-Ray Detectors Market
Imaging
Automotive 3D Imaging Market
Imaging
Acoustic Microscopy Market
Imaging
Photo Kiosk Market
Imaging
Machine Vision System Market
Imaging
Global Label-Free Array Systems Market
Imaging
Vintage Cameras Market
Imaging
TDI Camera Market
Imaging
Global Computed Radiography Market
Imaging
Borescope Market
Imaging
Photoacoustic Imaging Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Camera Technology Market