
 US Pin and Sleeve Devices Market | 2026-2036
US Pin and Sleeve Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Pin and Sleeve Devices Market Insights
Data center operators is rotating toward higher-reliability pin and sleeve configurations as hyperscale builds accelerate across the southern United States. Eaton Corporation leverages its vertical integration in circuit protection to anchor premium positioning in this buyer segment. Hubbell Corporation competes through specialized marine-grade and washdown-rated product lines that dominate food processing applications.
Pin and sleeve devices are mechanical power connectors comprising insulated cylindrical pins and matching sleeves with keyed housings, typically rated from 16A to 125A and constructed from UV-stabilized thermoplastics or nickel-plated brass to withstand chemical exposure and mechanical abuse in industrial environments. Their primary purpose is to enable safe, tool-free connection and disconnection of three-phase power in temporary or permanent installations where environmental sealing and polarization prevent accidental mating. The three pole and four pole configurations generate the deepest margin pools because they command specification premiums in heavy manufacturing and energy infrastructure. Permanent installation types sustain the largest volume base, while portable configurations are expanding fastest as modular construction and mobile power rental fleets multiply across the Gulf Coast and Midwest industrial corridors.
NFPA publishes the National Electrical Code that governs pin and sleeve device installation practices, while OSHA enforces workplace electrical safety standards that mandate ground-fault protection in construction and industrial settings. NEMA dimensional standards and UL 1686 pin-and-sleeve configuration specifications shape product interoperability and market access by defining mating interfaces and environmental ratings. Stakeholders must monitor evolving NEC cycle amendments addressing electrification loads and arc-fault containment as these will reshape product certification requirements and procurement specifications.
Market Dynamics
Hyperscale data center construction across Texas and the Gulf Coast is compressing procurement cycles for high-amperage pin and sleeve connectors, forcing distributors to carry deeper inventory positions and manufacturers to accelerate production lead times.
Growth Catalysts
- NFPA National Electrical Code updates:Tightened ingress protection mandates for wet-location installations are compelling facility operators to replace legacy connectors with sealed pin and sleeve configurations rated IP67 and above.
- Modular construction proliferation:Mobile power rental fleets and temporary industrial installations across the Midwest are driving portable configuration demand as contractors prioritize tool-free connection speed over permanent hardwiring.
- Texas industrial corridor expansion:Energy infrastructure projects and petrochemical facility builds are concentrating three-phase power distribution equipment procurement in Houston, Corpus Christi, and the Permian Basin.
Market Restraints
- Copper and nickel price volatility:Raw material cost swings for plated brass contacts and conductive alloys squeeze margin predictability for mid-tier manufacturers lacking forward commodity hedging.
- Domestic foundry concentration:Heavy reliance on a limited base of US-based thermoplastic molders and metal stamping operations creates geographic supply vulnerability during regional weather disruptions.
- UL 1686 certification timelines:Extended testing protocols for new amperage ratings and housing materials delay product launches by six to twelve months, freezing competitive response speed.
Strategic Opportunities
- OSHA ground-fault mandate expansion:Proposed workplace electrical safety standard revisions would require arc-fault detection integration in construction-site temporary power, opening specification windows for smart pin and sleeve devices.
- Food processing washdown environments:USDA-inspected facilities are adopting marine-grade connector specifications for sanitation compliance, creating cross-application demand for Hubbell-style sealed housings.
- Electric vehicle fleet charging infrastructure:Commercial depot charging installations require high-reliability three-phase connections capable of sustained 100A+ loads in outdoor environments.
Industry Challenges
- Electrical contractor skill specialization:Shortages of technicians trained in IEC 60309 pin-and-sleeve installation versus familiar NEMA twist-lock formats slow specification conversion in field conditions.
- Legacy system integration friction:Retrofit projects face mechanical incompatibility between existing panel cutouts and updated keyed housing dimensions, requiring custom adapter fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pin and Sleeve Devices Market |
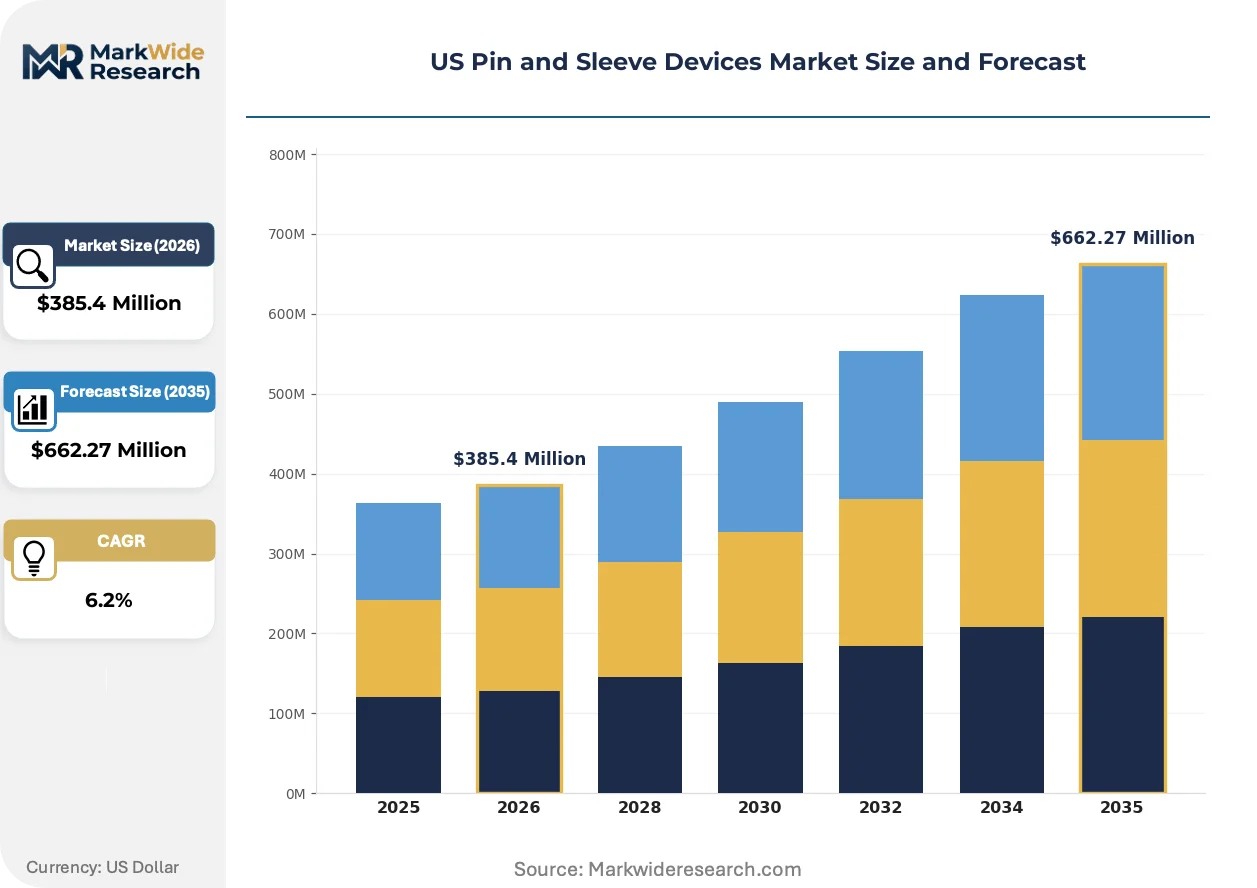
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Pole, Two Pole, Three Pole, Four Pole End User: Manufacturing, Construction, Event Management, Industrial Power Rating: 16A, 32A, 63A, 125A Installation: Temporary, Permanent, Portable, Fixed |
| Companies Covered | ABB Ltd., Eaton Corporation, Emerson Electric, Meltric Corporation, Schneider Electric, Hubbell Corporation, Amphenol Corporation, Walther Electric, Legrand SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pin and Sleeve Devices Market Trends and Innovations
Active material science advances and procurement behavior compression are reconfiguring competitive positioning across connector tiers, with differentiation increasingly anchored in environmental sealing performance rather than base electrical specifications.
Advanced thermoplastic compounds with embedded UV stabilizers and chemical resistance additives are displacing standard nylon housings in outdoor and petrochemical applications. Data center operators in Dallas-Fort Worth and Austin are specifying these materials for decade-long service life in unconditioned environments. The technology is bifurcating the market between premium sealed configurations and commodity-grade alternatives, compressing mid-tier positioning.
OSHA enforcement memoranda on construction-site ground-fault protection are tightening interpretation of existing workplace electrical safety standards without awaiting formal rulemaking. Contractors in Texas and Louisiana are preemptively upgrading temporary power distribution to avoid citation exposure during inspections. Heavy civil and energy infrastructure segments are absorbing compliance costs fastest, passing through specification premiums to project owners.
Direct procurement relationships between data center developers and connector manufacturers are displacing traditional electrical distributor intermediaries for high-volume projects. Eaton and Hubbell are establishing dedicated account structures for hyperscale buyers in Northern Virginia and Phoenix, unbundling specification support from material logistics. This channel compression is most visible in multi-megawatt campus developments where single-source accountability reduces interface complexity.
US Pin and Sleeve Devices Market Segmentation
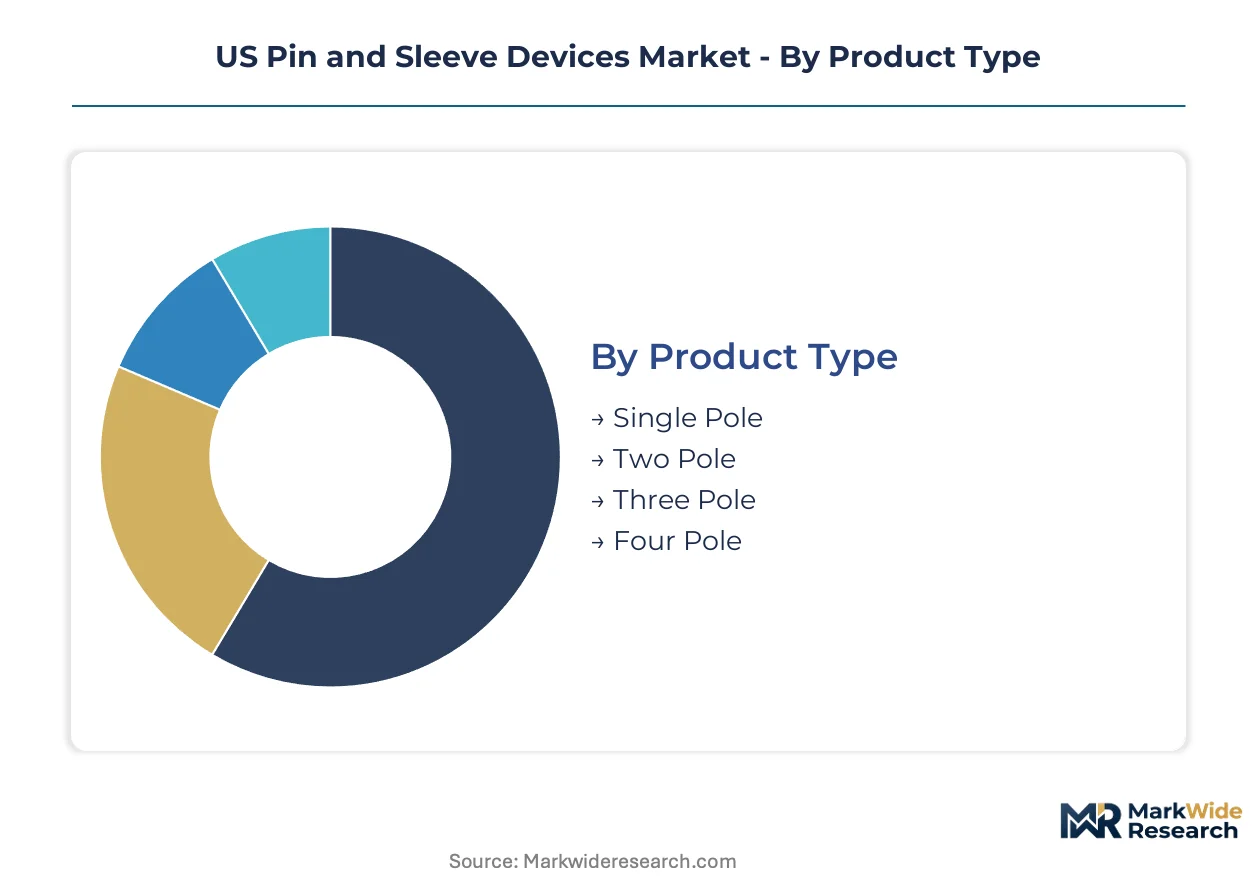
Pin and sleeve device procurement patterns diverge sharply across installation contexts and power requirements. Channel strategy must align with whether buyers prioritize speed of deployment, regulatory compliance, or lifecycle durability.
Product Type:
Electrical distributors stock heavier pole configurations for industrial accounts while contractors source single and two pole variants through supply houses for lighter commercial jobs.
- Three Pole:These configurations carry live, neutral, and ground conductors in a keyed housing rated for three-phase power distribution. Demand clusters in Texas petrochemical facilities and Gulf Coast energy infrastructure where NFPA 70 wet-location mandates require IP67 sealing. The segment commands specification premiums from engineering-procurement-construction firms.
- Four Pole:Incorporating separate neutral and ground paths plus an additional switched pole, these connectors serve heavy manufacturing with mixed single-phase and three-phase loads. Ohio and Michigan automotive plants specify four pole devices for flexible production line reconfiguration. OSHA ground-fault enforcement drives replacement cycles in legacy facilities.
- Single Pole:Modular cam-type connectors for high-current single-phase applications in entertainment and temporary power.
- Two Pole:Compact configurations for commercial lighting and small equipment feeds where space constraints dominate.
Three pole dominates installed base. Four pole is where expansion concentrates.
End User:
Cost tiers separate specification-grade procurement in industrial verticals from price-sensitive construction sourcing.
- Industrial:Integrated facility operators in refining, mining, and primary metals specify pin and sleeve devices with decade-plus service life expectations. These buyers demand captive supply agreements with manufacturers holding UL 1686 certification across full amperage ranges. The segment absorbs premium pricing for arc-fault detection readiness.
- Construction:General contractors and electrical subcontractors prioritize tool-free connection speed and rental fleet compatibility over housing material specifications. Midwest modular construction growth and Texas heavy civil projects drive portable configuration demand. Price pressure intensifies from commoditized distributor private-label offerings.
- Manufacturing:Discrete and process manufacturers balance downtime avoidance with capital expenditure constraints.
- Event Management:Staging and entertainment venues require frequent connection cycles with visual polarity confirmation.
Industrial anchors margin pools. Construction is climbing the fastest.
Power Rating:
Volume concentrates at standard IEC 60309 amperage steps where tooling and inventory economies align.
- 125A:High-amperage connectors with nickel-plated brass contacts and reinforced thermoplastic housings serve data center busway drops and electric vehicle fleet depots. Northern Virginia and Phoenix hyperscale developments specify 125A devices for direct utility interconnection. Lead times extend six to eight months due to limited domestic stamping capacity.
- 32A:The workhorse rating for commercial and light industrial three-phase distribution balances conductor sizing with handling ergonomics. Food processing washdown environments in California and Wisconsin specify 32A marine-grade housings for sanitation compliance. Distributor inventory turns fastest at this amperage.
- 16A:Standard rating for portable power and light commercial equipment.
- 63A:Mid-range connectors bridging temporary power rental and permanent industrial installation.
32A sustains largest volume base. 125A is gaining share fastest.
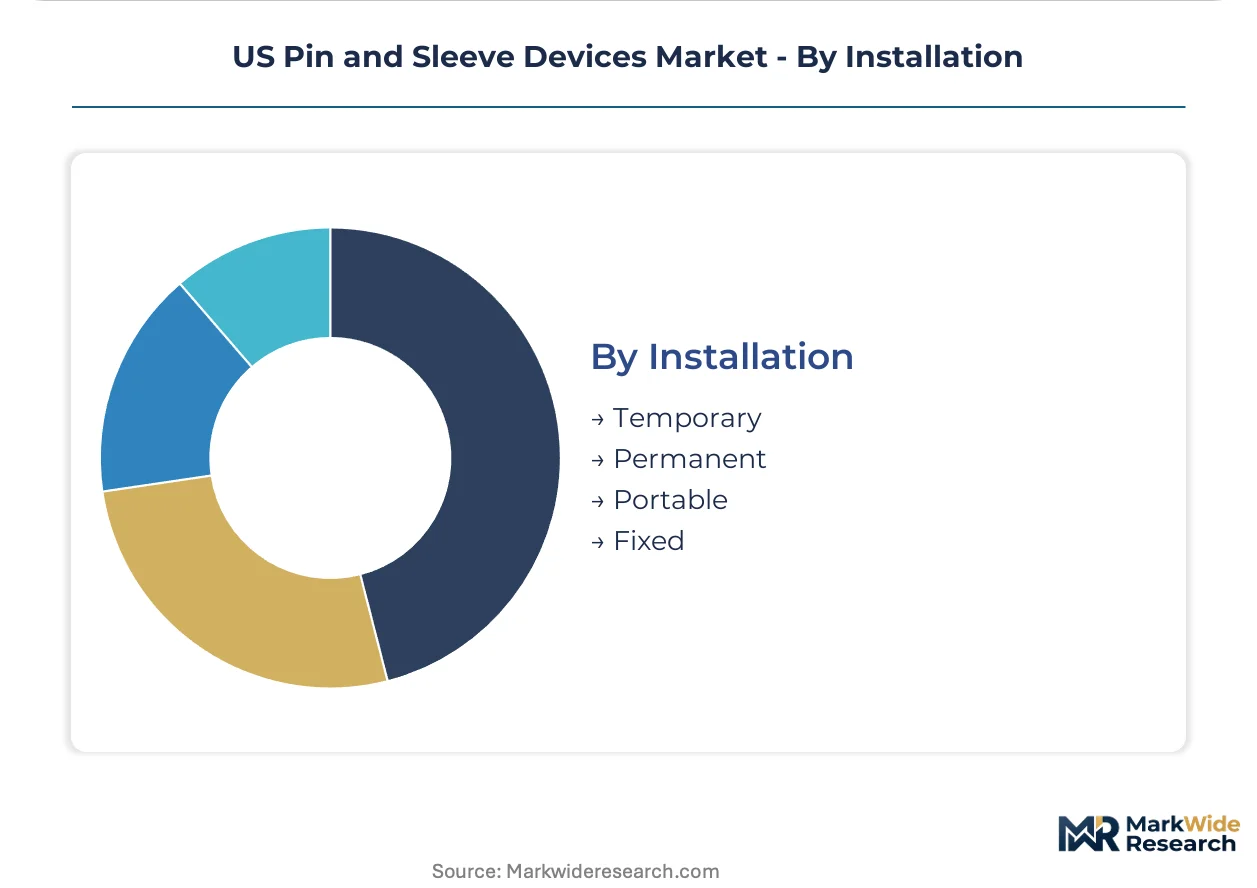
Installation:
Supply concentration in thermoplastic molding and metal stamping shapes availability across mounting configurations.
- Permanent:Panel-mounted and flanged receptacles with threaded conduit entries dominate manufacturing facility builds and infrastructure projects. These installations require coordination between electrical engineers and connector manufacturers on cutout dimensions and environmental ratings. Texas industrial corridor expansion sustains procurement velocity.
- Portable:Inline plugs and connectors with strain relief and cable grips serve mobile power rental fleets and modular construction. Gulf Coast petrochemical turnarounds and Midwest agricultural processing drives seasonal demand spikes. Contractors value color-coded voltage identification for field safety.
- Temporary:Stage and construction-site power distribution with frequent connection cycling.
- Fixed:Wall-mounted or equipment-integrated receptacles for dedicated machinery feeds.
Permanent anchors replacement revenue. Portable shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-manufactured pin and sleeve devices flow primarily to Canadian industrial buyers and Mexican maquiladora operations, with cross-border trade intensifying as North American energy infrastructure investment accelerates. Texas and Louisiana anchor domestic production capacity, serving downstream demand across the Gulf Coast industrial corridor.
Texas
Hyperscale data center construction in Dallas-Fort Worth and Austin compresses procurement cycles for 125A connectors. NFPA 70 National Electrical Code amendments tighten wet-location sealing requirements for petrochemical facilities along the Houston Ship Channel. Corpus Christi and the Permian Basin concentrate energy infrastructure builds, driving three-phase power distribution equipment procurement.
Louisiana
Heavy civil construction and offshore platform maintenance sustain portable configuration demand. OSHA ground-fault enforcement memoranda preemptively tighten temporary power standards before formal rulemaking. Baton Rouge and Lake Charles industrial complexes specify marine-grade housings for washdown environments.
California
Food processing facilities in the Central Valley adopt IP67-rated connectors for USDA sanitation compliance. State energy efficiency mandates accelerate electric vehicle fleet depot construction requiring high-amperage three-phase connections. Silicon Valley data center operators specify advanced thermoplastic compounds for decade-long outdoor service life.
Ohio
Automotive manufacturing plants in Detroit-Toledo corridor specify four pole devices for flexible production line reconfiguration. Industrial facility electrification retrofits face legacy panel cutout incompatibility, requiring custom adapter fabrication. Cleveland and Cincinnati distributors stock heavier pole configurations for manufacturing accounts.
Virginia
Northern Virginia hyperscale developments establish direct procurement relationships with connector manufacturers, bypassing traditional distributor intermediaries. Loudoun County and Prince William County data center clusters specify 125A devices for direct utility interconnection. Multi-megawatt campus developments prioritize single-source accountability to reduce interface complexity.
US Pin and Sleeve Devices Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and vertical integration intensity. The vendor base clusters around three tiers: diversified electrical conglomerates with captive supply chains, mid-cap specialists with focused IEC 60309 portfolios, and regional fabricators serving price-sensitive construction accounts. Strategic moves concentrate on backward integration into thermoplastic compounding and dedicated account structures for hyperscale data center developers.
Within the diversified conglomerate tier, Eaton Corporation and Hubbell Corporation exemplify contrasting positioning strategies. Eaton anchors premium positioning through in-house circuit protection integration, while Hubbell occupies the specialized marine-grade and washdown-rated segment. Among European-headquartered multinationals, ABB Ltd. and Schneider Electric represent scale-driven approaches with broad industrial automation portfolios. Legrand SA and Amphenol Corporation sit within the connectivity-focused archetype, emphasizing mating interface standardization across power and signal applications.
| Leading Market Players |
|---|
| ABB Ltd. |
| Eaton Corporation |
| Emerson Electric |
| Meltric Corporation |
| Schneider Electric |
| Hubbell Corporation |
| Amphenol Corporation |
| Walther Electric |
| Legrand SA |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between data center developers and connector manufacturers lock in both nickel-plated brass contact supply and price visibility across the analysis window. Texas hyperscale buyers leverage multi-year capacity reservations to bypass spot-market volatility in thermoplastic compounds while securing priority allocation from domestic molders.
Pricing Analysis
Current-generation IP67-sealed configurations command substantial premiums over prior-generation IP44-rated housings, while next-generation arc-fault-integrated devices are pre-quoting at additional specification premiums. Pricing stratifies across premium, standard, and economy tiers based on UL 1686 certification depth and captive supply chain control. Cost compression in the construction-grade segment is intensifying because distributor private-label offerings erode mid-tier positioning. General contractors exhibit highest price sensitivity, while integrated industrial operators absorb premium pricing for decade-long service life guarantees.
Supply Chain Analysis
Inbound logistics costs from Asian thermoplastic resin suppliers through West Coast ports create margin pressure for manufacturers lacking regional compounding partnerships. Domestic production draws from US-based nickel-plated brass stampers, Texas Gulf Coast petrochemical feedstocks, and Ohio thermoplastic molders. Single-source vulnerability concentrates in limited domestic foundry capacity for high-amperage contact assemblies. Distribution runs through electrical distributor networks for construction accounts and direct manufacturer relationships for hyperscale data center developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards players who control captive supply of UL-certified housings and nickel-plated contact stampings, as qualified domestic sources remain scarce relative to procurement velocity from Texas data center and energy infrastructure builds.
For Market Incumbents: Secure backward integration into thermoplastic compounding with UV stabilizer additives to defend margin position against commodity-grade imports. Prioritize dedicated account structures for Northern Virginia and Phoenix hyperscale developers, as direct procurement relationships are displacing traditional distributor intermediaries. Expand 125A production capacity ahead of OSHA ground-fault mandate expansion. For New Entrants and Emerging Players: Anchor in portable configuration supply for Midwest modular construction and Gulf Coast petrochemical turnaround markets, where rental fleet compatibility and color-coded voltage identification create specification stickiness. Target food processing washdown environments in California and Wisconsin with marine-grade housing offerings. Pursue private-label partnerships with regional electrical distributors to bypass UL 1686 certification timeline barriers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with captive UL 1686 certification across full amperage ranges and established relationships with Texas engineering-procurement-construction firms. Long-term viability hinges on backward integration depth and hyperscale data center account penetration. Monitor OSHA ground-fault enforcement memoranda as the signal for arc-fault detection integration inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermoplastic Compounding | Eaton's captive supply of UV-stabilized housings reduces exposure to resin price volatility from Gulf Coast petrochemical suppliers. |
| Direct Account Structures for Hyperscale Developers | Hubbell's dedicated teams in Northern Virginia bypass distributor margins while securing multi-year offtake commitments from data center operators. |
| Marine-Grade Product Line Expansion | Specialized IP67 housings for USDA-inspected food processing facilities in California command specification premiums over standard industrial grades. |
| Arc-Fault Detection R&D Investment | Early UL certification for smart pin and sleeve devices positions manufacturers for OSHA mandate expansion in construction-site temporary power. |
| Capacity Expansion in Texas Industrial Corridor | Proximity to Houston petrochemical facilities and Dallas-Fort Worth data center clusters reduces logistics costs and accelerates emergency response. |
Research Methodology
Initial hypotheses were tested against primary input from electrical distributor procurement managers, data center facility engineers, OSHA compliance officers, and thermoplastic compounders, then refined through secondary validation against NFPA code amendment dockets, UL 1686 certification records, EIA electricity demand projections, and SEC filings from listed electrical equipment manufacturers. Bottom-up demand modeling across installation types and power ratings was triangulated with top-down market sizing from trade flow analysis.
Variance decomposition across the projection horizon isolates volume drivers by pole configuration, amperage rating, and end-user vertical. The analytical framework segments by product type, power rating, installation method, and geographic demand cluster. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking capital expenditure disclosures from hyperscale data center developers. Industry-specific inputs include NEC amendment implementation timelines and copper-nickel alloy price indices.
Underlying assumptions cover continued NFPA 70 wet-location mandate enforcement, stable OSHA ground-fault interpretation, and sustained Texas industrial construction velocity, with deviation risk concentrated in raw material cost volatility and UL certification timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Digital Underground Metal Detector Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Temperature Detection Screen Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Global Surge Protection Devices Market