
 Global Portable Gas Detector Market | 2026-2036
Global Portable Gas Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Gas Detector Market Foresight
Sensor miniaturization and wireless connectivity is fragmenting the portable gas detector technology stack into modular, edge-computing platforms. Honeywell International Inc. leverages its integrated safety software ecosystem to anchor premium positioning across industrial accounts. MSA Safety Incorporated dominates North American firefighting and confined space channels through specialized distribution partnerships. Drägerwerk AG & Co. KGaA sustains German manufacturing scale while competing aggressively in Asian process industries.
A portable gas detector is a self-contained, battery-powered instrument that samples ambient air through electrochemical, infrared, or catalytic bead sensors to quantify toxic, combustible, or oxygen-deficient atmospheres; units typically operate from minus twenty to plus fifty degrees Celsius with response times under thirty seconds for life-critical alarms. Multi-gas detectors command the highest unit margins due to sensor density and firmware complexity, while electrochemical sensors remain the volume backbone across oilfield and chemical processing applications. Semiconductor sensor technology is gaining fastest in cost-sensitive environmental monitoring deployments where ppb-level precision is secondary to fleet scalability.
OSHA permissible exposure limits and EPA risk management plan requirements in the United States compel quarterly calibration cycles and documented alarm response protocols, directly expanding aftermarket service revenue pools. ECHA REACH restrictions on sensor materials and EU ATEX equipment directives shape product certification pathways for European market entry. Stakeholders must monitor evolving battery chemistry regulations and hydrogen economy infrastructure codes, as these will redefine sensor specifications and channel partnerships before the decade closes.
Market Dynamics
Sensor miniaturization and wireless connectivity are fragmenting the portable gas detector technology stack into modular, edge-computing platforms that demand new firmware architectures and cloud integration capabilities from incumbent suppliers.
Growth Catalysts
- OSHA calibration mandates:Quarterly calibration cycles and documented alarm response protocols in the United States compel facility managers to expand aftermarket service contracts and replacement sensor procurement.
- Hydrogen infrastructure buildout:Electrolyzer plants and fueling stations in Germany and China require specialized detectors for hydrogen embrittlement and flame-invisible leak scenarios.
- Electrochemical sensor density:Multi-gas architectures now integrate four to six sensor types in palm-sized enclosures, enabling oilfield operators to consolidate fleet inventories.
Market Restraints
- Semiconductor supply concentration:MEMS sensor substrates and ASIC controllers concentrate fabrication in Taiwan and South Korea, exposing detector OEMs to geopolitical logistics disruption.
- REACH material restrictions:ECHA limitations on lead and cadmium in electrochemical cells force reformulation of reference electrodes, extending R&D timelines by 12-18 months.
- Infrared cost premium:NDIR optical benches remain three to five times the unit cost of catalytic bead alternatives, constraining adoption in cost-sensitive environmental monitoring fleets.
Strategic Opportunities
- India industrial safety enforcement:State-level factory inspectorates are mandating gas detection in chemical clusters around Vadodara and Visakhapatnam ahead of national code harmonization.
- Connected safety platforms:Integration of Bluetooth 5.3 and private 5G modules enables real-time location tracking and predictive maintenance algorithms for confined space contractors.
- Battery chemistry evolution:Solid-state lithium architectures and hydrogen fuel cells promise extended runtime in arctic exploration and subsea pipeline inspection applications.
Industry Challenges
- ATEX/IECEx certification backlog:Testing laboratory capacity constraints in Europe delay market entry for novel sensor form factors by six to nine months.
- Legacy system integration:Brownfield chemical plants in the United States and Germany require analog 4-20mA signal conditioning to interface with thirty-year-old distributed control systems.
- Field calibration expertise:Maintenance technicians lack proficiency in multi-point span adjustments across electrochemical, infrared, and photoionization detection principles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Gas Detector Market |
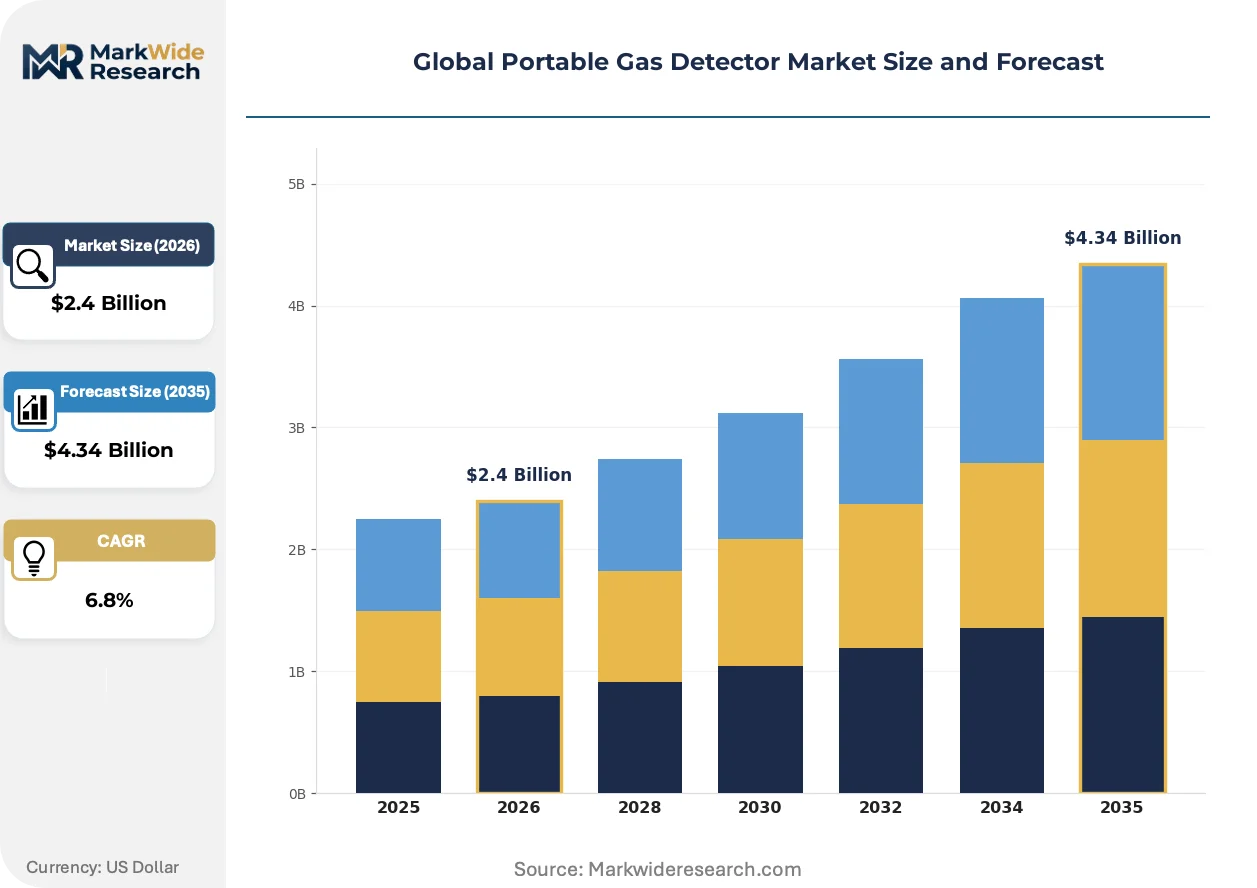
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Gas Detector, Multi-Gas Detector, Thermal Conductivity, Photoionization, Electrochemical, Catalytic Technology: Infrared Sensors, Ultrasonic Sensors, Semiconductor Sensors, Optical Sensors, Electrochemical Sensors, Acoustic Sensors Application: Oilfield Operations, Mining Operations, Firefighting, Confined Space Monitoring, Chemical Processing, Environmental Monitoring End User: Manufacturing Plants, Construction Sites, Emergency Responders, Laboratories, Agricultural Operations, Transportation Facilities |
| Companies Covered | Honeywell International Inc., MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, Industrial Scientific Corporation, Emerson Electric, Halma plc, Teledyne Technologies Incorporated, Riken Keiki, Crowcon Detection Instruments Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Gas Detector Market Shifts & Advancements
Edge computing architectures and predictive algorithms are redefining how gas detection data flows from field instruments to enterprise safety systems, compressing response latency and enabling condition-based maintenance.
Photonic integrated circuits are collapsing the size and power requirements of infrared absorption spectroscopy. Oil majors in the North Sea and Permian Basin are piloting chip-scale NDIR sensors for methane leak detection. This miniaturization is collapsing the cost barrier that previously restricted optical detection to premium industrial accounts.
EPA Risk Management Plan amendments and EU ATEX equipment directives are tightening documentation requirements for functional safety audits. Process industries in Texas and Rotterdam are deploying digital twin simulations to pre-validate alarm setpoints before regulatory inspection. Multi-gas detector firmware now embeds automated calibration logging to satisfy OSHA permissible exposure limit traceability mandates.
Asset-light procurement models are displacing capital purchase cycles in municipal water treatment and waste management sectors. Safety-as-a-service contracts bundle hardware, cloud analytics, and field maintenance into per-device monthly fees. This shift concentrates most visibly in California and the United Kingdom, where facility operators prioritize operational expenditure predictability over balance sheet ownership.
Global Portable Gas Detector Market Segmentation
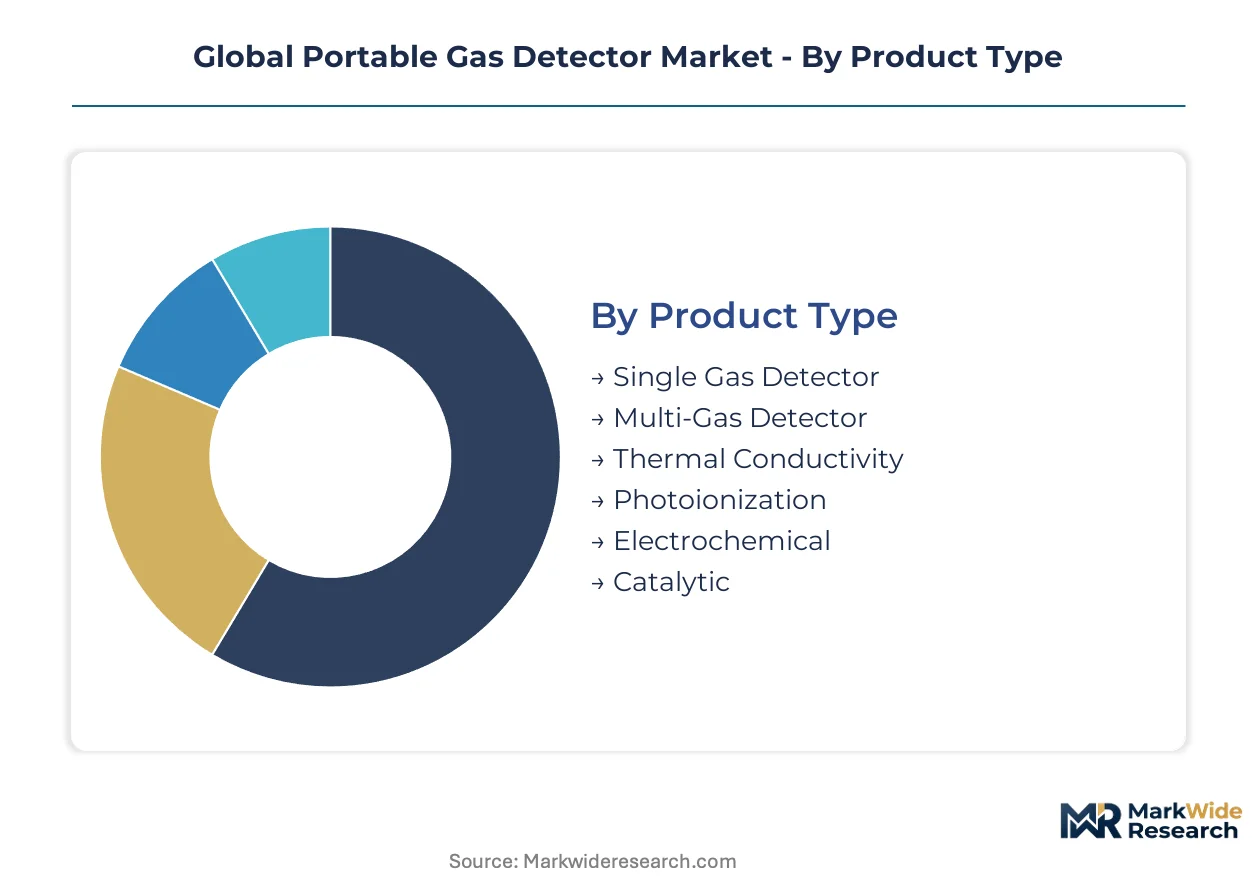
Segmentation in portable gas detectors separates procurement cycles, technical specifications, and compliance burdens across industrial verticals. Understanding these divisions clarifies where sensor replacement revenues concentrate versus where new fleet adoption accelerates.
Product Type:
Replacement cycles vary dramatically across product categories, with single-gas units turning over every 18-24 months while multi-gas platforms persist for 5-7 years in heavy industrial use.
- Multi-Gas Detector:Palm-sized enclosures integrate four to six sensor types simultaneously, commanding premium unit economics through firmware complexity and sensor density. Oilfield operators in Texas and North Dakota consolidate fleet inventories around these platforms to reduce training overhead and spare parts proliferation.
- Single Gas Detector:Dedicated hydrogen sulfide or carbon monoxide monitors dominate confined space contractor toolkits where task-specific hazards are predetermined. Construction sites across Germany deploy these as disposable PPE complements rather than capital assets.
- Thermal Conductivity:Hydrogen-specific detection leverages thermal diffusion principles for electrolyzer plant safety.
- Photoionization:Volatile organic compound detection serves environmental remediation contractors in California.
- Electrochemical:Toxic gas quantification remains the volume backbone for chemical processing applications.
- Catalytic:Combustible gas detection persists in legacy refinery infrastructure.
Single-gas detectors dominate installed base volume. Multi-gas platforms are where expansion concentrates as consolidation economics reshape procurement patterns.
Technology:
Cost tiers separate optical and acoustic innovations from mature electrochemical workhorses, with semiconductor architectures gaining fastest in price-sensitive environmental monitoring.
- Electrochemical Sensors:Amperometric cells using liquid or gel electrolytes deliver sub-ppm precision for hydrogen sulfide, chlorine, and ammonia detection. Chemical processing facilities in Louisiana and Rotterdam specify these for OSHA and ATEX compliance despite quarterly calibration burdens.
- Infrared Sensors:Non-dispersive absorption benches eliminate poisoning risks from silicone or sulfur compounds that destroy catalytic beads. Methane detection in Permian Basin wellheads and North Sea platforms is climbing the fastest as photonic integration collapses unit costs.
- Semiconductor Sensors:Metal-oxide substrates enable fleet-scale deployments where ppb precision is secondary to coverage density.
- Ultrasonic Sensors:Pressure-wave detection locates leaks without gas-specific calibration requirements.
- Optical Sensors:Tunable diode laser absorption targets specific hydrocarbon signatures.
- Acoustic Sensors:Vibration analysis identifies gas release events through sound pattern recognition.
Electrochemical sensors anchor replacement part revenue. Infrared architectures are climbing the fastest as optical miniaturization penetrates mid-market accounts.
Application:
Regulatory intensity varies sharply across use cases, with chemical processing and confined space monitoring facing the strictest calibration documentation while environmental monitoring prioritizes fleet scalability over precision.
- Chemical Processing:Continuous operation in corrosive atmospheres demands stainless steel enclosures and heated sample lines to prevent condensation errors. Facilities along the Texas Gulf Coast and in Germany's Ludwigshafen cluster specify multi-gas units with SIL-rated alarm relays for EPA Risk Management Plan compliance.
- Confined Space Monitoring:Pre-entry atmospheric testing combines oxygen deficiency, combustible, and toxic gas thresholds in single-button operation. Construction contractors in California and emergency responders in New York City face OSHA confined space standard citations driving fleet refresh cycles.
- Oilfield Operations:Drilling and production environments require explosion-proof housings and extended temperature ranges.
- Mining Operations:Underground coal and metal extraction mandates methane and carbon monoxide surveillance.
- Firefighting:Post-fire overhaul operations detect hydrogen cyanide and carbon monoxide in structural collapse zones.
- Environmental Monitoring:Fenceline and ambient air quality applications prioritize sensor density over laboratory-grade accuracy.
Chemical processing commands the highest service contract attachment rates. Confined space monitoring is expanding most quickly as construction safety enforcement tightens in India and Southeast Asia.
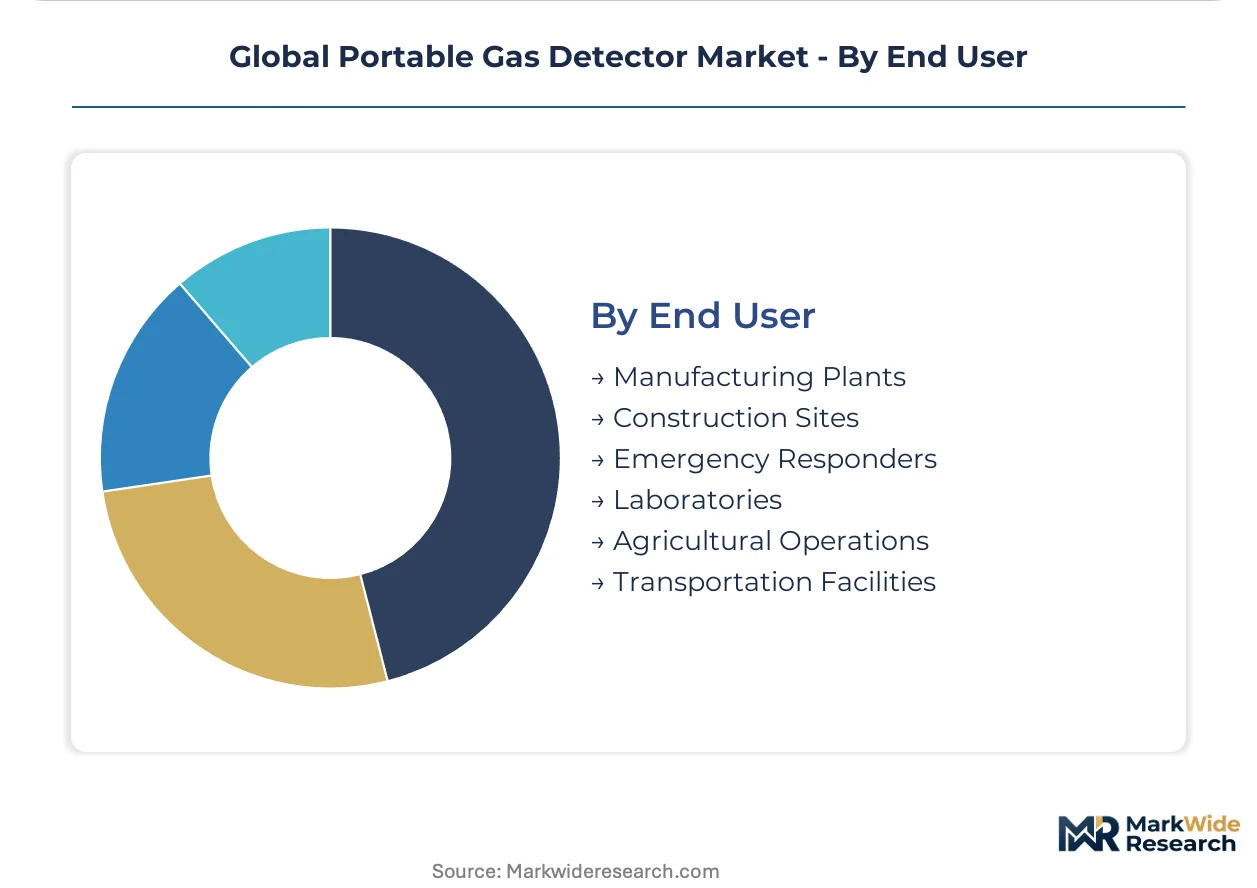
End User:
Procurement sophistication diverges between enterprise manufacturing accounts with integrated safety management systems and fragmented construction subcontractors purchasing through distributor channels.
- Manufacturing Plants:Integrated process safety systems demand 4-20mA analog outputs and Modbus digital interfaces for distributed control system integration. Automotive assembly plants in South Carolina and semiconductor fabs in Arizona specify connected detectors with predictive maintenance algorithms.
- Emergency Responders:Fire departments and hazmat teams prioritize intuitive alarm interpretation under respiratory protection. Urban search and rescue units in Tokyo and London require intrinsically safe designs for collapsed structure entry.
- Construction Sites:Temporary workforce models favor rental and leasing arrangements over capital purchase.
- Laboratories:Research institutions require ppb-level detection for toxic gas storage areas.
- Agricultural Operations:Grain silo and manure pit environments generate hydrogen sulfide and nitrogen dioxide hazards.
- Transportation Facilities:Marine vessel engine rooms and aircraft fueling operations mandate portable backup to fixed detection systems.
Manufacturing plants concentrate premium product demand. Emergency responders represent the steepest expansion trajectory as municipal safety budgets recover post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered detection systems to process industries across the Texas Gulf Coast and China's Yangtze River Delta, establishing a high-technology trade corridor that shapes regional procurement standards.
United States
OSHA calibration mandates and EPA Risk Management Plan requirements drive quarterly service contract expansion across chemical processing facilities. The Permian Basin oilfield operators are consolidating multi-gas detector fleets to reduce training overhead and spare parts proliferation.
Germany
ECHA REACH restrictions on sensor materials and EU ATEX equipment directives force reformulation of electrochemical reference electrodes. The Ludwigshafen chemical cluster specifies multi-gas units with SIL-rated alarm relays for process safety compliance.
China
Hydrogen infrastructure buildout for electrolyzer plants and fueling stations creates specialized detection demand for flame-invisible leak scenarios. State-level factory inspectorates around Shanghai and Shenzhen are mandating gas detection ahead of national code harmonization.
India
Construction safety enforcement tightening in chemical clusters around Vadodara and Visakhapatnam is accelerating confined space monitoring adoption. Central Electricity Authority guidelines for industrial safety are expanding procurement of connected detection systems.
Japan
METI industrial safety standards and hydrogen economy infrastructure codes are redefining sensor specifications for arctic exploration applications. Urban search and rescue units in Tokyo require intrinsically safe designs for collapsed structure entry protocols.
Global Portable Gas Detector Market Competitive Landscape
On the supply side, the industry is consolidating around integrated safety software ecosystems and specialized distribution partnerships. Three strategic archetypes dominate: diversified industrial conglomerates with captive safety divisions, pure-play detection specialists with regional manufacturing scale, and component suppliers expanding downstream into finished instruments. Competitive intensity centers on M&A activity to acquire predictive maintenance algorithms and strategic partnerships to secure semiconductor sensor substrate supply.
Among diversified industrial conglomerates, Honeywell International Inc. and Emerson Electric exemplify the integrated platform archetype through their safety software ecosystems. MSA Safety Incorporated and Drägerwerk AG & Co. KGaA occupy positions as pure-play specialists with established regional manufacturing scale and channel depth. These four companies collectively represent the competitive tension between bundled enterprise solutions and focused detection expertise that structures procurement decisions across oilfield, chemical, and emergency response verticals.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Drägerwerk AG & Co. KGaA |
| Industrial Scientific Corporation |
| Emerson Electric |
| Halma plc |
| Teledyne Technologies Incorporated |
| Riken Keiki |
| Crowcon Detection Instruments Ltd. |
| Others |
Supply & Pricing Matrix
Taiwan's MEMS foundry capacity for sensor substrates and ASIC controllers shapes downstream pricing power for detector OEMs, as fabrication bottlenecks in Hsinchu Science Park transmit cost volatility through electrochemical and infrared product tiers.
Pricing Analysis
Next-generation photonic integrated circuits carry a three-to-five-fold premium over catalytic bead alternatives, while prior-generation electrochemical platforms face compression from semiconductor sensor commoditization. Three-tier pricing structure across premium optical, standard electrochemical, and economy metal-oxide tiers separates buyers by calibration burden tolerance and regulatory exposure. Cost compression in economy tiers is intensifying because fleet-scale environmental monitoring buyers prioritize coverage density over ppb precision. Construction contractors and municipal water treatment operators exhibit highest price sensitivity, whereas chemical processing facilities in Texas and Ludwigshafen accept premium positioning for SIL-rated alarm reliability.
Supply Chain Analysis
Extended payment terms from Taiwanese and South Korean semiconductor suppliers strain working capital for European and North American detector assemblers, forcing supply-chain finance facilities to bridge component procurement cycles. Fabrication concentrates in Taiwan, South Korea, and Germany, with electrochemical cell assembly anchored in Chinese and Mexican plants. Raw material dependencies span palladium catalyst substrates, lead-based reference electrodes, and lithium-ion battery chemistries facing REACH reformulation mandates. Single-source vulnerability in MEMS substrate supply exposes OEMs to geopolitical logistics disruption. Distribution runs through specialized industrial safety distributors and direct enterprise sales teams serving oilfield and chemical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts and replacement sensor procurement are expanding faster than hardware unit sales, as OSHA quarterly calibration mandates and EPA documentation requirements convert transactional buyers into recurring revenue relationships.
For Market Incumbents: Harden firmware ecosystem lock-in by integrating predictive maintenance algorithms with private 5G connectivity modules, neutralizing modular edge-computing entrants fragmenting the technology stack. Deepen backward integration into electrochemical cell manufacturing to insulate margins from ECHA REACH reformulation delays and Taiwan substrate concentration. Prioritize SIL-rated certification investment for chemical processing accounts in the Texas Gulf Coast and Germany's Ludwigshafen cluster. For New Entrants and Emerging Players: Mid-market commercial buildings and municipal water treatment facilities in Southeast Asia represent the most penetrable entry point, as asset-light safety-as-a-service procurement models displace capital purchase cycles. Confined space contractor channels in India around Vadodara and Visakhapatnam offer white-space expansion ahead of national code harmonization. Target distributor partnerships with construction safety specialists rather than direct enterprise sales to bypass incumbent channel control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors predictive analytics software layers and connected safety platform integrators over hardware-centric assemblers. Long-term viability across the projection horizon rests on recurring revenue attachment rates and cloud analytics scalability rather than unit shipment volumes. Acquisition targets should demonstrate established private 5G or Bluetooth 5.3 integration capabilities. Monitor hydrogen economy infrastructure code finalization in Germany, China, and Japan as the critical inflection signal for specialized detector demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Miniaturization Investment | Photonic integrated circuits collapse NDIR cost barriers for methane detection in Permian Basin wellheads. |
| Connected Safety Platform Integration | Bluetooth 5.3 and private 5G modules enable real-time location tracking for confined space contractors. |
| Backward Integration into Cell Manufacturing | In-house electrochemical production insulates margins from REACH-driven reformulation delays. |
| Safety-as-a-Service Model Expansion | Per-device monthly fees attract California water treatment operators prioritizing operational expenditure predictability. |
| Hydrogen Detection Specialization | Electrolyzer plant safety requirements in Germany and China demand flame-invisible leak detection capabilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant safety managers at Texas and Rotterdam chemical facilities, procurement leads at oilfield service companies, distribution channel partners in North American firefighting equipment, and aftermarket service technicians responsible for multi-point span calibrations. Secondary validation drew from OSHA enforcement databases, EPA Risk Management Plan filings, EU ATEX equipment directive documentation, ECHA REACH substance restriction updates, and customs trade records for sensor substrate flows. Bottom-up unit economics triangulated against top-down industrial safety expenditure estimates.
Calibration against historical replacement cycles and regulatory enforcement intensity anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, sensor technology generation, application regulatory intensity, and end-user procurement sophistication. CAGRs derived from elasticity-adjusted adoption curves for hydrogen infrastructure buildout and connected safety platform penetration. Industry-specific forecast inputs incorporated electrolyzer plant commissioning timelines and state-level factory inspectorate mandate expansion in India.
Stress conditions across semiconductor supply disruption severity, REACH reformulation timeline extension, and hydrogen code harmonization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OSHA enforcement continuity and EU ATEX certification laboratory capacity. Macroeconomic contraction, regulatory rollback, or photonic integration breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Infrared Detector Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
IR Detector Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Neutron Detector Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Global Surge Protection Devices Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Electronic Article Surveillance Market
Detection and Regulation Devices
Hitoxic Gas Detector Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market