
 Medical X-Ray Detectors Market | 2026-2036
Medical X-Ray Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Medical X-Ray Detectors Market Insights
The capital-intensity divergence between full-stack imaging OEMs and component specialists is unwinding competitive dynamics across the sector. Siemens Healthineers leverages in-house flat panel fabrication to control detector supply chains for its angiography and mammography systems. Varex Imaging sustains a pure-play component model, supplying amorphous silicon and CMOS detectors to third-party equipment builders across multiple geographies. Canon anchors its position through vertical integration into scintillator crystal growth, a capability that few competitors replicate at equivalent scale.
Medical X-ray detectors are solid-state or photostimulable devices that convert ionizing radiation into electrical signals or digital images, with flat panel detectors employing thin-film transistor arrays on glass substrates achieving spatial resolution below 150 micrometers per pixel. These systems serve the core purpose of replacing analog film cassettes in radiological departments, enabling immediate image preview, dose reduction protocols, and PACS integration. Flat panel detectors occupy the dominant revenue position due to their superior detective quantum efficiency and seamless workflow integration, while CMOS-based technology is gaining fastest in dental and orthopedic segments where lower cost-per-unit and faster readout speeds attract ambulatory settings. Computed radiography detectors retain residual share in veterinary and developing-market installations where capital constraints delay full digital conversion.
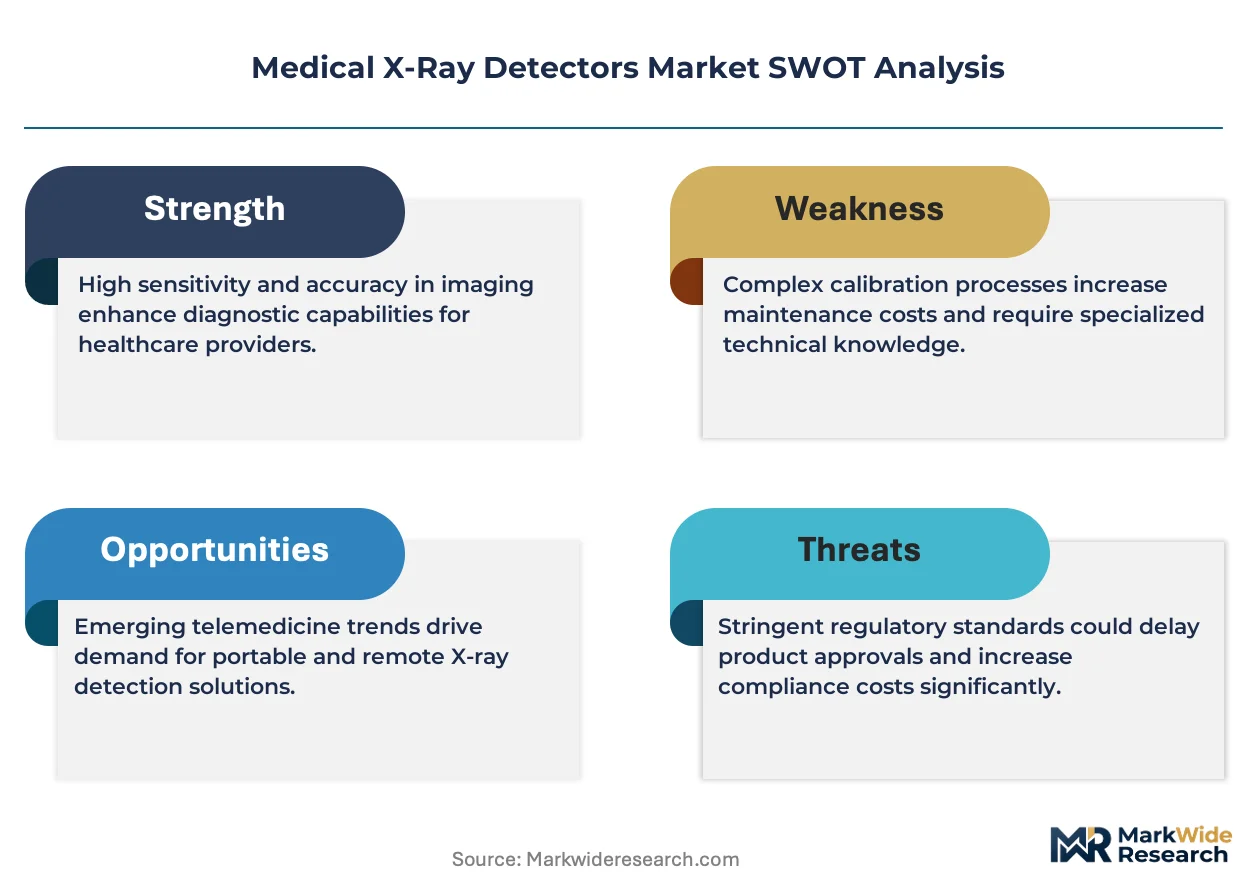
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards shape product development cycles, with both agencies intensifying scrutiny of electromagnetic compatibility and radiation safety declarations. The FDA's quality system regulation and ISO 13485 certification mandates enforce design controls that extend time-to-market for novel detector architectures. Stakeholders must monitor reimbursement code valuations for digital radiography relative to computed radiography, as payer preference signals will determine the pace of replacement demand across hospital systems and outpatient networks.
Market Dynamics
The replacement cycle of legacy computed radiography systems by flat panel detectors is compressing capital equipment timelines across hospital networks, forcing manufacturers to accelerate detector refresh rates while managing semiconductor supply constraints.
Growth Catalysts
- EU MDR compliance deadlines:European diagnostic centers face mandatory equipment recertification, triggering detector upgrade purchases ahead of technical documentation submission windows.
- Amorphous selenium direct conversion:Mammography suites in the United States adopt this material for its superior detective quantum efficiency at lower radiation doses compared to indirect scintillator approaches.
- China's healthcare infrastructure modernization:Provincial hospital expansion programs specify digital radiography suites, creating concentrated procurement windows for detector OEMs.
Market Restraints
- Thin-film transistor substrate concentration:Glass substrate fabrication for active matrix arrays concentrates among Asian suppliers, exposing detector manufacturers to single-source fragility.
- Cesium iodide crystal supply volatility:Scintillator material costs fluctuate with rare earth extraction quotas, compressing margin stability for indirect-conversion detector producers.
- FDA 510(k) pathway complexity:Electromagnetic compatibility validation requirements extend premarket notification review timelines, delaying revenue recognition for novel detector architectures.
Strategic Opportunities
- Veterinary imaging underpenetration:Small-animal practices in Germany retain computed radiography systems, creating conversion runway for cost-optimized flat panel detector offerings.
- CMOS-sensor convergence with wireless transmission:Portable radiography units integrate these technologies, enabling point-of-care imaging in ambulatory surgical centers without fixed-suite infrastructure.
- India's PLI scheme for medical electronics:Domestic manufacturing incentives attract detector assembly investments, reducing import duty exposure for regional equipment builders.
Industry Challenges
- ASIC design talent scarcity:Mixed-signal integrated circuit expertise for readout electronics concentrates among specialized semiconductor design houses, constraining in-house detector controller development.
- PACS integration complexity:Legacy hospital information systems require custom DICOM conformance testing, extending deployment timelines and service engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical X-Ray Detectors Market |
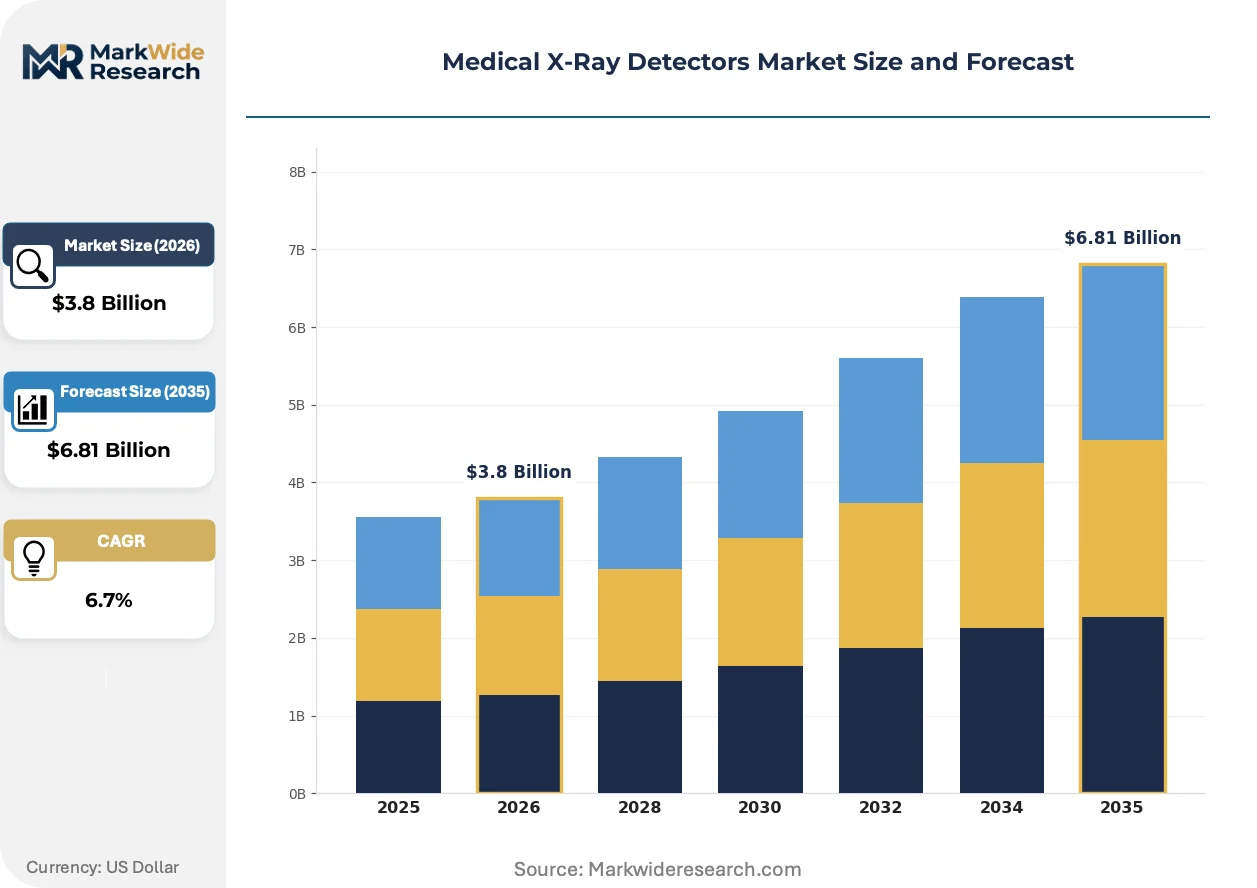
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Computed Radiography Detectors, Photostimulable Phosphor Detectors, Charge Coupled Device Detectors, Indirect Conversion Detectors Application: Dental Imaging, Orthopedic Imaging, Mammography, Fluoroscopy, Gastrointestinal Studies End User: Diagnostic Centers, Dental Clinics, Veterinary Clinics, Ambulatory Surgical Centers Technology: Amorphous Silicon, Complementary Metal Oxide Semiconductor, Charge Coupled Device, Silicon Photodiode |
| Companies Covered | Siemens Healthineers, Varex Imaging, Canon, Fujifilm Holdings Corporation, GE HealthCare, Konica Minolta, Philips, Hamamatsu Photonics, Agfa-Gevaert Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical X-Ray Detectors Market Trends and Innovations
Detector architecture evolution is fragmenting along application-specific performance requirements, with manufacturers diverging between premium quantum efficiency targets and cost-optimized portability specifications.
Direct deposition of cesium iodide onto thin-film transistor arrays improves light conversion efficiency for indirect-conversion detectors. Orthopedic and general radiography departments in the United States and Germany adopt these enhanced scintillator configurations for trauma imaging throughput. The technology is supplanting older powder-deposited scintillator layers that suffered from spatial resolution degradation at oblique incidence angles.
EU MDR technical documentation requirements now mandate clinical performance data for detector subclasses previously exempt from post-market surveillance. Manufacturers must establish quality management system audits beyond prior CE marking self-certification protocols. Mammography detector suppliers face the steepest compliance burden due to higher-risk classification and notified body scrutiny intensity.
Hospital procurement committees now unbundle detector hardware from complete radiography system purchases, sourcing flat panels separately from tube-stand assemblies. Third-party detector integrators in China and India gain channel access previously controlled by full-stack imaging OEMs. This disaggregation is most visible in mid-tier diagnostic centers seeking component-level cost transparency and multi-vendor service flexibility.
Medical X-Ray Detectors Market Segmentation
Medical X-ray detector procurement patterns diverge sharply across clinical settings and imaging modalities. Manufacturers must align product architectures with distinct performance requirements, regulatory pathways, and capital expenditure cycles that vary by segment.
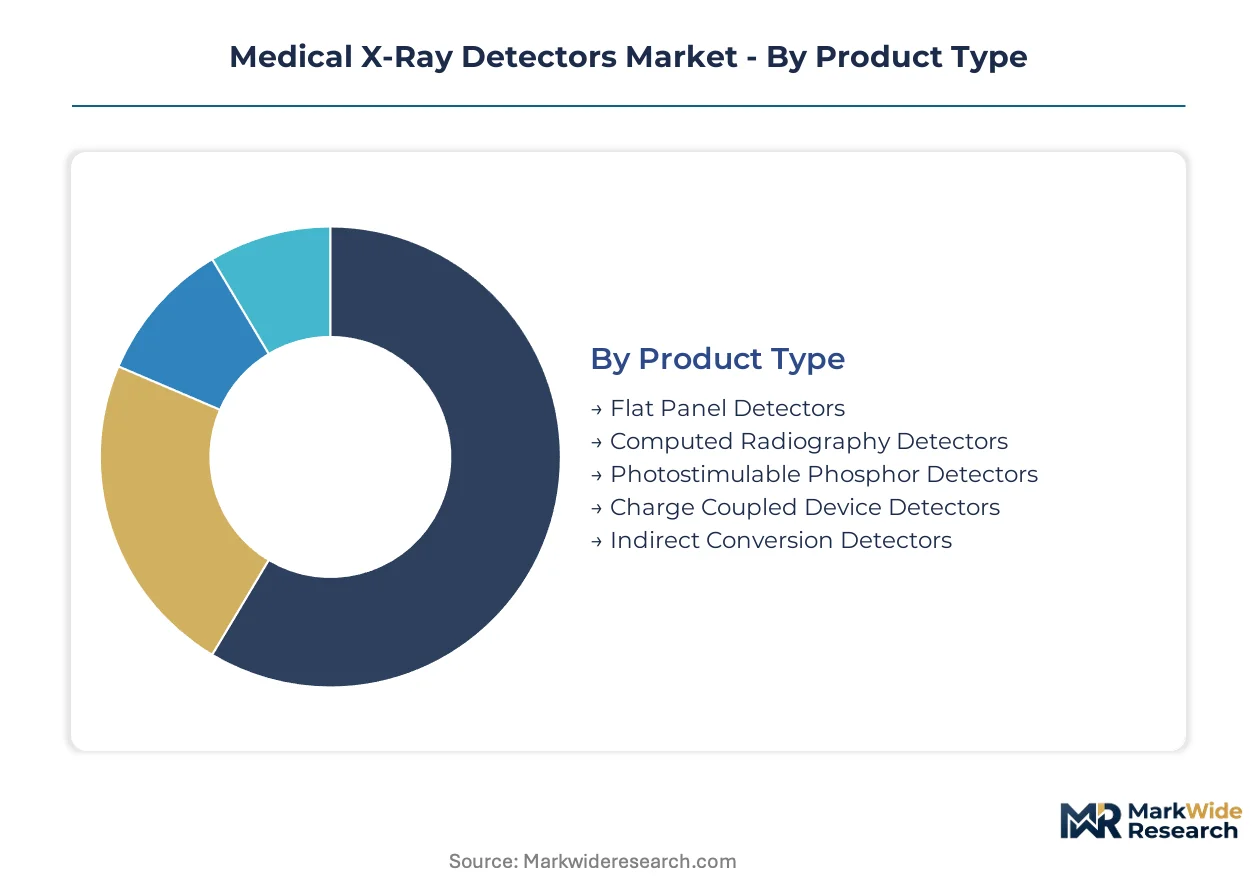
Product Type:
Flat panel detectors dominate export markets to Germany and China, while computed radiography retains domestic relevance in veterinary and developing-market installations where capital constraints persist.
- Flat Panel Detectors:Thin-film transistor arrays on glass substrates achieve spatial resolution below 150 micrometers per pixel. Hospital networks in the United States and Germany concentrate procurement here for immediate image preview and PACS integration capabilities.
- Computed Radiography Detectors:Photostimulable phosphor plates require laser scanning for image readout. Demand concentrates in veterinary clinics across Germany and provincial hospitals in China where equipment refresh cycles lag human-medicine standards.
- Photostimulable Phosphor Detectors:Older-generation technology retained in mobile imaging units for disaster response and military field hospitals.
- Charge Coupled Device Detectors:Legacy architecture supplanted by flat panels in most radiography applications.
- Indirect Conversion Detectors:Scintillator-based signal generation using cesium iodide crystals deposited on active matrix arrays.
Flat panel detectors command the established base. The steepest expansion runs through indirect conversion configurations with enhanced scintillator deposition.
Application:
Cost tier differentiation separates premium mammography systems from standardized dental units, with orthopedic imaging occupying the mid-tier volume position.
- Dental Imaging:CMOS-based compact detectors with wireless transmission enable chairside radiography. Ambulatory dental clinics in the United States and Germany drive volume for lower-cost-per-unit configurations.
- Mammography:Amorphous selenium direct conversion achieves superior detective quantum efficiency at reduced radiation doses. Screening programs in the United States mandate this technology for dose reduction protocols.
- Orthopedic Imaging:Trauma departments require high-throughput detectors for weight-bearing extremity studies.
- Fluoroscopy:Real-time imaging for interventional procedures demands rapid frame rates and thermal management.
- Gastrointestinal Studies:Barium swallow and enema procedures utilize portable detector configurations.
Mammography captures premium pricing tiers. Dental imaging gains share fastest through ambulatory clinic expansion.
End User:
Customer type determines service engineering intensity, with hospital-integrated diagnostic centers requiring complex PACS conformance testing that outpatient clinics avoid.
- Diagnostic Centers:High-throughput facilities integrated with hospital networks specify full-featured flat panel systems with DICOM integration.
- Dental Clinics:Standalone practices prioritize compact footprint and rapid image acquisition over advanced post-processing.
- Veterinary Clinics:Small-animal practices in Germany retain computed radiography systems, creating conversion runway for cost-optimized flat panel offerings.
- Ambulatory Surgical Centers:Point-of-care imaging requirements favor portable CMOS detectors with wireless transmission.
Diagnostic centers command the established base. The steepest expansion runs through ambulatory surgical centers seeking point-of-care capability.
Technology:
Supply concentration for amorphous silicon backplanes creates geographic dependency on Asian substrate fabricators, while CMOS sensor sourcing diversifies across foundry networks.
- Amorphous Silicon:Thin-film transistor backplanes fabricated on glass substrates dominate large-area detector production. Flat panel OEMs depend on concentrated Asian substrate suppliers for active matrix arrays.
- Complementary Metal Oxide Semiconductor:Silicon foundry production enables faster readout speeds and lower power consumption. Dental and orthopedic segments in ambulatory settings adopt this for portable unit integration.
- Charge Coupled Device:Legacy technology retained in specialized scientific and industrial imaging applications.
- Silicon Photodiode:Direct conversion architectures for mammography and extremity imaging requiring high spatial resolution.
Amorphous silicon commands the established base. The steepest expansion runs through complementary metal oxide semiconductor adoption in portable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German diagnostic centers absorb premium pricing for mammography-grade detectors, while provincial Chinese hospitals prioritize cost-optimized flat panel configurations. Indian equipment builders exhibit the highest price sensitivity, driving procurement of component-level detector assemblies rather than integrated systems.
United States
Hospital network consolidation concentrates procurement power among integrated delivery systems. FDA 510(k) premarket notification requirements extend review timelines for novel detector architectures, particularly for electromagnetic compatibility validation. The Boston-Cambridge corridor hosts specialized semiconductor design houses supplying ASIC readout electronics to detector OEMs.
Germany
Small-animal veterinary practices retain computed radiography systems, creating conversion runway for cost-optimized flat panel offerings. EU MDR technical documentation mandates now require clinical performance data for detector subclasses, accelerating recertification-driven upgrade cycles. Bavaria's medical technology cluster around Munich anchors detector assembly operations serving Central European diagnostic networks.
China
Provincial hospital expansion programs specify digital radiography suites, creating concentrated procurement windows. NMPA registration pathways for Class II medical devices enforce quality management system audits that extend time-to-market. The Yangtze River Delta concentration of thin-film transistor substrate fabricators exposes detector manufacturers to single-source supply fragility.
India
Domestic equipment builders source detector assemblies to avoid import duty exposure on finished systems. The PLI scheme for medical electronics attracts component assembly investments, reducing landed cost for regional radiography manufacturers. Karnataka's Bengaluru-Tumkur corridor hosts emerging detector integration facilities serving South Asian diagnostic markets.
Japan
CMOS sensor adoption in dental and orthopedic segments advances fastest among ambulatory clinics seeking portable configurations. PMDA quality system requirements align with global ISO 13485 standards, enabling streamlined dual-market registration. The Kansai region's precision manufacturing base supplies scintillator crystal processing equipment to indirect-conversion detector producers.
Medical X-Ray Detectors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-stack imaging OEMs controlling captive detector supply chains while component specialists serve third-party equipment builders. Siemens Healthineers leverages in-house flat panel fabrication for angiography and mammography systems. Varex Imaging sustains a pure-play component model across multiple geographies. Canon anchors its position through upstream control over scintillator crystal growth. The dominant competitive moves are backward integration into semiconductor fabrication and geographic expansion through regional assembly partnerships.
Among integrated imaging system OEMs, Siemens Healthineers and GE HealthCare exemplify the full-stack archetype, controlling detector supply chains for proprietary equipment lines. Varex Imaging occupies a distinct position as a pure-play component supplier, enabling multi-vendor detector sourcing for regional equipment builders. Canon represents the materials-integrated tier, with captive scintillator capabilities that few competitors replicate at equivalent scale. These three archetypes—full-stack OEM, component specialist, and materials-integrated player—structure competitive positioning across procurement segments.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Varex Imaging |
| Canon |
| Fujifilm Holdings Corporation |
| GE HealthCare |
| Konica Minolta |
| Philips |
| Hamamatsu Photonics |
| Agfa-Gevaert Group |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for thin-film transistor glass substrates concentrate pricing power among Asian foundries serving detector OEMs in Germany and the United States. This inventory compression forces manufacturers to absorb cost volatility or push price adjustments downstream to hospital procurement committees unbundling hardware purchases.
Pricing Analysis
Service contracts and replacement part revenues now exceed initial hardware margins as the dominant lifetime value driver. Three-tier pricing structure across premium mammography-grade, standard radiography, and economy veterinary configurations separates Siemens Healthineers from Varex Imaging's component supply. Price differentiation hinges on FDA 510(k) clearance tier and scintillator crystal quality grade. Margins are tightening due to cesium iodide supply volatility. Indian equipment builders exhibit highest price sensitivity; German diagnostic centers absorb premium tiers with minimal negotiation.
Supply Chain Analysis
Inventory positions for amorphous silicon backplanes run lean across detector assembly facilities in China, Japan, and South Korea. Glass substrate fabrication draws from concentrated Yangtze River Delta suppliers. Scintillator crystal growth and CMOS sensor foundry output constitute critical input dependencies. Single-source vulnerability for active matrix arrays exposes manufacturers to disruption. Distribution runs through regional equipment builders in India and third-party integrators in China rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detector procurement unbundling fragments channel control, creating entry niches for component specialists and regional assemblers as hospital committees demand cost transparency.
For Market Incumbents: Consolidate captive scintillator capabilities and flat panel fabrication to defend against third-party detector integrators eroding system-level pricing. Lock in long-term glass substrate offtake agreements with Yangtze River Delta suppliers to mitigate single-source concentration risk. Accelerate EU MDR technical documentation completion ahead of notified body bottlenecks. For New Entrants and Emerging Players: Post-sale calibration and DICOM conformance services represent the most exploitable gap where full-stack OEMs under-serve mid-tier diagnostic centers. Veterinary clinics in Germany retain computed radiography systems and offer penetrable conversion demand for cost-optimized flat panel configurations. Pursue PLI scheme partnerships with Karnataka-based assembly facilities to bypass import duty exposure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because detector procurement unbundling will compress component specialists before vertical reintegration waves. Target pure-play flat panel fabricators with established FDA 510(k) clearances and Asian substrate relationships. Watch NMPA Class II registration timelines in China as inflection signal for regional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Accelerates recertification-driven upgrade cycles ahead of notified body scrutiny intensity. |
| Scintillator Crystal Backward Integration | Canon anchors positioning through captive cesium iodide growth capabilities few competitors replicate. |
| CMOS-Wireless Portable Unit Development | Enables point-of-care imaging in ambulatory surgical centers without fixed-suite infrastructure. |
| India PLI Scheme Assembly Investment | Reduces landed cost for regional equipment builders sourcing detector components. |
| Hospital System Direct Partnership | Bypasses third-party integrators as procurement committees unbundle detector hardware purchases. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and detector OEM product managers; and secondary validation against FDA 510(k) filings, NMPA Class II registration databases, EU MDR notified body documentation, and hospital procurement contract repositories. Bottom-up unit demand estimates triangulated with top-down market sizing across flat panel and computed radiography configurations.
Across the modeling period, projections incorporate technology substitution curves for CMOS versus amorphous silicon architectures, regulatory compliance cost burdens, and geographic procurement concentration patterns. Segmentation dimensions span product type, application modality, end-user facility tier, and technology substrate. CAGRs derive from fitted adoption curves calibrated to equipment replacement cycles and infrastructure modernization program announcements.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR enforcement timelines, and NMPA quality system audits; material policy shifts would require re-modeling. Outputs reflect assumptions about semiconductor supply normalization and rare earth extraction quota stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Photography Equipment Market
Imaging
Uncooled Infrared Camera Market
Imaging
Photoacoustic Tomography Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Microwave Imaging Market
Imaging
SDI Camera Market
Imaging
Europe CT Market
Imaging
Fiducial Markers Market
Imaging
Handheld Retinal Scanners Market
Imaging
Cinematographic Camera Market
Imaging
Ent Cameras Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Digitizer Market
Imaging
Thermal Imaging Market
Imaging
High-Speed Camera Market
Imaging
Printed Image Sensors Market