

Battery Off-Gas Detection and Early Warning Test Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Off-Gas Detection and Early Warning Test Solutions Market Insights
Aftermarket calibration and sensor-recertification services is rewriting margin distribution across the value chain. Honeywell leverages its distributed service infrastructure to capture recurring revenue from battery testing labs. Nexceris anchors its position through electrochemical sensor specialization for lithium-ion off-gas signatures. MSA Safety competes on portable detection platforms deployed across industrial battery maintenance crews.
Battery off-gas detection and early warning test solutions comprise electrochemical and infrared sensor arrays calibrated to detect hydrogen, carbon monoxide, and hydrocarbon evolution at ppm thresholds, with integrated controllers triggering automated ventilation or shutdown protocols to prevent thermal runaway propagation. Electrochemical technology dominates installed base economics due to lower per-unit cost and established calibration workflows, while infrared analyzers command premium positioning in aerospace and energy storage system validation where multi-species discrimination matters. Application demand skews heavily toward electric vehicles and energy storage systems as cell format diversification and higher-nickel chemistries intensify off-gas complexity.
The EU Battery Regulation, UN ECE R100, and OSHA workplace exposure limits collectively mandate traceable off-gas detection across battery manufacturing, storage, and end-of-life handling, forcing vendors to certify against multiple jurisdictional standards simultaneously. EMA and ECHA frameworks in Europe further tighten chemical hazard classification requirements for electrolyte decomposition products. Stakeholders must monitor evolving certification body protocols in Germany and South Korea as these jurisdictions pioneer next-generation thermal runaway test methodologies that will reshape product qualification timelines.
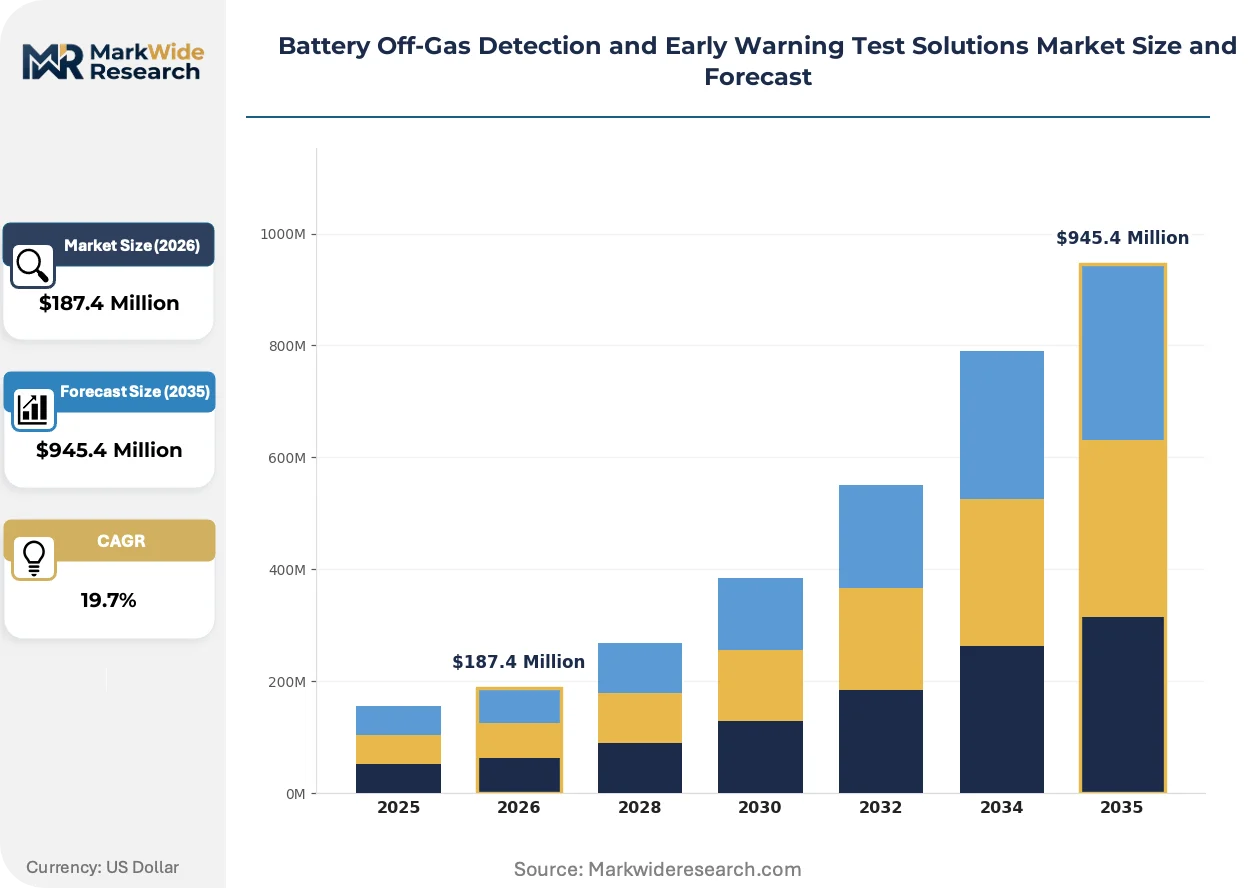
Market Dynamics
EU Battery Regulation enforcement timelines and UN ECE R100 homologation requirements are compressing certification cycles for off-gas detection architectures, forcing sensor vendors to pre-validate multi-jurisdictional compliance before product launch.
Growth Catalysts
- EU Battery Regulation:Mandatory off-gas monitoring across battery production and second-life phases creates installed-base expansion for electrochemical sensor arrays in German automotive OEM facilities.
- Solid-state battery prototyping:Next-generation cell chemistries with novel electrolyte decomposition signatures require recalibrated detection thresholds, generating replacement demand for legacy sensor platforms.
- German certification cluster:KBA and TÜV Rheinland co-development of thermal runaway test protocols positions domestic vendors for first-mover qualification advantages across European markets.
Market Restraints
- Palladium catalyst supply:Electrochemical sensor electrodes depend on concentrated Russian and South African palladium refining, exposing production costs to geopolitical supply disruptions.
- Infrared analyzer cost structure:Multi-species discrimination capabilities require indium antimonide detector arrays priced at 8-12x electrochemical equivalents, limiting penetration beyond aerospace validation labs.
- REACH registration burdens:ECHA chemical hazard classifications for electrolyte decomposition products impose 18-24 month pre-market notification timelines for new sensor membrane formulations.
Strategic Opportunities
- India battery manufacturing:PLI scheme incentives for domestic cell production create greenfield demand for off-gas detection in gigafactory construction, unburdened by legacy infrastructure retrofit constraints.
- Cloud-based predictive maintenance:Sensor-to-platform integration enables subscription revenue models for thermal runaway risk scoring, displacing capital-intensive hardware-only sales in fleet operator segments.
- Second-life storage systems:Decommissioned EV batteries repurposed for stationary energy storage require continuous off-gas surveillance through end-of-life handling, extending sensor service lifecycles.
Industry Challenges
- Cross-disciplinary calibration expertise:Electrochemistry, firmware engineering, and regulatory compliance competencies rarely concentrate in single hiring pools, inflating R&D team assembly timelines.
- Legacy BMS integration:Proprietary communication protocols from established battery management system vendors force costly adapter development for third-party detection hardware.
- Multi-standard certification parallelism:Simultaneous UN ECE R100, UL 9540A, and IEC 62660 validation requirements duplicate testing expenditure without harmonized mutual recognition.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Off-Gas Detection and Early Warning Test Solutions Market Trends and Innovations
Digital twin architectures are virtualizing physical validation workflows across battery safety testing, compressing development cycles while expanding the addressable scope of predictive detection systems beyond laboratory boundaries.
Photonic integrated circuits are virtualizing infrared absorption spectroscopy by consolidating benchtop analyzer functions onto silicon photonics chips. German automotive Tier-1 suppliers are piloting these miniaturized platforms for in-vehicle distributed sensing. The technology is virtualizing component count and power budgets that previously confined multi-species detection to stationary validation rigs.
REACH authorization timelines for perfluorinated electrolyte additives are accelerating substitution toward carbonate-based formulations with distinct off-gas signatures. Detection vendors must recalibrate sensor libraries mid-certification cycle. Energy storage system integrators in the Netherlands and Denmark face immediate sensor requalification obligations ahead of Q3 2025 enforcement windows.
Aftermarket recertification services are unbundling from original equipment sales as battery testing laboratories seek ISO 17025 traceability without captive calibration infrastructure. Independent service providers in South Korea and Japan are capturing recurring revenue through annual sensor drift correction and regulatory documentation packages. Fleet operators with distributed charging depots favor subscription-based sensor health monitoring over capital-intensive ownership models.
Battery Off-Gas Detection and Early Warning Test Solutions Market Segmentation
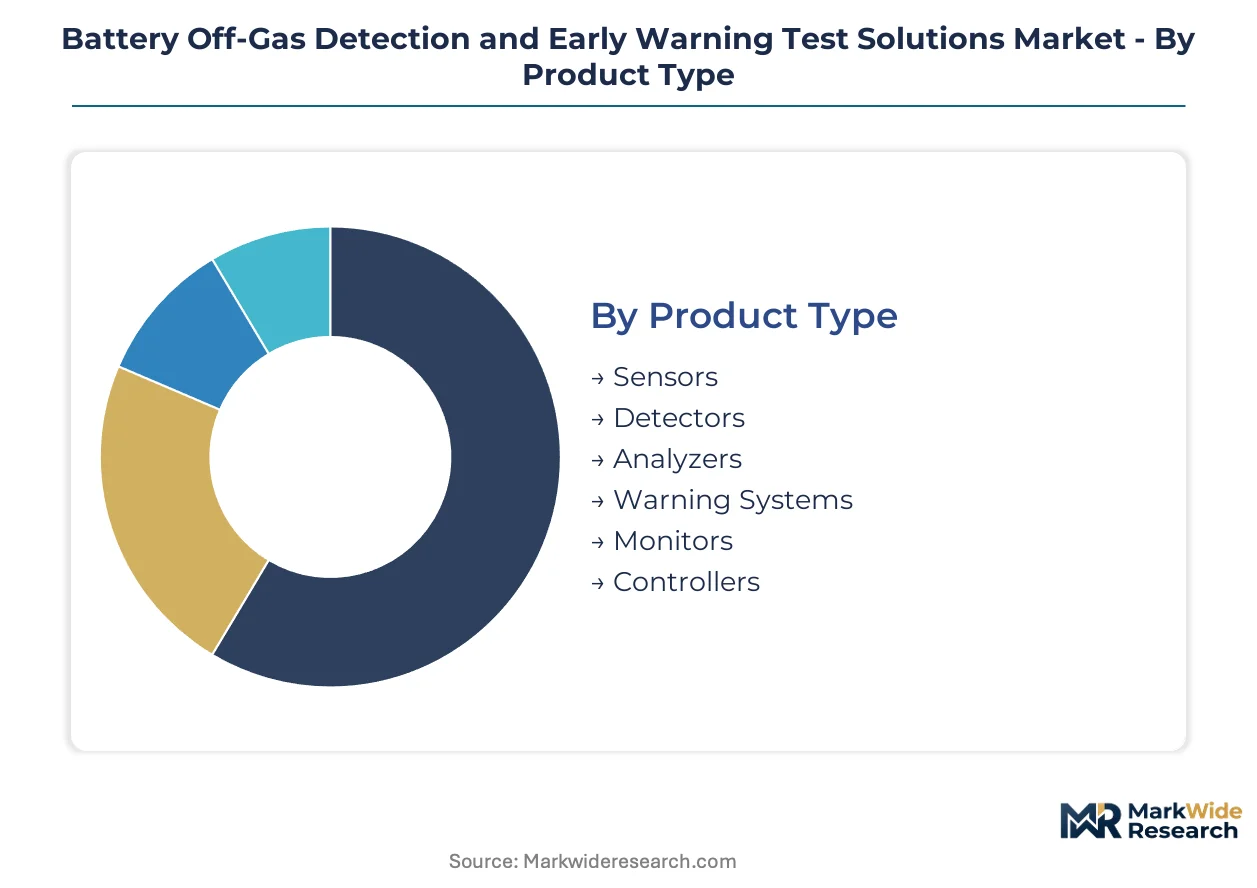
Segmentation in battery off-gas detection reveals how technical specifications, regulatory mandates, and end-use risk profiles fragment procurement patterns. Vendors must align sensor architectures with distinct certification timelines and thermal runaway severity levels across customer categories.
Product Type:
Mature electrochemical platforms anchor installed base economics while emerging photonic-integrated analyzers redefine performance boundaries in aerospace validation.
- Sensors:Discrete electrochemical cells calibrated to hydrogen, carbon monoxide, and hydrocarbon thresholds at parts-per-million resolution. Automotive OEMs in Germany specify these for in-vehicle distributed arrays ahead of UN ECE R100 homologation deadlines.
- Analyzers:Multi-species infrared absorption systems with indium antimonide detector arrays discriminating electrolyte decomposition signatures. Aerospace battery validation labs in France and the United States absorb premium unit economics for traceable thermal runaway forensics.
- Detectors:Single-point alarm devices triggering ventilation shutdown at threshold breach.
- Warning Systems:Audible-visual annunciators integrated with building management systems.
- Monitors:Continuous data-logging platforms with cloud connectivity for fleet depot surveillance.
- Controllers:Programmable logic units executing automated emergency protocols.
Sensors retain volume leadership; analyzers hold the steepest expansion curve.
Technology:
Cost tier stratification separates commodity electrochemical production from premium spectroscopic platforms requiring exotic material inputs.
- Electrochemical:Palladium-catalyzed electrodes operating at ambient temperature with established calibration workflows. Battery manufacturers in South Korea and Germany dominate procurement volumes for production line integration.
- Infrared:Non-dispersive absorption spectroscopy with multi-species discrimination capability. Energy storage system integrators in Denmark and the Netherlands specify these ahead of REACH authorization enforcement for electrolyte additive monitoring.
- Photoionization:Ultraviolet lamp ionization for volatile organic compound detection.
- Metal Oxide Semiconductor:Solid-state resistance-change detection for hydrogen surveillance.
- Catalytic:Wheatstone bridge pellistor arrays for combustible gas screening.
- Ultrasonic:Acoustic emission analysis detecting cell venting precursors.
Electrochemical platforms dominate procurement volumes; infrared configurations command the highest value-per-unit trajectory.
Application:
Application demand concentrates where cell format diversification and higher-nickel chemistries intensify off-gas complexity and thermal runaway propagation risk.
- Electric Vehicles:Distributed cabin and battery pack sensing architectures with millisecond response latency. German automotive OEMs and Tier-1 suppliers co-develop detection protocols with KBA and TÜV Rheinland certification bodies.
- Energy Storage Systems:Container-level and rack-level monitoring for utility-scale and commercial installations. Project developers in India under PLI scheme incentives specify detection infrastructure for greenfield gigafactory construction.
- Consumer Electronics:Compact single-point detectors for portable device battery compartments.
- Aerospace:FAA-certifiable multi-species analyzers for aircraft battery bay surveillance.
- Industrial Equipment:Forklift and material handling fleet maintenance protocols.
- Smart Grids:Grid-stabilization battery asset protection with predictive maintenance integration.
Electric vehicle applications anchor current revenue concentration; energy storage systems are expanding most quickly as stationary deployment scales.
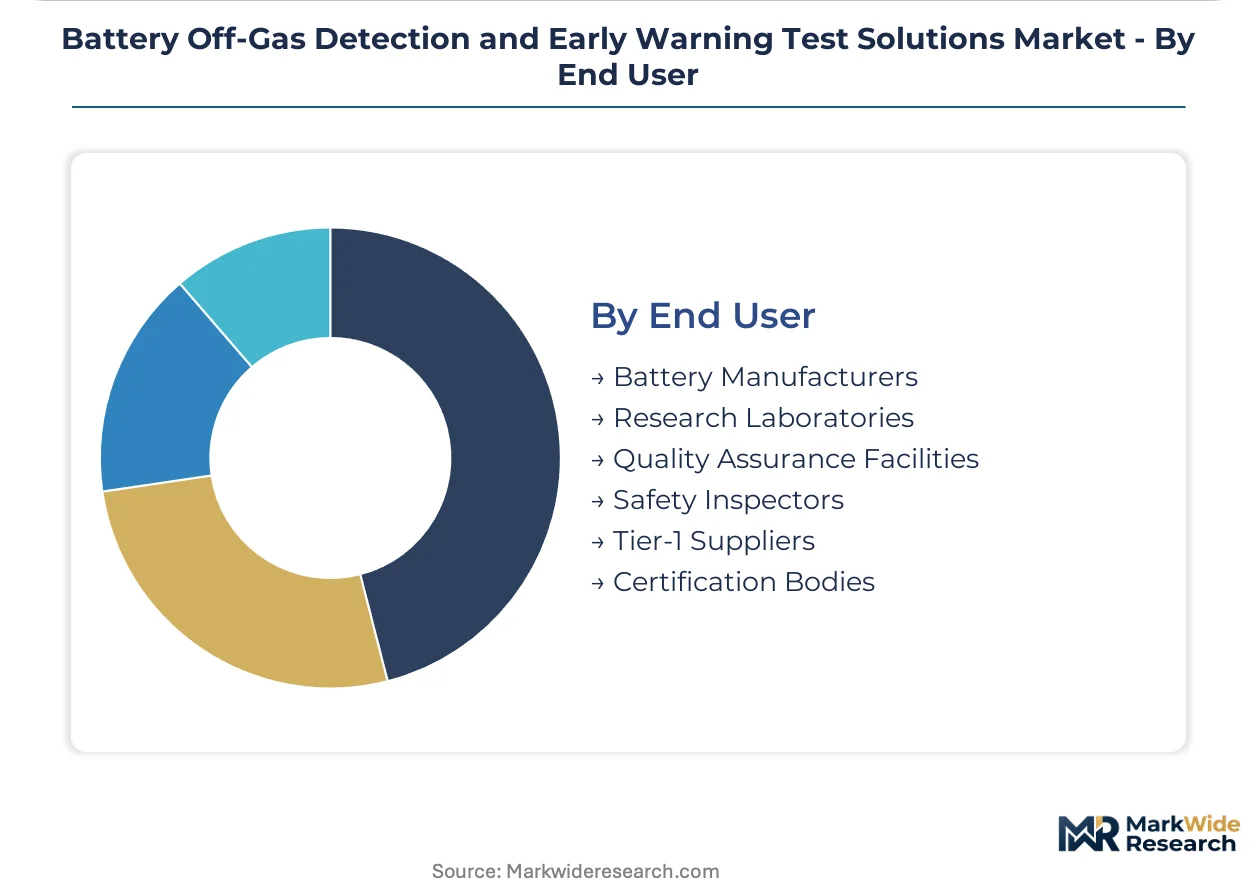
End User:
Customer type determines procurement sophistication, from standardized production line integration to bespoke research calibration requirements.
- Battery Manufacturers:High-volume sensor procurement for formation, aging, and storage facility monitoring. Cell producers in Germany and South Korea drive standardization demands through certification body co-development programs.
- Certification Bodies:Reference-grade analyzer procurement for thermal runaway test protocol validation. TÜV Rheinland and KBA in Germany pioneer methodologies subsequently adopted across European markets.
- Research Laboratories:Configurable platforms for next-generation chemistry characterization.
- Quality Assurance Facilities:Production sampling and incoming inspection protocols.
- Safety Inspectors:Portable detection equipment for field audit deployment.
- Tier-1 Suppliers:Module and pack-level integration for OEM supply contracts.
Battery manufacturers retain procurement volume leadership; certification bodies hold the steepest capability investment trajectory as protocol complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs deploy distributed sensor arrays for in-vehicle thermal runaway prevention, while Indian project developers specify detection infrastructure for greenfield gigafactory construction under production-linked incentives. This consumption-mix differential separates mature regulatory compliance markets from capacity-buildout frontiers.
Germany
KBA and TÜV Rheinland co-develop next-generation thermal runaway test protocols that reshape European qualification timelines. The EU Battery Regulation mandates off-gas monitoring across production and second-life phases. Stuttgart and Munich anchor automotive OEM and Tier-1 supplier co-development programs for UN ECE R100 homologation.
United States
FAA-certifiable multi-species analyzers serve aircraft battery bay surveillance requirements from aerospace validation labs. OSHA workplace exposure limits enforce traceable detection across battery manufacturing and storage facilities. California and Washington State concentrate energy storage system integrators specifying container-level monitoring for utility-scale deployment.
India
PLI scheme incentives for domestic cell production generate greenfield demand unburdened by legacy infrastructure retrofit constraints. CEA technical standards for battery energy storage systems incorporate off-gas surveillance mandates. Gujarat and Tamil Nadu host gigafactory construction where detection infrastructure is specified from commissioning.
South Korea
MFDS and KATS frameworks govern chemical hazard classification for electrolyte decomposition products in manufacturing environments. Cell producers drive standardization demands through certification body engagement for IEC 62660 validation. Seoul and Ulsan concentrate high-volume sensor procurement for formation and aging facility monitoring.
Netherlands
REACH authorization timelines for perfluorinated electrolyte additives force immediate sensor requalification obligations for energy storage system integrators. ECHA chemical hazard classifications impose pre-market notification timelines for new sensor membrane formulations. Eindhoven and Rotterdam host project developers specifying infrared analyzers for additive monitoring ahead of enforcement windows.
Battery Off-Gas Detection and Early Warning Test Solutions Market Competitive Landscape
Capability concentration sits with electrochemical specialists and photonic-integrated circuit developers; scale advantage sits with diversified industrial safety conglomerates leveraging distributed service infrastructure. The market structures around three archetypes: component specialists optimizing sensor specificity, integrated platform vendors bundling hardware with predictive analytics, and certification-aligned reference-grade suppliers. Consolidation pressure favors M&A between sensor technology developers and cloud-platform integrators; geographic expansion into Indian and Southeast Asian manufacturing corridors represents the parallel competitive move.
Among diversified industrial safety conglomerates, Honeywell occupies a position exemplifying service-network scale for aftermarket calibration revenue capture. Electrochemical specialists include Nexceris, which sits within the sensor-specific tier representing off-gas signature optimization. Portable detection platform vendors include MSA Safety, anchoring the industrial maintenance crew deployment segment.
| Leading Market Players |
|---|
| Honeywell |
| Nexceris |
| FM |
| MSA Safety |
| Drägerwerk |
| Industrial Scientific |
| Crowcon Detection Instruments |
| Figaro Engineering |
| Winsen |
| Others |
Pricing and Supply Chain Analysis
Palladium refining concentration in Russia and South Africa funnels margin capture toward electrochemical sensor specialists with secured catalyst supply agreements, while infrared analyzer vendors absorb indium antimonide detector premiums through aerospace certification lock-in.
Pricing Analysis
Long-term offtake contracts dominate procurement between German automotive OEMs and electrochemical sensor vendors, locking in volume commitments ahead of UN ECE R100 homologation deadlines. Price differentiation stems from certification tier—UL 9540A-validated analyzers command substantial premiums over standard production-line sensors—and from after-sales service bundling. Cost compression in commodity electrochemical cells is intensifying because South Korean and Chinese manufacturers are scaling palladium-catalyzed electrode production. Fleet operators with distributed charging depots exhibit the highest price sensitivity, favoring subscription-based sensor health monitoring over capital-intensive hardware ownership.
Supply Chain Analysis
Indium antimonide detector feedstock draws from specialized semiconductor foundries in the United States and Japan, while palladium catalyst supply rests on Russian and South African refining infrastructure. Critical inputs span noble metal catalysts, photonic integrated circuit substrates, and fluoropolymer sensor membranes. Single-source vulnerability concentrates in indium antimonide wafer supply for infrared analyzer production. Distribution runs through battery testing laboratory networks and Tier-1 supplier integration channels rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-to-cloud platform economics are displacing hardware-only sales as fleet operators demand predictive thermal runaway risk scoring, creating interoperability premiums for vendors with integrated analytics stacks.
For Market Incumbents: Harden certification-aligned reference-grade positioning through deeper engagement with KBA and TÜV Rheinland protocol co-development, insulating against photonic-integrated circuit miniaturization threats from German automotive Tier-1 suppliers. Prioritize backward integration into palladium catalyst supply through offtake agreements with South African refiners, securing electrode cost stability against geopolitical disruption. For New Entrants and Emerging Players: Greenfield gigafactory construction under India's PLI scheme represents the most penetrable entry point, unburdened by legacy BMS integration constraints that entrench established vendors in European markets. Target cloud-based predictive maintenance subscriptions for fleet depot operators seeking to avoid capital-intensive sensor ownership, leveraging API-first architectures to bypass proprietary communication protocol barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with electrochemical sensor specialists possessing ISO 17025 traceability infrastructure but lacking cloud-platform integration capabilities. Five-to-ten year viability hinges on regulatory enforcement trajectory rather than technology substitution risk. Watch for REACH authorization timeline acceleration for perfluorinated electrolyte additives as the inflection signal forcing sensor recalibration demand and requalification services expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Miniaturization | Consolidates benchtop analyzer functions onto silicon photonics chips for in-vehicle distributed sensing. |
| Cloud-Based Predictive Maintenance Platform | Enables subscription revenue models displacing capital-intensive hardware sales for fleet operators. |
| Palladium Catalyst Supply Agreement | Secures electrode cost stability against Russian and South African geopolitical supply disruptions. |
| Certification Body Protocol Co-Development | Positions vendors for first-mover qualification advantages with KBA and TÜV Rheinland. |
| Second-Life Storage System Monitoring Extension | Extends sensor service lifecycles through continuous off-gas surveillance of decommissioned EV batteries. |
Research Methodology
A standing panel of battery safety test engineers, automotive OEM platform architects, certification body technical leads, and energy storage system integrators provided ongoing calibration against secondary validation sources. Primary fieldwork combined structured interviews with these stakeholders alongside analysis of UN ECE R100 homologation filings, EU Battery Regulation implementation guidance, IEC 62660 validation protocols, and SEC disclosures from listed industrial safety conglomerates. Bottom-up sensor procurement volume estimates triangulated against top-down market sizing from certification body test protocol expansion timelines.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling demand trajectories under varying EU Battery Regulation enforcement intensities and solid-state battery chemistry commercialization paths. Segmentation dimensions spanned product architecture, detection technology, application severity tier, and end-user procurement sophistication. CAGRs derived from installed base expansion rates for electrochemical sensors and replacement demand curves for infrared analyzers. Forecast inputs incorporated REACH authorization timeline acceleration for electrolyte additives and PLI scheme gigafactory construction schedules in India.
Macroeconomic conditions sit as an overlay; deviation in palladium commodity pricing, indium antimonide wafer availability, or EU regulatory enforcement cadence would shift the trajectory. Cross-checking against certification body test protocol publication schedules and automotive OEM platform engineering disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.