
 Dental Regeneration Market | 2026-2036
Dental Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Regeneration Market Insights
Specialist dental distributor networks is tilting toward direct-to-clinic procurement platforms that bypass traditional intermediaries. Institut Straumann AG leverages its vertically integrated manufacturing footprint to control premium implant-biomaterial bundles across Europe. Geistlich Pharma AG anchors its position through proprietary collagen extraction protocols that sustain clinician loyalty in guided bone regeneration. Dentsply Sirona competes by extending its digital dentistry workflow into regenerative case planning software.
Dental regeneration encompasses clinical interventions that restore alveolar bone, periodontal ligament, and pulp-dentin complex using biocompatible matrices with defined porosity exceeding 90% and controlled resorption rates matched to bone formation timelines. Bone grafts dominate current revenue as clinicians default to mineralized allograft and bovine xenograft for socket preservation, while growth factors represent the fastest-expanding margin pool as recombinant human platelet-derived formulations command premium reimbursement in periodontal defect repair. Injectable solutions lead delivery mode adoption for minimally invasive sinus lift procedures, though solid implants retain preference in ridge augmentation where dimensional stability determines outcomes.
FDA 510(k) premarket notification and EMA Medical Device Regulation classification govern biocompatibility testing and clinical evidence requirements for collagen membranes and synthetic scaffolds entering the United States and European Union markets. ISO 10993 biological evaluation standards and ASTM F2150 bone graft substitute specifications further constrain material selection and manufacturing validation protocols for ceramic and polymer substrates. Stakeholders must monitor evolving reimbursement coding for regenerative procedures across national health systems and private payers to align portfolio investments with coverage expansion trajectories.
Market Dynamics
Oral surgeons in hospital-affiliated dental clinics now demand bone graft substitutes with validated osteoconductive performance, forcing manufacturers to prioritize biocompatibility data over marketing claims. This clinical evidence imperative is compressing product development timelines and reshaping competitive positioning across the value chain.
Growth Catalysts
- FDA 510(k) pathway clarity:The FDA's streamlined premarket notification process for collagen membranes accelerates commercialization timelines for synthetic scaffold developers targeting the United States.
- Aging implantology volume:Germany's expanding geriatric population drives socket preservation procedures requiring mineralized allograft and bovine xenograft solutions.
- Recombinant protein synthesis:Advancements in recombinant human platelet-derived growth factor production enable premium reimbursement capture in periodontal defect repair across South Korea.
Market Restraints
- Bovine-derived material sourcing:Supply concentration risk in European abattoir networks creates input volatility for xenograft manufacturers dependent on proprietary collagen extraction protocols.
- EMA MDR clinical evidence burden:The European Union's Medical Device Regulation mandates extended biocompatibility testing timelines that delay collagen membrane launches by 18-24 months.
- Synthetic ceramic substitution:Beta-tricalcium phosphate scaffolds with defined porosity exceeding 90% threaten traditional allograft pricing in ridge augmentation procedures.
Strategic Opportunities
- Injectable delivery white space:Minimally invasive sinus lift procedures in the United States favor flowable bone graft substitutes over solid implant formats.
- Digital workflow convergence:Integration of regenerative case planning software with cone beam computed tomography systems creates bundled service revenue in German dental clinics.
- MFDS fast-track designation:South Korea's Ministry of Food and Drug Safety offers accelerated review pathways for novel biomaterials with controlled resorption rates matched to bone formation timelines.
Industry Challenges
- ISO 10993 biological evaluation expertise:Scarce toxicology specialists capable of executing cytotoxicity and sensitization studies for polymer substrates extend certification timelines.
- ASTM F2150 validation capex:Mechanical testing infrastructure for bone graft substitute specifications requires substantial capital investment in compression and degradation apparatus.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Regeneration Market |
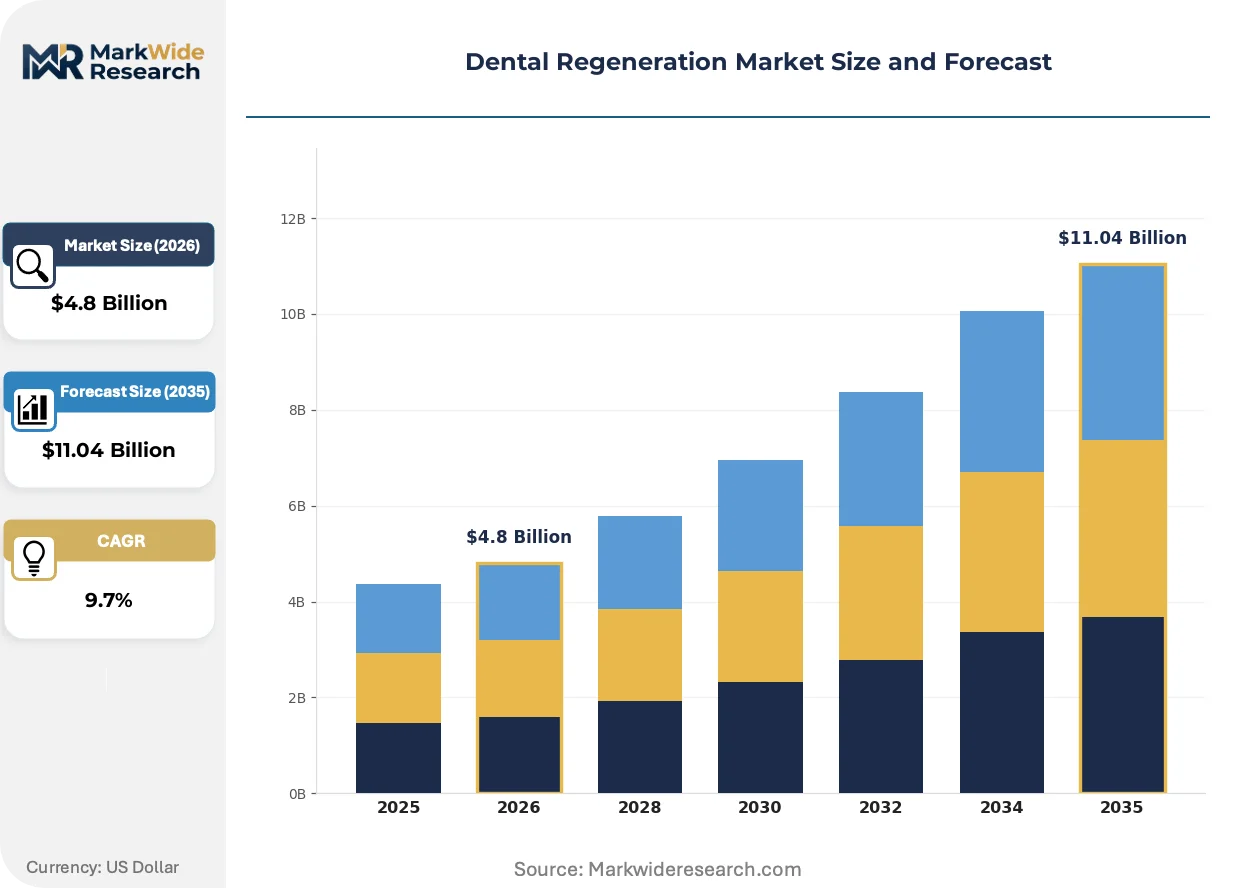
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Grafts, Membranes, Growth Factors, Scaffolds End User: Dental Clinics, Hospitals, Research Institutions, Orthodontic Offices Material: Biodegradable Polymers, Ceramics, Allografts, Xenografts Delivery Mode: Injectable Solutions, Solid Implants, Coatings, Sprays |
| Companies Covered | Dentsply Sirona, Institut Straumann AG, Geistlich Pharma AG, Zimmer Biomet Holdings, Inc., ZimVie Inc., Medtronic, BioHorizons Implant Systems, Inc., Integra LifeSciences Holdings Corporation, Henry Schein, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Regeneration Market Trends and Innovations
Digital technologies are virtualizing traditional regenerative workflows while regulatory frameworks tighten evidence requirements. These simultaneous pressures are forcing manufacturers to reconfigure product development pipelines and distribution strategies.
Three-dimensional printing of patient-specific scaffolds is virtualizing the production of alveolar bone matrices. Oral surgery departments in academic medical centers now commission custom porous structures with architecture matched to defect morphology. This capability is virtualizing the role of off-the-shelf grafts in complex ridge augmentation cases.
EMA Medical Device Regulation classification rules now mandate clinical performance data for collagen membranes entering European Union markets. Manufacturers must submit prospective studies demonstrating osteoconductive outcomes equivalent to predicate devices. Synthetic scaffold developers targeting Germany and France face the steepest compliance burdens.
Direct-to-clinic procurement platforms are displacing traditional specialist dental distributor networks in the United States. Hospital purchasing committees now negotiate bone graft substitute contracts through centralized supply chain systems. This channel compression is most visible in multi-site dental clinic chains across Texas and Florida.
Dental Regeneration Market Segmentation
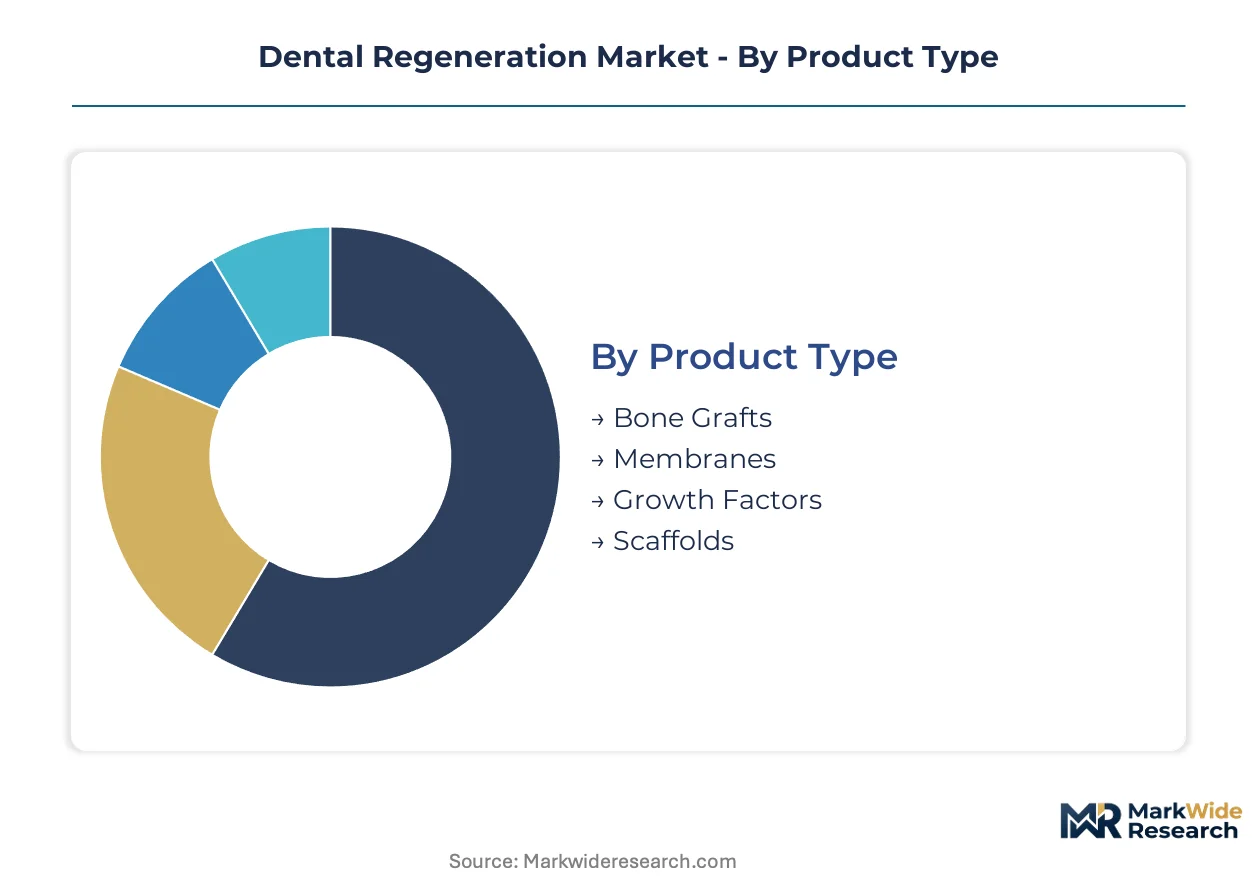
Segmentation in dental regeneration reveals distinct technical and commercial profiles across product architectures, clinical settings, and material platforms. Each dimension carries unique regulatory pathways, reimbursement codes, and supply chain configurations that shape manufacturer strategy and distributor economics.
Product Type:
After-sales service intensity varies sharply across product categories, with growth factor formulations demanding cold-chain logistics support and membrane products requiring sterile handling protocols that extend vendor relationships beyond the point of sale.
- Bone Grafts:Mineralized allograft and bovine xenograft formulations with osteoconductive matrices dominate socket preservation procedures in United States hospital-affiliated dental clinics where clinician training programs sustain repeat procurement. Aging implantology volume in Germany and South Korea drives steady consumption for ridge augmentation and sinus lift applications.
- Growth Factors:Recombinant human platelet-derived protein formulations command premium reimbursement in periodontal defect repair across South Korea's national health insurance system. MFDS fast-track designation accelerates commercialization timelines for novel synthesis methods, though cold-chain distribution requirements inflate service costs.
- Membranes:Collagen barrier products with defined resorption rates matched to bone formation timelines require sterile handling protocols and inventory management support.
- Scaffolds:Synthetic and biologic porous structures with architecture exceeding 90% porosity serve complex ridge augmentation cases.
By volume, bone grafts lead. By growth pace, growth factors are ahead.
End User:
Customer concentration patterns split between high-volume institutional purchasers and dispersed specialty practices, with procurement centralization reshaping vendor access in the largest accounts.
- Dental Clinics:Independent and multi-site practices in Texas and Florida increasingly adopt direct-to-clinic procurement platforms that bypass traditional distributor networks. Cone beam computed tomography integration with regenerative case planning software creates bundled technology decisions.
- Hospitals:Academic medical centers commission patient-specific three-dimensional printed scaffolds for complex alveolar bone reconstruction. Centralized purchasing committees negotiate bone graft substitute contracts through supply chain systems that compress vendor margins.
- Research Institutions:University oral surgery departments drive early adoption of novel biomaterials with controlled resorption rates.
- Orthodontic Offices:Limited regenerative procedure volume concentrates in accelerated tooth movement applications.
By procedure count, dental clinics dominate. By technology access, hospitals pull ahead.
Material:
Raw material sourcing geography and biocompatibility certification burden determine cost structures and regulatory timelines across substrate categories.
- Allografts:Human-derived mineralized matrices with established osteoconductive performance dominate United States socket preservation where tissue bank networks ensure supply security. FDA 510(k) predicate device pathways accelerate commercialization compared to novel synthetic alternatives.
- Xenografts:Bovine-derived collagen extraction protocols anchor Geistlich Pharma AG's competitive position in European guided bone regeneration. Supply concentration risk in European abattoir networks creates input volatility for manufacturers dependent on proprietary sourcing relationships.
- Ceramics:Beta-tricalcium phosphate scaffolds with defined porosity threaten traditional allograft pricing in ridge augmentation procedures.
- Biodegradable Polymers:Synthetic polymer substrates require ISO 10993 cytotoxicity and sensitization studies that extend certification timelines.
By revenue contribution, allografts lead. By substitution threat, ceramics are climbing fastest.
Delivery Mode:
Procedure invasiveness preferences and dimensional stability requirements drive format selection across clinical applications.
- Injectable Solutions:Flowable bone graft substitutes with controlled viscosity enable minimally invasive sinus lift procedures in United States outpatient settings. Surgeon demand for reduced morbidity drives fastest adoption in periodontal defect repair and small-volume socket preservation.
- Solid Implants:Prefabricated blocks and granules retain preference in ridge augmentation where mechanical stability determines outcomes. German dental clinics favor solid formats for vertical bone gain procedures requiring sustained architecture.
- Coatings:Surface-modified dental implants with osteoinductive layers extend regenerative intervention to prosthetic integration.
- Sprays:Aerosolized delivery systems serve topical applications with limited current penetration.
By current utilization, solid implants lead. By expansion trajectory, injectable solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS fast-track designation in South Korea and FDA 510(k) pathway clarity in the United States are accelerating commercialization timelines for novel biomaterials. EMA MDR classification rules in Germany and France are extending biocompatibility testing requirements. Aging populations across these markets are driving implantology volume and socket preservation demand.
United States
Hospital-affiliated dental clinics in Texas and Florida are consolidating procurement through direct-to-clinic platforms that bypass traditional distributor networks. FDA 510(k) premarket notification governs collagen membrane and synthetic scaffold approvals, compressing development timelines for predicate device pathways. The Greater Boston academic medical corridor is commissioning patient-specific three-dimensional printed scaffolds for complex alveolar bone reconstruction.
Germany
Geriatric population expansion is driving ridge augmentation and vertical bone gain procedures requiring mineralized allograft and bovine xenograft solutions. EMA Medical Device Regulation mandates extended clinical evidence submissions that delay collagen membrane launches by 18-24 months. The Baden-Württemberg industrial cluster anchors Geistlich Pharma AG's proprietary collagen extraction protocols for guided bone regeneration.
South Korea
National health insurance reimbursement for recombinant human platelet-derived growth factor formulations is commanding premium capture in periodontal defect repair. MFDS accelerated review pathways are attracting novel biomaterial developers with controlled resorption rate technologies. The Seoul Capital Area concentration of dental implantology centers is driving fastest adoption of injectable delivery solutions for minimally invasive sinus lift procedures.
Switzerland
Swissmedic medical device regulations enforce stringent biocompatibility standards for ceramic and polymer substrates entering the domestic market. Vertically integrated manufacturing footprints control premium implant-biomaterial bundles across European distribution networks. The Basel-Zurich corridor sustains specialist dental research institutions driving early adoption of novel scaffold architectures.
Japan
PMDA pharmaceutical and medical device agency oversight shapes clinical trial requirements for growth factor formulations and membrane products. METI industrial policy is supporting domestic production capacity for beta-tricalcium phosphate scaffolds threatening traditional allograft pricing. The Kanto/Tokyo metropolitan dental clinic density is generating concentrated demand for digital workflow integration with regenerative case planning software.
Dental Regeneration Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive biomaterial production and specialized extraction capabilities. Three strategic archetypes dominate: premium-tier implant-biomaterial bundlers, proprietary protocol specialists controlling collagen sourcing, and digital workflow integrators extending software into regenerative planning. Competitive moves concentrate on backward integration into raw material supply and technology licensing partnerships that accelerate regulatory clearance timelines.
Among Swiss-based manufacturers, Institut Straumann AG and Geistlich Pharma AG exemplify divergent archetypes within the premium segment. Straumann represents the vertically integrated bundler model with manufacturing footprint control across Europe. Geistlich occupies the proprietary protocol specialist position anchored by extraction technology. Dentsply Sirona, a US-domiciled Co., sits within the digital convergence tier extending workflow software into regenerative case planning. These three anchors illustrate how geography and capability configuration determine competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Institut Straumann AG |
| Geistlich Pharma AG |
| Zimmer Biomet Holdings, Inc. |
| ZimVie Inc. |
| Medtronic |
| BioHorizons Implant Systems, Inc. |
| Integra LifeSciences Holdings Corporation |
| Henry Schein, Inc. |
| Others |
Pricing and Supply Chain Analysis
European abattoir network concentration for bovine-derived collagen feeds directly into premium membrane pricing power at Geistlich Pharma AG and competing xenograft manufacturers. Margin pools concentrate downstream with clinicians in German hospital-affiliated dental clinics who command reimbursement premiums for guided bone regeneration procedures.
Pricing Analysis
Volume-discount tiering separates hospital purchasing committees negotiating multi-site contracts from independent dental clinics procuring through direct-to-clinic platforms. Pricing stratifies across premium recombinant growth factor formulations, standard mineralized allografts, and economy-grade synthetic ceramics. Cost compression in the ceramic segment is intensifying because beta-tricalcium phosphate manufacturers exploit defined porosity specifications to undercut allograft positioning. Hospital-affiliated clinics demonstrate lowest price sensitivity due to centralized procurement budgets, while independent Texas and Florida practices face acute margin pressure from distributor bypass.
Supply Chain Analysis
Contract-manufacturing capacity for collagen membrane finishing concentrates with Swiss and German medical device specialists serving Straumann and Geistlich production networks. Raw material sourcing draws from United States tissue bank networks for allografts, European abattoir chains for xenograft collagen, and Chinese ceramic precursor suppliers for beta-tricalcium phosphate scaffolds. Single-source vulnerability in proprietary collagen extraction protocols creates supply chain risk for manufacturers dependent on Baden-Württemberg industrial cluster relationships. Distribution runs through specialist dental distributor networks being displaced by direct-to-clinic procurement platforms in Texas, Florida, and the Seoul Capital Area.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where digital workflow convergence with cone beam computed tomography systems is rewiring purchase decisions around bundled software-biomaterial offerings rather than standalone graft products.
For Market Incumbents: Build regulatory data moats by accelerating FDA 510(k) predicate device filings ahead of EMA MDR clinical evidence burdens that will delay competitor launches. Prioritize backward integration into bovine collagen sourcing to defend against supply concentration risk in European abattoir networks. Synthetic ceramic substitution threatens traditional allograft pricing in ridge augmentation procedures. For New Entrants and Emerging Players: Pursue injectable delivery white space in United States outpatient settings where flowable bone graft substitutes enable minimally invasive sinus lift procedures with reduced morbidity. Target South Korea's MFDS fast-track pathway for novel biomaterials with controlled resorption rates matched to bone formation timelines. Go-to-market leverage rests on cold-chain logistics partnerships that incumbent growth factor suppliers have underinvested in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across three-dimensional printed scaffold manufacturing as academic medical centers commission patient-specific alveolar bone matrices. Acquisition targets should concentrate on digital workflow integrators with regenerative case planning software assets. Signal to monitor: MFDS accelerated review pathway expansion attracting novel biomaterial developers away from FDA and EMA jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Device Pathway | Streamlined premarket notification accelerates commercialization timelines for synthetic scaffold developers targeting United States hospital-affiliated dental clinics. |
| Proprietary Collagen Extraction Investment | Captive supply of bovine-derived matrices defends Geistlich Pharma AG's positioning in European guided bone regeneration against synthetic substitution. |
| Digital Workflow Integration | Cone beam computed tomography convergence with regenerative case planning software creates bundled technology decisions in German dental clinics. |
| MFDS Fast-Track Designation Pursuit | South Korea's accelerated review pathway attracts novel biomaterial developers with controlled resorption rate technologies away from EMA MDR burdens. |
| Direct-to-Clinic Platform Buildout | Procurement centralization in Texas and Florida multi-site chains compresses traditional specialist dental distributor margins and vendor access. |
Research Methodology
The analysis maps bone graft substitutes, growth factor formulations, collagen membranes, and synthetic scaffolds, each validated through oral surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, MFDS approval records, and hospital procurement contracts supported bottom-up and top-down triangulation across the analysis window.
Assumptions held regulatory pathway clarity fixed in the United States and South Korea while varying EMA MDR compliance timelines across Germany and France. Segmentation dimensions modeled include product architecture, clinical setting, material substrate, and delivery mode. CAGRs were derived from procedure volume trajectories in aging implantology populations and reimbursement coding evolution. Forecast inputs incorporated ISO 10993 biological evaluation completion rates and ASTM F2150 mechanical testing infrastructure deployment.
Sensitivities concentrate around EMA MDR clinical evidence requirement changes, bovine-derived material sourcing disruptions, and synthetic ceramic porosity specification advances. Forecasts reflect assumptions about regulatory pathway stability and reimbursement coverage expansion. Quarterly review of MFDS fast-track designation utilization rates, FDA 510(k) clearance velocity, and hospital procurement platform adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Europe Dental Aligners Market
Dental Devices
Europe Dental Implants Market
Dental Devices
Global Dental Labs Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Dental Units Market
Dental Devices
Teeth Whitening Pen Market
Dental Devices
Dental Needle Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Dental Aligners Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Dental Scalers Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Implants Market