
 Wound Irrigation Devices Market | 2026-2036
Wound Irrigation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Irrigation Devices Market Outlook
Saline-based formulations is shifting toward polymer-enhanced surfactant solutions that reduce biofilm adherence in chronic wounds. Stryker Corporation leverages its orthopedic surgical ecosystem to bundle irrigation systems with power tools. Zimmer Biomet anchors its position through dedicated wound care portfolios targeting post-operative infection prevention. BD competes on disposable kit scale, supplying integrated delivery formats to health system GPOs.
Wound irrigation devices mechanically debride and cleanse wound beds using pressurized fluid streams, typically operating at 4-15 psi to dislodge contaminants without damaging granulation tissue. Powered irrigation systems command premium placement in operating rooms due to controlled pressure delivery and integrated suction, while disposable irrigation kits dominate ambulatory settings where turnover efficiency matters. Chronic wound management applications are deepening as diabetic foot ulcer protocols expand in outpatient clinics, though surgical wound care retains the largest volume footprint.
FDA 510(k) clearances and EPA sterility assurance standards govern device classification and antimicrobial claim validation, while ISO 13485 quality management certifications shape supplier eligibility for institutional contracts. The EU MDR transition is lengthening conformity assessment timelines for manufacturers exporting to European markets. Stakeholders must monitor reimbursement code consolidation for outpatient wound care procedures and assess sterile solution sourcing resilience against supply chain volatility.
Market Dynamics
Powered irrigation systems are displacing manual syringe methods in operating rooms as surgical volumes rebound and pressure-controlled delivery becomes non-negotiable for infection prevention protocols. This technology shift is compressing margins for disposable kit manufacturers while creating premium placement opportunities for integrated suction-irrigation platforms.
Growth Catalysts
- Reimbursement code consolidation:United States CMS bundling rules for outpatient wound care procedures are incentivizing ambulatory surgical centers to standardize on disposable irrigation kits for turnover efficiency.
- Diabetic foot ulcer protocol expansion:Outpatient clinics in Germany and Japan are adopting pressurized irrigation for chronic wound debridement as first-line mechanical cleansing.
- Polymer-enhanced surfactant solutions:Antimicrobial formulations with biofilm-disruption properties are penetrating post-operative infection prevention pathways previously dominated by saline.
Market Restraints
- Supply concentration in sterile solution sourcing:Sodium chloride and purified water supply chains cluster in coastal United States manufacturing corridors, exposing distributors to weather-related disruption.
- EU MDR conformity assessment timelines:European notified body capacity constraints are extending clearance durations for Class IIa irrigation devices by twelve to eighteen months.
- Technical limitation in pressure precision:Manual bulb syringes lack consistent psi delivery, limiting their utility in surgical settings where tissue trauma thresholds are critical.
Strategic Opportunities
- Underpenetrated home care segment:Post-acute patients in the United States with surgical site infections present untapped demand for portable low-pressure irrigation devices with simplified user interfaces.
- Technology convergence:Integration of negative pressure wound therapy with automated irrigation cycles is creating hybrid device categories for chronic wound management.
- Direct-to-hospital distribution:Manufacturers are bypassing traditional distributor networks to contract directly with United States health system GPOs for kit standardization.
Industry Challenges
- ISO 13485 certification backlog:Quality management system audits for new market entrants face scheduling delays at accredited bodies, slowing supplier eligibility for institutional contracts.
- Integration complexity with legacy suction systems:Powered irrigation platforms require electrical and vacuum line compatibility with existing operating room infrastructure, complicating retrofit decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Irrigation Devices Market |
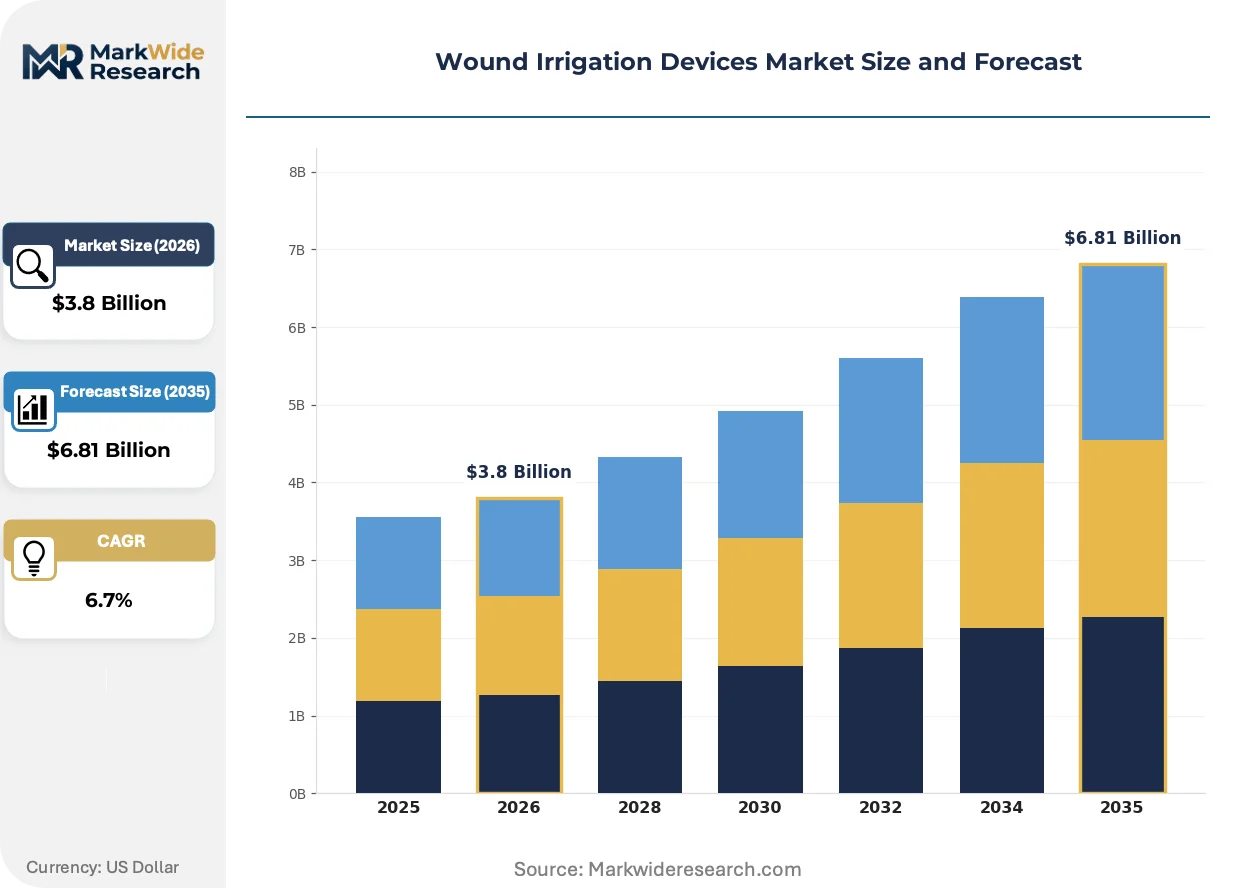
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Irrigation Devices, Powered Irrigation Systems, Disposable Irrigation Kits, Handheld Sprayers End User: Hospitals, Clinics, Homecare Settings, Surgical Centers Application: Trauma Treatment, Surgical Wound Care, Chronic Wound Management, Post-operative Care Delivery Mode: Direct Use, Sterile Solutions, Non-sterile Solutions, Automated Dispensing |
| Companies Covered | Zimmer Biomet, Stryker Corporation, BD, Smith & Nephew, Irrimax Corporation, Centurion Medical Products, C. R. Bard, CooperSurgical, Molnlycke Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Irrigation Devices Market Strategic Shifts
Fluid delivery mechanisms are converging with digital pressure monitoring and antimicrobial formulation chemistry, reshaping how wound beds are prepared across acute and chronic care settings.
Battery-powered handheld irrigation devices with integrated real-time pressure sensors are absorbing market share from pneumatic console systems in ambulatory surgery centers. These units reduce capital expenditure requirements while maintaining 4-15 psi precision for safe tissue interaction. The shift is compressing revenue per procedure for manufacturers but expanding total addressable procedure volume through point-of-care deployment.
EPA sterility assurance standards for antimicrobial claim validation are tightening documentation requirements for solution manufacturers seeking 510(k) clearance in the United States. The agency now demands quantitative biofilm reduction data rather than qualitative efficacy statements. Solution suppliers are responding by restructuring regulatory affairs teams and extending clinical study timelines.
Health system procurement committees are consolidating vendor lists around integrated delivery formats that bundle sterile solutions with single-use applicators. United States hospital networks with centralized supply chain operations are displacing fragmented purchasing across individual departments. This concentration is visible most acutely in multi-hospital systems in Texas and Florida where standardization mandates have reduced approved irrigation SKUs by forty percent.
Wound Irrigation Devices Market Segmentation
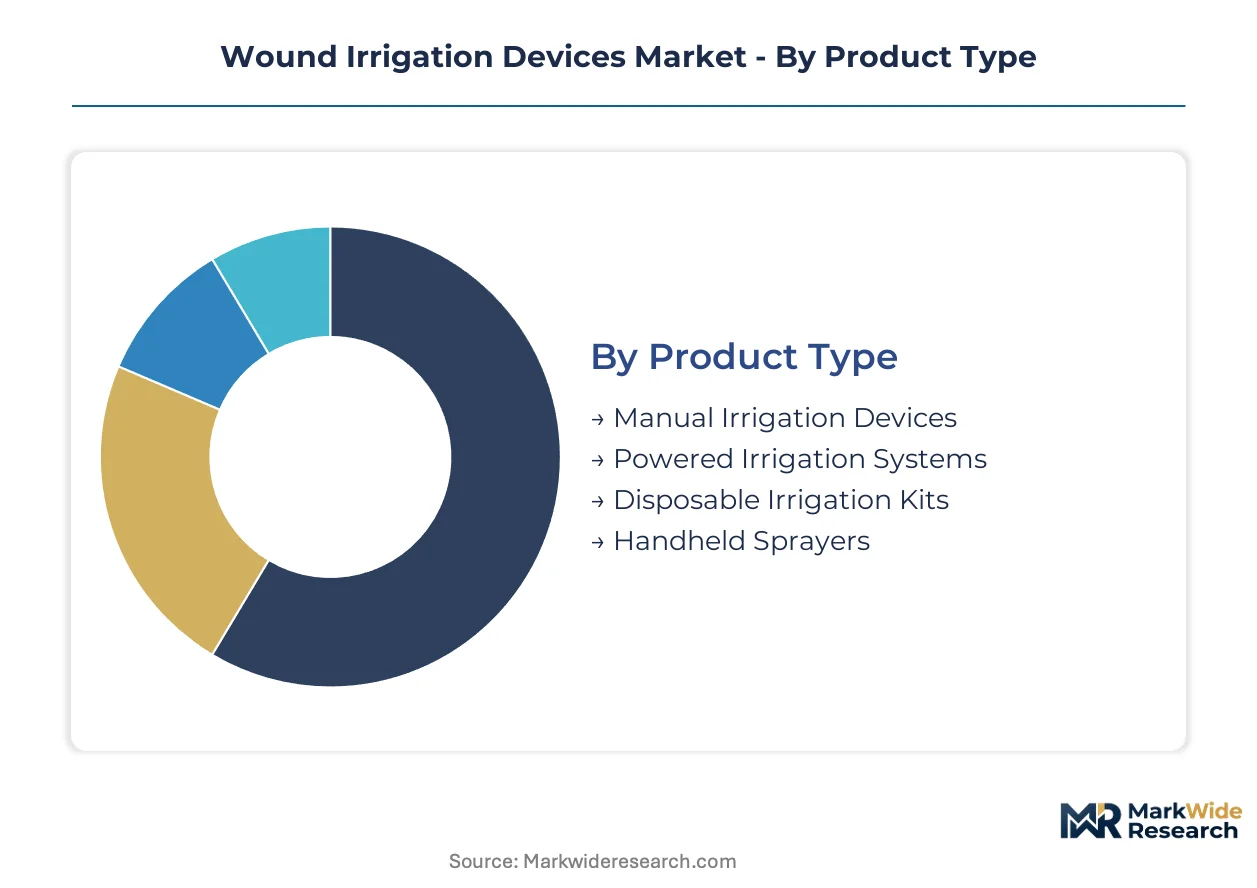
Segmentation in wound irrigation devices tracks how pressure delivery mechanisms, sterile solution formats, and care settings reshape procurement patterns. Manufacturers configure product portfolios around the tension between capital-intensive powered systems and high-turnover disposable formats.
Product Type:
Pressure control specifications distinguish clinical utility across mechanical and electromechanical delivery platforms.
- Powered Irrigation Systems:Electromechanical consoles deliver calibrated 4-15 psi streams with integrated suction capability. Hospital operating rooms in the United States concentrate demand as surgical infection prevention protocols mandate pressure precision.
- Disposable Irrigation Kits:Single-use syringe and bag assemblies bundle sterile saline with delivery hardware. Ambulatory surgical centers in Texas and Florida health systems drive volume through standardized SKU consolidation.
- Manual Irrigation Devices:Bulb syringes and piston systems offer low-cost mechanical delivery without pressure monitoring.
- Handheld Sprayers:Portable trigger-operated units target pre-hospital and field trauma applications.
Powered Irrigation Systems lead on scale; Disposable Irrigation Kits lead on momentum.
End User:
Procurement authority and reimbursement pathways segment demand across institutional and post-acute channels.
- Hospitals:Centralized supply chain committees negotiate multi-year contracts for powered systems and bulk solution purchases. United States health system GPOs in California and New York dominate contract value.
- Surgical Centers:Freestanding ASCs prioritize disposable kit standardization to minimize turnover time between procedures. CMS bundling rules for outpatient wound care accelerate kit consumption.
- Clinics:Outpatient wound care facilities manage diabetic foot ulcer protocols with mid-pressure handheld units.
- Homecare Settings:Post-acute patients with surgical site infections present emerging demand for simplified low-pressure devices.
Hospitals capture the largest contract value; Homecare Settings present the steepest expansion trajectory.
Application:
Wound etiology determines pressure requirements, solution chemistry, and frequency of intervention.
- Surgical Wound Care:Operating room protocols demand biofilm-disrupting surfactant solutions with documented sterility assurance. FDA 510(k) clearance requirements shape solution manufacturer compliance investments.
- Chronic Wound Management:Diabetic foot ulcer and pressure injury protocols in German and Japanese outpatient clinics adopt pressurized irrigation as first-line mechanical debridement.
- Trauma Treatment:Emergency departments require rapid contamination removal without granulation tissue damage.
- Post-operative Care:Surgical site infection prevention drives scheduled irrigation cycles in hospital step-down units.
Surgical Wound Care dominates procedure volume; Chronic Wound Management is climbing the fastest.
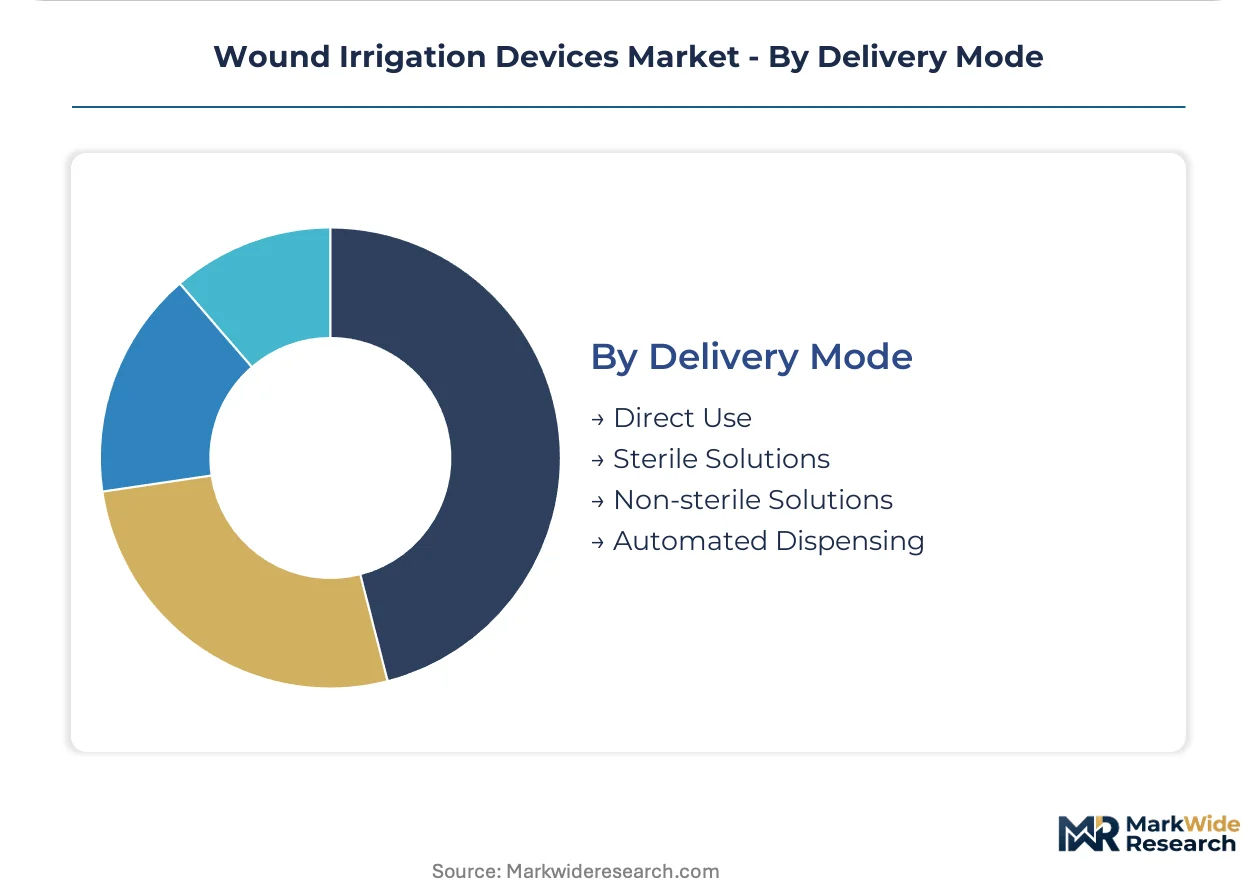
Delivery Mode:
Sterility assurance and automation level define regulatory classification and reimbursement eligibility.
- Sterile Solutions:Pre-packaged sodium chloride and surfactant formulations meet EPA sterility validation standards for antimicrobial claims. Coastal United States manufacturing corridors concentrate supply.
- Automated Dispensing:Programmable volume and pressure cycles integrate with negative pressure wound therapy platforms for hybrid chronic wound protocols.
- Direct Use:Immediate application without intermediate storage or mixing steps.
- Non-sterile Solutions:Irrigation fluids for mechanical cleansing without antimicrobial claim requirements.
Sterile Solutions anchor institutional procurement; Automated Dispensing gains share fastest through technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal United States manufacturing corridors anchor sterile solution production for wound irrigation devices. Health system consolidation in Texas and Florida drives kit standardization mandates. German and Japanese outpatient clinics are expanding pressurized irrigation protocols for diabetic foot ulcer management.
United States
Hospital procurement committees in California and New York negotiate multi-year contracts for powered irrigation systems through health system GPOs. FDA 510(k) pathway updates streamline Class II medical device clearance timelines for manufacturers. Texas and Florida health systems have reduced approved irrigation SKUs by forty percent through centralized supply chain mandates.
Germany
Outpatient wound care facilities adopt pressurized irrigation as first-line mechanical debridement for diabetic foot ulcer protocols. EU MDR transition extends conformity assessment timelines for Class IIa irrigation devices by twelve to eighteen months. The Baden-Württemberg medical technology cluster houses notified bodies managing quality system certifications for institutional supplier eligibility.
Japan
Chronic wound management applications deepen as diabetic foot ulcer protocols expand in outpatient clinics across Kanto and Kansai regions. METI guidelines influence reimbursement structures for post-operative infection prevention devices. Osaka-based distributors concentrate procurement authority for ambulatory surgical center kit consumption in western prefectures.
United Kingdom
NHS supply chain consolidation favors disposable irrigation kit standardization for turnover efficiency in surgical settings. MHRA alignment with EU MDR requirements shapes post-Brexit device registration pathways for manufacturers. The Greater London health system procurement hub negotiates integrated delivery format contracts covering sterile solutions with single-use applicators.
India
Post-acute home care demand emerges for portable low-pressure irrigation devices with simplified user interfaces in metropolitan centers. CDSCO medical device regulations classify powered irrigation systems under notified category standards requiring import licensing. The Maharashtra pharmaceutical corridor expands sterile solution manufacturing capacity for domestic wound care product supply.
Wound Irrigation Devices Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers bundle irrigation systems with adjacent surgical technologies. The vendor base concentrates around orthopedic surgical ecosystems, dedicated wound care portfolios, and disposable kit scale operations. Three archetypes define positioning: integrated platform providers, chronic wound specialists, and high-volume disposable suppliers. M&A activity and direct-to-hospital distribution contracts represent the primary competitive vectors reshaping market access.
Within the integrated platform tier, Stryker Corporation and Zimmer Biomet exemplify archetypes leveraging surgical ecosystem adjacencies. Stryker occupies a position bundling powered irrigation with power tool portfolios, while Zimmer Biomet anchors through dedicated wound care portfolios targeting infection prevention. BD represents the scale-driven disposable format archetype, supplying integrated delivery kits to health system GPOs. These three entities collectively illustrate how competitive positioning stratifies across technology integration, clinical specialization, and procurement efficiency vectors.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker Corporation |
| BD |
| Smith & Nephew |
| Irrimax Corporation |
| Centurion Medical Products |
| C. R. Bard |
| CooperSurgical |
| Molnlycke Health Care |
| Others |
Value Chain & Pricing Dynamics
Health system GPO concentration in the United States dictates contract-based procurement structures where multi-year bundled agreements lock in volume commitments for powered irrigation systems and disposable kits. This buyer consolidation shifts pricing power toward institutional purchasers capable of standardizing SKUs across multi-hospital networks.
Pricing Analysis
Input-cost pass-through from sodium chloride and polymer-enhanced surfactant formulations shapes margin structures for solution manufacturers. Pricing stratifies across premium integrated suction-irrigation platforms, standard powered consoles, and economy disposable syringe kits. Cost compression in manual bulb syringe segments intensifies as battery-powered handheld units absorb ambulatory market share. Surgical centers exhibit highest price sensitivity due to capital expenditure constraints, while hospital operating rooms prioritize pressure precision over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from United States health system procurement committees mandate qualified backup suppliers for sterile sodium chloride solutions and single-use applicator components. Manufacturing concentrates in coastal United States corridors for purified water processing, Germany's Baden-Württemberg cluster for electromechanical console assembly, and China's polymer component fabrication. Supply chain risk centers on weather-related disruption to coastal sterile solution production facilities. Distribution runs through health system GPO contracts with direct-to-hospital logistics bypassing traditional medical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wound irrigation devices function as a stable compounder anchored by surgical volume recovery and infection prevention protocol standardization across acute care settings. Reimbursement code consolidation and ambulatory surgical center expansion provide durable demand tailwinds.
For Market Incumbents: Anchor market position through backward integration into sterile solution manufacturing to capture margin from polymer-enhanced surfactant formulations. Deepen hospital system GPO relationships with multi-year bundled contracts that displace fragmented departmental purchasing. Prioritize ISO 13485 certification maintenance to defend supplier eligibility against audit backlogs affecting new entrants.
For New Entrants and Emerging Players: The price-point gap between premium powered consoles and economy manual syringes creates entry space for mid-tier battery-powered handheld units with integrated pressure sensors. Target underpenetrated home care settings in United States metropolitan centers where post-acute surgical site infection management lacks portable device options. Pursue direct-to-hospital distribution partnerships with regional health systems outside consolidated Texas and Florida networks.
For Investors and Strategic Acquirers: Orthopedic surgical device manufacturers are the most active acquirer in this space, seeking irrigation system capabilities to complement power tool portfolios. Five-to-ten year viability rests on chronic wound protocol expansion and technology convergence with negative pressure wound therapy platforms. Watch FDA 510(k) clearance timelines for Class II devices as an inflection indicator for manufacturer revenue recognition acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Texas and Florida GPO standardization mandates reduce approved irrigation SKUs by forty percent. |
| FDA 510(k) Submission | Streamlined Class II pathway accelerates clearance timelines for powered irrigation console manufacturers. |
| CE Marking Pathway | EU MDR transition extends conformity assessment timelines for German and United Kingdom market access. |
| Software Companion Development | Real-time pressure monitoring integration differentiates battery-powered handheld units in ambulatory settings. |
| Reimbursement Strategy | CMS bundling rules for outpatient wound care procedures accelerate disposable kit consumption in surgical centers. |
Study Parameters
Multiple input streams — hospital procurement database analysis, GPO contract documentation, regulatory filing review, and clinician workflow observation — were reconciled to construct demand estimates. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and outpatient wound care clinicians informed operational assumptions. Secondary validation drew from FDA 510(k) clearance databases, EPA sterility assurance standards documentation, CMS reimbursement code filings, and ISO 13485 certification records. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis were triangulated to anchor market sizing.
Historical shipment data cross-referenced against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include pressure delivery mechanism, sterile solution format, end-user procurement channel, and wound etiology application. CAGRs were derived from procedure volume trajectories and average selling price evolution patterns. Forecast inputs incorporated surgical volume rebound rates, ambulatory surgical center expansion pipelines, and diabetic foot ulcer protocol adoption curves in German and Japanese outpatient settings.
Caveats apply where EU MDR notified body capacity constraints, supply chain disruption to coastal sterile solution manufacturing, or reimbursement code restructuring could materially shift the outlook. Deviation in health system GPO consolidation pace or FDA clearance timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Burn Care Centers Market
Wound Care
Alginate Dressing Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Italy Wound Care Market
Wound Care
Pressure Bandages Market
Wound Care
South Korea Wound Care Market
Wound Care
Wound Debridement Products Market
Wound Care
Liquid Bandages Market
Wound Care
Venous Ulcer Treatment Market
Wound Care
Asia Pacific Wound Care Market
Wound Care
Global Active Wound Care Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Wound Care Biologics Market
Wound Care
Next Generation Wound Closure Device Market