
 Wound Biologics Market | 2026-2036
Wound Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Biologics Market Outlook
Hospital procurement is rebalancing toward outpatient wound centers as site-of-care migration accelerates. Smith & Nephew leverages its orthopedics heritage to dominate advanced wound matrix distribution in integrated delivery networks. Integra LifeSciences anchors regenerative tissue portfolios through sustained R&D intensity in skin substitute platforms. Organogenesis specializes in living cell therapies that compete on clinical outcomes in chronic wound protocols.
Wound biologics comprise active therapeutic products derived from human, animal, or recombinant biological sources, formulated as matrices, grafts, or topical agents that modulate healing cascades through cytokine signaling and extracellular matrix deposition. These products serve to restore dermal architecture in wounds that have stalled in the inflammatory phase. Skin substitutes command premium positioning due to manufacturing complexity and living cell content, while collagen dressings occupy mature, volume-driven segments with established reimbursement. Growth factors represent the fastest-expanding category as recombinant protein engineering reduces immunogenicity risks and extends formulary access across ambulatory settings.
FDA biologics license requirements and CMS national coverage determinations shape product development timelines and commercial launch sequencing in the United States. The EU Medical Device Regulation and EMA advanced therapy medicinal product classifications create parallel compliance burdens for manufacturers seeking transatlantic market presence. Stakeholders must monitor evolving real-world evidence mandates that increasingly determine payer access for premium biologic interventions.
Market Dynamics
CMS reimbursement migration toward bundled payments for diabetic foot ulcers is compressing site-of-care economics and forcing hospital systems to consolidate wound center procurement under centralized value-based contracts.
Growth Catalysts
- Medicare Advantage coverage expansion:Private Medicare plans in the United States now routinely authorize advanced biologic dressings for chronic wounds, expanding patient access beyond traditional fee-for-service limits.
- Recombinant protein engineering:Advances in bacterial and mammalian expression systems yield growth factors with reduced immunogenic profiles, accelerating formulary inclusion across ambulatory surgery centers.
- Outpatient wound center proliferation:Hospital systems are decanting chronic wound volume from inpatient beds to dedicated outpatient facilities, creating concentrated demand nodes for high-touch biologic therapies.
Market Restraints
- Allogeneic tissue supply volatility:Skin substitute manufacturing depends on screened donor tissue networks concentrated in the United States, exposing production to procurement interruptions.
- FDA biologics license complexity:Living cell therapies require multi-phase clinical validation and facility inspections that extend development timelines beyond synthetic alternatives.
- Collagen price compression:Mature bovine and porcine collagen dressings face commoditization pressure from hydrocolloid and foam substitutes in cost-sensitive segments.
Strategic Opportunities
- Underpenetrated home health integration:Skilled nursing facilities and home health agencies remain underserved channels for advanced biologic application, requiring simplified delivery logistics.
- EU MDR harmonization window:Manufacturers achieving CE marking under the Medical Device Regulation gain preferential access to centralized procurement frameworks in Germany and France.
- 3D bioprinting convergence:Integration of patient-derived cells with printable scaffold architectures enables personalized wound matrices for complex burn and trauma cases.
Industry Challenges
- Specialized wound care nursing shortage:Application of living cell therapies requires trained clinicians capable of sterile handling and staging assessment, constraining throughput at high-volume centers.
- Cold chain infrastructure capex:Temperature-controlled distribution for viable biologics demands capital investment in validated packaging and logistics partnerships that smaller manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Biologics Market |
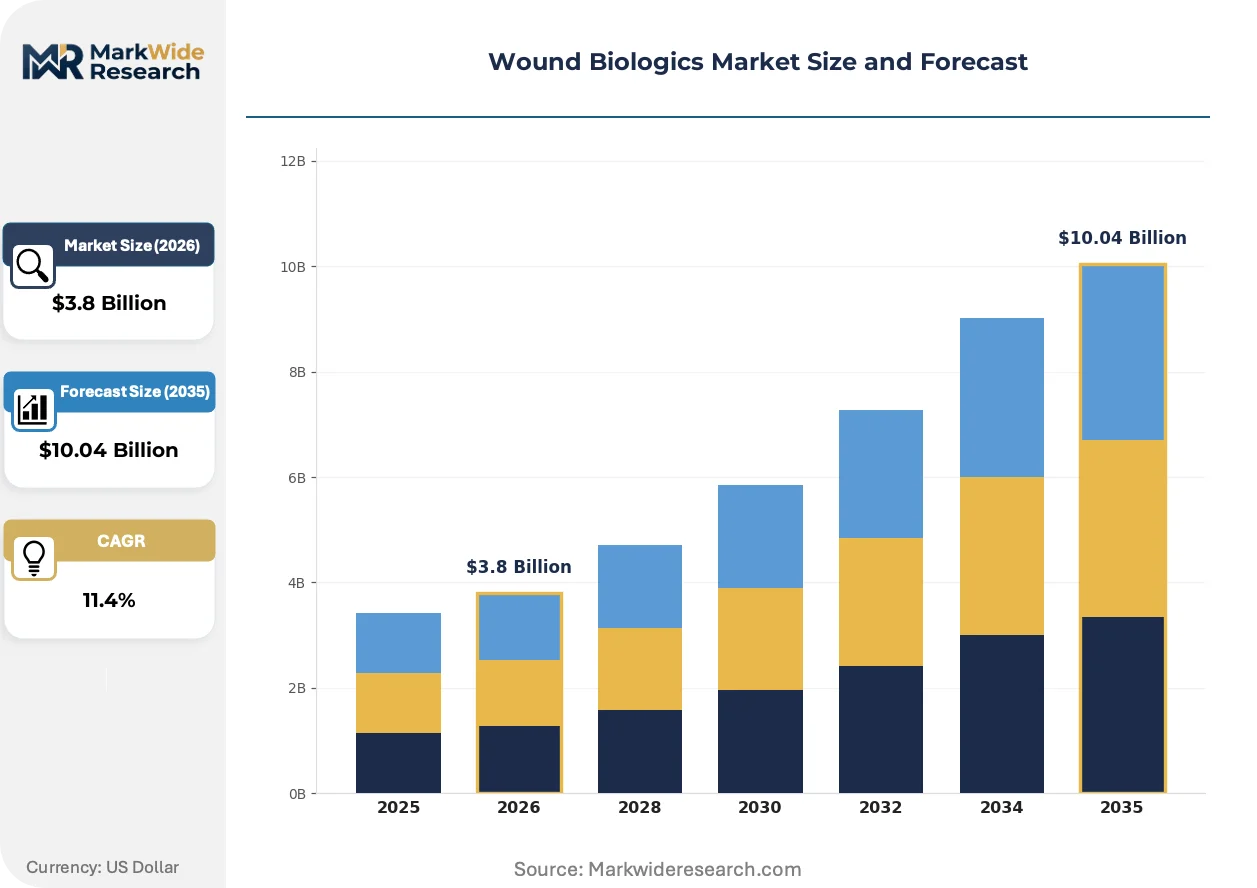
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Factors, Skin Substitutes, Collagen Dressings, Antimicrobial Agents Application: Chronic Wounds, Surgical Wounds, Acute Wounds, Burns End User: Hospitals, Ambulatory Surgical Centers, Home Healthcare, Community Clinics Technology: Regenerative Medicine, Biologics, Tissue Engineering, Stem Cell Therapy |
| Companies Covered | Smith & Nephew, Integra LifeSciences, MIMEDX Group, Organogenesis, ConvaTec, Mölnlycke Health Care, Kerecis, Stryker, Skye Biologics Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Biologics Market Strategic Shifts
Manufacturing and regulatory architectures are converging to enable scalable production of patient-matched biologic therapies while reimbursement frameworks compress toward episode-based accountability.
Gene-edited allogeneic cell lines are unifying donor variability reduction with manufacturing scale, enabling consistent cytokine profiles across production batches. Large academic medical centers are piloting these platforms for recalcitrant venous leg ulcers. The technology is unifying research-grade consistency with commercial viability, compressing the gap between autologous precision and allogeneic accessibility.
EU Medical Device Regulation recertification deadlines are forcing portfolio rationalization among skin substitute manufacturers seeking European market presence. Products lacking sufficient clinical evidence under the new classification rules face withdrawal or downclassification to lower-reimbursement categories. German hospital procurement associations are responding by consolidating preferred supplier lists around MDR-compliant portfolios.
Hospital purchasing cooperatives are consolidating wound biologic sourcing through single-source agreements that bundle advanced matrices with service-level guarantees on inventory availability. Integrated delivery networks in the United States are displacing fragmented distributor relationships with direct manufacturer contracts. This concentration is most visible in the Southeast, where regional health systems have formed dedicated wound care purchasing alliances.
Wound Biologics Market Segmentation
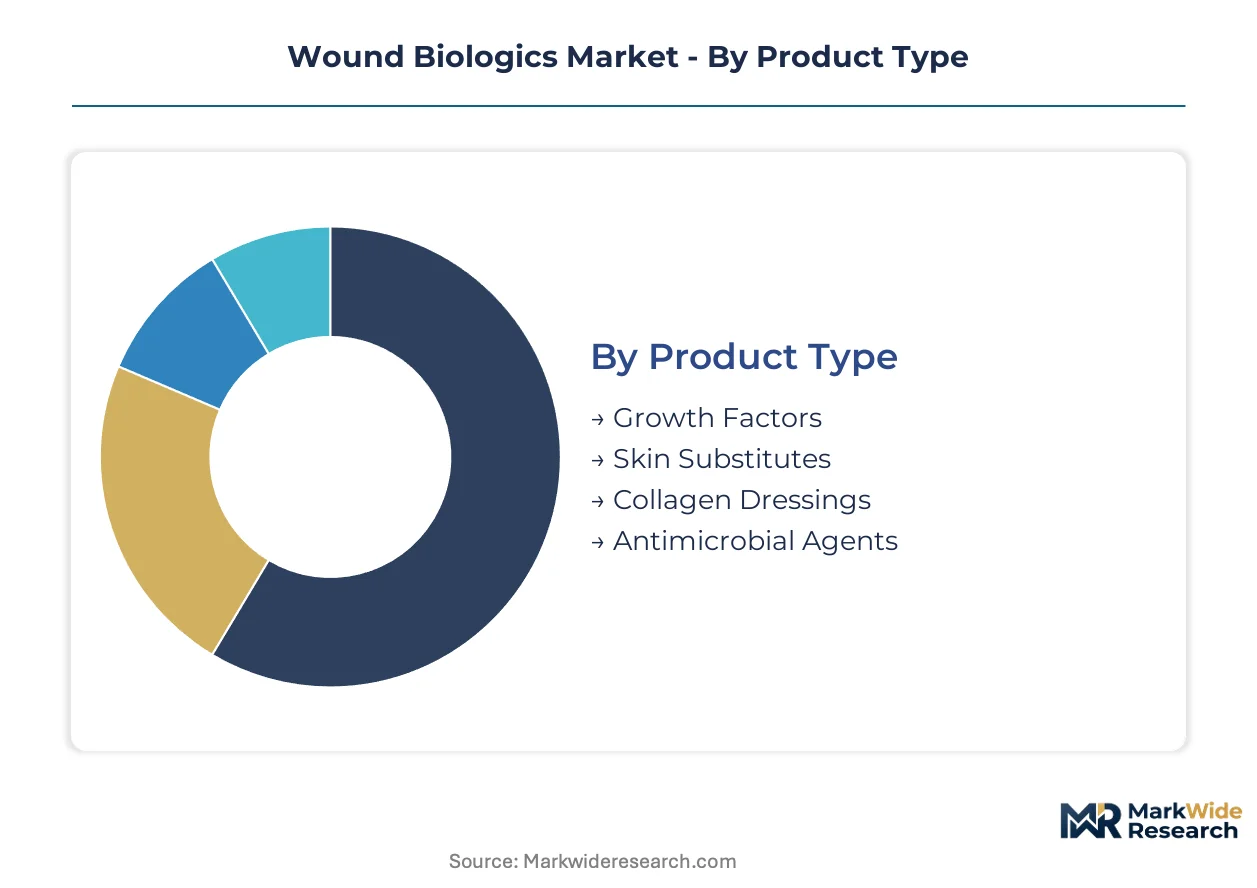
Wound biologics segmentation reveals divergent margin structures across product categories, with living cell therapies commanding premium pricing while commodity dressings compete on volume throughput. Hospital procurement teams segment suppliers by clinical outcome guarantees and cold-chain reliability rather than unit cost alone.
Product Type:
Reimbursement tier determines procurement priority, with Medicare Advantage plans creating distinct coverage bands for advanced versus standard biologic interventions.
- Skin Substitutes:Living cell matrices derived from human dermal fibroblasts and keratinocytes require cryopreserved distribution networks. Demand concentrates in hospital-based outpatient wound centers across Texas and Florida, where diabetic foot ulcer prevalence drives prior authorization volume.
- Growth Factors:Recombinant proteins engineered through bacterial expression systems deliver platelet-derived and epidermal signaling molecules with reduced immunogenicity. Ambulatory surgery centers in the Northeast are expanding formulary access for these agents as manufacturing scale reduces per-dose costs.
- Collagen Dressings:Bovine and porcine extracellular matrix scaffolds serve cost-sensitive wound bed preparation in skilled nursing facilities.
- Antimicrobial Agents:Silver-impregnated and iodine-based biologics target infected wound protocols in community clinic settings.
Skin substitutes lead on scale; growth factors lead on momentum.
Application:
Clinical endpoint requirements vary sharply by wound etiology, with chronic protocols demanding sustained biologic intervention versus acute cases favoring single-application matrices.
- Chronic Wounds:Venous leg ulcers and pressure injuries that stall in the inflammatory phase require repeated application of cytokine-modulating therapies. Hospital systems in California are consolidating chronic wound protocols under value-based bundled payment arrangements with CMS.
- Surgical Wounds:Post-operative incisions and dehisced closures utilize antimicrobial biologics to prevent biofilm formation. Academic medical centers in Massachusetts prioritize surgical wound matrices with demonstrated reduction in readmission rates.
- Burns:Partial-thickness thermal injuries employ temporary dermal substitutes for eschar management.
- Acute Wounds:Traumatic lacerations and abrasions drive volume demand for collagen-based primary dressings in emergency departments.
Chronic wounds dominate revenue concentration; burns show steepest expansion trajectory as regenerative protocols advance.
End User:
Site-of-care migration is redistributing biologic consumption from inpatient beds toward outpatient facilities with specialized wound nursing capability.
- Hospitals:Inpatient wound services concentrate complex cases requiring operating room debridement and staged graft application. Integrated delivery networks in the Southeast are centralizing biologic procurement through dedicated wound center alliances.
- Ambulatory Surgical Centers:Freestanding facilities perform incisional wound management and minor debridement with same-day discharge protocols. Medicare Advantage penetration in Arizona and Nevada is expanding prior authorization for ASC-based biologic application.
- Home Healthcare:Skilled nursing visits for wound dressing changes remain underpenetrated for advanced biologics due to cold-chain limitations.
- Community Clinics:Federally qualified health centers serve as access points for uninsured populations needing standard collagen dressings.
Hospitals retain volume leadership; ambulatory surgical centers gain share fastest as site-of-care economics shift.
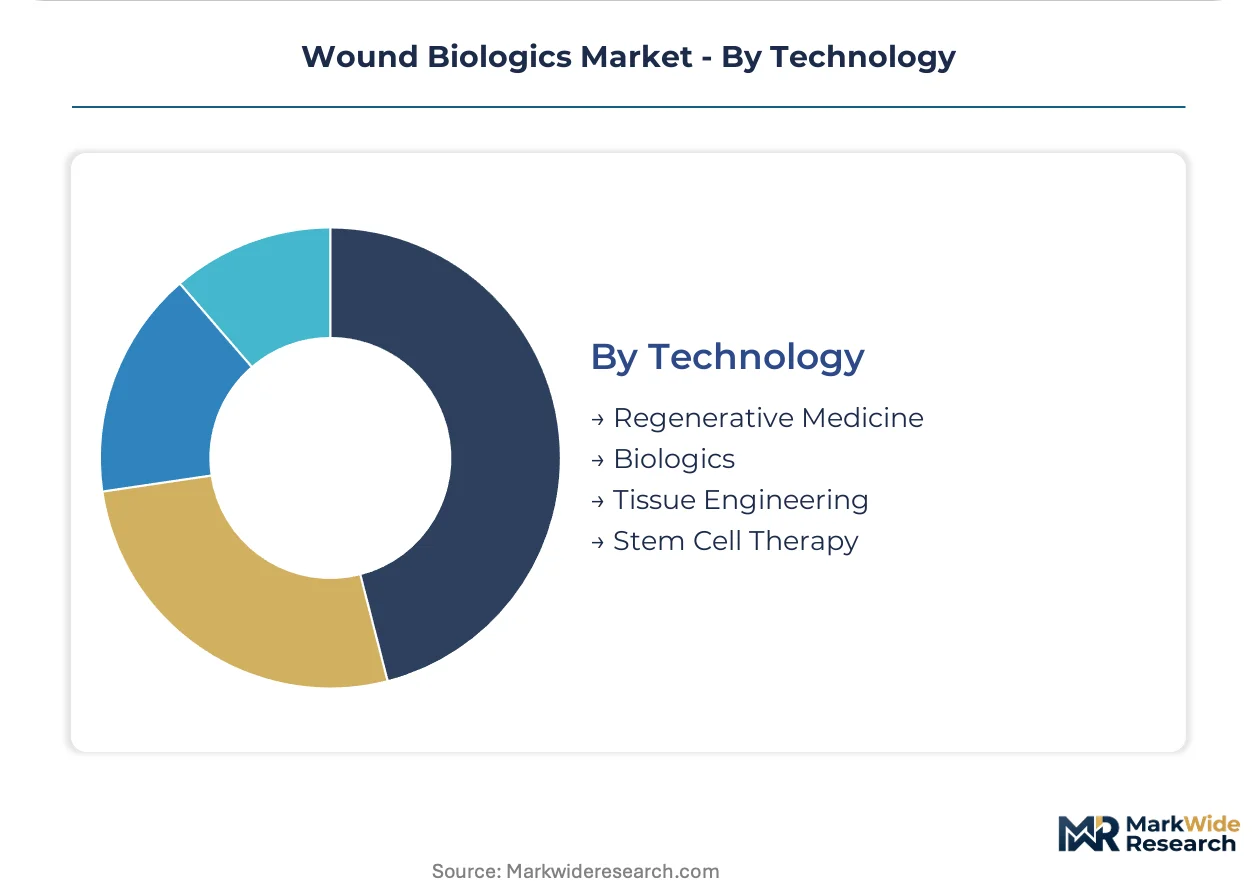
Technology:
Regulatory pathway complexity separates scalable manufacturing platforms from artisanal production methods, with FDA biologics license requirements filtering market entry.
- Regenerative Medicine:Tissue-engineered products combining scaffold architectures with living cells require GMP facility validation and lot-release testing. Manufacturers with approved BLAs are securing preferred supplier status with group purchasing organizations.
- Biologics:Naturally derived matrices from human or animal sources face donor screening and pathogen inactivation protocols that extend production cycles.
- Tissue Engineering:Synthetic-biologic hybrid scaffolds enable off-the-shelf availability without cold-chain constraints.
- Stem Cell Therapy:Mesenchymal stromal cell products remain investigational for most wound indications, with academic centers conducting phase trials under FDA IND protocols.
Regenerative medicine commands premium positioning; tissue engineering offers the most accessible expansion pathway for mid-tier manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers navigate divergent regulatory compliance costs across jurisdictions, with FDA biologics license pathways in the United States commanding premium R&D investment while EU MDR harmonization creates temporary market access windows for prepared entrants.
United States
Medicare Advantage plans in Florida and Texas drive prior authorization volume for diabetic foot ulcer interventions. FDA biologics license requirements and CMS national coverage determinations filter market entry timelines. Hospital-based outpatient wound centers in Houston and Miami concentrate demand for cryopreserved skin substitutes.
Germany
Hospital procurement associations consolidate preferred supplier lists around MDR-compliant regenerative portfolios. EU Medical Device Regulation recertification deadlines force portfolio rationalization among skin substitute manufacturers. The Rhine-Ruhr metropolitan region anchors centralized purchasing frameworks for advanced wound matrices.
United Kingdom
NHS England value-based procurement frameworks compress reimbursement toward episode-based accountability for chronic wound protocols. MHRA post-Brexit regulatory autonomy creates parallel compliance pathways distinct from EU MDR. London and Manchester academic medical centers pilot gene-edited allogeneic cell lines for venous leg ulcers.
Japan
PMDA regenerative medicine product designations accelerate conditional approval pathways for tissue-engineered therapies. METI industrial policy supports domestic biomanufacturing scale-up for export competitiveness. The Kansai region around Osaka hosts concentrated GMP facility validation for scaffold-based products.
Australia
TGA priority review pathways for breakthrough wound biologics attract sponsor applications from Asia-Pacific headquarters operations. Public hospital formulary committees in New South Wales and Victoria evaluate real-world evidence packages for premium biologic inclusion. Sydney anchors regional distribution infrastructure for temperature-controlled logistics.
Wound Biologics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated wound care companies commanding premium positioning in hospital procurement while mid-tier manufacturers compete on volume throughput in cost-sensitive channels. The vendor base concentrates around three strategic archetypes: orthopedics-heritage conglomerates with distribution depth, pure-play regenerative medicine specialists with R&D intensity, and diversified medical technology portfolios with service-level bundling. Consolidation through direct manufacturer contracts displaces fragmented distributor relationships, while cold-chain infrastructure investments filter participation in viable biologics segments.
Within the pure-play regenerative tier, Organogenesis and MIMEDX Group exemplify living cell therapy specialists competing on clinical outcome differentiation, while Smith & Nephew anchors the orthopedics-heritage archetype through integrated delivery network penetration. These three occupy positions that reflect divergent strategic bets: cell-based manufacturing scale versus matrix distribution infrastructure versus hospital system consolidation.
| Leading Market Players |
|---|
| Smith & Nephew |
| Integra LifeSciences |
| MIMEDX Group |
| Organogenesis |
| ConvaTec |
| Mölnlycke Health Care |
| Kerecis |
| Stryker |
| Skye Biologics Holdings |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up wound care specialists have consolidated procurement leverage across hospital systems, compressing distributor margins while concentrating pricing power among manufacturers with validated cold-chain infrastructure. This ownership pattern feeds into supply behavior that favors long-term service contracts over transactional spot purchasing, embedding pricing discipline through guaranteed volume commitments.
Pricing Analysis
Distributor margin compression runs through the wound biologics channel as hospital purchasing cooperatives consolidate around direct manufacturer contracts. Three-tier pricing structure across premium, standard, and economy levels separates cryopreserved living cell matrices from bovine collagen dressings and synthetic foam alternatives. Pricing pressure stems from Medicare Advantage prior authorization requirements that demand clinical outcome documentation for premium tiers. Skilled nursing facilities exhibit highest price sensitivity due to fixed per-diem reimbursement, while academic medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Domestic-content mandates in the United States and EU MDR localization requirements are reshaping sourcing patterns for allogeneic tissue networks. Manufacturing draws from screened donor tissue concentrated in the United States, recombinant protein production anchored in Ireland and Singapore, and bovine collagen processing in New Zealand and Brazil. Raw material dependencies include cryopreserved human dermal fibroblasts, recombinant growth factor expression systems, and pathogen-inactivated extracellular matrix scaffolds. Single-source vulnerability in viable cell distribution networks poses structural risk. Distribution runs through temperature-validated logistics partnerships with regional GMP facility hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wound biologics represent a late-cycle quality story as Medicare Advantage coverage expansion tilts demand toward premium skin substitutes with demonstrated clinical outcomes. This shift rewards manufacturers with validated BLA pathways and cold-chain reliability over commodity competitors.
For Market Incumbents: Deploy backward integration into allogeneic tissue procurement networks to secure supply continuity against donor screening bottlenecks. Consolidate hospital system relationships through service-level guarantees on inventory availability, countering emerging entrants with simplified logistics. Capacity addition in Texas and Florida wound center corridors reinforces geographic density. For New Entrants and Emerging Players: Telehealth-integrated wound assessment platforms offer a digital-channel route to bypass entrenched distributor relationships. Home health agencies remain the most penetrable segment due to cold-chain simplification opportunities. Target Medicare Advantage plan formulary inclusion through real-world evidence partnerships with regional health systems. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier collagen dressing manufacturers facing commoditization pressure. Long-term viability favors platforms with regenerative medicine pipelines and GMP facility validation. The signal to watch is CMS national coverage determination expansion for gene-edited allogeneic cell therapies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Biologics License Pathway | BLA approval unlocks Medicare coverage and hospital formulary inclusion for living cell therapies. |
| CE Marking Under EU MDR | MDR compliance secures preferred supplier status with German hospital procurement associations. |
| Hospital System Partnership | Direct contracts with integrated delivery networks displace fragmented distributor relationships. |
| Cold Chain Infrastructure Investment | Validated temperature-controlled logistics enable viable biologic distribution to outpatient centers. |
| Reimbursement Strategy | Medicare Advantage prior authorization expertise expands patient access beyond fee-for-service limits. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, wound center clinical directors, GPO contracts specialists, and regulatory affairs leads with secondary validation. Sources included FDA biologics license filings, CMS national coverage determinations, hospital procurement databases, and EU MDR submission records. Bottom-up product-level estimates triangulated against top-down market sizing across the analysis window.
Historical reference periods anchored the forecast framework to observed adoption curves for prior biologic categories. Modeled dimensions spanned product type, wound etiology, site-of-care migration patterns, and technology regulatory pathway. CAGRs derived from segment-level growth rate reconciliation with macro healthcare expenditure trends. Forecast inputs incorporated Medicare Advantage penetration trajectories and EU MDR recertification timelines.
The model assumes a particular technology adoption path; alternative pathways for 3D bioprinted patient-matched matrices would alter the outlook if manufacturing scale achieves cost parity with allogeneic substitutes. Forecasts reflect assumptions on reimbursement stability and donor tissue supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Negative Pressure Wound Therapy Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Wound Evacuators Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Dental Wound Dressings Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Wound Healing Nutrition Market
Wound Care
Wound Measurement Devices Market
Wound Care
Global Antimicrobial Dressings Market
Wound Care
Australia Wound Care Management Devices Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Global Wound Irrigation System Market
Wound Care
Maggot Debridement Market
Wound Care
Europe Wound Care Market
Wound Care
Alginate Dressing Market