
 Collagen Dressings Market | 2026-2036
Collagen Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Collagen Dressings Market Analysis
ISO 13485 certification is reorganizing competitive access in the collagen dressings landscape, raising barriers for new entrants lacking established quality management systems. Smith & Nephew leverages its wound care heritage to sustain premium positioning across advanced dressing portfolios. Integra LifeSciences anchors its presence through regenerative tissue expertise that extends into collagen-based wound management. Coloplast Corp competes through specialized continence and wound care channels that control direct hospital access in European markets.
Collagen dressings comprise matrices derived from bovine, porcine, or avian sources, processed into gels, sheets, or particles that provide a scaffold for cellular migration and granulation tissue formation while maintaining a moist wound environment conducive to autolytic debridement. Hospitals dominate end-user demand as the site of complex surgical wound and pressure ulcer management, while home care segments are gaining traction as reimbursement shifts favor outpatient chronic wound protocols. Hydrocolloid and alginate formulations lead product type revenue pools, though sheet collagen variants command higher margins in burn treatment applications where conformability and hemostasis are critical.
FDA 510(k) pathways and the EU Medical Device Regulation shape product development timelines, with MDR transition deadlines forcing manufacturers to resubmit technical documentation for legacy collagen devices. The EPA and USDA jointly influence source material traceability for bovine-derived collagen, constraining supply chain flexibility. Stakeholders must monitor evolving biodegradability standards and reimbursement coding changes for advanced wound care to anticipate which formulation investments will yield sustainable returns.
Market Dynamics
EU Medical Device Regulation transition deadlines are forcing manufacturers to resubmit technical documentation for legacy collagen devices, compressing margins while ISO 13485 certification requirements raise competitive barriers for new market entrants.
Growth Catalysts
- Chronic wound prevalence:Hospital settings in the United States are accelerating uptake of advanced collagen matrices for diabetic foot ulcer management as aging demographics expand the addressable patient base.
- FDA 510(k) pathways:Streamlined clearance mechanisms for Class II medical devices are reducing time-to-market for novel collagen gel and sheet formulations.
- Avian source diversification:Processing innovations in avian-derived collagen are broadening raw material options beyond traditional bovine and porcine supply chains.
Market Restraints
- Bovine collagen traceability:EPA and USDA joint oversight of source material documentation constrains supply chain flexibility and extends qualification timelines for new suppliers.
- Alginate substitution:Hydrocolloid and alginate wound dressings compete directly with collagen in moist wound healing applications, pressuring price positioning in standard care segments.
- MDR compliance costs:European legacy device resubmission requirements are diverting R&D investment toward regulatory affairs rather than formulation innovation.
Strategic Opportunities
- Home care channel expansion:Reimbursement shifts favoring outpatient chronic wound protocols in Germany are creating direct-to-patient distribution potential for sheet collagen variants.
- Burn treatment specialization:Conformable collagen matrices with hemostatic properties command premium positioning in specialized burn centers across the United States.
- Biodegradability standards:Evolving environmental compliance frameworks in the European Union are opening differentiation pathways for manufacturers with certified sustainable sourcing.
Industry Challenges
- ISO 13485 implementation:Quality management system certification requires 12-18 month investment cycles that strain mid-tier manufacturer cash flows.
- Granulation tissue optimization:Formulation science talent scarcity in cellular scaffold engineering limits product development velocity for next-generation matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collagen Dressings Market |
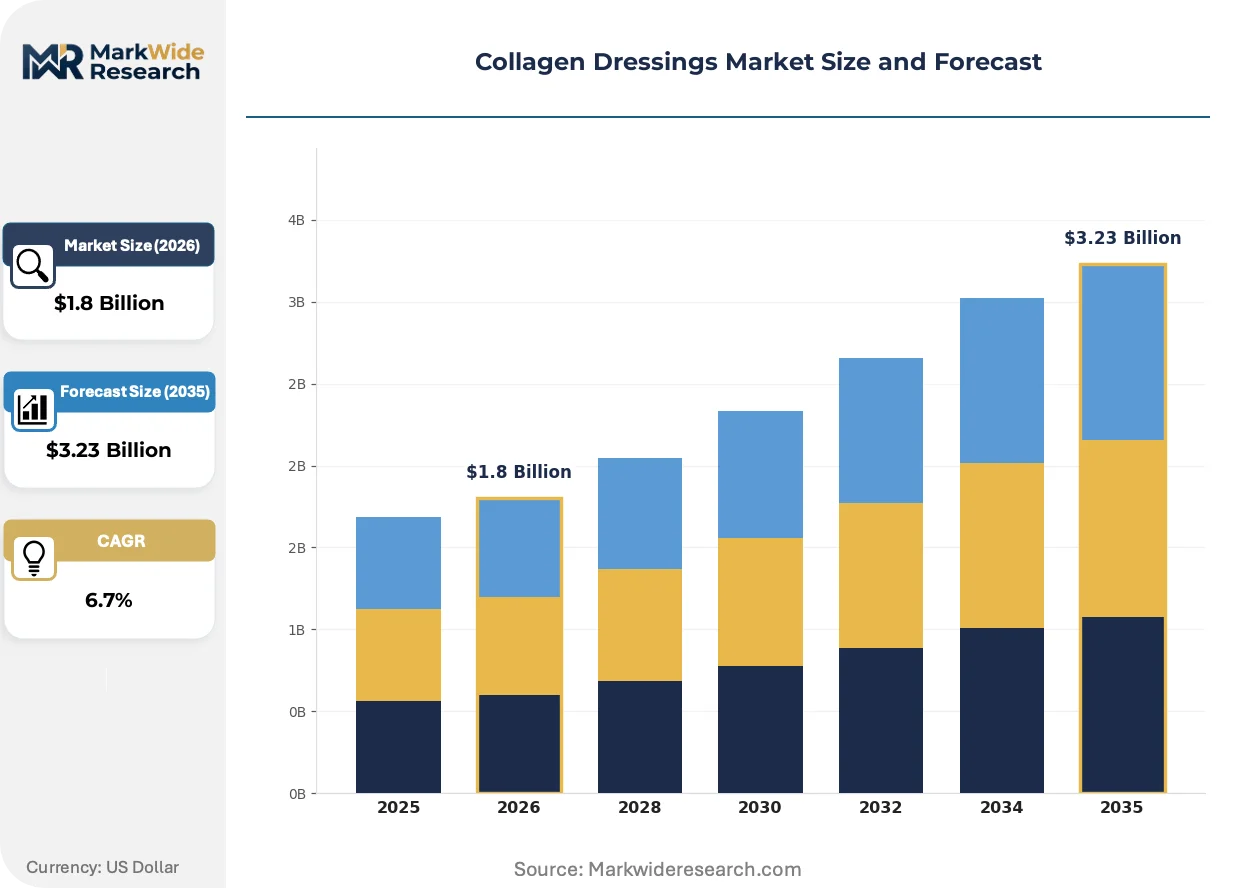
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid, Foam, Alginate, Sheet Application: Dermal Ulcers, Surgical Wounds, Burn Treatment, Chronic Wounds End User: Hospitals, Home Care, Clinics, Long-term Care Facilities Formulation: Gel, Paste, Powder, Liquid |
| Companies Covered | 3M, Smith & Nephew, Coloplast Corp, Integra LifeSciences, McKesson Corporation, Paul Hartmann, Lohmann & Rauscher, DermaRite Industries, Convatec Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collagen Dressings Market Emerging Trajectories
Collagen dressing technology is fragmenting across performance tiers as manufacturers balance advanced regenerative capabilities against cost-competitive standard care positioning. Regulatory complexity and procurement evolution are simultaneously reshaping competitive access.
Antimicrobial collagen matrices incorporating silver or iodine are bifurcating the premium segment from standard collagen offerings. Burn centers and surgical wards in the United States are adopting these enhanced formulations at accelerated rates. The technology is bifurcating contract structures, with antimicrobial variants capturing separate reimbursement codes that standard collagen cannot access.
EU Medical Device Regulation Article 120 transition timelines are forcing legacy collagen device manufacturers to rebuild technical documentation from foundational clinical data. European notified body capacity constraints are extending review periods beyond original projections. Sheet and particle collagen categories face the steepest resubmission burdens due to higher-risk classifications under MDR Annex VIII rules.
Hospital procurement consolidation is compressing vendor lists to suppliers with full advanced wound care portfolios rather than single-product collagen specialists. Integrated delivery networks in the United States are negotiating system-wide contracts that bundle collagen with negative pressure wound therapy and skin substitutes. Germany exhibits the most pronounced consolidation, with university hospital alliances standardizing on three to four primary dressing suppliers.
Collagen Dressings Market Segmentation
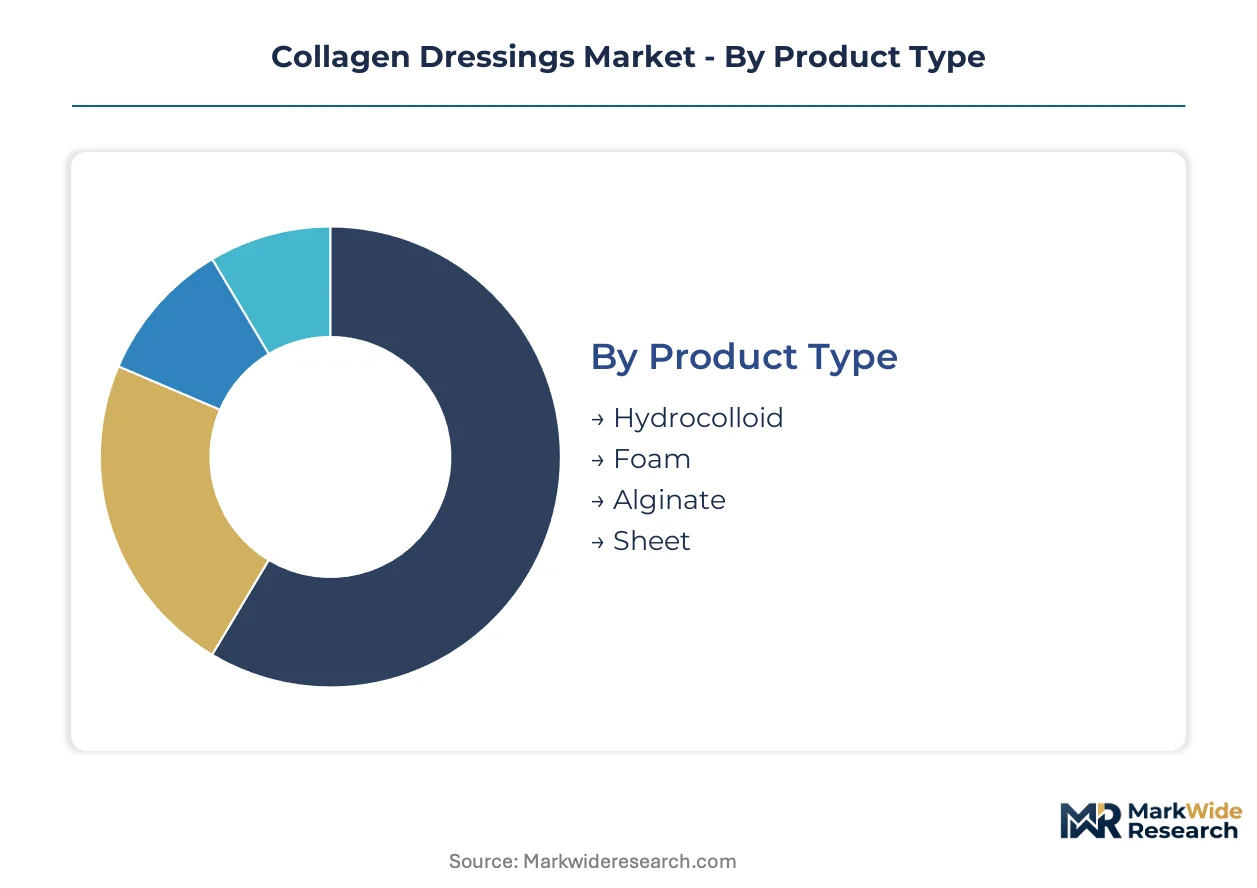
Collagen dressing manufacturers must align product portfolios across four distinct taxonomies to capture reimbursement codes and procurement contracts. Each segmentation axis carries different margin profiles, regulatory burdens, and channel access requirements that determine competitive positioning.
Product Type:
Hydrocolloid and alginate variants dominate domestic hospital procurement in the United States, while sheet collagen exports concentrate toward specialized burn centers in Germany and Switzerland.
- Hydrocolloid:Carboxymethylcellulose-based matrices absorb exudate while maintaining moist wound interfaces. Demand clusters in United States long-term care facilities managing pressure ulcers, where Medicare reimbursement favors cost-effective moist wound healing protocols over advanced regenerative options.
- Sheet:Freeze-dried collagen membranes provide conformable scaffolds for cellular migration in partial-thickness burns. German university hospital alliances source these through centralized tenders that bundle hemostatic dressings with negative pressure wound therapy systems.
- Foam:Polyurethane-backed collagen composites manage moderate-to-heavy exudate in surgical wound applications.
- Alginate:Seaweed-derived calcium alginate fibers blended with collagen address infected wounds requiring absorbency.
Sheet collagen holds the largest share; momentum sits with hydrocolloid variants as home care reimbursement expands.
Application:
Chronic wound protocols drive volume at standard care price points, while burn treatment commands premium positioning through specialized procurement channels.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers in United States Medicare populations consume collagen matrices for granulation tissue induction. Hospital outpatient departments are shifting these cases to ambulatory settings under bundled payment models that favor lower-cost dressing changes.
- Burn Treatment:Partial-thickness thermal injuries require conformable collagen sheets with hemostatic properties. United States burn centers in Texas, Georgia, and Massachusetts maintain separate formularies for these high-acuity applications, insulating them from standard wound care procurement consolidation.
- Surgical Wounds:Post-operative incision management in German inpatient settings.
- Dermal Ulcers:Pressure injury protocols in United States nursing facilities.
Burn treatment captures the highest margins; chronic wounds are climbing the fastest as diabetic prevalence rises.
End User:
Hospital procurement consolidation favors suppliers with full advanced wound care portfolios, while home care channels fragment toward specialized distributors.
- Hospitals:Integrated delivery networks in the United States negotiate system-wide contracts bundling collagen with skin substitutes and negative pressure therapy. Three to four primary suppliers now control university hospital alliance formularies in Germany.
- Home Care:Outpatient chronic wound protocols in Germany are creating direct-to-patient distribution potential for gel and paste collagen variants. Reimbursement shifts favor home-based dressing changes that reduce hospital readmission penalties.
- Clinics:Outpatient wound centers in United States metropolitan areas.
- Long-term Care Facilities:Pressure ulcer prevention programs in United States skilled nursing facilities.
Hospitals retain the dominant share; home care is gaining share fastest as outpatient protocols expand.
Formulation:
Gel formulations align with ambulatory care cost structures, while powder variants serve specialized surgical applications requiring precise scaffold density control.
- Gel:Hydrated collagen matrices enable easy application in irregular wound beds without secondary dressing requirements. United States home health agencies favor these for diabetic foot ulcer protocols where patient self-application reduces nursing visit frequency.
- Powder:Lyophilized collagen particles allow surgeons to customize scaffold density for deep cavity wounds. German orthopedic and trauma centers utilize these in compound fracture management where controlled biodegradation rates match bone healing timelines.
- Paste:Pre-mixed collagen suspensions for tunneling wounds.
- Liquid:Sprayable collagen formulations for large surface area coverage.
Gel formulations hold the largest share; powder variants show the steepest expansion trajectory as surgical applications diversify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European distribution efficiency for temperature-sensitive collagen matrices. German hospital procurement networks leverage this gateway for just-in-time delivery of advanced wound care materials.
United States
Diabetic foot ulcer prevalence in Medicare populations drives hospital uptake of collagen matrices. FDA 510(k) pathways compress clearance timelines for novel gel formulations. Texas burn centers in Houston and Dallas maintain specialized formularies for hemostatic collagen sheets.
Germany
University hospital alliances standardize procurement across three to four primary dressing suppliers. EU Medical Device Regulation resubmission deadlines force legacy device manufacturers to rebuild technical documentation. Bavarian medical device clusters around Munich face extended notified body review periods.
Switzerland
Swissmedic oversight maintains stringent quality benchmarks for bovine-derived collagen imports. Precision manufacturing heritage supports premium positioning of sheet collagen variants. Basel's pharmaceutical-industrial corridor hosts specialized wound care research facilities.
United Kingdom
NHS procurement consolidation favors suppliers with full advanced wound care portfolios. MHRA post-Brexit regulatory autonomy creates parallel compliance tracks for collagen device registrations. London integrated care systems negotiate bundled contracts spanning acute and community settings.
Japan
PMDA marketing authorization requirements extend lead times for novel collagen formulations. Aging demographics expand chronic wound patient pools in metropolitan Tokyo and Osaka. Kansai region medical device manufacturers specialize in conformable matrices for pressure ulcer protocols.
Collagen Dressings Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and channel access dimensions. Market structure concentrates around established wound care conglomerates with ISO 13485 quality systems and hospital procurement relationships. Three archetypes dominate: diversified medical device majors leveraging portfolio breadth, regenerative medicine specialists with tissue engineering heritage, and regional champions controlling European pharmacy channels. Competitive moves center on M&A for geographic expansion and strategic partnerships for raw material security.
Within the diversified medical device tier, 3M and Smith & Nephew exemplify scale-driven positioning across multiple wound care categories. Coloplast Corp and Integra LifeSciences occupy specialist positions anchored in continence care and regenerative tissue expertise respectively. Convatec Group PLC represents the listed leader archetype with integrated advanced wound care portfolios. McKesson Corporation anchors distribution-centric positioning through pharmaceutical supply chain dominance.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| Coloplast Corp |
| Integra LifeSciences |
| McKesson Corporation |
| Paul Hartmann |
| Lohmann & Rauscher |
| DermaRite Industries |
| Convatec Group PLC |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates both supplier qualification timelines and price tier differentiation in collagen dressings, compressing margins for uncertified entrants while enabling certified manufacturers to command sustained premiums across hospital procurement contracts. Bovine source traceability requirements under EPA and USDA joint oversight further stratify supply costs, with compliant suppliers capturing volume commitments from integrated delivery networks that penalize documentation gaps.
Pricing Analysis
Volume-discount tiering structures dominate hospital system contracts in the United States, with three-tier pricing separating antimicrobial-enhanced collagen from standard matrices and economy hydrocolloid alternatives. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification status, with uncertified manufacturers facing cost compression in standard care segments. Alginate substitution pressure runs through economy tiers as hospital procurement consolidates vendor lists. Medicare outpatient departments exhibit highest price sensitivity, while specialized burn centers demonstrate lowest sensitivity due to hemostatic performance requirements.
Supply Chain Analysis
Inventory lead times for avian-derived collagen matrices have compressed as processing innovations diversify beyond traditional bovine supply chains concentrated in the United States, Brazil, and Australia. Raw material dependencies center on bovine tendon, porcine dermis, and avian sternum cartilage feedstocks. Single-source vulnerability persists in European notified body capacity for MDR technical documentation review. Distribution runs through pharmaceutical wholesalers and hospital GPO contracts in the United States, with direct-to-hospital logistics dominating German university hospital alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collagen dressings market represents high-growth disruption as antimicrobial matrix formulations bifurcate reimbursement codes and reshape procurement formularies. EU Medical Device Regulation transition deadlines constitute the critical regulatory inflection compressing legacy manufacturer margins while opening acquisition opportunities.
For Market Incumbents: Compound portfolio breadth advantages by integrating negative pressure wound therapy bundling with collagen sheet offerings to defend against alginate substitution threats. Pursue backward integration into avian collagen processing to secure raw material qualification timelines that ISO 13485 certification demands. Hospital procurement consolidation favors suppliers with full advanced wound care portfolios rather than single-product specialists.
For New Entrants and Emerging Players: Home care channel service gaps in German outpatient chronic wound protocols offer penetrable entry points where reimbursement shifts favor direct-to-patient distribution. Target gel formulation segments for diabetic foot ulcer self-application protocols, leveraging lower certification barriers compared to sheet collagen MDR classifications. Partner with specialized wound care distributors bypassing consolidated hospital vendor lists.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MDR compliance and notified body resubmission activities, favoring scaled manufacturers with existing quality infrastructure. Mid-tier European collagen specialists facing documentation rebuild costs represent viable acquisition targets over a five-to-ten year viability window. Monitor notified body capacity expansion announcements as inflection indicators for regulatory bottleneck resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Resubmission | European notified body engagement secures legacy device market access under Annex VIII classification rules. |
| Antimicrobial Matrix Formulation Launch | Silver or iodine incorporation unlocks separate reimbursement codes inaccessible to standard collagen. |
| Avian Source Supply Agreement | Processing partnerships diversify raw material beyond EPA-USDA regulated bovine traceability constraints. |
| Hospital System Partnership | Integrated delivery network contracts bundle collagen with negative pressure wound therapy and skin substitutes. |
| Home Care Distribution Expansion | Direct-to-patient channels in Germany capture outpatient chronic wound protocol reimbursement shifts. |
Methodological Framework
Operator-level perspectives from hospital purchasing committee members, GPO contracts managers, biomedical engineers, and regulatory affairs specialists anchored the qualitative base for this study. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across product type, application, end user, and formulation dimensions.
Sensitivity analysis framed the quantitative approach across the projection horizon, with segmentation modeling spanning chronic wound versus burn treatment applications, hospital versus home care end users, and gel versus sheet versus powder formulations. CAGRs derived from installed base erosion rates, procedure volume growth, and pricing trajectory assumptions. Forecast inputs incorporated diabetic foot ulcer prevalence trends and antimicrobial formulation adoption curves specific to burn center procurement patterns.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR transition timelines; material policy shifts in notified body capacity or reimbursement coding would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Wound Cleanser Products Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Europe Compression Bandages Market
Wound Care
Venous Ulcer Treatment Market
Wound Care
Global Traditional Wound Management Market
Wound Care
Vascular Dressings Market
Wound Care
Wound Care Centers Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Wound Care Biologics Market
Wound Care
Wound Irrigation Devices Market
Wound Care
US Burn Care Centers Market
Wound Care
Global Wound Dressings Market
Wound Care
LAMEA Surgical Dressing Market