
 Heart Beat Monitor and Sensor Market | 2026-2036
Heart Beat Monitor and Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Beat Monitor and Sensor Market Foresight
Photoplethysmography integration with multi-wavelength LED arrays is reconfiguring the cost-performance frontier for consumer-grade heart rate sensing. Apple Inc. leverages its silicon design capabilities to embed custom optical engines directly into watch casings, tightening hardware-software coupling. Medtronic anchors the clinical tier with implantable loop recorders that stream encrypted rhythm data through cellular gateways. Samsung Electronics competes across both consumer and regulated clinical segments with Galaxy Watch platforms that carry FDA-cleared atrial fibrillation detection.
Heart beat monitors and sensors comprise electromechanical systems that detect cardiac mechanical or electrical activity through skin-contact electrodes, transmitted light absorption, or acoustic transduction, typically resolving pulse intervals within 10 millisecond precision for clinical applications. Their primary purpose spans arrhythmia screening, exertion tracking, hemodynamic assessment, and longitudinal cardiovascular risk stratification across ambulatory and acute settings. Wearable monitors dominate volume shipments while handheld devices retain margin concentration in point-of-care diagnostics where ECG waveform fidelity commands premium pricing. Optical sensors lead consumer adoption due to miniaturization headroom, yet electrocardiography segments capture disproportionate clinical value through diagnostic-grade 12-lead equivalence claims. Home care represents the fastest-growing end user channel as telehealth reimbursement codes mature, while hospitals remain the reference standard for algorithm training and regulatory validation.
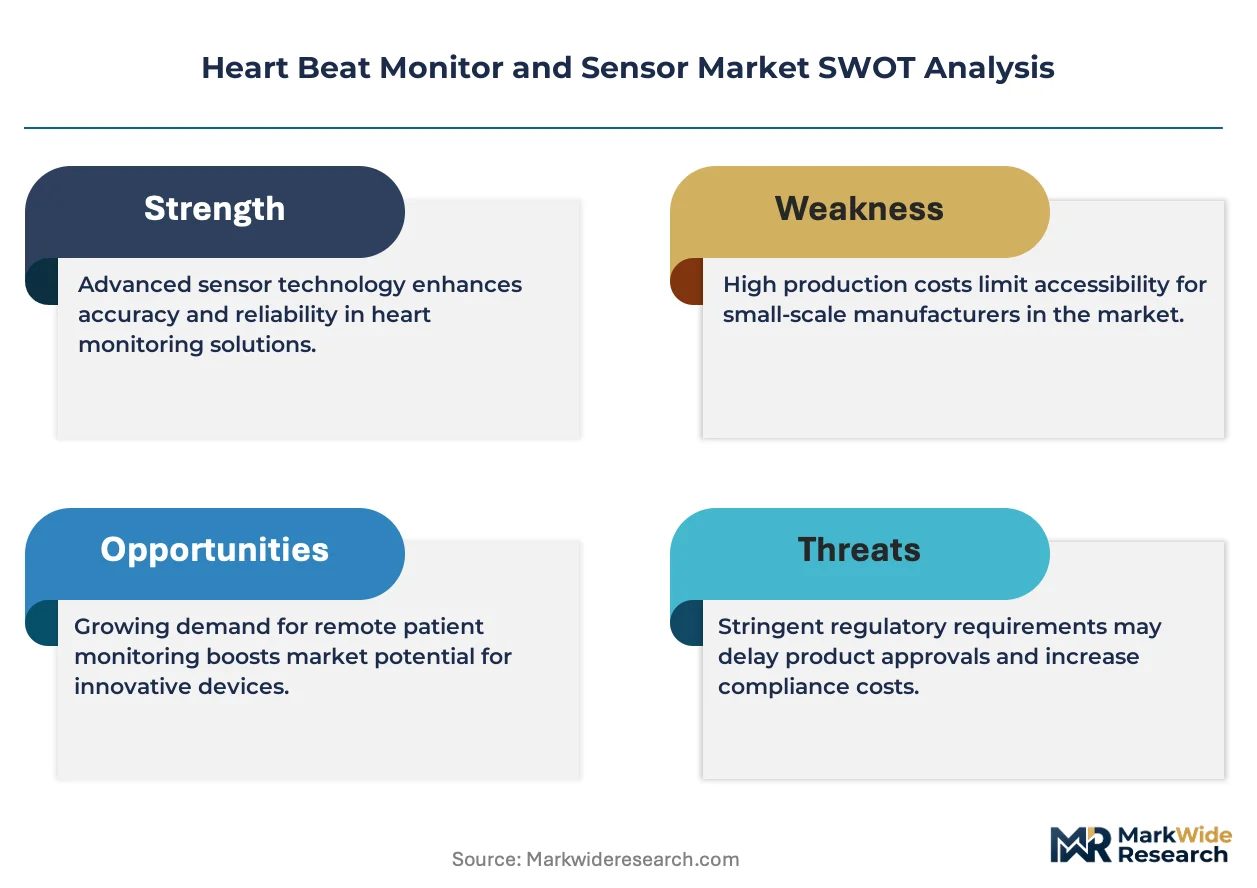
FDA digital health pre-certification and EU MDR Class IIa requirements for active diagnostic devices impose divergent compliance burdens on manufacturers seeking transatlantic market access. The FDA's evolving approach to artificial intelligence-enabled cardiac notifications creates pathway uncertainty for software update cycles, while EMDR technical documentation demands for clinical evidence are lengthening CE marking timelines. Stakeholders must monitor how health technology assessment bodies in Germany, France, and England calibrate reimbursement for preventive remote monitoring versus reactive acute intervention.
Market Dynamics
Medicare reimbursement code expansion for remote patient monitoring is pulling cardiac sensor deployment from hospital telemetry wards into residential settings, restructuring channel economics and hardware specifications simultaneously.
Growth Catalysts
- Telehealth Reimbursement Expansion:CMS CPT codes 99453-99458 now cover remote cardiac monitoring for chronic heart failure patients, accelerating physician practice adoption of cellular-connected wearable devices.
- Photoplethysmography Miniaturization:Multi-wavelength LED array integration into sub-millimeter silicon packages enables continuous SpO2 and pulse rate sensing in jewelry-form-factor wearables.
- United States:Aging demographics concentrated in Florida, Arizona, and Texas retirement corridors generate concentrated demand for home-based arrhythmia screening tools.
Market Restraints
- Optical Sensor Limitations:Skin tone pigmentation and motion artifact interference degrade photoplethysmography signal fidelity in darker skin types, constraining clinical validity claims.
- EU MDR Compliance Burden:Class IIa active diagnostic device technical documentation requirements and notified body capacity constraints extend CE marking timelines to 18-24 months.
- Implantable Battery Chemistry:Lithium-iodine cell supply concentration among three specialty manufacturers creates single-source vulnerability for implantable loop recorder production.
Strategic Opportunities
- India:CDSCO streamlined medical device registration pathways and Ayushman Bharat digital health infrastructure expansion create entry points for affordable wearable ECG monitors.
- AI-Enabled Diagnostic Notifications:FDA pre-certification pilot programs for software-as-medical-device cardiac algorithms offer accelerated clearance for machine learning-based atrial fibrillation detection.
- Pharmacy Retail Integration:CVS Health and Walgreens clinic networks are deploying shelf-based consumer heart rate monitors with telehealth referral pathways, creating new distribution density.
Industry Challenges
- Biomedical Algorithm Talent Scarcity:Competition for signal processing engineers with cardiovascular physiology domain expertise outpaces university pipeline output.
- FDA AI/ML Guidance Uncertainty:Evolving predicate device requirements for continuously learning cardiac notification algorithms complicates software update deployment strategies.
- Legacy EHR Integration Complexity:HL7 FHIR interoperability gaps between consumer wearable data formats and Epic, Cerner, and Meditech hospital systems impede clinical workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Beat Monitor and Sensor Market |
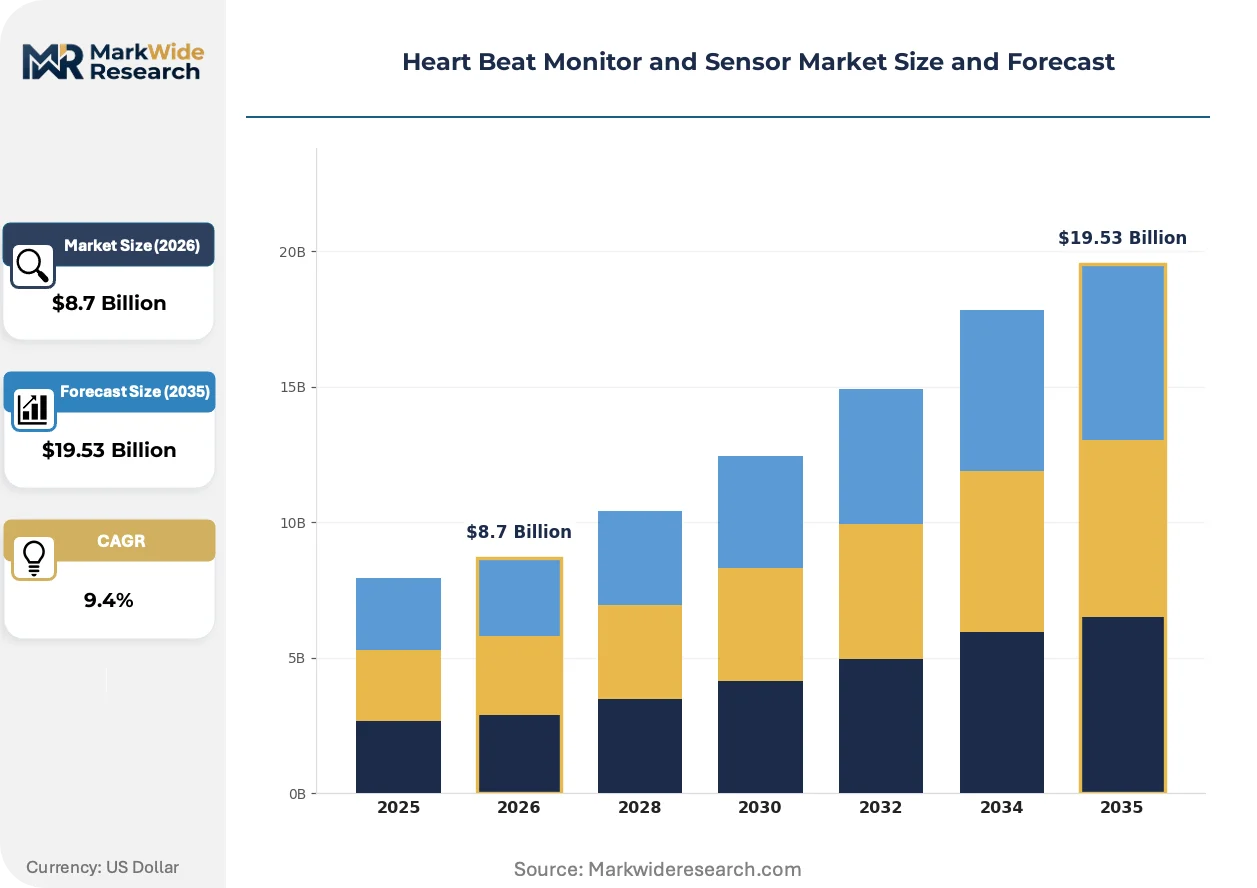
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Handheld Devices, Remote Sensors, Smartphone Apps Technology: Electrocardiography, Optical Sensors, Acoustic Sensors, Biometrics End User: Hospitals, Home Care, Fitness Centers, Research Institutions Connectivity: Bluetooth, Wi-Fi, Cellular, USB |
| Companies Covered | Samsung Electronics, Medtronic, Apple Inc., Suunto, Xiaomi, Garmin Ltd., Polar Electro, Masimo, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Beat Monitor and Sensor Market Shifts & Advancements
Silicon photonics and edge AI inference are compressing the form-factor and power-consumption constraints that historically separated consumer wellness devices from clinical-grade cardiac monitors.
Reflectance-mode photoplethysmography utilizing green and infrared LED arrays is collapsing the cost-performance gap between hospital pulse oximetry and consumer wrist-worn sensors. Cardiology outpatient clinics in the United States are adopting these devices for ambulatory rhythm screening. The technology is collapsing premium pricing power in entry-level diagnostic monitoring segments.
EU MDR Class IIa requirements for active diagnostic devices are extending technical documentation and clinical evidence demands for software-enabled cardiac sensors. Notified body capacity constraints in Germany and the Netherlands are creating regulatory bottlenecks. Manufacturers are responding by front-loading clinical validation studies and establishing dedicated EU regulatory affairs functions.
Direct-to-consumer subscription models for continuous cardiac monitoring are displacing traditional durable medical equipment rental channels. Telehealth platforms in the United States are bundling wearable ECG patches with virtual cardiology consultations. This shift is most visible in Medicare Advantage plan populations seeking preventive rhythm screening outside traditional fee-for-service structures.
Heart Beat Monitor and Sensor Market Segmentation
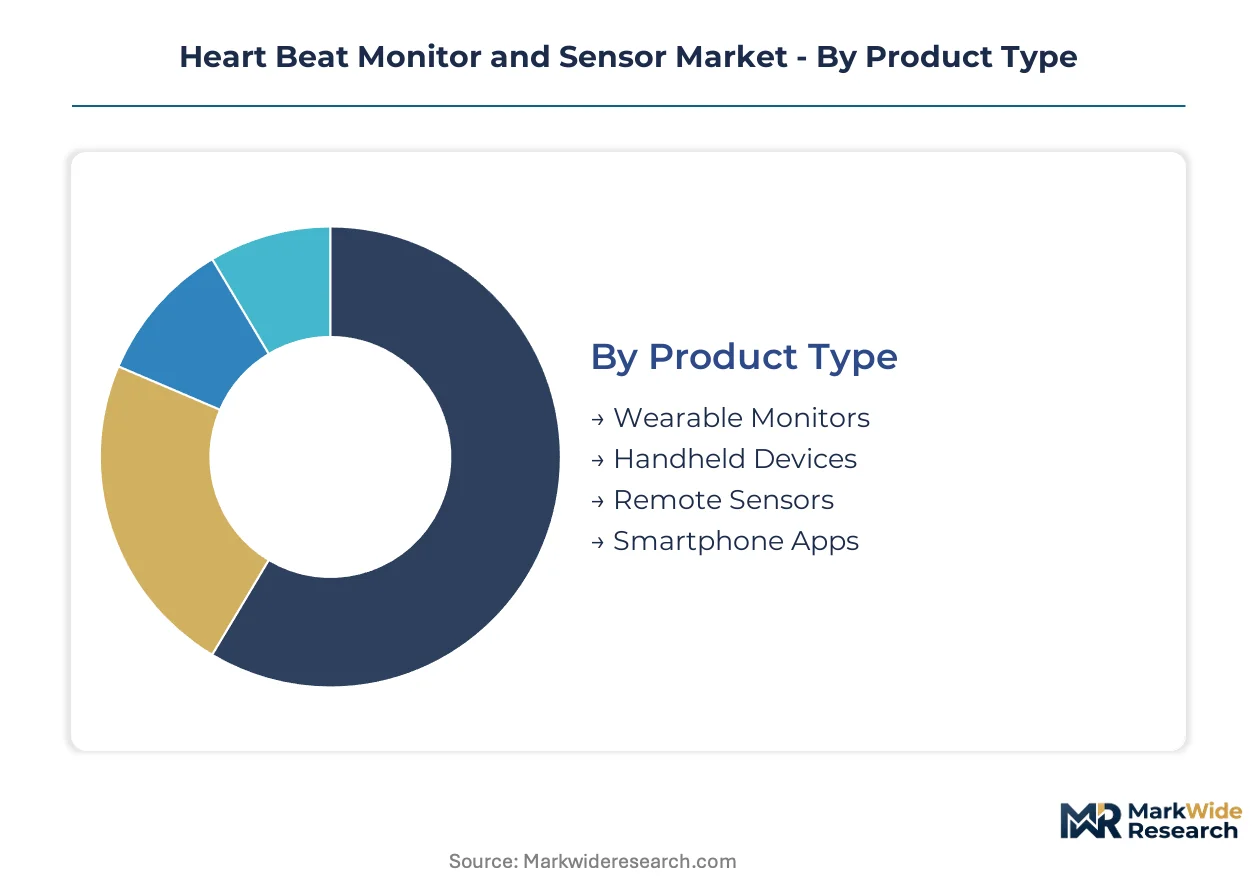
Segmentation in cardiac monitoring reveals divergent hardware specifications, regulatory pathways, and service intensity requirements across use cases. Product architecture, sensing modality, and connectivity protocol selections directly determine reimbursement eligibility and clinical validation burden for manufacturers.
Product Type:
After-sales service intensity varies sharply across form factors, with implantable and prescription-grade wearables demanding 24/7 technical support and remote monitoring infrastructure that consumer devices rarely require.
- Wearable Monitors:Wrist-worn and chest-strap devices integrate photoplethysmography or single-lead ECG electrodes for continuous ambulatory monitoring. Demand concentrates in United States Medicare Advantage populations seeking preventive arrhythmia screening outside hospital settings, pulled by expanded CPT reimbursement codes for remote patient monitoring.
- Handheld Devices:Portable units with fingertip or palm electrodes deliver diagnostic-grade 12-lead ECG equivalence for point-of-care triage. Clinical procurement in United States cardiology outpatient clinics favors these devices for same-day rhythm assessment, though FDA 510(k) predicate requirements extend development timelines.
- Remote Sensors:Patch-based adhesive monitors with cellular gateways enable multi-day longitudinal recording without patient interaction. Post-acute care facilities in Germany deploy these for heart failure discharge monitoring under Diagnosis-Related Group reimbursement incentives.
- Smartphone Apps:Software platforms leveraging device camera or accessory peripherals for pulse detection occupy the lowest hardware cost tier. Direct-to-consumer adoption in India climbs alongside Ayushman Bharat digital health infrastructure expansion.
By volume, Wearable Monitors leads. By growth pace, Remote Sensors is ahead.
Technology:
Cost tier stratification separates high-fidelity electrical sensing from miniaturized optical alternatives, with reimbursement codes favoring diagnostic-grade modalities.
- Electrocardiography:Skin-contact electrodes detect cardiac electrical activity with millivolt resolution and 10-millisecond interval precision. United States hospital systems prioritize ECG-based devices for algorithm training and regulatory validation as reference standards.
- Optical Sensors:Multi-wavelength LED arrays measure blood volume changes through photoplethysmography in reflectance or transmittance modes. Consumer electronics manufacturers in South Korea and United States dominate volume production through silicon design integration.
- Acoustic Sensors:Piezoelectric or MEMS microphones capture heart sounds and murmurs for valvular assessment. Research institutions in Japan explore phonocardiography integration for structural heart disease screening.
- Biometrics:Multi-modal fusion combines cardiac signals with galvanic skin response or temperature for stress and sleep analytics. Fitness centers in United Kingdom and Australia adopt these for member retention programs.
Electrocardiography commands premium pricing. Optical Sensors expand most quickly in consumer channels.
End User:
Customer type determines regulatory classification, with clinical settings demanding FDA Class II or EU MDR Class IIa certification that fitness and research applications circumvent.
- Hospitals:Acute care and outpatient cardiology departments require 12-lead diagnostic equivalence and EHR interoperability through HL7 FHIR protocols. United States health systems anchor demand for algorithm training datasets and predicate device establishment.
- Home Care:Residential settings with aging-in-place populations drive fastest adoption of cellular-connected wearable and patch monitors. Medicare reimbursement code expansion in United States accelerates physician practice deployment for chronic heart failure management.
- Fitness Centers:Commercial gyms and corporate wellness programs prioritize cost-minimized optical wristbands for member engagement metrics. Subscription bundling with virtual coaching platforms gains traction in Germany and Netherlands.
- Research Institutions:Academic medical centers and contract research organizations source devices for clinical trial endpoints and cardiovascular epidemiology studies. Procurement emphasizes raw data export capabilities and GCP compliance documentation.
By revenue concentration, Hospitals leads. Home Care gains share fastest as telehealth reimbursement matures.
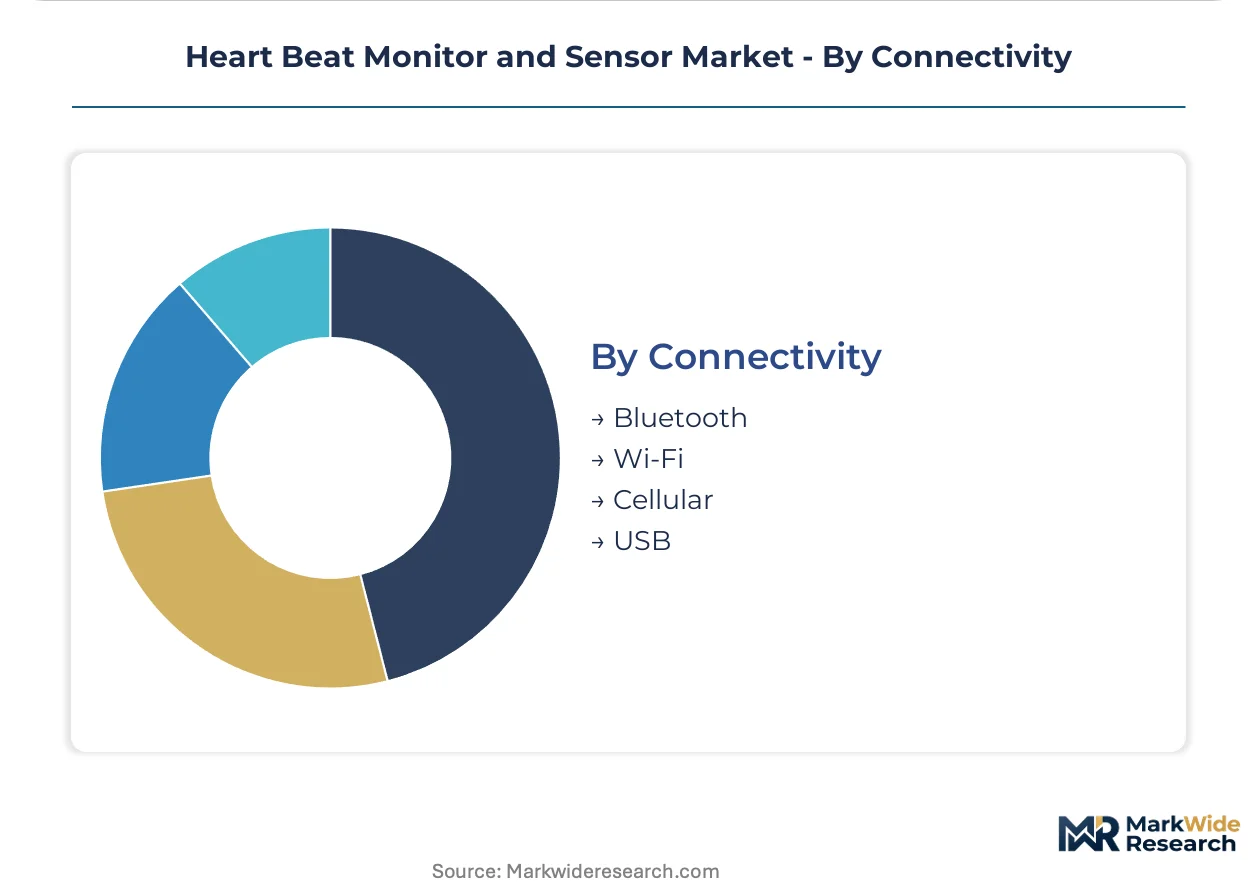
Connectivity:
Supply concentration in cellular module manufacturing and cloud infrastructure shapes hardware BOM cost structures and geographic deployment feasibility.
- Bluetooth:Short-range wireless protocol dominates consumer wearable pairing with smartphones for local data buffering. Low energy consumption enables multi-day battery life in compact form factors.
- Wi-Fi:Higher bandwidth supports continuous waveform streaming for inpatient telemetry and remote intensive care applications. United States hospital IT departments prioritize WPA3 encryption and network segmentation compliance.
- Cellular:LTE-M and NB-IoT modules enable standalone operation without patient smartphone dependency. FDA-cleared implantable loop recorders from specialty manufacturers rely on cellular gateways for encrypted rhythm data transmission.
- USB:Wired connectivity persists in clinical diagnostic equipment requiring guaranteed bandwidth and minimal latency for 12-lead ECG acquisition. Point-of-care devices in India and Brazil favor USB for interoperability with legacy hospital infrastructure.
Bluetooth dominates shipment volume. Cellular climbs the fastest as standalone prescription devices proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare Advantage plans and aging-in-place demographics concentrate cardiac sensor procurement in specific national markets. Reimbursement code expansion and digital health infrastructure maturity determine geographic deployment velocity.
United States
Florida, Arizona, and Texas retirement corridors generate concentrated demand for home-based arrhythmia screening tools. FDA digital health pre-certification pilot programs accelerate software-as-medical-device clearance pathways for machine learning-enabled cardiac notifications. Boston and San Francisco anchor algorithm development clusters where academic medical centers train diagnostic-grade detection models.
Germany
Diagnosis-Related Group reimbursement incentives pull cardiac patch monitors into post-acute heart failure discharge protocols. EU MDR Class IIa technical documentation requirements and notified body capacity constraints extend CE marking timelines for active diagnostic devices. Munich and Berlin host regulatory affairs functions that front-load clinical validation studies for transatlantic market access.
India
Ayushman Bharat digital health infrastructure expansion creates entry points for affordable wearable ECG monitors in tier-2 and tier-3 cities. CDSCO streamlined medical device registration pathways reduce import clearance friction for foreign manufacturers. Karnataka's Bengaluru cluster concentrates software development talent for signal processing algorithm engineering.
Japan
Research institutions explore phonocardiography integration for structural heart disease screening through acoustic sensor miniaturization. PMDA consultative review pathways for SaMD cardiovascular algorithms provide regulatory predictability for iterative software updates. Tokyo and Osaka metropolitan areas anchor aging-population demand for continuous residential cardiac monitoring.
South Korea
Consumer electronics manufacturers dominate volume production of multi-wavelength LED array sensors through silicon design integration. MFDS expedited review tracks for AI-enabled diagnostic devices align with national digital health strategy priorities. Seoul Capital Area concentrates vertically integrated optical engine fabrication for wrist-worn form factors.
Heart Beat Monitor and Sensor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin tiers in cardiac monitoring. Consumer technology conglomerates leverage silicon design capabilities and retail distribution density against medical device incumbents with implantable hardware and regulatory validation depth. Three archetypes dominate: vertically integrated consumer electronics platforms, prescription-grade implantable specialists, and component-focused sensor suppliers. Competitive moves concentrate on M&A for algorithm talent acquisition and strategic partnerships for EHR interoperability certification.
Within the consumer-platform archetype, Samsung Electronics and Apple Inc. exemplify hardware-software coupling strategies that embed custom optical engines directly into watch casings. Medtronic anchors the clinical-tier implantable segment with encrypted cellular data transmission infrastructure for prescription-grade rhythm monitoring. These three entities represent the poles of a market bifurcating between wellness-adjacent consumer volumes and diagnostic-validated clinical margins.
| Leading Market Players |
|---|
| Samsung Electronics |
| Medtronic |
| Apple Inc. |
| Suunto |
| Xiaomi |
| Garmin Ltd. |
| Polar Electro |
| Masimo |
| Fitbit |
| Others |
Supply & Pricing Matrix
Shanghai-Los Angeles container freight corridors transmit cost volatility from Asian optical sensor foundries into United States retail pricing, concentrating margin pressure on consumer-grade wrist-worn devices while prescription-grade implantable hardware maintains cost-plus insulation through Medicare reimbursement indexation.
Pricing Analysis
Cost-plus contracts with lithium-iodine battery suppliers index to specialty chemical commodity benchmarks, insulating implantable loop recorder manufacturers from spot volatility. Three-tier pricing structure across premium diagnostic-grade, standard clinical-wearable, and economy consumer-wellness levels separates FDA-cleared ECG devices from photoplethysmography fitness bands. Pricing pressure stems from reflectance-mode LED sensor commoditization in South Korean consumer electronics. Fitness center procurement teams exhibit highest price sensitivity; hospital purchasing committees accept premium positioning for 12-lead equivalence claims.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for multi-wavelength LED array sourcing. Optical sensor fabrication concentrates in South Korea, Taiwan, and China. Raw material dependencies span indium phosphide substrates, lithium-iodine cells, and medical-grade silicon wafers. Single-source vulnerability persists in implantable battery chemistry among three specialty manufacturers. Distribution runs through pharmacy retail networks, hospital GPO contracts, and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as Medicare reimbursement code expansion fragments demand across home care, outpatient cardiology, and fitness-adjacent prevention segments, creating specialized niches for differentiated hardware-software bundles.
For Market Incumbents: Harden algorithm validation infrastructure against FDA AI/ML guidance uncertainty by front-loading clinical evidence generation for continuously learning cardiac notification systems. Consolidate EHR interoperability certification through HL7 FHIR protocol mastery to defend against consumer electronics platform encroachment into clinical channels.
For New Entrants and Emerging Players: Tier-2 Indian cities present underpenetration for affordable wearable ECG monitors aligned with Ayushman Bharat digital health infrastructure expansion. CDSCO streamlined registration pathways reduce import friction. Target pharmacy retail telehealth referral partnerships as lowest customer acquisition cost channel.
For Investors and Strategic Acquirers: FDA pre-certification pilot program expansion reshapes the acquisition landscape toward software-as-medical-device cardiac algorithm specialists with validated training datasets. Five-to-ten year viability favors targets with EU MDR Class IIa technical documentation capabilities. Signal to watch: notified body capacity constraints in Germany and the Netherlands as CE marking bottleneck indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Accelerates software-as-medical-device clearance for machine learning-based atrial fibrillation detection algorithms. |
| EU MDR Class IIa Technical Documentation | Front-loads clinical validation studies to overcome notified body capacity constraints in Germany and the Netherlands. |
| HL7 FHIR EHR Integration | Enables seamless data exchange with Epic and Cerner hospital systems for clinical workflow adoption. |
| Cellular-Connected Patch Development | Supports standalone prescription device proliferation without patient smartphone dependency for Medicare reimbursement. |
| Pharmacy Retail Partnership | Creates distribution density through CVS Health and Walgreens clinic networks with telehealth referral pathways. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR technical documentation submissions. Interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and signal processing algorithm specialists inform demand-side validation. Secondary sources include hospital procurement databases, CDSCO registration records, and cellular module manufacturer supply disclosures. Bottom-up shipment modeling triangulates against top-down reimbursement code analysis.
Forecast inputs span product type segmentation across wearable monitors, handheld devices, remote sensors, and smartphone apps; technology modality including electrocardiography, optical sensors, acoustic sensors, and biometrics; end user channels from hospitals through home care; and connectivity protocols from Bluetooth through cellular. CAGRs derive from regression analysis against Medicare Advantage enrollment trends and telehealth reimbursement code expansion trajectories. Industry-specific inputs incorporate photoplethysmography miniaturization curves and EU MDR notified body capacity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by consumer electronics platforms or accelerated FDA AI/ML guidance finalization would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Patient Scales Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Critical Care Patient Monitoring Products Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Global IOT Sensors in Healthcare Market