
 Acute Care Market | 2026-2036
Acute Care Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Care Market Intelligence
North American hospital infrastructure expansion is reshaping competitive dynamics across the acute care sector. HCA Healthcare leverages its scale across 182 facilities to dominate inpatient service lines in high-growth metropolitan corridors. Tenet Healthcare Corporation anchors its position through concentrated geographic clustering in Texas and Florida, where population migration sustains volume growth. Fresenius Medical Care specializes in integrated renal and critical care delivery, extending its therapeutic footprint beyond traditional dialysis centers into hospital-based acute settings.
Acute care encompasses time-sensitive medical interventions for severe, episodic conditions requiring immediate clinical stabilization, typically delivered through emergency departments, intensive care units, and specialized procedure suites equipped with continuous physiological monitoring, mechanical ventilation support, and rapid diagnostic imaging capabilities. The application dimension shows trauma management and cardiac care commanding the deepest margin pools due to reimbursement complexity and technology intensity, while respiratory support segments are gaining structural share following sustained investment in ventilator and oxygenation platforms. Hospitals remain the dominant end-user channel, though ambulatory care centers are capturing migration toward same-day surgical and observation protocols that blur traditional inpatient-outpatient boundaries.
FDA device clearance frameworks, CMS reimbursement rules for inpatient prospective payment, and Joint Commission accreditation standards collectively determine market access timelines and capital deployment priorities for equipment manufacturers and facility operators. OSHA workplace safety mandates and state-level certificate-of-need regulations further constrain expansion velocity in oversaturated markets. Stakeholders must monitor how telemedicine reimbursement parity evolves against in-person care mandates, as this tension will dictate capital allocation between physical bed expansion and distributed care infrastructure.
Market Dynamics
Hospital emergency departments face mounting pressure to compress door-to-treatment intervals as patient acuity intensifies and CMS reimbursement ties payment to throughput metrics. This structural compression is forcing capital allocation toward integrated monitoring platforms and rapid diagnostic imaging suites that enable clinical decision-making within regulatory-mandated timeframes.
Growth Catalysts
- FDA 510(k) Clearance Pathways:Streamlined premarket notification for Class II medical devices accelerates deployment of next-generation patient monitoring systems in hospital-based acute settings.
- CMS Inpatient Prospective Payment:Reimbursement structures reward facilities demonstrating superior patient outcomes and reduced length-of-stay, incentivizing investment in advanced cardiac and trauma intervention capabilities.
- Aging Demographics in the United States:Chronic disease prevalence and population migration patterns concentrate demand for specialized acute interventions in high-growth metropolitan corridors across Texas and Florida.
Market Restraints
- Certificate-of-Need Regulations:State-level CON laws in oversaturated markets constrain bed expansion velocity and capital deployment timelines for facility operators seeking geographic diversification.
- Critical Care Workforce Scarcity:Specialized nursing and intensivist shortages limit operational scaling regardless of installed equipment capacity or physical infrastructure availability.
- Medical Device Input Concentration:Semiconductor and sensor supply chains remain concentrated in East Asian manufacturing clusters, exposing equipment manufacturers to geopolitical disruption risk.
Strategic Opportunities
- Telemedicine Reimbursement Parity:Evolving state-level mandates for virtual care payment equivalence create distributed infrastructure investment opportunities beyond traditional physical bed expansion.
- Ambulatory Care Center Migration:Same-day surgical and observation protocols blur inpatient-outpatient boundaries, enabling capture of procedural volume in lower-cost settings.
- Integrated Renal-Critical Care Delivery:Therapeutic footprint extension beyond dialysis centers into hospital-based acute settings addresses unmet demand for continuous renal replacement therapy.
Industry Challenges
- Joint Commission Accreditation Timelines:Extended survey cycles and corrective action protocols delay market access for new facility entrants and equipment installations.
- Legacy System Interoperability:Electronic health record integration with next-generation monitoring platforms requires costly middleware development and data standardization efforts.
- OSHA Workplace Safety Compliance:Evolving exposure limits and protective equipment mandates necessitate continuous operational reconfiguration in high-acuity clinical environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Care Market |
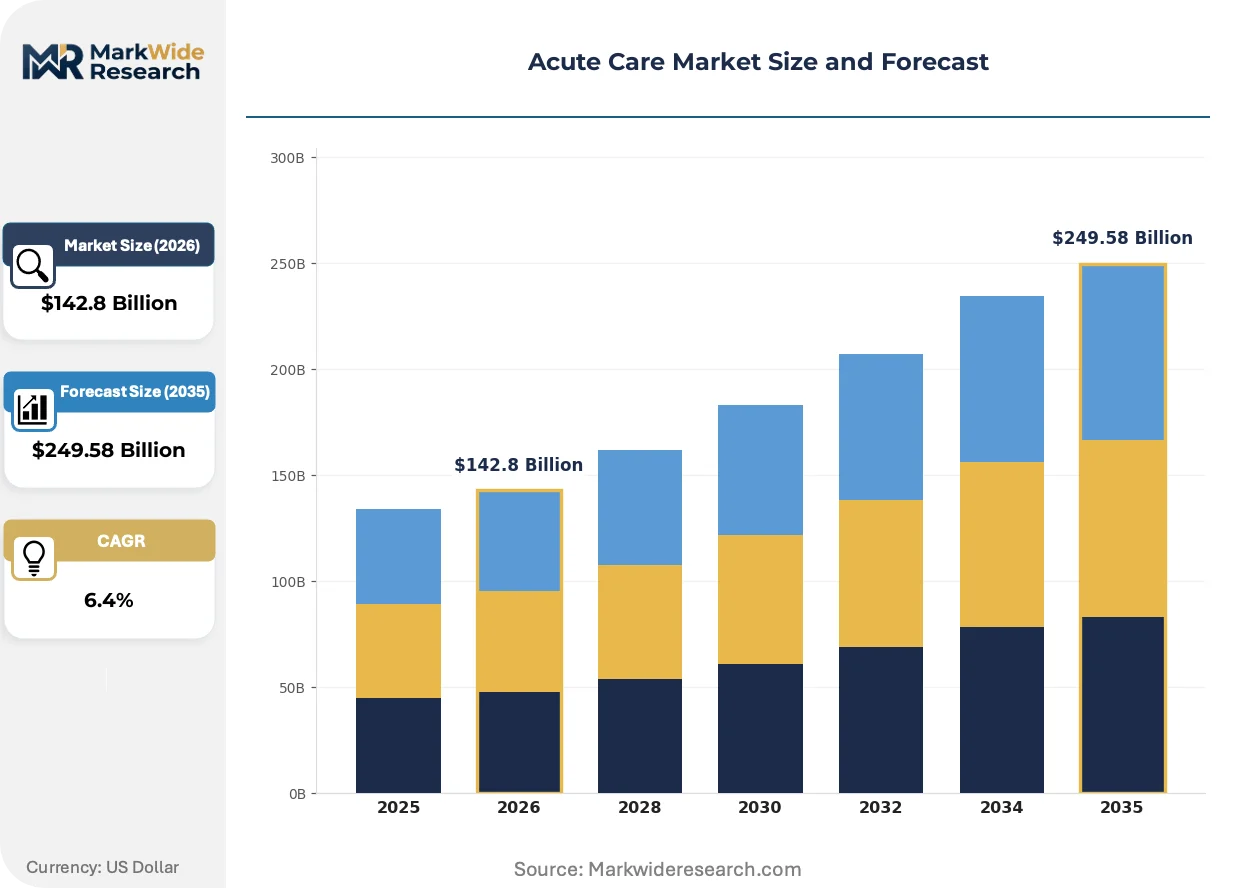
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $249.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Devices, Diagnostic Equipment, Therapeutic Solutions, Monitoring Systems, Surgical Instruments Application: Trauma Management, Cardiac Care, Emergency Response, Respiratory Support, Infection Control End User: Hospitals, Emergency Medical Services, Ambulatory Care Centers, Surgical Clinics, Critical Care Units Delivery Mode: Inpatient Care, Outpatient Services, Telemedicine, Home Healthcare, Mobile Clinics |
| Companies Covered | HCA Healthcare, Tenet Healthcare Corporation, Universal Health Services, Community Health Systems, Ascension, Fresenius Medical Care, Ramsay Health Care, Mayo Clinic, Cleveland Clinic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Care Market Strategic Shifts & Innovations
Continuous physiological monitoring technology is collapsing the latency between patient deterioration and clinical intervention, compressing traditional response workflows into automated alert-to-action sequences. This capability shift is redrawing competitive boundaries between device manufacturers and enterprise software platforms.
Artificial intelligence-enabled diagnostic algorithms embedded in bedside monitors is collapsing the distinction between detection and diagnosis, enabling real-time arrhythmia identification and sepsis risk stratification without specialist interpretation delays. Large health systems in the United States are deploying these platforms across intensive care units to reduce alarm fatigue and false-positive rates. The structural consequence is a compression of clinical staffing ratios and a redefinition of intensivist oversight models.
The FDA's updated 510(k) clearance framework for software-as-a-medical-device is accelerating deployment timelines for algorithm-based monitoring tools while tightening post-market surveillance requirements. Manufacturers must now demonstrate continuous learning system controls and drift detection protocols to maintain clearance status. Cardiac monitoring segments face the steepest compliance burden as real-time diagnostic claims trigger heightened scrutiny.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts that bundle hardware, software, and predictive analytics under single-source agreements. This behavioral shift displaces traditional best-of-breed purchasing for individual device categories. The concentration is most visible in the United States, where health system consolidation has reduced the number of independent purchasing decision-makers by half over the past decade.
Acute Care Market Segmentation
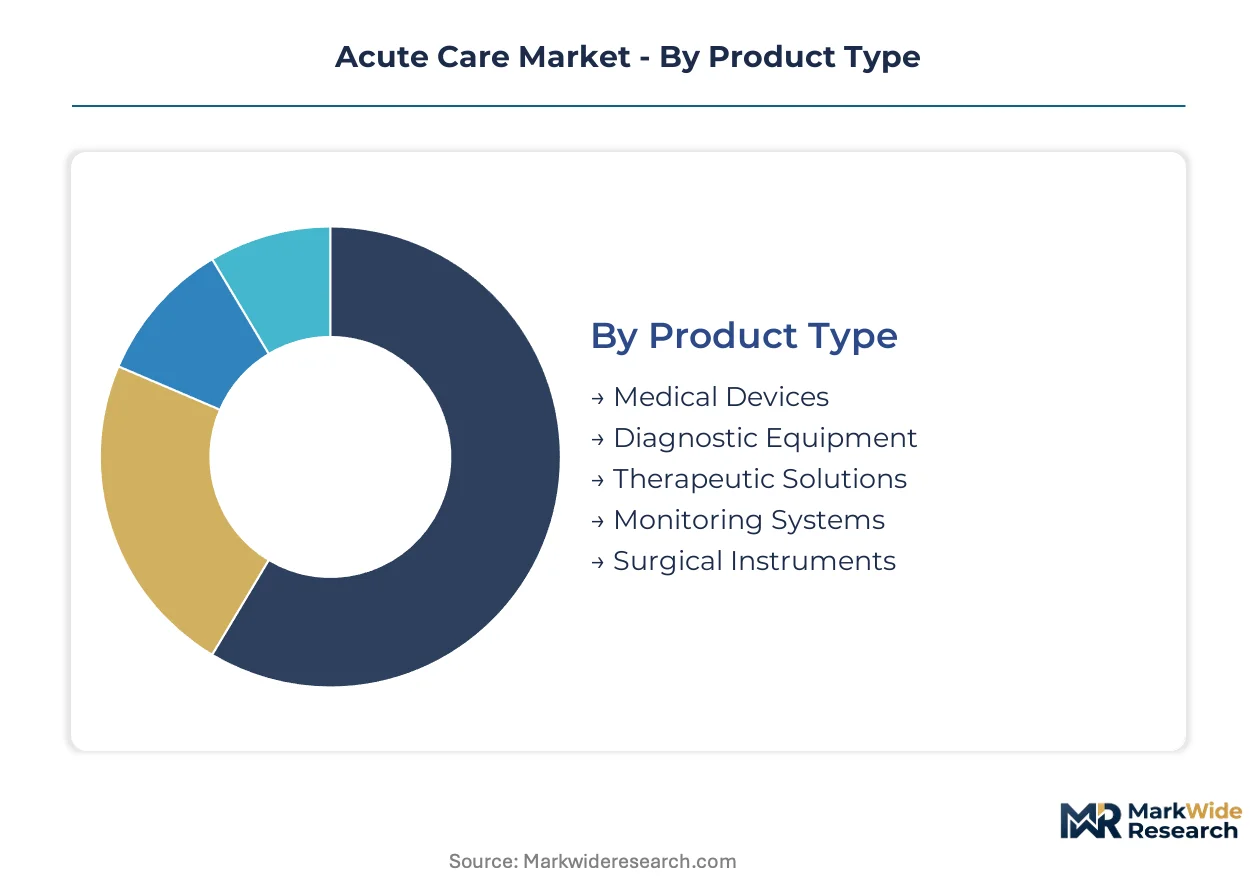
Acute care segmentation reveals how capital flows concentrate around high-acuity interventions and integrated technology platforms. Distinct product, application, and delivery configurations determine reimbursement pathways and facility investment priorities.
Product Type:
Use-case spectrum spans life-sustaining intervention to diagnostic confirmation, with technology intensity dictating margin architecture and regulatory burden.
- Medical Devices:Mechanical ventilators, infusion pumps, and defibrillators form the procedural backbone of emergency and critical care environments. Demand clusters in HCA Healthcare and Tenet Health system corridors across Texas and Florida, where bed expansion outpaces national averages.
- Diagnostic Equipment:Point-of-care ultrasound, rapid CT scanners, and laboratory analyzers compress door-to-diagnosis intervals in high-throughput emergency departments. FDA 510(k) clearance velocity for portable imaging systems is accelerating deployment in ambulatory settings seeking to capture observation stays.
- Therapeutic Solutions:Renal replacement systems and targeted temperature management devices address organ failure cascades.
- Monitoring Systems:Continuous multi-parameter platforms integrate AI-enabled arrhythmia detection with centralized alarm management.
- Surgical Instruments:Minimally invasive toolsets support same-day procedural migration in specialized intervention suites.
The dominant share belongs to Medical Devices, while Monitoring Systems is closing the gap fastest.
Application:
Margin depth varies sharply across clinical domains, with reimbursement complexity and technology density determining capital allocation priority.
- Trauma Management:Damage control resuscitation protocols demand integrated hemorrhage control, massive transfusion coordination, and rapid surgical intervention capabilities. Level I trauma centers in high-migration metropolitan corridors command premium reimbursement through CMS disproportionate share adjustments.
- Cardiac Care:Percutaneous coronary intervention, electrophysiology mapping, and mechanical circulatory support require catheterization lab infrastructure and specialized interventional teams. Demand concentrates where aging demographics intersect with Certificate-of-Need regulated bed expansion constraints.
- Emergency Response:Pre-hospital stabilization and rapid transport protocols bridge scene-to-door clinical continuity.
- Respiratory Support:High-flow oxygenation and extracorporeal membrane oxygenation gained structural investment priority following pandemic-era supply chain stress.
- Infection Control:Antimicrobial stewardship and isolation infrastructure address resistant organism containment in immunocompromised populations.
Cardiac Care commands the deepest margin pool, though Trauma Management is expanding most quickly in CON-constrained expansion markets.
End User:
Channel configuration determines reimbursement rate, regulatory oversight intensity, and technology deployment scale.
- Hospitals:Emergency departments and intensive care units anchor acute care delivery through 24-hour specialist coverage and comprehensive intervention capability. CMS inpatient prospective payment structures reward length-of-stay compression and outcome metrics that favor integrated monitoring platform investment.
- Emergency Medical Services:Ground and air ambulance systems extend therapeutic intervention into pre-hospital windows, with 12-lead ECG transmission and mechanical CPR devices narrowing time-to-treatment gaps.
- Ambulatory Care Centers:Observation protocols and same-day surgical migration capture lower-acuity volume outside traditional inpatient admission pathways.
- Surgical Clinics:Specialized procedure suites concentrate elective intervention away from emergency department bottlenecks.
- Critical Care Units:Dedicated neuro, cardiac, and medical ICU configurations target specific organ failure phenotypes with tailored staffing ratios.
Hospitals retain dominant volume share, yet Ambulatory Care Centers are capturing procedural migration fastest.
Delivery Mode:
Site-of-care flexibility is reshaping capital deployment between physical infrastructure and distributed access platforms.
- Inpatient Care:Traditional hospital admission for stabilization, intervention, and recovery remains the default for high-acuity, multi-system failure presentations. Bed availability constraints in oversaturated markets drive investment toward throughput optimization rather than greenfield expansion.
- Outpatient Services:Observation stays and short-procedure suites enable reimbursement capture without overnight admission classification. Ambulatory surgical centers in Texas and Florida migration corridors are expanding procedural capacity to meet volume displacement from hospital emergency departments.
- Telemedicine:Virtual consultation and remote patient monitoring extend specialist reach into underserved geographies.
- Home Healthcare:Post-acute transition and chronic disease management reduce readmission exposure.
- Mobile Clinics:Deployable units address surge capacity and rural access gaps.
Inpatient Care maintains structural dominance, though Outpatient Services is gaining share fastest as reimbursement parity evolves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-35 corridor freight rail network and Dallas-Fort Worth International Airport's cargo capacity underwrite Texas's central role in acute care supply chain distribution across the southern United States.
United States
Aging demographics in Florida and Texas migration corridors concentrate demand for cardiac and trauma interventions. CMS inpatient prospective payment structures reward facilities demonstrating superior throughput metrics and reduced length-of-stay. HCA Healthcare operates 182 facilities across high-growth metropolitan areas, leveraging scale to dominate inpatient service lines.
Germany
Industrial clusters in Baden-Württemberg and Bavaria anchor precision medical device manufacturing for European acute care deployment. EMA medical device regulations and MDR compliance frameworks shape product certification timelines. Stuttgart-based manufacturers supply monitoring platforms to hospital systems across the continent.
Japan
Super-aging society dynamics in the Kanto region intensify demand for intensive care capacity and continuous renal replacement therapy. PMDA regulatory pathways for software-as-a-medical-device accelerate AI-enabled diagnostic algorithm deployment. Tokyo metropolitan hospitals pioneer automated alert-to-action monitoring workflows.
China
Hospital infrastructure expansion in the Yangtze River Delta and Pearl River Delta regions addresses unmet acute care capacity. NMPA streamlined approval processes for Class II medical devices enable faster platform deployment. Shanghai-based health systems invest in integrated monitoring and rapid diagnostic imaging suites.
United Kingdom
London and Southeast England concentrate specialized trauma and cardiac intervention capabilities within NHS trusts. MHRA post-Brexit regulatory autonomy modifies device approval pathways while maintaining alignment with international standards. Imperial College Healthcare anchors academic medical center innovation in high-acuity clinical environments.
Acute Care Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The acute care sector exhibits tiered consolidation around multi-facility health systems and specialized device manufacturers. Three archetypes dominate: scale-driven hospital operators, integrated renal-critical care specialists, and technology-anchored academic medical centers. Competitive intensity manifests through geographic clustering strategies and vendor consolidation around integrated platform contracts.
Among United States-based health systems, HCA Healthcare, Tenet Healthcare Corporation, and Fresenius Medical Care occupy distinct strategic positions. HCA exemplifies the scale-driven operator archetype through its 182-facility footprint. Tenet represents geographic clustering concentration in high-migration corridors. Fresenius anchors the integrated therapeutic delivery model extending beyond traditional dialysis into hospital-based acute settings.
| Leading Market Players |
|---|
| HCA Healthcare |
| Tenet Healthcare Corporation |
| Universal Health Services |
| Community Health Systems |
| Ascension |
| Fresenius Medical Care |
| Ramsay Health Care |
| Mayo Clinic |
| Cleveland Clinic |
| Others |
Cost & Logistics Intelligence
East Asian semiconductor manufacturing clusters anchor component pricing for patient monitoring platforms, with foundry capacity allocation decisions cascading directly into equipment manufacturers' margin structures and hospital procurement timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates acute care equipment procurement, with FDA 510(k) clearance tier and integrated software bundling as the primary differentiation drivers. Pricing pressure stems from health system consolidation reducing independent purchasing decision-makers by half over the past decade, forcing volume discounts. Ambulatory care centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize outcome-linked value metrics over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese and South Korean EMS providers holding capacity for sensor modules and semiconductor packaging. Raw material dependencies center on rare earth elements for magnetic components, specialized polymers for disposable circuits, and precision glass for optical sensors. Single-source vulnerability in East Asian lithography equipment exposes manufacturers to geopolitical disruption risk. Distribution runs through regional medical device distributors with GPO contract management capabilities serving consolidated health system networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acute care delivery is undergoing a platform-economics inflection as AI-enabled monitoring systems collapse the distinction between hardware vendors and enterprise software providers, with interoperability standards determining competitive survival.
For Market Incumbents: Harden integrated platform contracts by bundling predictive analytics with hardware maintenance agreements, locking out best-of-breed competitors. Deepen backward integration into sensor manufacturing to reduce exposure to East Asian supply chain volatility. Prioritize FDA software-as-a-medical-device clearance investment to maintain algorithm deployment velocity against emerging AI-native entrants.
For New Entrants and Emerging Players: Rural telemedicine corridors in the Mountain West and Upper Midwest present underpenetrated demand for remote patient monitoring with reimbursement parity tailwinds. Target ambulatory surgical centers seeking observation stay capture outside hospital emergency department bottlenecks. Pursue hospital-at-home partnerships as the primary go-to-market angle, leveraging CMS waiver extensions for acute-level care in residential settings.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm-enabled monitoring specialists with demonstrated drift detection protocols and continuous learning system controls. Long-term viability hinges on regulatory compliance automation capabilities rather than hardware manufacturing scale. Monitor FDA enforcement discretion letters on AI diagnostic claims as the critical inflection signal for valuation repricing across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Accelerates AI algorithm deployment timelines while tightening post-market surveillance obligations for cardiac monitoring segments. |
| Hospital System Partnership | Locks in multi-year integrated platform contracts that displace fragmented best-of-breed purchasing across HCA and Tenet networks. |
| CE Marking Pathway | Opens European acute care deployment through EMA MDR compliance for manufacturers with Stuttgart-based precision device supply relationships. |
| Software Companion Development | Enables EHR integration with next-generation monitoring platforms, reducing costly middleware development for health system customers. |
| Reimbursement Strategy | Aligns product positioning with CMS inpatient prospective payment metrics rewarding length-of-stay compression and throughput optimization. |
Research Approach
A standing panel of intensive care unit directors, hospital purchasing committee chairs, biomedical engineering managers, and GPO contracts specialists provided ongoing calibration against secondary validation through FDA 510(k) clearance databases, CMS Medicare cost report filings, hospital procurement transaction records, and Joint Commission accreditation survey cycles. Bottom-up equipment shipment tracking triangulated against top-down health system capital expenditure disclosures.
Scenario-bracketing framed demand projections across the modeling period, with segmentation dimensions spanning product type intensity, application acuity tier, end-user channel configuration, and delivery mode flexibility. CAGRs derived from installed base replacement cycles and greenfield capacity expansion pipelines in high-migration metropolitan corridors. Forecast inputs incorporated Certificate-of-Need regulatory velocity and telemedicine reimbursement parity evolution as swing variables.
Practitioners should monitor FDA guidance document releases on continuous learning system controls and state-level CON moratorium movements for early signals of capacity constraint relaxation or tightening. Quarterly review of health system merger announcements and GPO contract consolidation patterns is advised to detect inflection in vendor pricing power and procurement committee composition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Metabolomics Services Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
Funeral Goods and Services Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Blood Bank Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
Global Healthcare Contract Manufacturing Market
Healthcare Services
Global Hospital Services Market