
 Saudi Arabia Wound Care Management Devices Market | 2026-2036
Saudi Arabia Wound Care Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Wound Care Management Devices Market Analytics
Saudi manufacturing of wound care consumables is decoupling from pure import dependency as local packaging and sterilization capabilities expand. ConvaTec Inc. leverages its hydrocolloid technology leadership to sustain premium positioning in hospital tenders. Molnlycke Health Care anchors its presence through specialized burn care and surgical wound portfolios. Smith and Nephew differentiates via advanced negative pressure wound therapy systems deployed across Saudi tertiary centers.
Wound care management devices encompass dressings, bandages, topical agents, and closure mechanisms engineered from hydrocolloid, foam, alginate, or silver-infused substrates to maintain moist healing environments, manage exudate, and prevent infection across acute, chronic, surgical, and burn indications. Silver-infused technology commands margin concentration due to antimicrobial premium pricing in diabetic foot and post-surgical applications, while foam dressings lead volume throughput in hospital settings where exudate management dominates clinical workflows. Hydrocolloid segments compete on cost efficiency in home care transitions, where patient self-management reduces readmission exposure.
The Saudi Food and Drug Authority (SFDA) governs medical device registration and post-market surveillance, enforcing conformity with Gulf Standardization Organization (GSO) technical requirements that shape import timelines and local labeling obligations. The Ministry of Health's procurement frameworks and Health Sector Transformation Program directives steer demand toward value-based wound care outcomes in public hospital networks. Stakeholders must monitor SFDA's evolving digital submission portals and localization incentives that could reshape competitive access for multinational suppliers.
Market Dynamics
Hospital procurement centralization under Saudi Arabia's Health Sector Transformation Program is consolidating purchasing power and redirecting demand toward advanced wound care technologies that demonstrate measurable clinical outcomes.
Growth Catalysts
- Advanced Dressing Adoption:Tertiary hospitals in Riyadh and Jeddah are standardizing hydrocolloid and foam dressings for post-surgical and diabetic foot protocols. The Ministry of Health's value-based procurement frameworks reward suppliers demonstrating reduced healing times.
- SFDA Registration Streamlining:The Saudi Food and Drug Authority's digital submission portals and accelerated review pathways for Class II medical devices are compressing import timelines for novel wound care technologies.
- Burn Care Infrastructure Expansion:Specialized burn centers in the Eastern Province and Asir region are driving demand for silver-infused and alginate dressings engineered for exudate management in complex thermal injuries.
Market Restraints
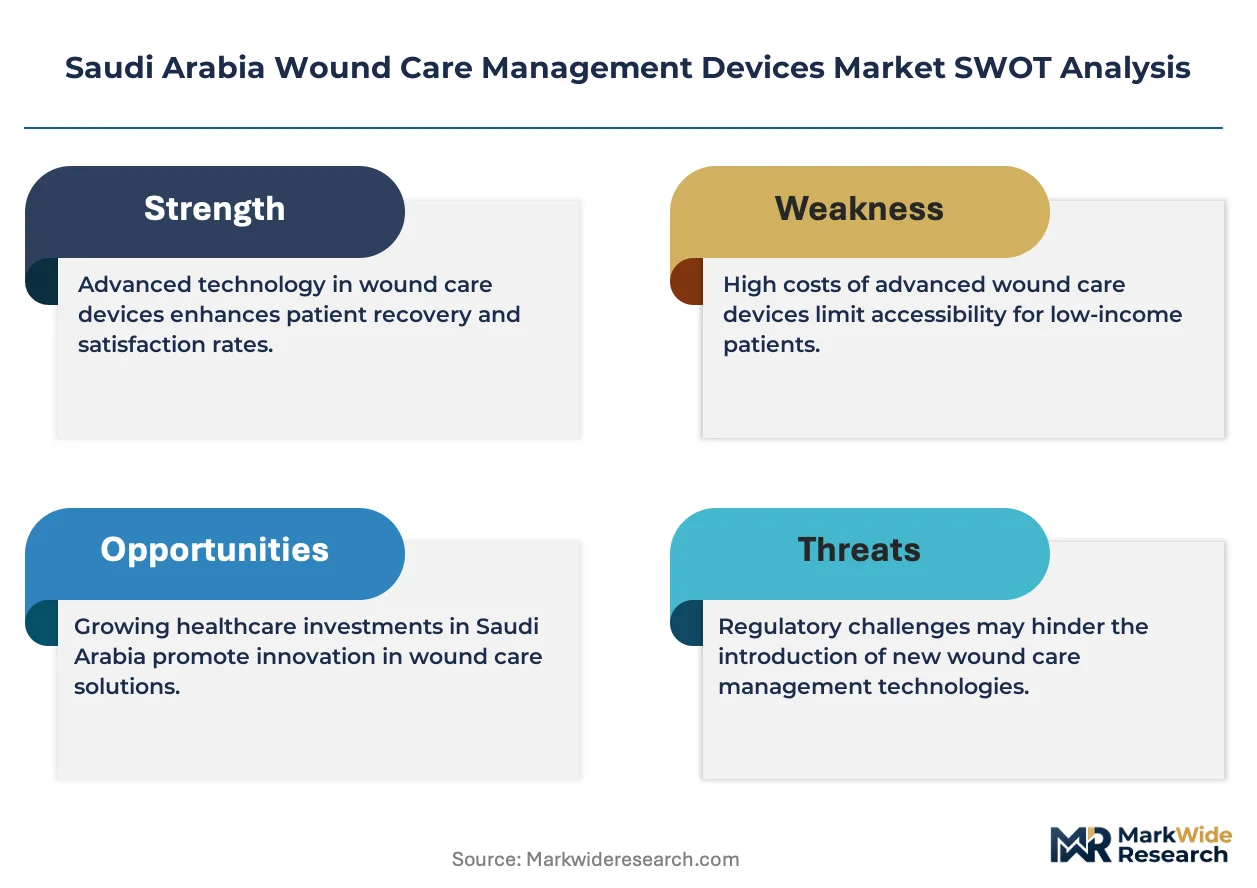
- Import Dependency Concentration:Local manufacturing remains limited to packaging and sterilization, with raw material supply chains anchored in European and Asian polymer suppliers creating forex exposure.
- Reimbursement Compression:The Council of Health Insurance's standardized pricing schedules for advanced wound dressings compress margins on antimicrobial and negative pressure wound therapy systems.
- Technical Skill Gaps:Community hospital nursing staff lack standardized training in negative pressure wound therapy application, limiting deployment outside tertiary referral centers.
Strategic Opportunities
- Home Care Transition Services:The Ministry of Health's hospital-at-home initiatives create demand for patient-managed hydrocolloid and foam dressing kits with telemedicine integration.
- Localization Incentives:SFDA's emerging local content requirements and Made in Saudi program offer preferential tender access for manufacturers establishing sterilization and final assembly within the Kingdom.
- Diabetic Foot Prevention:The Saudi National Diabetes Center's screening protocols are expanding early-intervention wound care into primary care clinics across Asir and Tabuk regions.
Industry Challenges
- SFDA Conformity Assessment Delays:Gulf Standardization Organization technical documentation requirements and local labeling obligations extend registration timelines for novel substrate technologies.
- Integration Complexity:Electronic health record systems in private hospital networks lack standardized wound documentation modules, complicating outcome tracking for value-based contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Wound Care Management Devices Market |
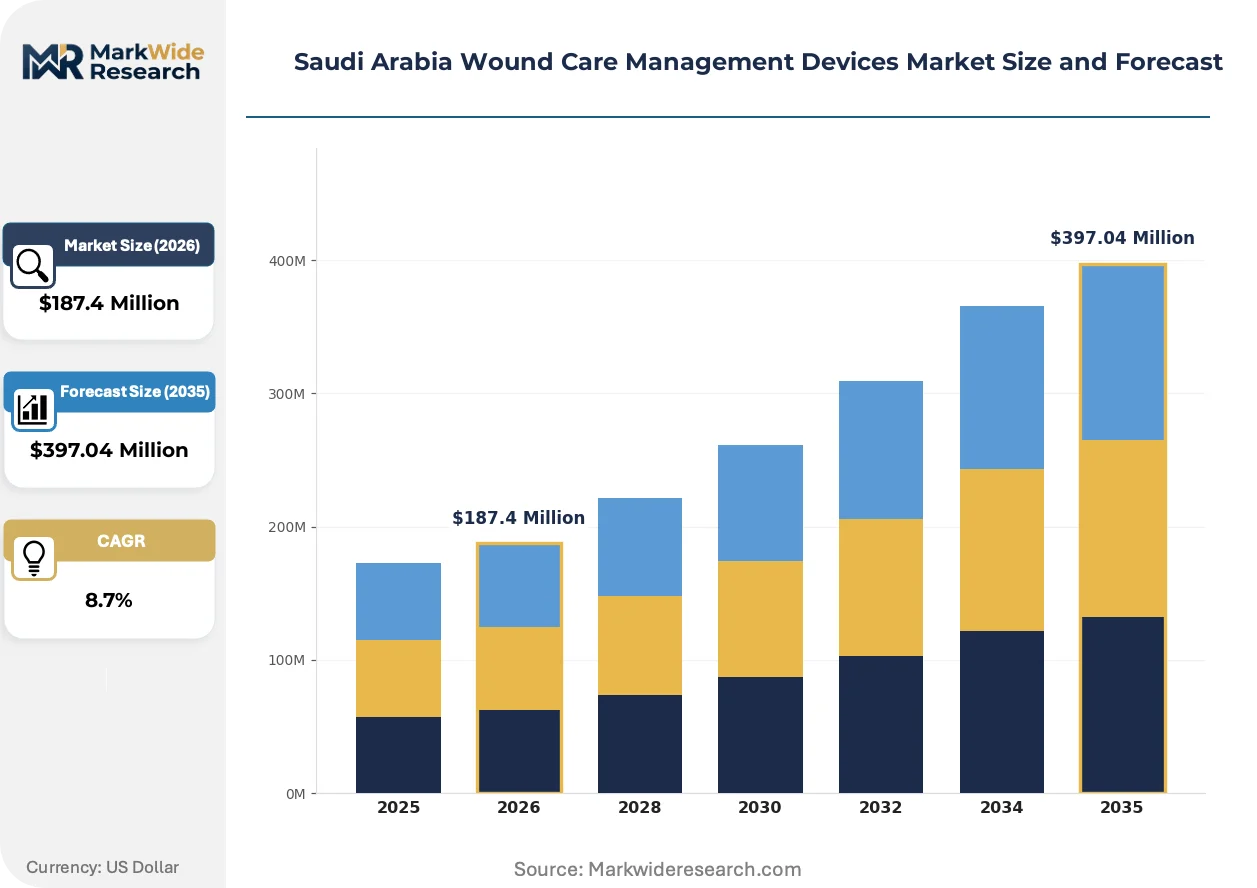
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Bandages, Topical Agents, Wound Closure Devices Technology: Hydrocolloid, Foam, Alginate, Silver-Infused End User: Hospitals, Clinics, Home Care, Long-Term Care Facilities Application: Acute Wounds, Chronic Wounds, Surgical Wounds, Burn Care |
| Companies Covered | ConvaTec Inc., Coloplast Ltd, Johnson and Johnson, B. Braun SE, Molnlycke Health Care, 3M Company, Medtronic Plc, Solventum, Smith and Nephew, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Wound Care Management Devices Market Evolving Landscape
Digital wound assessment tools and smart dressing substrates are converging with Saudi telemedicine infrastructure to enable remote monitoring of chronic wounds outside hospital settings.
Silver-ion and PHMB-impregnated foam dressings are electrifying antimicrobial protection standards in diabetic foot and post-surgical applications. King Faisal Specialist Hospital and Research Centre in Riyadh has adopted these substrates for high-risk wound protocols. The technology is electrifying competitive differentiation as manufacturers compete on sustained-release kinetics and biocompatibility profiles rather than commodity pricing.
SFDA's alignment with Gulf Standardization Organization technical requirements and forthcoming medical device single audit program recognition is harmonizing conformity assessment across Gulf Cooperation Council markets. Manufacturers registering in Saudi Arabia gain streamlined access to Bahrain, Kuwait, and UAE markets through mutual recognition agreements. Negative pressure wound therapy systems face the most intensive scrutiny under these evolving post-market surveillance protocols.
Hospital procurement consolidation is fragmenting supplier relationships as the Ministry of Health's Nupco platform aggregates demand across public sector facilities. Specialized distributors with clinical training capabilities are displacing general medical device traders in tender participation. Private hospital groups in Jeddah's growing healthcare cluster are most aggressively pursuing direct manufacturer relationships to secure technical support and inventory guarantees.
Saudi Arabia Wound Care Management Devices Market Segmentation
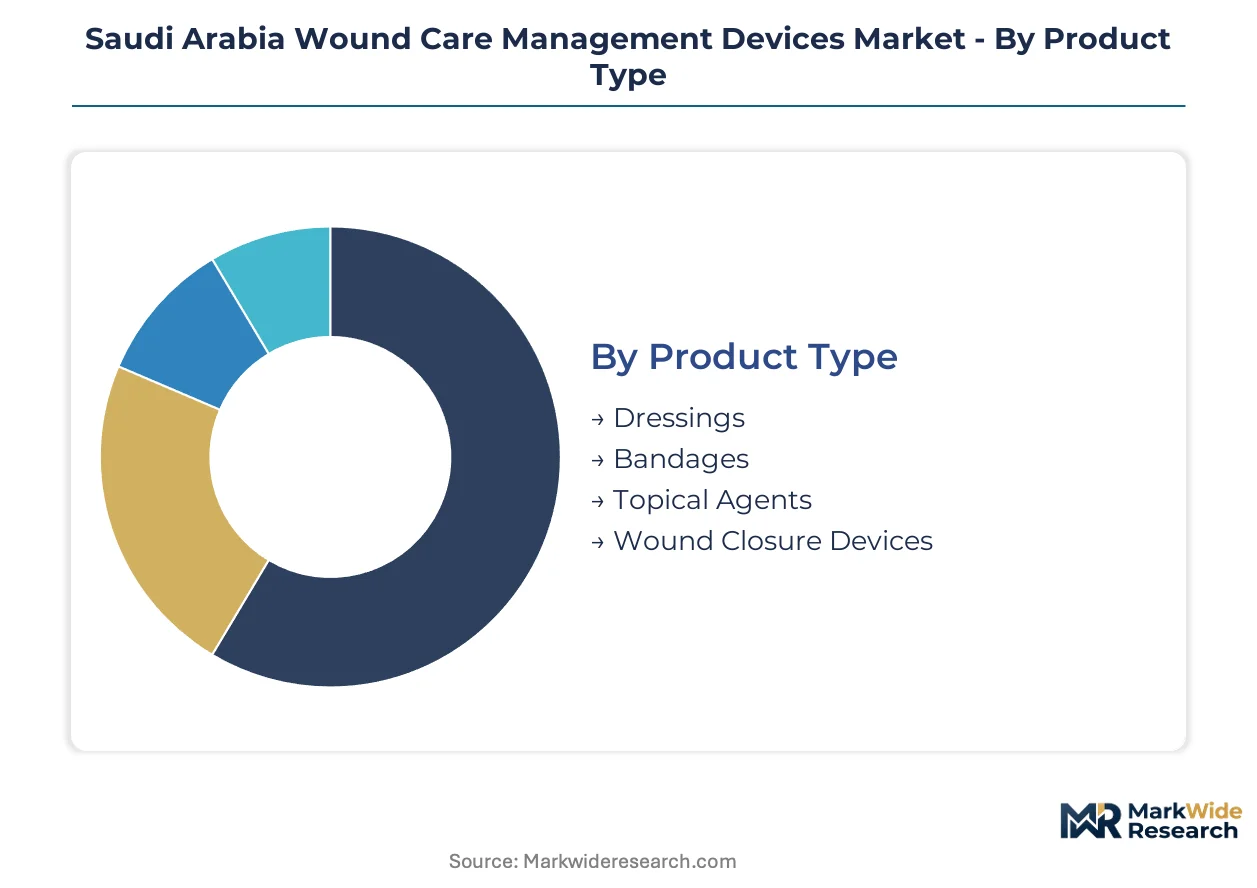
Wound care procurement in Saudi Arabia fragments across substrate technologies, clinical settings, and wound etiologies. Understanding these segment boundaries clarifies where value concentrates and which upgrade cycles reshape competitive positioning.
Product Type:
Replacement cycles vary dramatically across product categories, with advanced dressings refreshing every 12-18 months versus durable closure devices spanning 3-5 year procurement windows.
- Dressings:Advanced substrates including hydrocolloid, foam, alginate, and silver-impregnated variants dominate hospital formularies. Riyadh's King Faisal Specialist Hospital and Research Centre maintains centralized dressing protocols that standardize antimicrobial foam for post-surgical cases.
- Bandages:Elastic, compression, and retention bandages serve secondary fixation and edema management. Jeddah's private hospital cluster sources these through Nupco's aggregated procurement platform, compressing distributor margins.
- Topical Agents:Ointments, hydrogels, and enzymatic debriders complement mechanical dressings. Demand concentrates in burn centers across the Eastern Province where enzymatic agents reduce operative debridement frequency.
- Wound Closure Devices:Sutures, staples, adhesives, and negative pressure wound therapy systems anchor surgical supply chains. SFDA Class II registration pathways govern these higher-risk devices, extending import timelines versus consumable dressings.
Dressings sit at the top of the volume ranking, with wound closure devices climbing the fastest as tertiary centers expand negative pressure wound therapy capabilities.
Technology:
Cost tiers separate commodity substrates from premium antimicrobial platforms, with reimbursement schedules compressing mid-tier positioning.
- Hydrocolloid:Gel-forming cellulose derivatives maintain moist healing environments for low-exudate wounds. Home care transitions in Asir and Tabuk regions favor these for patient self-management, reducing readmission exposure.
- Foam:Polyurethane matrices manage moderate-to-heavy exudate across surgical and pressure injury indications. Volume leadership reflects hospital standardization for post-operative protocols where exudate control dominates clinical workflows.
- Alginate:Seaweed-derived calcium sodium fibers gel on contact with wound fluid, suiting cavity and tunneling wounds. Burn care infrastructure expansion in the Eastern Province drives specialized demand for these conformable substrates.
- Silver-Infused:Ionic silver release systems command antimicrobial premium pricing in diabetic foot and post-surgical applications. The Saudi National Diabetes Center's screening protocols are expanding addressable cases for these high-margin products.
Foam sits at the top of the volume ranking, with silver-infused technology gaining share fastest as diabetic foot prevention programs penetrate primary care.
End User:
Customer type determines packaging formats, training requirements, and reimbursement pathways across the Kingdom's fragmented delivery system.
- Hospitals:Tertiary centers in Riyadh and Jeddah anchor demand for advanced negative pressure wound therapy and antimicrobial dressings. Ministry of Health value-based procurement frameworks reward suppliers demonstrating reduced healing times.
- Clinics:Primary care and specialty wound clinics manage stable chronic wounds and debridement services. SFDA's emerging local content requirements could reshape tender access for multinational suppliers serving this channel.
- Home Care:Patient-managed dressing kits with telemedicine integration are expanding under Ministry of Health hospital-at-home initiatives. Hydrocolloid and foam formats dominate this transition given self-application feasibility.
- Long-Term Care Facilities:Pressure injury prevention and management in aged care settings drives demand for repositioning protocols combined with protective dressings. This channel remains underpenetrated versus Western benchmarks.
Hospitals sit at the top of the volume ranking, with home care climbing the fastest as Health Sector Transformation Program directives accelerate discharge optimization.
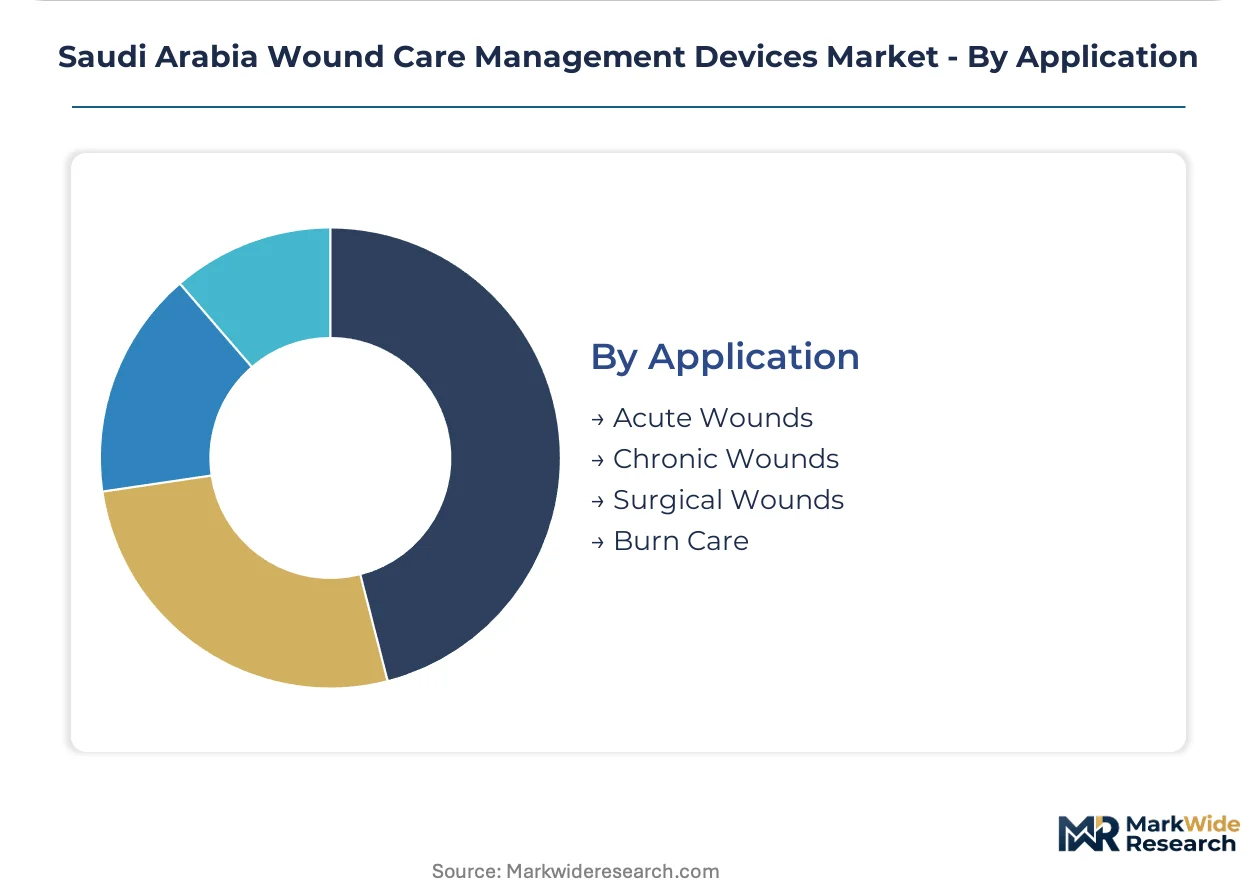
Application:
Wound etiology shapes substrate selection, with surgical and diabetic foot cases commanding premium antimicrobial deployment versus standard foam for uncomplicated acute wounds.
- Acute Wounds:Traumatic injuries and minor surgical incisions require rapid epithelialization support. Standard hydrocolloid and transparent film dressings satisfy most cases, limiting margin expansion opportunity.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries demand sustained antimicrobial protection and exudate management. The Saudi National Diabetes Center's protocols are expanding early intervention across Asir and Tabuk regions.
- Surgical Wounds:Post-operative incision care spans clean closures to contaminated dehiscence cases. Negative pressure wound therapy systems face intensive scrutiny under SFDA's evolving post-market surveillance protocols.
- Burn Care:Thermal and chemical injuries require specialized silver-infused and alginate dressings for exudate control and infection prevention. Dedicated burn centers in the Eastern Province and Asir region anchor concentrated demand.
Surgical wounds sit at the top of the volume ranking, with chronic wounds expanding most quickly as diabetes prevalence and screening intensity rise across the Kingdom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping wound care supply chains as manufacturers migrate final assembly toward jurisdictions offering streamlined medical device registration and localization incentives. The Kingdom's SFDA pathways now compress import timelines relative to European notified body backlogs, attracting sterilization and packaging investment.
Riyadh
King Faisal Specialist Hospital and Research Centre anchors tertiary demand for advanced negative pressure wound therapy and antimicrobial dressings. The Ministry of Health's Nupco procurement platform centralizes purchasing across public facilities, consolidating supplier relationships toward manufacturers demonstrating reduced healing metrics. King Saud Medical City and specialized diabetes centers drive concentrated consumption of silver-infused substrates.
Eastern Province
Dedicated burn centers in Dammam and Al-Khobar generate specialized demand for alginate and silver-infused dressings managing complex thermal injuries. SFDA's alignment with Gulf Standardization Organization technical requirements enables streamlined market access for European wound care suppliers targeting this cluster. The region's petrochemical infrastructure supports emerging local polymer substrate development.
Jeddah
Private hospital groups in this Western Region hub aggressively pursue direct manufacturer relationships to secure inventory guarantees and clinical training support. Home care transition initiatives under the Health Sector Transformation Program expand patient-managed dressing kits with telemedicine integration. International Medical Center and private specialty clinics anchor premium-tier demand.
Asir Region
The Saudi National Diabetes Center's screening protocols are expanding early-intervention wound care into primary care clinics across Abha and surrounding provinces. Hydrocolloid formats dominate home care transitions here given patient self-application feasibility. Mountain terrain complicates logistics, favoring suppliers with established distributor networks.
NEOM Northwest
The giga-project's healthcare infrastructure planning incorporates smart dressing substrates and digital wound assessment tools aligned with telemedicine architecture. SFDA's emerging local content requirements could reshape tender access for multinational suppliers establishing sterilization capabilities within this zone. Regulatory sandbox provisions may accelerate novel substrate trials.
Saudi Arabia Wound Care Management Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue localization partnerships and home care service integration. Market structure concentrates around multinational medical device conglomerates with Gulf registration experience, while specialized distributors displace general traders in tender participation. Three archetypes dominate: technology licensors with proprietary substrate patents, regional distributors with clinical training capabilities, and sterilization service providers enabling local content compliance. Competitive moves center on strategic partnerships with Saudi polymer suppliers and portfolio diversification into patient-managed care formats.
Among multinational wound care specialists, ConvaTec Inc., Molnlycke Health Care, and Smith and Nephew exemplify distinct positioning archetypes. ConvaTec represents hydrocolloid technology leadership sustaining premium hospital tender positioning. Molnlycke anchors presence through specialized burn care and surgical wound portfolios. Smith and Nephew occupies the advanced therapy systems tier with negative pressure wound therapy deployment across tertiary centers. These three entities illustrate how substrate specialization, clinical application focus, and technology platform breadth segment competitive access under SFDA registration frameworks.
| Leading Market Players |
|---|
| ConvaTec Inc. |
| Coloplast Ltd |
| Johnson and Johnson |
| B. Braun SE |
| Molnlycke Health Care |
| 3M Company |
| Medtronic Plc |
| Solventum |
| Smith and Nephew |
| Others |
Value Network & Pricing Analysis
SFDA's evolving local content requirements and Gulf Standardization Organization alignment are gating qualified supply access while stratifying premium-tier pricing for antimicrobial substrates and negative pressure wound therapy systems. These regulatory milestones compress import timelines for compliant manufacturers while excluding non-qualifying suppliers from Ministry of Health tenders.
Pricing Analysis
Distributor margins in the 15-25% range separate Nupco-aggregated public hospital procurement from direct manufacturer relationships pursued by Jeddah's private hospital cluster. Three-tier pricing structure across premium silver-infused substrates, standard foam dressings, and economy hydrocolloid formats reflects certification grade and clinical outcome documentation. Pricing pressure stems from Council of Health Insurance reimbursement compression on advanced antimicrobial dressings. Public hospital procurement committees exhibit highest price sensitivity, while tertiary burn centers demonstrate lowest sensitivity given clinical protocol rigidity.
Supply Chain Analysis
CE marking and SFDA Class II registration requirements gate market entry for European and Asian wound care manufacturers seeking Gulf Cooperation Council access. Raw material supply chains draw from German polymer suppliers for hydrocolloid substrates, Swedish manufacturers for foam matrices, and Japanese producers for alginate fibers. Single-source vulnerability concentrates in silver-ion antimicrobial additive supply anchored to specialty chemical producers. Distribution runs through Nupco's centralized platform for public sector facilities and specialized clinical distributors serving private hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's accelerated review pathways for Class II medical devices compound market access advantages for early registrants, amplifying returns on regulatory investment across the projection horizon.
For Market Incumbents: Lock in tender positioning by deepening backward integration into Saudi-based sterilization and final assembly operations under Made in Saudi localization incentives. Secure multi-year inventory guarantees with King Faisal Specialist Hospital and Research Centre to defend against emerging regional distributors displacing general medical device traders. Prioritize certification investment in Gulf Standardization Organization technical documentation to maintain streamlined Bahrain, Kuwait, and UAE market access.
For New Entrants and Emerging Players: SFDA's emerging local content requirements in Saudi Arabia open a window for sterilization service providers and packaging specialists to capture preferential tender access without full substrate manufacturing investment. Target home care transition services in Asir and Tabuk regions where mountain terrain complicates logistics and established distributor networks remain thin. Pursue direct relationships with private hospital groups in Jeddah bypassing Nupco aggregation to secure technical training contracts alongside product supply.
For Investors and Strategic Acquirers: Roll-up economics work for specialized clinical distributors with SFDA registration capabilities and hospital training infrastructure because Ministry of Health procurement centralization is fragmenting supplier relationships and displacing general traders. The 5-10 year viability window favors platforms consolidating Gulf registration expertise and telemedicine-integrated dressing kit capabilities. Watch for inflection in diabetic foot screening protocol penetration across primary care clinics as signal for antimicrobial substrate demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Class II Registration Acceleration | Compresses import timelines for novel foam and alginate substrates against European notified body backlogs. |
| Made in Saudi Sterilization Partnership | Unlocks preferential Nupco tender access through local content compliance without full manufacturing investment. |
| Telemedicine-Integrated Home Care Kits | Captures Ministry of Health hospital-at-home initiative demand with patient-managed hydrocolloid formats. |
| Burn Center Clinical Training Contracts | Secures long-term alginate and silver-infused dressing commitments in Eastern Province specialized facilities. |
| Gulf Cooperation Council Registration Harmonization | Leverages SFDA alignment with GSO requirements for streamlined Bahrain, Kuwait, and UAE market entry. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, SFDA regulatory affairs specialists, and specialized wound care distributors grounded qualitative findings in operational reality. Secondary validation drew from SFDA medical device registration databases, Ministry of Health procurement disclosures, Gulf Standardization Organization technical standards, and hospital supply chain records. Bottom-up demand modeling across dressing substrate categories triangulated against top-down healthcare expenditure projections from national transformation program documentation.
Top-down macroeconomic framing anchored aggregate market sizing, while bottom-up segmentation analysis disaggregated volume across hydrocolloid, foam, alginate, and silver-infused technology tiers. The analytical framework modeled end-user splits between tertiary hospitals, primary care clinics, home care transitions, and long-term care facilities alongside application categories spanning acute, chronic, surgical, and burn indications. CAGRs were derived from regression analysis of historical procurement velocity against Health Sector Transformation Program spending targets and diabetic foot prevention program rollout intensity.
Revisions become necessary when SFDA local content requirements materialize ahead of schedule, Council of Health Insurance reimbursement schedules shift substantially, or NEOM healthcare infrastructure deployment accelerates novel substrate trial opportunities. A model refresh is warranted upon material change in Ministry of Health value-based procurement weighting for reduced healing time metrics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Collagen Dressings Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Surgical Wound Care Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Wound Closure Market
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Wound Closure Strips Market
Wound Care
Wound Care Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Global Burn Care Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Middle East and Africa Advanced Wound Care Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Wound Evacuators Market