
 Acute Wound Care Market | 2026-2036
Acute Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Wound Care Market Intelligence
Modular dressing kits is shifting how hospital purchasing committees evaluate acute wound care suppliers, bundling foam dressings with fixation accessories into single SKUs that reduce nursing labor. Smith & Nephew leverages its negative pressure wound therapy platform to anchor premium hospital contracts across North America. Medtronic competes through its broad surgical portfolio, extending acute wound offerings into integrated operating room workflows. Mölnlycke Health Care specializes in silicone-adhesive foam technology, dominating European procurement tenders where MDR compliance documentation carries heavy scoring weight.
Acute wound care encompasses sterile dressings, closure devices, and active healing technologies designed to manage traumatic injuries, surgical incisions, and burns through moisture balance, infection prevention, and granulation tissue promotion. Foam dressings with superabsorbent polymer cores manage moderate-to-heavy exudate while maintaining periwound skin integrity during the inflammatory phase. Wet dressings and hydrogels represent mature, high-volume segments where price compression limits margin expansion, whereas negative pressure wound therapy and biologics command premium positioning due to clinical evidence requirements and specialized training needs. Alginate dressings derived from brown seaweed extract occupy a mid-tier niche in heavily exuding wounds, particularly within hospital burn centers where rapid hemostasis matters.
FDA 510(k) pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for acute wound care manufacturers. Health Technology Assessment bodies in Germany and France increasingly demand randomized trial evidence before granting premium reimbursement codes for novel dressing categories. Stakeholders must monitor how antimicrobial resistance surveillance data from CDC and ECDC influences future claims substantiation requirements for silver-impregnated and iodine-based dressings.
Market Dynamics
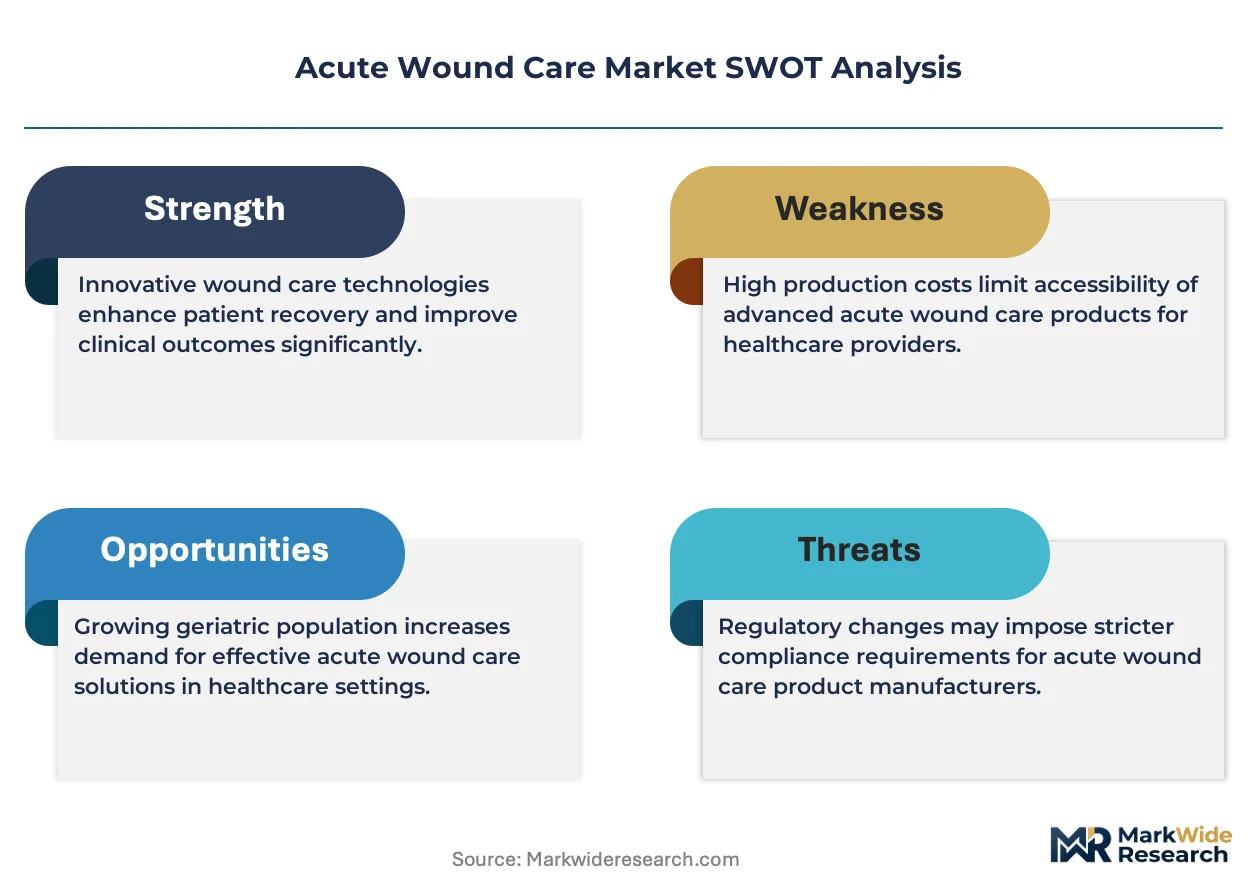
Hospital procurement committees now weight EU MDR technical documentation scores above unit price in tender evaluations, compressing vendor qualification timelines and favoring manufacturers with captive regulatory affairs capacity.
Growth Catalysts
- EU MDR recertification mandates:Germany's Health Technology Assessment body now requires randomized trial evidence for premium reimbursement codes, accelerating clinical investment among dressing manufacturers seeking favorable G-DRG positioning.
- Superabsorbent polymer foam cores:These materials manage moderate-to-heavy exudate while preserving periwound skin integrity, driving replacement demand in surgical wards managing post-operative drainage.
- Surgical volume recovery:Operating room throughput normalization across tertiary hospitals in the United States and Japan is expanding advanced dressing budgets as elective procedure backlogs clear.
Market Restraints
- Silver and iodine raw material volatility:Antimicrobial agent supply concentration in Chinese chemical processing clusters exposes manufacturers to input cost swings and export license unpredictability.
- Wet dressing commoditization:Hydrogel and basic gauze segments face price compression from private-label hospital contracts, limiting margin expansion even as volumes stabilize.
- FDA 510(k) evidentiary inflation:Substantial equivalence determinations now demand larger comparator studies for antimicrobial claims, extending premarket timelines by eight to fourteen months.
Strategic Opportunities
- Negative pressure wound therapy in outpatient settings:Home health agencies in the United States seek portable NPWT devices as CMS reimbursement shifts toward site-neutral payment models.
- Silicone-adhesive foam convergence:Combination products merging gentle adhesion with superabsorbent layers address fragile skin populations in geriatric and burn care applications.
- Japan's PMDA Sakigake designation:Fast-track approval pathways for regenerative medicine products create regulatory tailwinds for biologic dressing developers targeting chronic wound extensions.
Industry Challenges
- EU MDR notified body capacity:Technical documentation review queues at designated conformity assessment bodies extend recertification timelines, threatening market access continuity for legacy product lines.
- Specialized wound care nursing shortage:Negative pressure therapy and advanced biologic application require certified clinician training; hospital staffing gaps limit adoption velocity in community settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Wound Care Market |
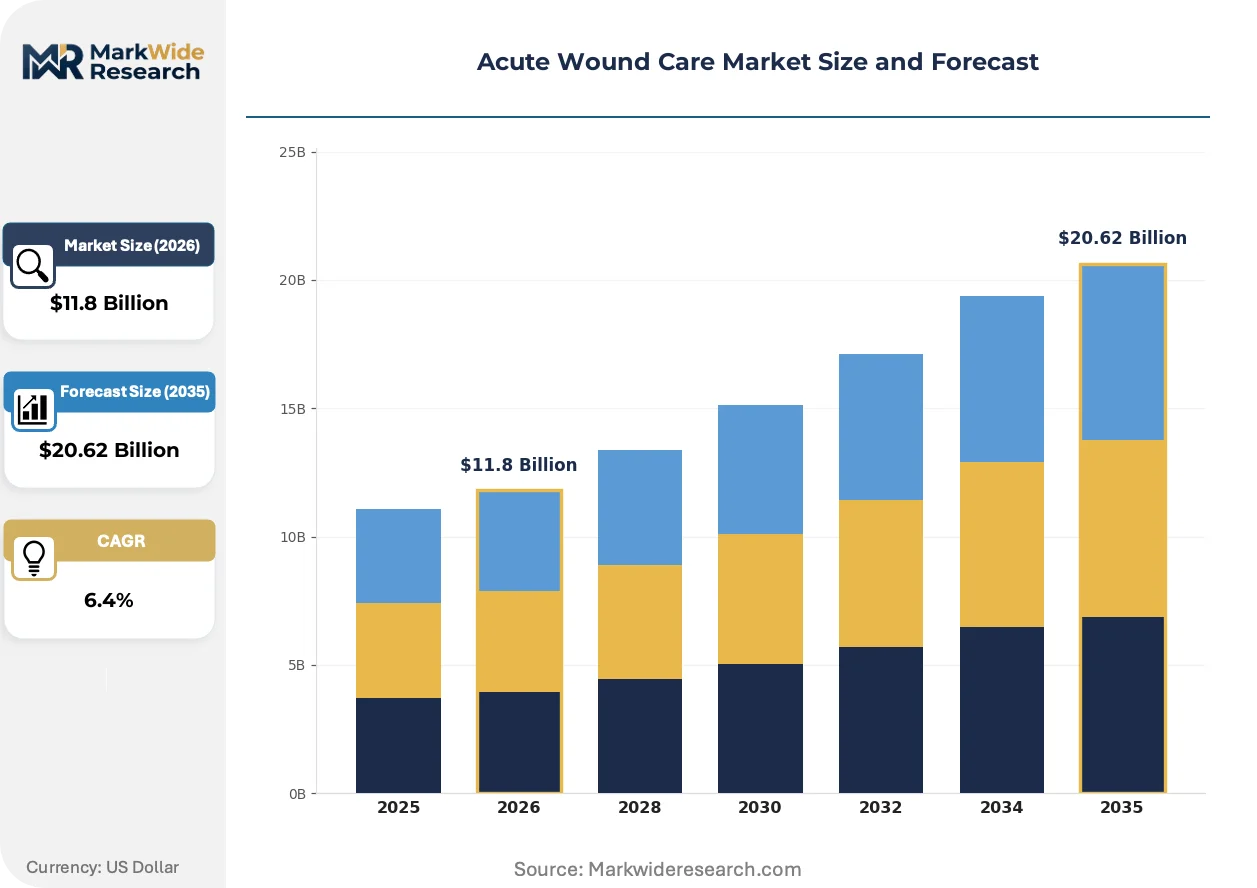
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Dressings, Hydrogels, Alginate Dressings, Foam Dressings End User: Hospitals, Home Care, Ambulatory Surgical Centers, Long-term Care Facilities Application: Trauma, Surgical, Burns, Diabetic Ulcers Technology: Advanced Dressings, Negative Pressure Wound Therapy, Electrical Stimulation Devices, Biologics |
| Companies Covered | ConvaTec, Medtronic, Smith & Nephew, Baxter International, Medline Industries, Mölnlycke Health Care, Coloplast, Integra LifeSciences, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Wound Care Market Strategic Shifts & Innovations
Modular dressing kits are restructuring how supply chain managers configure acute wound portfolios, bundling fixation accessories and foam layers into single-SKU offerings that reduce nursing labor and inventory complexity.
Antimicrobial dressings impregnated with ionic silver are overtaking traditional iodine-based alternatives in hospital burn centers and surgical wards. These products provide sustained bacterial load reduction without cytotoxicity concerns. Burn unit directors in Germany and the United States are standardizing silver foam protocols for partial-thickness injuries. The shift is compressing iodine dressing volumes while elevating price floors for advanced antimicrobial categories.
EU MDR Article 117 imposes stricter quality management system audits on manufacturers of sterile wound care devices. Notified bodies now evaluate clinical evaluation reports against state-of-the-art benchmarks rather than predecessor device comparisons. Small and mid-size suppliers with legacy technical files face disproportionate documentation burdens, accelerating consolidation among European contract manufacturers.
Hospital value analysis committees now mandate total cost-of-care evidence before approving premium dressing conversions. These committees compare nursing time, change frequency, and complication rates against acquisition price. Integrated delivery networks in the United States increasingly source through committed volume agreements that lock in multi-year supply relationships in exchange for utilization guarantees.
Acute Wound Care Market Segmentation
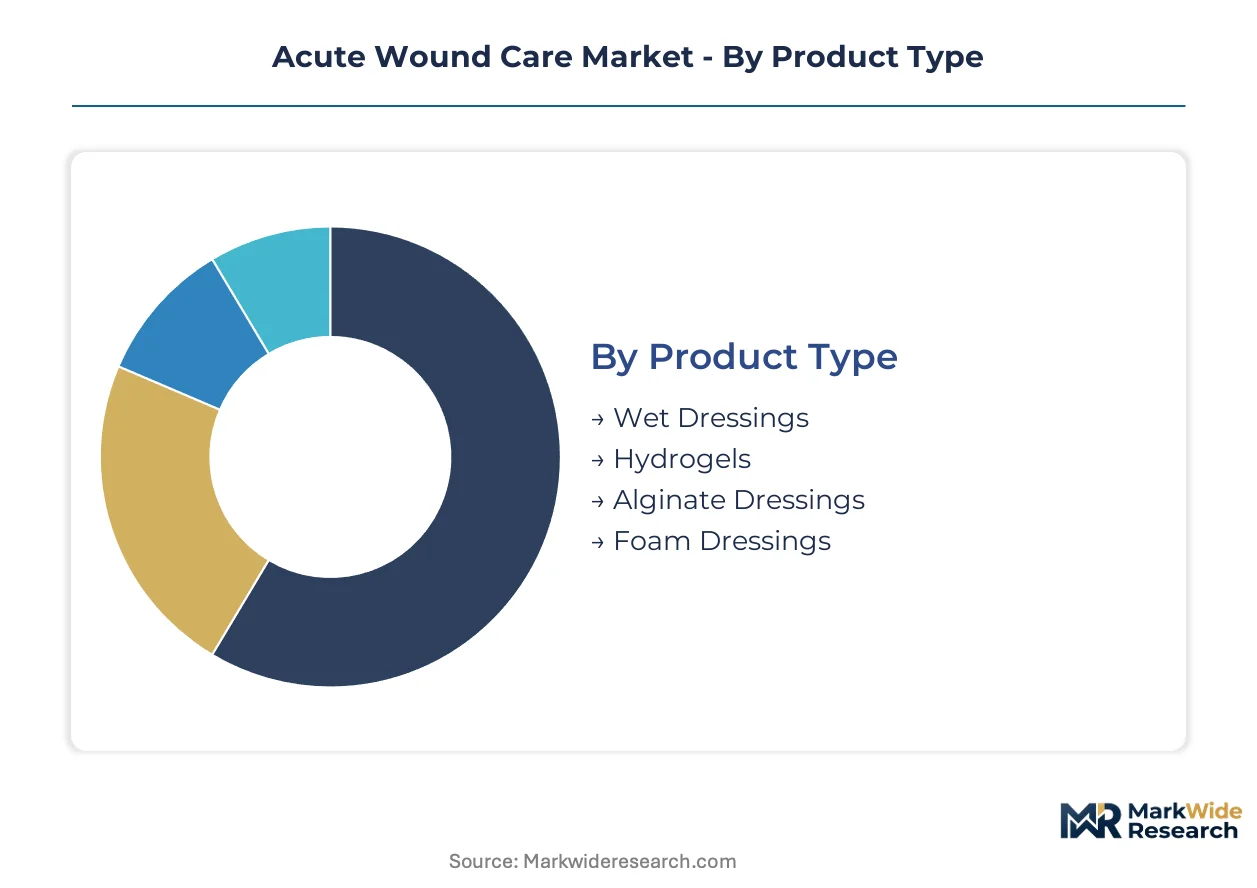
Acute wound care procurement committees evaluate suppliers through four intersecting lenses: material composition determines reimbursement tiers, care setting dictates training requirements, wound etiology shapes clinical protocols, and technology intensity defines margin profiles. Understanding how these axes combine explains why hospital value analysis committees weight total cost-of-care evidence above unit price.
Product Type:
Material science specifications differentiate segments by exudate management capacity and periwound skin interaction.
- Foam Dressings:Superabsorbent polymer cores manage moderate-to-heavy exudate while preserving periwound skin integrity during the inflammatory phase. Surgical wards in the United States and Germany drive replacement demand as post-operative drainage protocols standardize on silicone-adhesive foam convergence products.
- Alginate Dressings:Derived from brown seaweed extract, these dressings occupy a mid-tier niche in heavily exuding wounds. Hospital burn centers across Japan and the United States prioritize rapid hemostasis capabilities where alginate fiber-gelling action controls bleeding in partial-thickness injuries.
- Wet Dressings:Basic gauze and saline-moistened products face price compression from private-label hospital contracts despite stable procedural volumes.
- Hydrogels:Water-based amorphous gels provide moisture donation to dry necrotic wounds with limited margin expansion potential.
Mature deployment sits with wet dressings. Newer deployment is concentrated in foam dressings.
End User:
Care setting infrastructure determines reimbursement pathways and product complexity requirements.
- Hospitals:Tertiary facilities anchor demand for negative pressure wound therapy and advanced biologics where certified clinician training programs support technology adoption. Operating room throughput normalization across the United States and Japan expands advanced dressing budgets as elective procedure backlogs clear.
- Home Care:Portable negative pressure devices gain traction as CMS reimbursement shifts toward site-neutral payment models in the United States.
- Ambulatory Surgical Centers:Same-day discharge protocols favor modular dressing kits that reduce nursing labor.
- Long-term Care Facilities:Geriatric skin fragility drives silicone-adhesive foam specifications where gentle removal prevents mechanical damage.
Hospital procurement dominates volume concentration. Home care represents the steepest expansion trajectory.
Application:
Wound etiology dictates moisture balance requirements and antimicrobial intervention intensity.
- Surgical:Incision management protocols standardize on antimicrobial foam dressings for post-operative infection prevention. FDA 510(k) evidentiary inflation for antimicrobial claims extends premarket timelines by eight to fourteen months, compressing product development cycles.
- Burns:Partial-thickness thermal injuries drive silver-impregnated foam adoption in German and United States burn centers where sustained bacterial load reduction without cytotoxicity concerns matters.
- Trauma:Acute traumatic wounds require rapid hemostasis and exudate control in emergency department settings.
- Diabetic Ulcers:Chronic wound extensions into acute care settings leverage biologic dressing technologies.
Surgical applications anchor procurement volume. Burns command the highest technology intensity.
Technology:
Innovation intensity stratifies segments by clinical evidence requirements and specialized training needs.
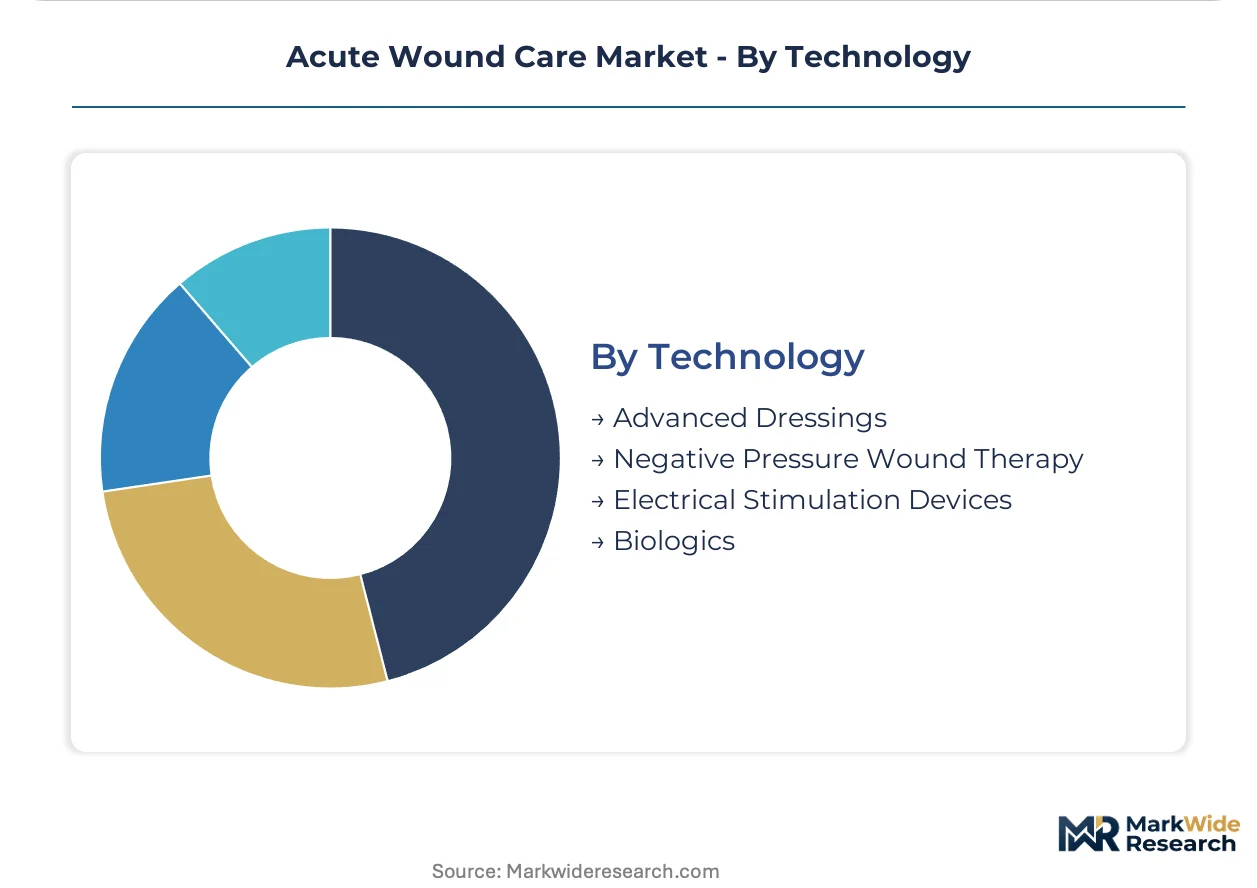
- Negative Pressure Wound Therapy:Portable systems address outpatient migration while hospital contracts anchor premium positioning. EU MDR recertification mandates compress vendor qualification timelines, favoring manufacturers with captive regulatory affairs capacity.
- Biologics:Regenerative medicine products target chronic wound extensions with Japan's PMDA Sakigake designation creating regulatory tailwinds for developers.
- Advanced Dressings:Superabsorbent and antimicrobial layers represent the revenue core where Health Technology Assessment bodies demand randomized trial evidence.
- Electrical Stimulation Devices:Adjunct therapy systems require specialized clinician training that limits adoption velocity in community settings.
Advanced dressings dominate current deployment. Negative pressure wound therapy is gaining share fastest in outpatient channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shanghai and Shenzhen concentrate wound care manufacturing capacity for Asia-Pacific export markets. Special economic zones in Ireland and the Netherlands anchor European distribution hubs serving EU MDR-compliant supply chains.
United States
Hospital value analysis committees in Cleveland Clinic and Mayo Clinic networks drive standardization on silicone-adhesive foam protocols. CMS site-neutral payment reforms accelerate portable negative pressure wound therapy adoption in home health settings. Manufacturing clusters in Minnesota and Massachusetts supply advanced dressing materials to integrated delivery networks.
Germany
Health Technology Assessment bodies in Berlin and Cologne mandate randomized trial evidence for premium G-DRG reimbursement codes. EU MDR notified body capacity constraints in Munich and Hamburg compress vendor qualification timelines for legacy product recertification. Baden-Württemberg medical device clusters specialize in superabsorbent polymer core production.
Japan
PMDA Sakigake fast-track designation attracts biologic dressing developers targeting regenerative medicine extensions. Tokyo and Osaka tertiary hospitals anchor demand for antimicrobial foam in post-operative infection prevention. Chubu region chemical processors supply alginate raw materials derived from regional seaweed cultivation.
United Kingdom
NHS supply chain consolidation in England favors modular dressing kit suppliers reducing nursing labor costs. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment pathways for sterile wound devices. Medical technology corridors in Cambridge and Oxford host advanced dressing R&D facilities.
China
NMPA priority review channels accelerate antimicrobial dressing approvals for hospital procurement tenders. Yangtze River Delta chemical clusters supply silver and iodine antimicrobial agents to domestic manufacturers. Shanghai free trade zone warehousing supports just-in-time delivery to Asia-Pacific hospital networks.
Acute Wound Care Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across acute wound care procurement channels. The vendor base stratifies into three tiers: multinational medical technology groups with integrated operating room workflows, mid-size dressing specialists with captive regulatory affairs capacity, and regional contract manufacturers serving private-label hospital contracts. Dominant competitive moves include EU MDR technical documentation investments compressing vendor qualification timelines and strategic partnerships anchoring multi-year committed volume agreements with integrated delivery networks.
Within the diversified medical technology tier, Medtronic and 3M occupy positions exemplifying broad surgical portfolio leverage. Smith & Nephew represents the focused wound care specialist archetype with negative pressure wound therapy platform anchoring. These three companies illustrate how regulatory scale and clinical evidence capacity separate premium-tier positioning from commodity dressing suppliers.
| Leading Market Players |
|---|
| ConvaTec |
| Medtronic |
| Smith & Nephew |
| Baxter International |
| Medline Industries |
| Mölnlycke Health Care |
| Coloplast |
| Integra LifeSciences |
| 3M |
| Others |
Cost & Logistics Intelligence
Hospital procurement committees in Germany and the United States now weight EU MDR technical documentation scores above unit price in tender evaluations, forcing suppliers to absorb compliance certification costs that compress margins on legacy wet dressing lines while creating pricing power for manufacturers with captive regulatory affairs capacity.
Pricing Analysis
Short lead-time premiums for silicone-adhesive foam dressings run 15-25 percent above contract pricing for scheduled deliveries, while spot inventory liquidations of hydrogel and basic gauze products trade at distressed levels. Three-tier pricing structure across premium antimicrobial foam, standard superabsorbent polymer cores, and economy wet dressing categories tracks certification grade and clinical evidence depth. Price erosion runs through mature hydrogel segments as private-label hospital contracts displace branded suppliers. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge protocols; tertiary burn centers show lowest sensitivity where clinical outcomes data anchors purchasing decisions.
Supply Chain Analysis
Reverse logistics flows for negative pressure wound therapy devices concentrate refurbishment and remanufacturing operations in Minnesota and Massachusetts manufacturing clusters, extending asset life cycles for hospital rental fleets. Raw material supply draws from Chinese chemical processing clusters for silver and iodine antimicrobial agents, German superabsorbent polymer core production, and Japanese alginate fiber extraction from regional seaweed cultivation. Single-source vulnerability in Chinese antimicrobial agent supply exposes manufacturers to export license unpredictability. Distribution runs through integrated delivery network committed volume agreements in the United States and EU MDR-compliant distribution hubs in Ireland and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification mandates function as a cost-of-compliance barrier-to-entry moat, concentrating procurement access among manufacturers with technical documentation capacity while marginalizing mid-size suppliers dependent on European contract manufacturers.
For Market Incumbents: Anchor premium hospital contracts through multi-year committed volume agreements that lock in utilization guarantees against emerging pure-play specialists. Deepen backward integration into superabsorbent polymer core production to defend margin position against raw material volatility from Chinese chemical clusters. Prioritize captive regulatory affairs capacity to compress vendor qualification timelines as notified body review queues extend. For New Entrants and Emerging Players: Capture portable negative pressure wound therapy demand in United States home health agencies where CMS site-neutral payment reforms create reimbursement parity with hospital settings. Target silicone-adhesive foam convergence products for geriatric long-term care facilities where skin fragility specifications remain underpenetrated. Pursue GPO contract access through modular dressing kit offerings that reduce nursing labor costs for supply chain managers. For Investors and Strategic Acquirers: The window for entry favors mid-size dressing specialists with EU MDR technical documentation already filed and captive manufacturing in Baden-Württemberg or Minnesota clusters. Acquisition candidates with randomized trial evidence for Health Technology Assessment submissions command premium positioning in German G-DRG reimbursement negotiations. Monitor antimicrobial resistance surveillance data from CDC and ECDC as inflection indicator for silver-impregnated dressing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body certification compresses vendor qualification timelines for hospital tenders. |
| Hospital System Partnership | Mayo Clinic and Cleveland Clinic networks standardize silicone-adhesive foam protocols. |
| Backward Integration into Polymer Production | Baden-Württemberg clusters anchor superabsorbent core supply for margin defense. |
| Reimbursement Strategy | G-DRG premium codes require randomized trial evidence from German HTA bodies. |
| Software Companion Development | Portable NPWT devices integrate patient monitoring for home health agency adoption. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement tender records, and CMS reimbursement code updates, complemented by interviews with hospital purchasing committee directors, wound care nursing specialists, biomedical engineers, GPO contracts managers, and regulatory affairs leads at dressing manufacturers. Secondary validation drew from hospital supply chain databases, antimicrobial resistance surveillance reports, and Health Technology Assessment body publications. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, application, and technology intensity dimensions.
Cross-reference between historical surgical volume recovery patterns and expert panel input on procurement budget allocation shaped the analytical framework across the projection horizon. Segmentation modeling captured material composition specifications, care setting infrastructure requirements, wound etiology protocols, and technology intensity tiers. CAGRs derived from procedure volume trajectories, reimbursement pathway evolution, and product replacement cycle dynamics in surgical wards and burn centers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity constraints, antimicrobial raw material export license volatility, and CMS site-neutral payment model implementation pace. Practitioners should monitor CDC and ECDC resistance surveillance data, German G-DRG code revisions, and Japanese PMDA Sakigake designation awards for early signals of segment inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Europe Compression Bandages Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Moist Wound Dressings Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
US Wound Irrigation System Market
Wound Care
Chronic Wound Care Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
US Wound Care Centers Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Wound Measurement Devices Market