
 Global Compression Bandages Market | 2026-2036
Global Compression Bandages Market Size, Share, and Industry Trends Forecast 2026-2036
Global Compression Bandages Market Foresight
European textile manufacturers is hardening output standards for medical-grade elastic fabrics. Essity leverages its vertically integrated fiber-to-bandage production across Germany and Sweden. Paul Hartmann AG anchors its position through specialized lymphedema therapy portfolios. Smith & Nephew competes in the premium compression segment with advanced silicone-adhesive technologies.
Compression bandages are woven or knitted textile devices engineered to deliver calibrated pressure measured in millimeters of mercury for therapeutic vascular support. Elastic bandages dominate hospital procurement due to standardized mmHg ratings and reusable sterilization compatibility. The application landscape tilts toward venous ulcer management where reimbursement codes favor evidence-backed compression protocols. Home healthcare channels represent the fastest-growing distribution vector as remote wound monitoring platforms expand patient self-management capabilities.
FDA 510(k) clearances and EU MDR conformity assessments shape product entry timelines for manufacturers targeting transatlantic distribution. The EU Green Deal textile sustainability mandates and REACH chemical restrictions are forcing material substitutions in adhesive coatings and synthetic yarns. Stakeholders must monitor evolving pressure-classification harmonization between ISO 13485 quality systems and national wound care guidelines.
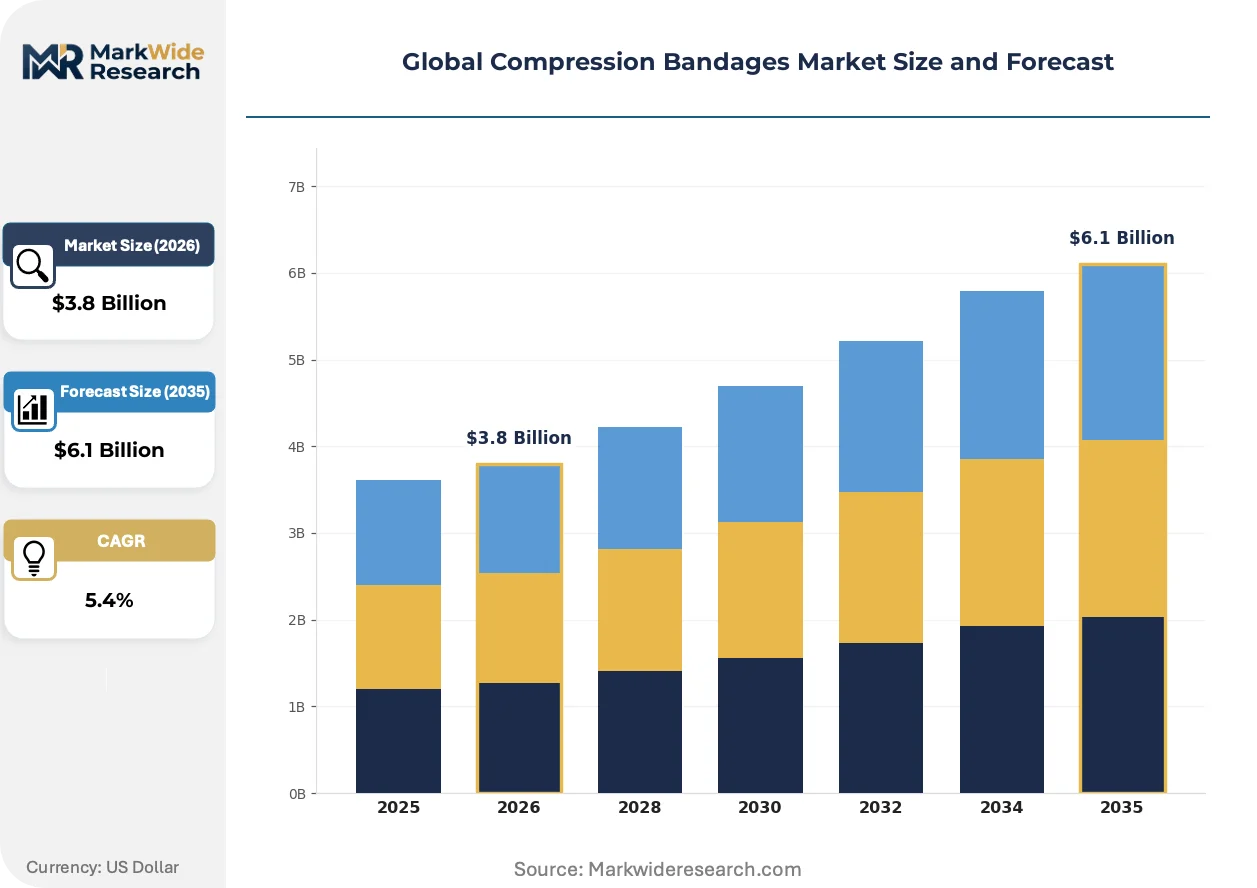
Market Dynamics
EU MDR conformity assessments are compressing product entry timelines while REACH chemical restrictions force material substitutions in adhesive coatings and synthetic yarns, reshaping competitive positioning across transatlantic distribution networks.
Growth Catalysts
- Post-surgical care protocols:Hospital settings in Germany and Sweden are embedding calibrated mmHg-rated bandages into standardized venous ulcer management pathways, with reimbursement codes favoring evidence-backed compression therapies.
- EU Green Deal textile mandates:Sustainability requirements for medical-grade elastic fabrics are accelerating R&D investment in biodegradable yarns and solvent-free adhesive systems among European textile manufacturers.
- Remote wound monitoring platforms:Home healthcare channels are expanding patient self-management capabilities through integrated pressure-sensing bandages that transmit compliance data to clinical dashboards.
Market Restraints
- Synthetic yarn cost volatility:Petroleum-derived elastane prices fluctuate with crude oil indices, squeezing margin structures for manufacturers dependent on imported polymer feedstocks.
- Supply concentration in German wound care clusters:Advanced weaving and knitting capabilities for medical-grade elastic fabrics concentrate in Baden-Württemberg and Bavaria, creating geographic vulnerability to regional logistics disruptions.
- Silicone-adhesive technical limitations:Premium compression segments face skin adhesion failures in high-moisture wound environments, limiting application scope for silicone-coated variants.
Strategic Opportunities
- Underpenetrated Indian home healthcare:Urban centers in Maharashtra and Karnataka lack standardized compression therapy distribution, presenting white space for mmHg-classified product introductions aligned with CDSCO device registration pathways.
- CE-MDR regulatory tailwind:Tightened classification standards for wound care devices create barrier-to-entry advantages for manufacturers with established ISO 13485 quality systems and notified body relationships.
- Digital health convergence:Integration of pressure-sensing textiles with Bluetooth-enabled patient monitoring apps enables subscription-based remote care models for lymphedema therapy.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing sequences for new adhesive coatings extend product development cycles by 18-24 months, delaying revenue recognition for reformulated portfolios.
- Specialized weaving technician scarcity:Medical-grade elastic fabric production requires operators trained on Karl Mayer raschel machines, with skill pipelines constricted by aging workforce demographics in European textile regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Compression Bandages Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Bandages, Cohesive Bandages, Non-Elastic Bandages, Compression Wraps, Tubular Bandages Application: Venous Ulcers, Lymphedema, Deep Vein Thrombosis, Sports Injuries, Post-Surgical Care End User: Hospitals, Specialized Clinics, Rehabilitation Centers, Home Healthcare, Nursing Facilities Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Essity (BSN Medical), Paul Hartmann AG, Smith & Nephew, 3M Company, Medi GmbH & Co. KG, Sigvaris Group, ConvaTec Group plc, Arjo, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Compression Bandages Market Shifts & Advancements
Silicone-adhesive technologies are consolidating market structure while regulatory chemistry restrictions and home-based care models simultaneously reshape material selection and distribution architecture across the value chain.
Smart compression textiles with integrated pressure sensors are consolidating control over therapy compliance monitoring. Hospital procurement teams in Germany and the Netherlands are adopting these systems for venous ulcer protocols. The technology is consolidating accountability for treatment outcomes into device manufacturers, compressing traditional distinctions between product and service revenue streams.
REACH chemical restrictions on isocyanate-based adhesives are forcing material substitutions across European manufacturing footprints. Manufacturers are reformulating pressure-sensitive coatings to maintain skin adhesion without restricted chemical classes. Wound care device segments with direct patient contact face the steepest compliance costs and shortest reformulation timelines.
Hospital-at-home reimbursement expansions are fragmenting traditional institutional procurement concentration. German statutory health insurers are reimbursing domiciliary compression therapy at parity with inpatient protocols. Home healthcare agencies in North Rhine-Westphalia and Bavaria are building inventory positions for patient-managed mmHg-rated bandage systems.
Global Compression Bandages Market Segmentation
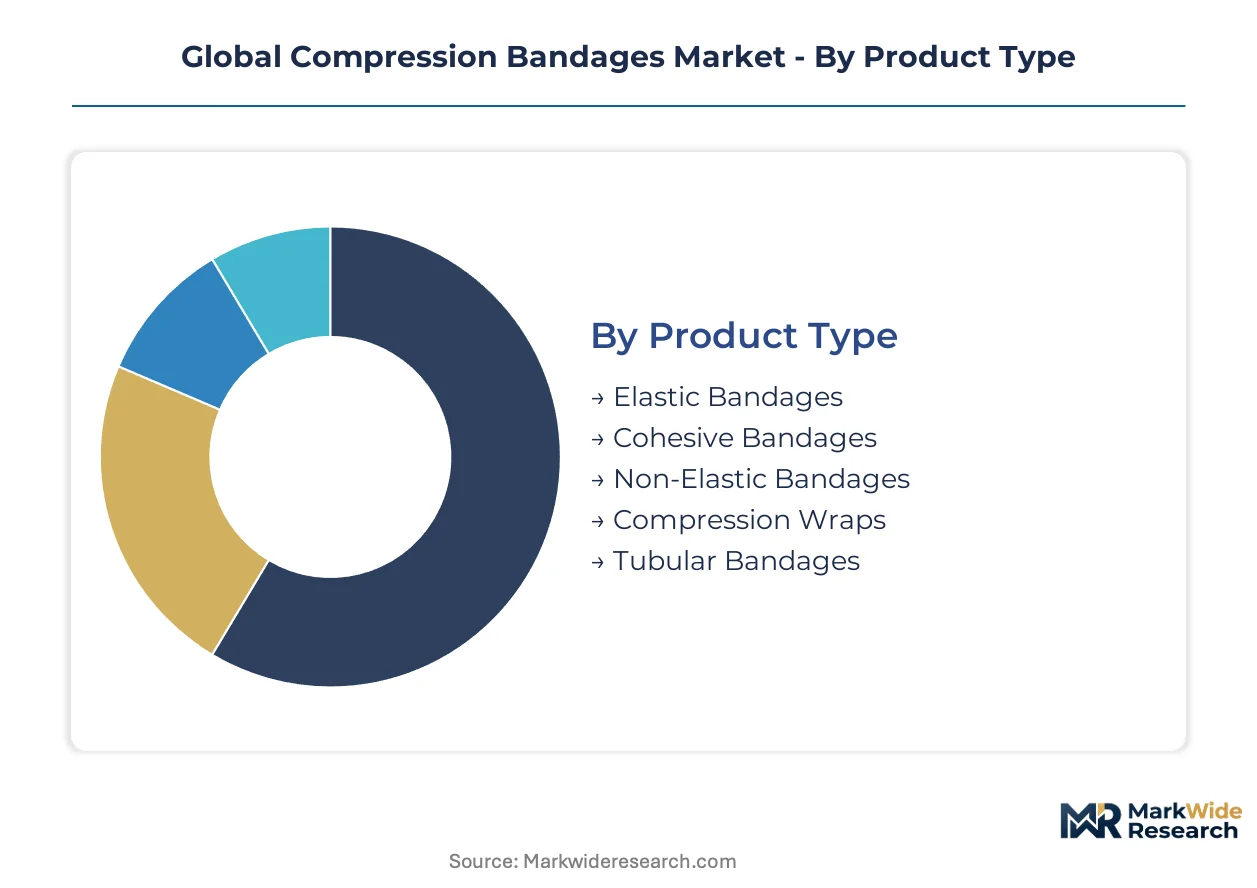
Compression bandage manufacturers configure product portfolios around pressure calibration standards, reimbursement code alignment, and sterilization compatibility requirements. Segmentation strategy determines margin capture across institutional procurement and patient-managed care channels.
Product Type:
Supply concentration for medical-grade elastic fabrics tilts procurement leverage toward manufacturers with captive weaving operations in Germany and Sweden.
- Elastic Bandages:Knitted textile structures with calibrated mmHg ratings dominate hospital procurement due to reusable sterilization protocols. Demand concentrates in German venous ulcer management pathways where statutory insurers reimburse evidence-backed compression therapies.
- Cohesive Bandages:Self-adhering synthetic wraps bond to themselves without clips or fasteners, enabling rapid application in emergency and sports medicine settings. French and Italian hospital networks embed these into trauma stabilization protocols where application speed determines clinical workflow efficiency.
- Non-Elastic Bandages:Rigid cotton or linen constructions deliver fixed compression for acute edema control.
- Compression Wraps:Velcro-fastened adjustable systems accommodate limb volume fluctuations during lymphedema treatment.
- Tubular Bandages:Seamless knit sleeves simplify application for geriatric and self-managed care scenarios.
Today's leader: Elastic Bandages. Tomorrow's challenger: Cohesive Bandages.
Application:
Cost tier stratification separates premium silicone-adhesive systems from standard elastic constructions across reimbursement categories.
- Venous Ulcers:Chronic lower-extremity wounds drive the largest addressable patient population for mmHg-calibrated compression therapy. German statutory health insurance reimbursement codes favor graduated compression protocols, anchoring volume concentration in Baden-Württemberg and Bavaria hospital networks.
- Lymphedema:Long-term limb volume management requires durable, washable bandage systems with sustained elastic recovery. Swedish and Dutch home healthcare agencies are building inventory positions for patient-managed therapy as domiciliary reimbursement expands.
- Deep Vein Thrombosis:Acute prophylaxis and post-thrombotic syndrome management utilize fixed-compression gradients.
- Sports Injuries:Athletic training rooms and physiotherapy clinics prioritize cohesive and elastic variants for acute sprain management.
- Post-Surgical Care:Orthopedic and vascular surgery discharge protocols increasingly specify take-home compression systems.
Venous Ulcers command current volume concentration. Lymphedema is climbing the fastest as home-based reimbursement parity spreads across EU member states.
End User:
Customer type fragmentation is accelerating as hospital-at-home reimbursement models displace traditional institutional procurement concentration.
- Hospitals:Centralized procurement teams in Germany and the Netherlands specify ISO 13485-certified bandages with validated mmHg ratings. Standardized venous ulcer protocols embed compression therapy into clinical pathways with outcome accountability shifting toward device manufacturers.
- Home Healthcare:Patient-managed care models are expanding fastest as remote monitoring platforms integrate pressure-sensing textiles. Maharashtra and Karnataka urban centers in India present white space for mmHg-classified product introductions aligned with CDSCO registration pathways.
- Specialized Clinics:Lymphedema therapy centers and wound care clinics drive premium segment adoption.
- Rehabilitation Centers:Post-acute recovery facilities prioritize reusable elastic systems for cost efficiency.
- Nursing Facilities:Long-term care operators balance staff application time against product durability requirements.
Today's anchor: Hospitals. Tomorrow's expansion vector: Home Healthcare.
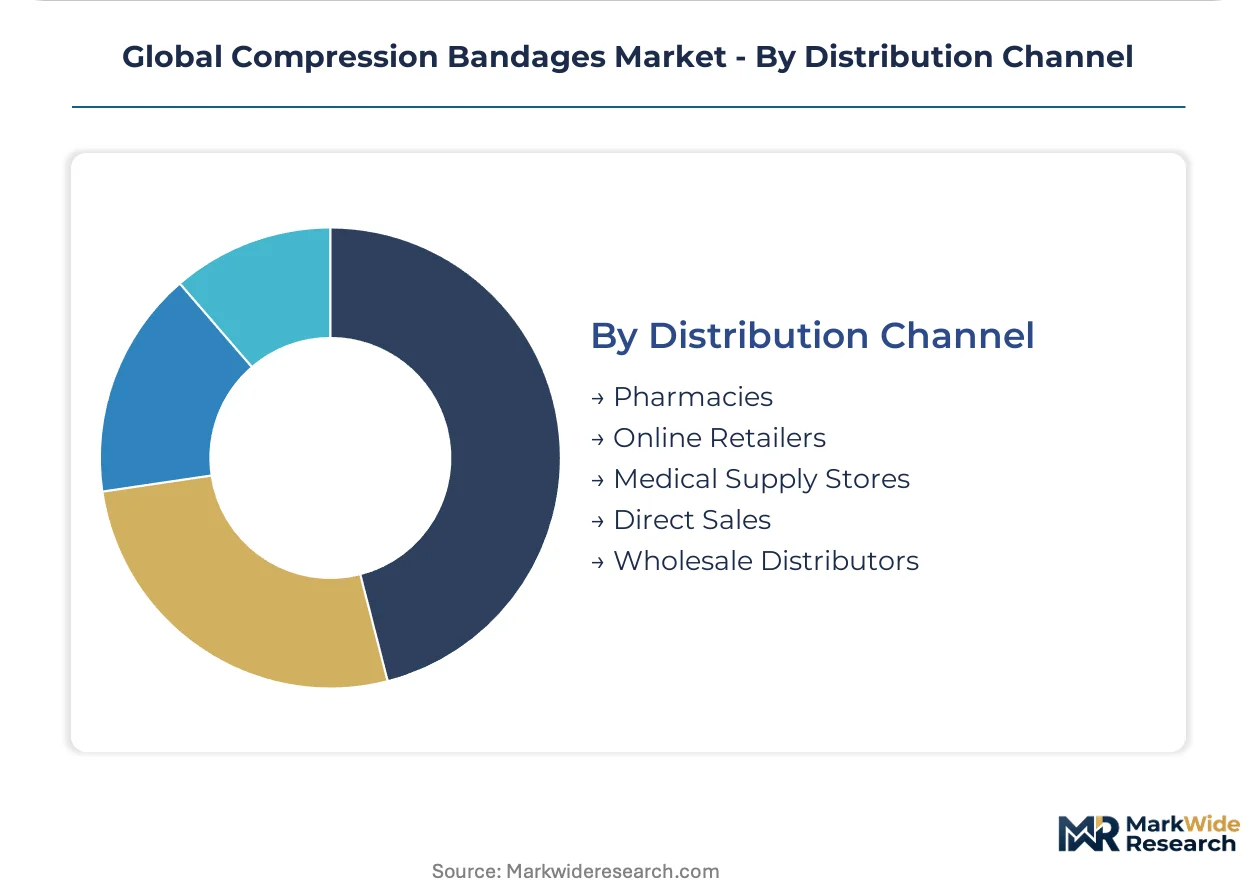
Distribution Channel:
Margin structures vary sharply across channel tiers, with direct sales capturing premium pricing and wholesale distributors handling volume commoditized segments.
- Pharmacies:Community and hospital outpatient dispensaries serve as the primary patient access point for reimbursed compression therapy. German statutory insurance contracts concentrate volume through appointed pharmacy networks in North Rhine-Westphalia.
- Online Retailers:E-commerce platforms are gaining share fastest for self-pay compression garments and sports medicine applications. Patient education content and mmHg specification transparency drive conversion in direct-to-consumer channels.
- Medical Supply Stores:Specialized durable medical equipment dealers serve home healthcare agency procurement.
- Direct Sales:Manufacturer field forces target large hospital systems and specialized clinic networks.
- Wholesale Distributors:Broadline medical distributors aggregate demand from smaller institutional accounts.
Pharmacies dominate reimbursed volume. Online Retailers are gaining share fastest in self-pay and sports medicine segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate toward jurisdictions with streamlined medical device pathways and lower compliance-cost burdens. Germany and Sweden retain captive weaving advantages, while India and the United States present contrasting entry-cost profiles for new capacity deployment.
Germany
Statutory health insurance reimbursement codes favor graduated compression protocols for venous ulcer management. EU MDR conformity assessments compress product entry timelines while REACH chemical restrictions force adhesive coating reformulations. The Baden-Württemberg and Bavaria clusters concentrate advanced Karl Mayer raschel weaving capabilities for medical-grade elastic fabrics.
Sweden
Home healthcare agencies are building inventory positions for patient-managed lymphedema therapy as domiciliary reimbursement expands to parity with inpatient protocols. The EU Green Deal textile sustainability mandates accelerate R&D investment in biodegradable yarns among Nordic textile manufacturers. Vertically integrated fiber-to-bandage production operations anchor industrial capacity in Stockholm and Gothenburg regions.
United States
FDA 510(k) clearance pathways shape transatlantic distribution strategies for manufacturers targeting hospital procurement networks. Post-surgical care protocols increasingly specify take-home compression systems for orthopedic and vascular surgery discharge pathways. The Southeast and Midwest regions concentrate durable medical equipment distribution infrastructure for home healthcare channel expansion.
India
Urban centers in Maharashtra and Karnataka lack standardized compression therapy distribution, presenting white space for mmHg-classified product introductions. CDSCO device registration pathways govern market entry for imported wound care devices. Mumbai and Bangalore clusters are emerging as logistics hubs for medical textile distribution across South Asian markets.
Netherlands
Hospital procurement teams specify ISO 13485-certified bandages with validated mmHg ratings for venous ulcer clinical pathways. Dutch home healthcare agencies are adopting remote wound monitoring platforms that integrate pressure-sensing textiles. The Randstad region concentrates specialized lymphedema therapy centers and wound care clinic networks.
Global Compression Bandages Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital health convergence and smart textile integration. The vendor base stratifies across three maturity tiers: legacy medical textile conglomerates with captive weaving operations, mid-scale specialists focused on lymphedema and sports medicine niches, and technology-enabled challengers embedding sensor platforms into compression systems. Dominant competitive moves include backward integration into medical-grade elastic fabric production and strategic partnerships with remote patient monitoring platform developers.
Within the vertically integrated tier, Essity and Paul Hartmann AG exemplify archetypes of fiber-to-bandage production control. Smith & Nephew occupies a position representing premium silicone-adhesive technology specialization. These three anchors illustrate contrasting strategic postures: Nordic supply-chain control, German therapeutic portfolio depth, and British advanced materials positioning.
| Leading Market Players |
|---|
| Essity (BSN Medical) |
| Paul Hartmann AG |
| Smith & Nephew |
| 3M Company |
| Medi GmbH & Co. KG |
| Sigvaris Group |
| ConvaTec Group plc |
| Arjo |
| Cardinal Health |
| Others |
Supply & Pricing Matrix
EU Green Deal textile sustainability mandates gate qualified supply for medical-grade elastic fabrics while anchoring premium-tier pricing access to manufacturers with certified biodegradable yarn portfolios and solvent-free adhesive systems. Hospital procurement teams in Germany and the Netherlands pay measurable premiums for REACH-compliant bandages with validated mmHg ratings, compressing margin structures for uncertified competitors.
Pricing Analysis
Distributor margin layers absorb 15-25 points before pharmacy retail markup, with direct-to-hospital contracts commanding volume discounts that offset service bundling costs. Three-tier pricing structure across premium silicone-adhesive, standard elastic, and economy cohesive levels separates reimbursement-eligible venous ulcer protocols from self-pay sports medicine applications. Cost compression in economy tiers intensifies because petroleum-derived elastane prices track crude oil volatility. Home healthcare agencies exhibit highest price sensitivity; specialized lymphedema therapy centers demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from German hospital procurement teams mandate qualified suppliers in both Baden-Württemberg and Sweden to mitigate geographic concentration risk. Medical-grade elastic fabric production draws from Germany, Sweden, and emerging capacity in India for tubular bandage assembly. Karl Mayer raschel machine operators represent a critical bottleneck; aging workforce demographics in European textile regions threaten output expansion. REACH chemical restrictions on isocyanate-based adhesives create regulatory chokepoint exposure. Distribution runs through appointed pharmacy networks in statutory insurance systems and direct sales for large hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Compression Bandages Market functions as a stable compounder anchored by irreversible demographic shifts toward aging populations requiring chronic wound management and post-surgical vascular support.
For Market Incumbents: Hedge against REACH-driven material cost inflation by locking multi-year supply contracts for biodegradable yarn feedstocks. Deepen backward integration into captive Karl Mayer weaving capacity in Germany or Sweden to defend margin position against emerging Indian competitors. Prioritize ISO 13485 certification maintenance as EU MDR tightens conformity assessment timelines for wound care device reclassification. For New Entrants and Emerging Players: E-commerce direct-to-patient channels offer the lowest barrier to entry for mmHg-classified compression wraps in Indian urban centers lacking standardized distribution. Target Maharashtra and Karnataka home healthcare agencies with Bluetooth-enabled pressure-sensing bandages that transmit compliance data to clinical dashboards. Pursue CDSCO device registration pathways for imported wound care devices to establish regulatory foothold before incumbent localization. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale lymphedema therapy specialists because domiciliary reimbursement parity across EU member states creates predictable revenue visibility for patient-managed care platforms. Five-to-ten year viability hinges on digital health convergence capabilities rather than commodity elastic production. Watch for FDA 510(k) clearance acceleration for pressure-sensing textiles as inflection signal for smart compression segment consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Conformity Acceleration | EU MDR tightened classification standards compress entry timelines for wound care devices with direct patient contact. |
| Biodegradable Yarn R&D Partnership | EU Green Deal mandates force material substitutions that favor manufacturers with Nordic textile R&D relationships. |
| Remote Monitoring Platform Integration | Bluetooth-enabled pressure-sensing bandages enable subscription-based revenue models for lymphedema therapy compliance. |
| Indian Distribution Infrastructure Buildout | Maharashtra and Karnataka logistics hubs anchor South Asian market entry for mmHg-classified product introductions. |
| Karl Mayer Operator Training Pipeline | Medical-grade elastic fabric production requires specialized raschel machine skills constricted by aging European workforce demographics. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down medical-grade elastic fabric production tracking forms the analytical core of this study. Primary interviews with clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers cross-validated against secondary sources including FDA 510(k) filings, EU MDR notified body databases, German statutory health insurance reimbursement codes, and CDSCO device registration records. Trade data from European textile machinery associations and Karl Mayer production statistics anchored supply-side calibration.
Input-output matrices mapped mmHg-rated bandage unit demand by application segment against Karl Mayer raschel machine installed capacity across Germany, Sweden, and emerging Indian textile clusters. Segmentation dimensions modeled include product type, application, end user, and distribution channel with geographic regulatory cluster overlays. CAGRs were derived from trend extrapolation of reimbursement code expansions and hospital-at-home protocol adoptions. Forecast inputs incorporated REACH chemical restriction implementation timelines and EU Green Deal textile sustainability mandate compliance costs.
The model assumes a particular technology adoption path for pressure-sensing smart textiles; alternative pathways for silicone-adhesive durability breakthroughs would alter the outlook for premium segment capture. Deviation in EU MDR notified body capacity or CDSCO registration processing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Moist Wound Dressings Market
Wound Care
Australia Wound Care Management Devices Market
Wound Care
Wound Skin Care Market
Wound Care
Dental Wound Dressings Market
Wound Care
South Korea Wound Care Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Burn Care Centers Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Wound Care Market
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Europe Compression Bandages Market
Wound Care
Wound Healing Supplement Market
Wound Care
North America Wound Care Management Market