
 Animal Wound Care Market | 2026-2036
Animal Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Wound Care Market Intelligence
Subscription-based replenishment programs for chronic wound dressings is hardening into a recurring revenue layer that reshapes vendor-buyer relationships. Zoetis Inc. leverages its veterinary distribution network to lock in clinic-level contracts across North America. B. Braun SE anchors its position through sterile manufacturing scale that supports bulk institutional procurement. Dechra Pharmaceuticals specializes in species-specific formulations that differentiate its portfolio from commoditized alternatives.
Animal wound care encompasses medical devices and pharmaceutical products designed to protect, debride, moisturize, and accelerate healing of traumatic or surgical lesions in livestock, companion animals, and exotic species. Collagen dressings derived from bovine or porcine sources provide a scaffold for cellular migration and granulation tissue formation in full-thickness wounds. Antimicrobial dressings dominate current volume due to their broad applicability across bite wounds and contaminated abrasions where infection risk is elevated. Hydrocolloid variants represent the fastest-expanding category as small-animal practitioners adopt moisture-retentive therapy for pressure ulcers and surgical incisions in geriatric pets.
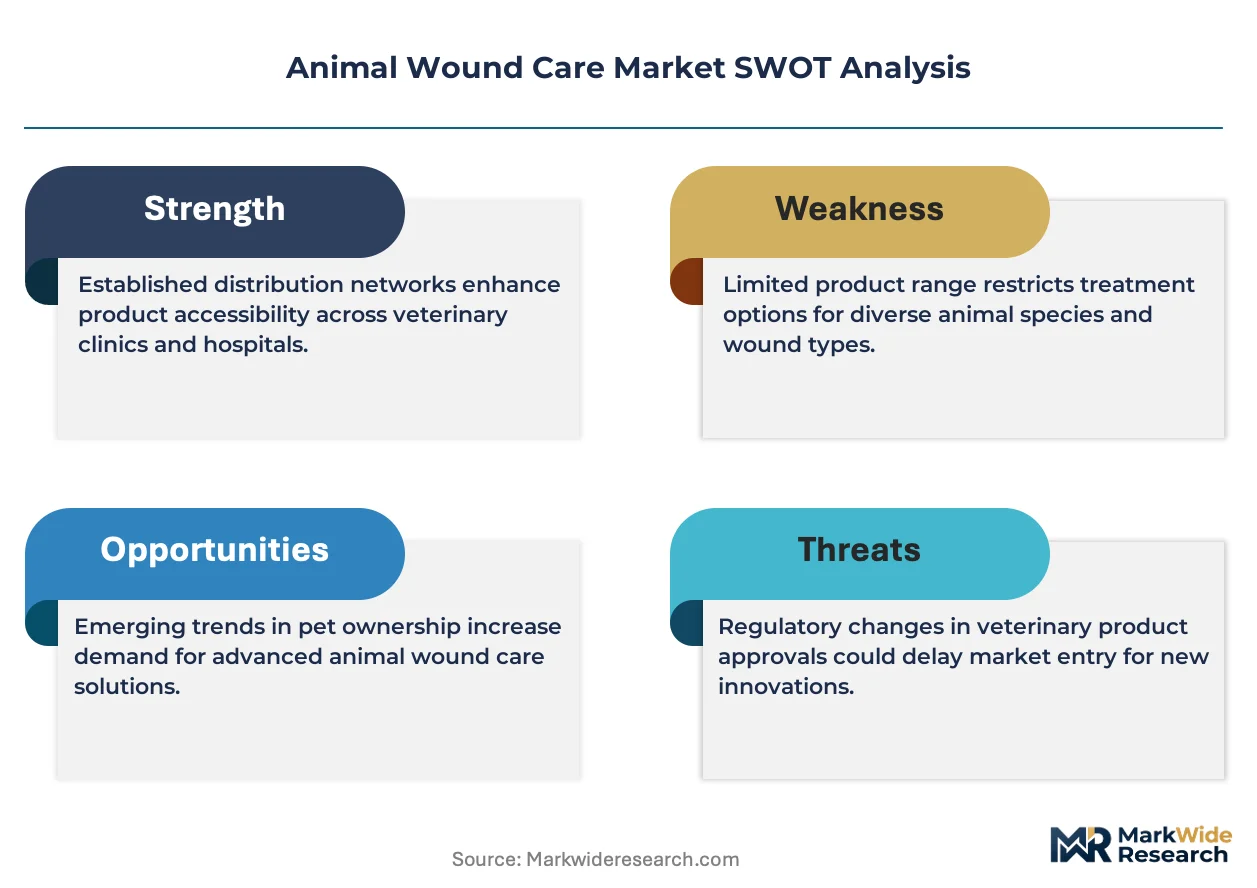
The FDA Center for Veterinary Medicine and the USDA regulate topical wound care products differently based on whether claims imply drug action or device function, creating compliance complexity for cross-border suppliers. The EU Veterinary Medicines Regulation and MDR frameworks are converging on stricter biocompatibility documentation for collagen and silver-impregnated dressings sold into European veterinary channels. Stakeholders must monitor how regulatory divergence between US and European classification schemes affects product registration timelines and market access costs.
Market Dynamics
Veterinary clinics are consolidating procurement decisions under centralized buying groups, compressing vendor margins while elevating technical specifications for advanced wound dressings. This buyer-side concentration is forcing manufacturers to restructure their commercial organizations around account-based selling rather than territory coverage.
Growth Catalysts
- EU MDR biocompatibility mandates:Stricter documentation requirements for collagen and silver-impregnated dressings are filtering out marginal suppliers and expanding addressable market share for compliant incumbents.
- Geriatric companion animal population:Extended lifespans among dogs and cats are elevating chronic wound caseloads in small-animal practices, driving recurring demand for moisture-retentive hydrocolloid therapies.
- Species-specific formulation pipelines:Targeted development for equine and exotic species is opening premium pricing tiers unavailable in commoditized canine-feline segments.
Market Restraints
- Bovine collagen supply concentration:Overreliance on North American and Brazilian abattoir sourcing creates vulnerability to herd health events and export restriction volatility.
- FDA-USDA classification ambiguity:Divergent jurisdiction over antimicrobial claims forces dual-track regulatory strategies that extend time-to-market by 18-36 months for novel actives.
- Silver resistance development:Widespread historical use of silver sulfadiazine in veterinary settings is reducing clinical efficacy and triggering formulary exclusions in academic referral hospitals.
Strategic Opportunities
- India companion animal segment:Underpenetrated metro veterinary infrastructure in Mumbai, Bangalore, and Delhi presents first-mover positioning for advanced dressing portfolios before local manufacturing scales.
- 3D-printed scaffold convergence:Integration of patient-specific wound geometry with bioactive ink deposition is converging with telemedicine triage workflows to enable remote specialist consultation.
- Subscription replenishment channels:Direct-to-clinic auto-replenishment platforms are capturing lifetime value through locked-in formulary status and reduced switching friction.
Industry Challenges
- Veterinary pharmaceutical salesforce retraining:Traditional antibiotic-detail representatives lack technical depth to position advanced wound bed preparation and moist wound healing protocols effectively.
- ISO 10993 biocompatibility testing backlog:Contract laboratory capacity constraints are extending certification timelines for novel collagen cross-linking chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Wound Care Market |
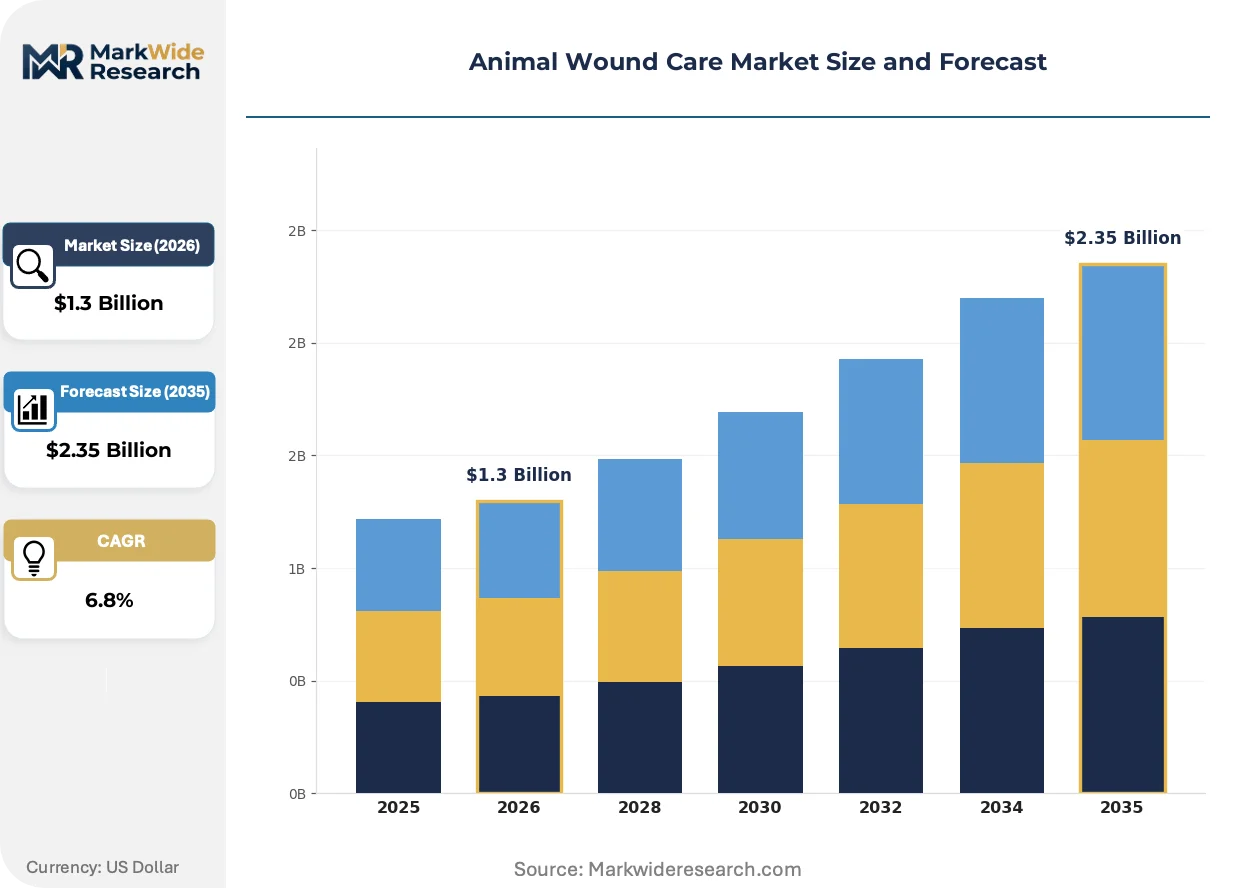
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bandages, Antimicrobial Dressings, Hydrocolloid Dressings, Collagen Dressings, Pain Relief Sprays Application: Post-Surgical Treatment, Burn Management, Abrasions, Chronic Ulcers, Bite Wound Care End User: Veterinary Clinics, Animal Shelters, Zoos, Research Institutions, Home Care Providers Distribution Channel: Veterinary Pharmacies, Online Retailers, Specialty Stores, Direct Sales, Veterinary Hospitals |
| Companies Covered | Virbac, Ethicon, Inc., 3M Company, Jorgen Kruuse A/S, Zoetis Inc., Medtronic Plc, Neogen Corporation, Dechra Pharmaceuticals, B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Wound Care Market Strategic Shifts & Innovations
Bioactive material science is migrating from human wound care into veterinary applications with accelerated regulatory pathways, while digital connectivity is embedding inventory management into clinical workflow software.
Electrospun nanofiber matrices loaded with sustained-release antimicrobials are converging with negative pressure wound therapy systems in equine referral hospitals. Large-animal practitioners at university teaching hospitals in the United States and Germany are adopting these combinations for distal limb wounds with exposed bone. The convergence is compressing healing timelines from weeks to days in complicated traumatic injuries, justifying premium reimbursement rates.
REACH authorization requirements for silver nanoparticles are forcing reformulation of legacy antimicrobial dressings sold into European veterinary channels. Manufacturers are substituting ionic silver with alternative metal oxides or plant-derived antimicrobial peptides to maintain market access. Small-animal product lines face the most acute compliance pressure due to higher volume exposure and tighter margin structures.
Consolidated buying groups are displacing independent distributor relationships in North American specialty and emergency practice networks. These organizations negotiate formulary exclusivity in exchange for volume commitments and data-sharing on clinical outcomes. The shift is most pronounced in corporate-owned clinic chains operating across multiple metropolitan markets.
Animal Wound Care Market Segmentation
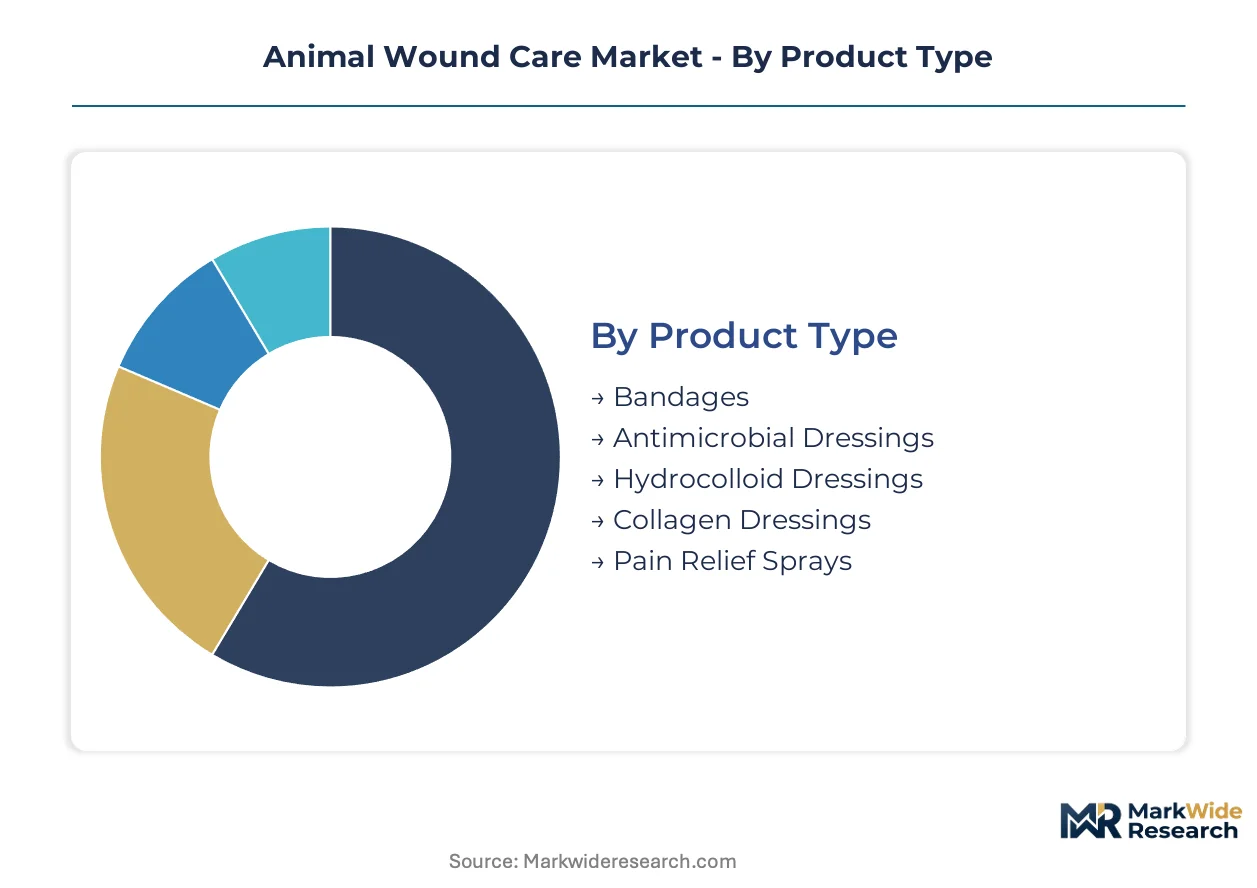
Product differentiation in animal wound care follows distinct clinical workflows across species and settings. Manufacturers align formulation complexity with end-user technical capability and reimbursement tiers.
Product Type:
Cost tier separates commodity buyers from premium adopters seeking bioactive performance.
- Antimicrobial Dressings:Silver-impregnated gauze and hydrogel matrices dominate bite wound protocols in companion animal emergency practices. Demand concentrates in US metropolitan specialty hospitals where infection control protocols drive formulary standardization amid rising methicillin-resistant staphylococcus cases.
- Hydrocolloid Dressings:Moisture-retentive polyurethane formulations accelerate epithelial migration in pressure ulcers and surgical incisions. German and French geriatric pet clinics are expanding procurement fastest as extended canine lifespans elevate chronic wound caseloads.
- Bandages:Elastic and adhesive wraps remain volume leaders for traumatic injury stabilization in field settings.
- Collagen Dressings:Bovine-derived scaffolds support granulation tissue formation in full-thickness wounds at university teaching hospitals.
- Pain Relief Sprays:Topical anesthetic formulations target minor abrasion management in home care and shelter environments.
Volume sits with antimicrobial variants; growth tilts toward hydrocolloid therapies.
Application:
Clinical setting determines whether products face institutional procurement or retail purchasing patterns.
- Post-Surgical Treatment:Suture line protection and incision management drive recurring demand across sterilized procedure volumes. North American corporate veterinary chains are consolidating purchasing for advanced dressings through centralized buying groups that negotiate exclusivity contracts.
- Bite Wound Care:Penetrating trauma with polymicrobial contamination requires aggressive antimicrobial intervention. Urban emergency practices in London and New York report elevated caseloads from dog-to-dog aggression incidents.
- Burn Management:Thermal and chemical injuries in livestock and companion animals demand specialized hydrogel protocols.
- Abrasions:Superficial wounds generate high-frequency, low-margin sales through retail channels.
- Chronic Ulcers:Geriatric companion animal diabetes and circulatory compromise sustain long-duration dressing regimens.
Post-surgical applications capture the largest revenue pool; bite wound protocols are expanding most quickly.
End User:
Technical sophistication gaps between institutional and retail buyers reshape packaging and support requirements.
- Veterinary Clinics:Small-animal practices represent the primary demand node for advanced dressings with documented outcomes. Australian and Canadian clinic networks are adopting subscription replenishment platforms to lock in formulary status.
- Research Institutions:Preclinical wound healing studies require standardized, lot-traceable collagen matrices. US National Institutes of Health-funded facilities drive premium pricing for GMP-certified materials.
- Animal Shelters:High-volume, cost-constrained operations prioritize generic bandaging supplies for intake trauma.
- Zoos:Exotic species anatomy necessitates custom sizing and species-specific formulation development.
- Home Care Providers:Pet owner direct purchasing favors over-the-counter sprays and adhesive strips.
Veterinary clinics anchor current volume; research institutions command the steepest expansion trajectory.
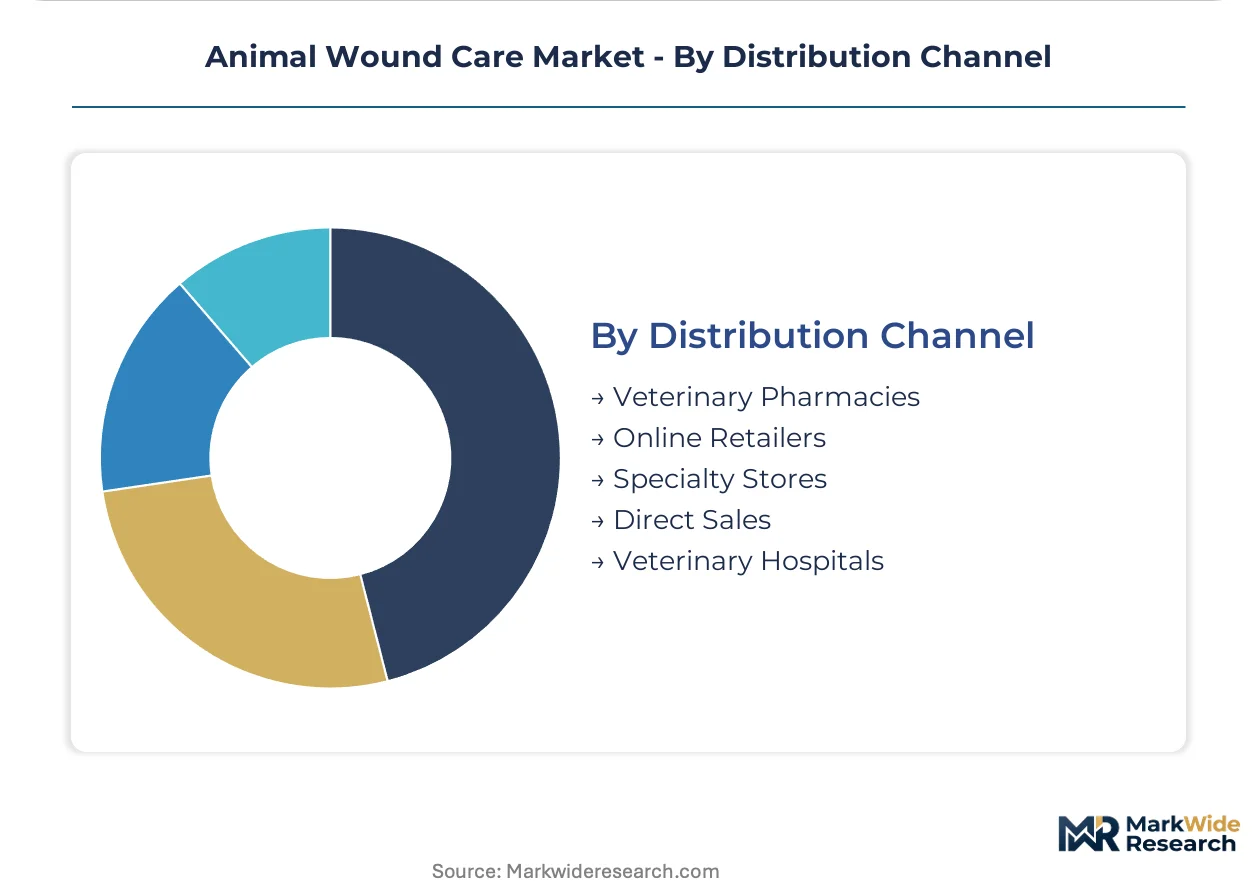
Distribution Channel:
Channel selection reflects buyer urgency, technical support needs, and inventory carrying cost tolerance.
- Veterinary Pharmacies:Clinic-adjacent dispensaries capture immediate-need prescriptions and emergency restocking. Brazilian and Mexican urban centers are expanding pharmacy networks to reduce distributor markup layers.
- Online Retailers:E-commerce platforms aggregate home care and shelter demand with competitive pricing transparency. Direct-to-consumer auto-replenishment is gaining traction for chronic wound management regimens.
- Direct Sales:Manufacturer field representatives service high-volume institutional accounts with technical training.
- Specialty Stores:Equine supply retailers target large-animal practitioners with wound care adjacent to nutrition and equipment.
- Veterinary Hospitals:Academic referral centers maintain captive inventory for complex trauma protocols.
Veterinary pharmacies retain the dominant share; online retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of collagen matrices and antimicrobial dressings concentrates in Germany and the United States, while consumption growth accelerates in companion animal clinics across India and Brazil. This geographic split creates supply chain complexity for vendors seeking to serve expanding veterinary markets.
United States
Corporate veterinary chains in Texas and California are consolidating procurement through centralized buying groups that negotiate formulary exclusivity for advanced dressings. The FDA Center for Veterinary Medicine maintains jurisdiction over antimicrobial claims, creating compliance hurdles for cross-border suppliers. University teaching hospitals in the Midwest anchor demand for bioactive scaffolds in equine trauma protocols.
Germany
Geriatric pet clinics in Bavaria and North Rhine-Westphalia are expanding hydrocolloid procurement as extended canine lifespans elevate chronic wound caseloads. The EU Medical Device Regulation mandates stricter biocompatibility documentation for collagen dressings sold into veterinary channels. Berlin-based research institutions drive premium pricing for GMP-certified matrices used in preclinical studies.
India
Metro veterinary infrastructure in Mumbai, Bangalore, and Delhi remains underpenetrated by advanced dressing portfolios, presenting first-mover positioning before local manufacturing scales. The Central Drugs Standard Control Organization regulates topical wound products entering companion animal clinics. Maharashtra's emerging pharmaceutical clusters are developing generic bandaging capacity for domestic shelter networks.
Brazil
Urban pharmacy networks in São Paulo and Rio de Janeiro are expanding to reduce distributor markup layers for emergency wound care restocking. ANVISA classification ambiguity for antimicrobial-device hybrids extends registration timelines for novel entrants. Southern livestock regions generate field dressing demand for traumatic injury stabilization in cattle operations.
United Kingdom
Urban emergency practices in London report elevated bite wound caseloads from dog-to-dog aggression incidents, driving silver-impregnated gauze consumption. The Veterinary Medicines Directorate aligns with EU MDR frameworks on biocompatibility standards for collagen imports. Southeast England's specialty referral hospitals are adopting subscription replenishment platforms for chronic ulcer management.
Animal Wound Care Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the animal wound care sector. Vertically integrated pharmaceutical conglomerates with captive manufacturing assets face pressure from specialized dressing developers outsourcing sterile production to contract manufacturers. Three archetypes dominate: diversified human-health giants extending veterinary divisions, pure-play animal health specialists, and regional fabricators serving local livestock markets. Competitive intensity centers on formulary lock-in through subscription replenishment contracts and sterile manufacturing scale sufficient to serve consolidated buying groups.
Within the diversified pharmaceutical tier, Zoetis Inc., B. Braun SE, and Dechra Pharmaceuticals exemplify contrasting strategic positions. Zoetis leverages its veterinary distribution network to anchor clinic-level contracts across North America. B. Braun SE occupies a position defined by sterile manufacturing scale supporting bulk institutional procurement. Dechra Pharmaceuticals sits within the species-specific formulation specialist archetype, differentiating through targeted development for equine and exotic segments unavailable to commoditized canine-feline competitors.
| Leading Market Players |
|---|
| Virbac |
| Ethicon, Inc. |
| 3M Company |
| Jorgen Kruuse A/S |
| Zoetis Inc. |
| Medtronic Plc |
| Neogen Corporation |
| Dechra Pharmaceuticals |
| B. Braun SE |
| Others |
Cost & Logistics Intelligence
Consolidated buying groups at North American corporate veterinary chains are compressing vendor margins and forcing a contract-based pricing model that rewards sterile manufacturing scale and formulary lock-in over product differentiation.
Pricing Analysis
Margin tightening in antimicrobial dressings reflects procurement concentration under centralized buying groups that negotiate volume-based rebates. Three-tier pricing structure across premium bioactive scaffolds, standard hydrocolloid formulations, and economy bandaging supplies separates university teaching hospitals from metropolitan specialty practices and cost-constrained shelter networks. Pricing pressure intensifies in silver-impregnated segments as REACH authorization requirements force costly reformulation. Home care providers exhibit highest price sensitivity, while research institutions tolerate premium positioning for GMP-certified collagen matrices.
Supply Chain Analysis
Dual-sourcing mandates from EU veterinary distributors are compelling manufacturers to qualify secondary abattoir suppliers for bovine collagen extraction. Manufacturing concentrates in Germany, the United States, and Brazil, with raw material dependencies on North American and Brazilian cattle herds, porcine tissue processors, and silver nanoparticle refiners. Single-source vulnerability in bovine collagen supply creates exposure to herd health events and export restriction volatility. Distribution runs through veterinary pharmacy networks in urban centers, supplemented by direct sales for institutional accounts and online retail for home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around sterile manufacturing scale and subscription replenishment platforms, with EU MDR biocompatibility mandates and FDA-USDA classification ambiguity forcing marginal suppliers toward exit.
For Market Incumbents: Extend formulary lock-in through auto-replenishment platform deployment at Australian and Canadian clinic networks before local competitors replicate the model. Invest in ISO 10993 biocompatibility certification capacity to capture share from suppliers facing contract laboratory backlogs. Anchor position through captive collagen cross-linking chemistry development that reduces dependence on Brazilian abattoir concentration. For New Entrants and Emerging Players: Exotic species practitioners at zoos and wildlife rehabilitation centers represent an underserved buyer archetype with custom sizing requirements that resist commoditization. Target metro veterinary infrastructure in Mumbai, Bangalore, and Delhi before domestic pharmaceutical clusters scale generic bandaging capacity. Pursue telemedicine-integrated 3D-printed scaffold partnerships as a go-to-market angle that bypasses traditional distribution markups. For Investors and Strategic Acquirers: The window for entry favors species-specific formulation specialists with equine and exotic pipelines that command premium tiers unavailable to canine-feline commoditized competitors. Position for five-to-ten year horizon viability by targeting developers with validated collagen sourcing relationships outside Brazil. Watch for ANVISA regulatory clarity on antimicrobial-device hybrids as the inflection signal for Brazilian market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Replenishment Platform Deployment | Captures lifetime value through locked-in formulary status at North American corporate chains. |
| EU MDR Biocompatibility Certification Investment | Filters out marginal suppliers and expands addressable share for compliant collagen dressing incumbents. |
| Species-Specific Formulation Pipeline Expansion | Opens premium pricing tiers in equine and exotic segments resistant to commoditization pressure. |
| Dual-Source Collagen Supply Qualification | Mitigates herd health event exposure and satisfies EU distributor sourcing mandates. |
| Telemedicine-Integrated 3D Scaffold Development | Converges with remote specialist consultation workflows at university teaching hospitals. |
Research Approach
Multi-period observation of veterinary clinic procurement patterns, antimicrobial resistance surveillance data, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with small-animal practice owners, GPO contracts managers, biomedical engineers at university teaching hospitals, and sterile manufacturing quality directors. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, EMA veterinary medicines registers, EU MDR technical documentation requirements, and customs trade data on collagen matrix imports. Bottom-up clinic-level demand modeling and top-down pharmaceutical revenue triangulation cross-validated segment estimates.
Input-output matrices mapped product type, application setting, end-user technical capability, and distribution channel throughput across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro veterinary service expenditure trends. Modeled inputs included geriatric companion animal population trajectories, silver resistance development rates at academic referral hospitals, and REACH authorization timelines for antimicrobial nanoparticles.
Revisions become necessary when EU MDR biocompatibility enforcement intensity shifts, FDA-USDA jurisdiction clarifications emerge, or Brazilian cattle herd health events disrupt collagen supply availability. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Management Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Belgium and Netherlands Advanced Wound Care Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Post-Operative Wound Treatment Market
Wound Care
North America Wound Care Management Market
Wound Care
Pressure Bandages Market
Wound Care
US Burn Care Centers Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Advanced Wound Dressings Market
Wound Care
US Wound Irrigation System Market
Wound Care
Collagen Dressings Market
Wound Care
Wound Retractor Market
Wound Care
Vascular Dressings Market