
 Bioactive Wound Care Market | 2026-2036
Bioactive Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Bioactive Wound Care Market Analysis
The gap between premium bioactive dressings and commodity wound coverings is pivoting on reimbursement validation and clinical evidence depth. Smith+Nephew leverages its orthobiologics heritage to sustain high-margin positions in skin substitutes. Organogenesis Inc. anchors its competitive stance through vertically controlled human cell-based manufacturing. Mölnlycke Health Care AB dominates European hospital procurement channels with broad dressing portfolios.
Bioactive wound care encompasses dressings and skin substitutes engineered with biologically active agents such as antimicrobial compounds, growth factors, or living cells to accelerate tissue regeneration and modulate the wound microenvironment. These products typically incorporate collagen matrices, hyaluronic acid, or silver-ion complexes and function primarily to reduce healing time, infection risk, and scar formation in acute and chronic lesions. Antimicrobial dressings command substantial margin pools due to rising hospital-acquired infection protocols, while alginate dressings compete intensely on raw material sourcing from brown seaweed suppliers. Chronic wounds represent the structurally dominant application segment, driven by diabetic foot ulcer and venous leg ulcer epidemiology, whereas phototherapy technology remains nascent with limited payer coverage.
The FDA regulates bioactive wound products through distinct pathways for devices, biologics, and combination products, creating compliance complexity that favors well-capitalized incumbents. The EMA's Medical Device Regulation and REACH chemical safety standards impose additional formulation and clinical testing burdens on European market participants. Stakeholders must monitor evolving regenerative medicine advanced therapy designations and parallel payer evidence requirements to anticipate which product categories will secure sustainable reimbursement.
Market Dynamics
Medicare reimbursement policy in the United States is accelerating hospital procurement of advanced dressings over standard wound coverings, compressing purchasing cycles and elevating clinical evidence requirements for market access.
Growth Catalysts
- Regenerative medicine guidance:The FDA's evolving framework on human cell-based products is streamlining trial pathways for skin substitutes, reducing time-to-market for qualified developers.
- Chronic wound epidemiology:Diabetic foot ulcer prevalence among aging populations in Germany and Japan is expanding addressable patient pools for bioactive interventions.
- Silver-ion complexes:Hospital-acquired infection protocols in acute care settings are mandating antimicrobial dressing integration into standard wound protocols.
Market Restraints
- Raw material concentration:Alginate supply chains depend on brown seaweed harvesting concentrated in Norwegian coastal waters, exposing processors to marine climate volatility.
- REACH compliance burden:The EMA's Medical Device Regulation imposes additive clinical testing requirements on European manufacturers of collagen-based dressings.
- Commodity substitution:Standard hydrocolloid dressings compete aggressively on unit economics in price-sensitive long-term care facilities.
Strategic Opportunities
- Phototherapy convergence:Light-activated wound healing platforms combining LED arrays with photosensitizing agents are opening reimbursement negotiations with private payers in Switzerland.
- Home care channel expansion:Direct-to-patient distribution models for chronic wound management are penetrating rural health systems in Australia bypassing traditional hospital procurement.
- Hyaluronic acid innovation:Cross-linked matrices engineered for sustained growth factor release are creating premium positioning in burn center protocols.
Industry Challenges
- Cell culture technician scarcity:Human cell-based manufacturing requires specialized bioprocessing expertise that outpaces vocational training output in established production regions.
- Combination product classification:Ambiguous FDA jurisdiction between device and biologic pathways for living cell dressings creates regulatory timeline uncertainty and capital planning friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioactive Wound Care Market |
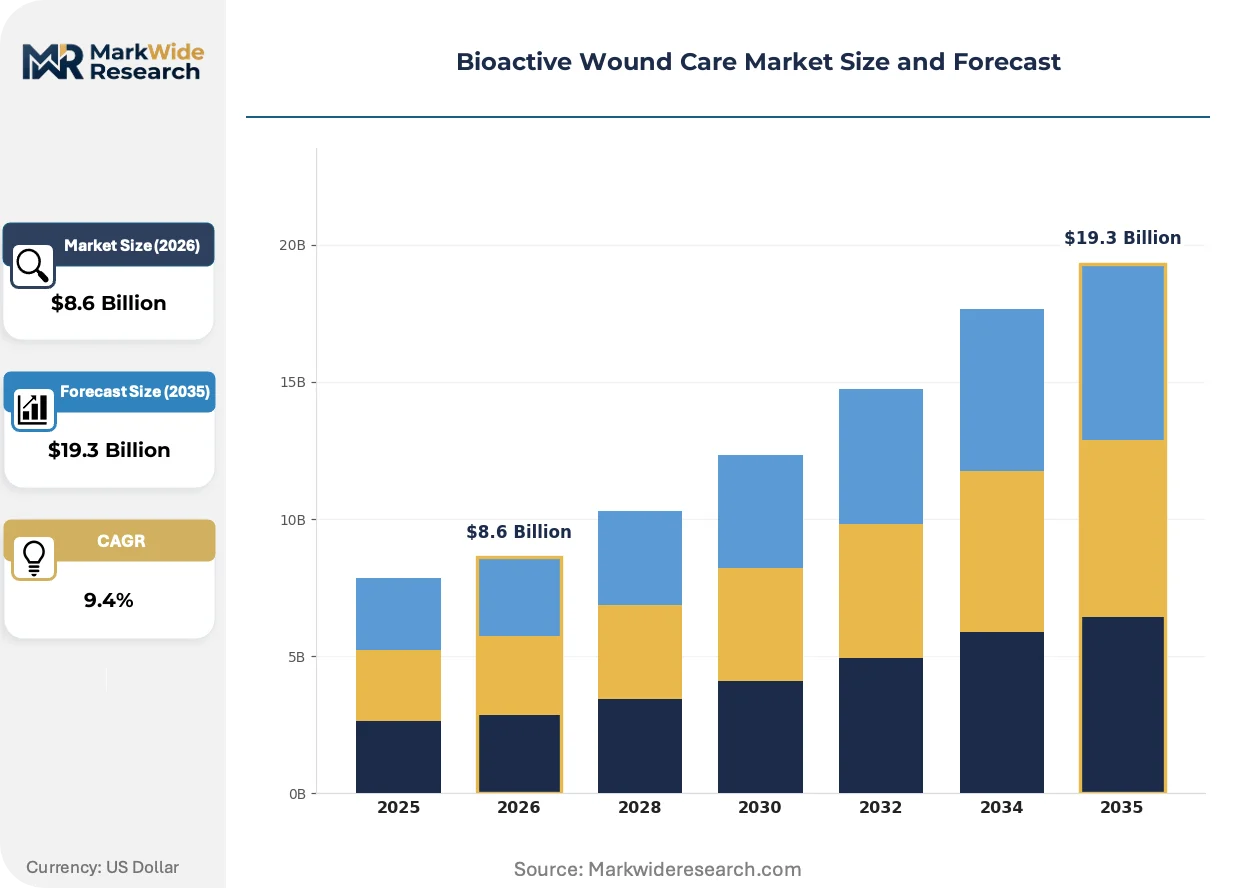
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $19.3 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Dressings, Alginate Dressings, Foam Dressings, Antimicrobial Dressings Technology: Biogel Technology, Hydrogel Technology, Nanotechnology, Phototherapy Application: Chronic Wounds, Surgical Wounds, Burns, Traumatic Wounds End User: Hospitals, Home Care, Ambulatory Surgical Centers, Outpatient Clinics |
| Companies Covered | 3M, Integra LifeSciences, Smith+Nephew, B. Braun SE, Medline Industries, LP, ConvaTec Group PLC, Coloplast Corp, Organogenesis Inc., Mölnlycke Health Care AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioactive Wound Care Market Emerging Trajectories
Product architectures in bioactive wound care are converging around controlled-release mechanisms and living cellular platforms, reshaping how manufacturers structure clinical evidence and manufacturing scale.
Collagen-hyaluronic acid composite matrices are unifying moisture retention with growth factor delivery in single-layer dressings. Burn centers and plastic surgery units in the United States are adopting these platforms at accelerated cadence. The technology is unifying previously separate product categories into integrated therapy systems, compressing vendor consolidation timelines.
The EU's Medical Device Regulation enforcement is elevating post-market surveillance requirements for antimicrobial dressings containing silver or iodine. Manufacturers must now maintain clinical follow-up registries that extend five years beyond commercialization. European hospital procurement committees are responding by consolidating supplier panels to entities with established pharmacovigilance infrastructure.
Hospital supply chain directors are bundling bioactive dressing procurement with outcomes accountability clauses. Traditional distributor intermediaries face compression as manufacturers establish direct contractual relationships with integrated delivery networks. This restructuring is most visible in Medicare Advantage plan regions where capitated payment models dominate reimbursement.
Bioactive Wound Care Market Segmentation
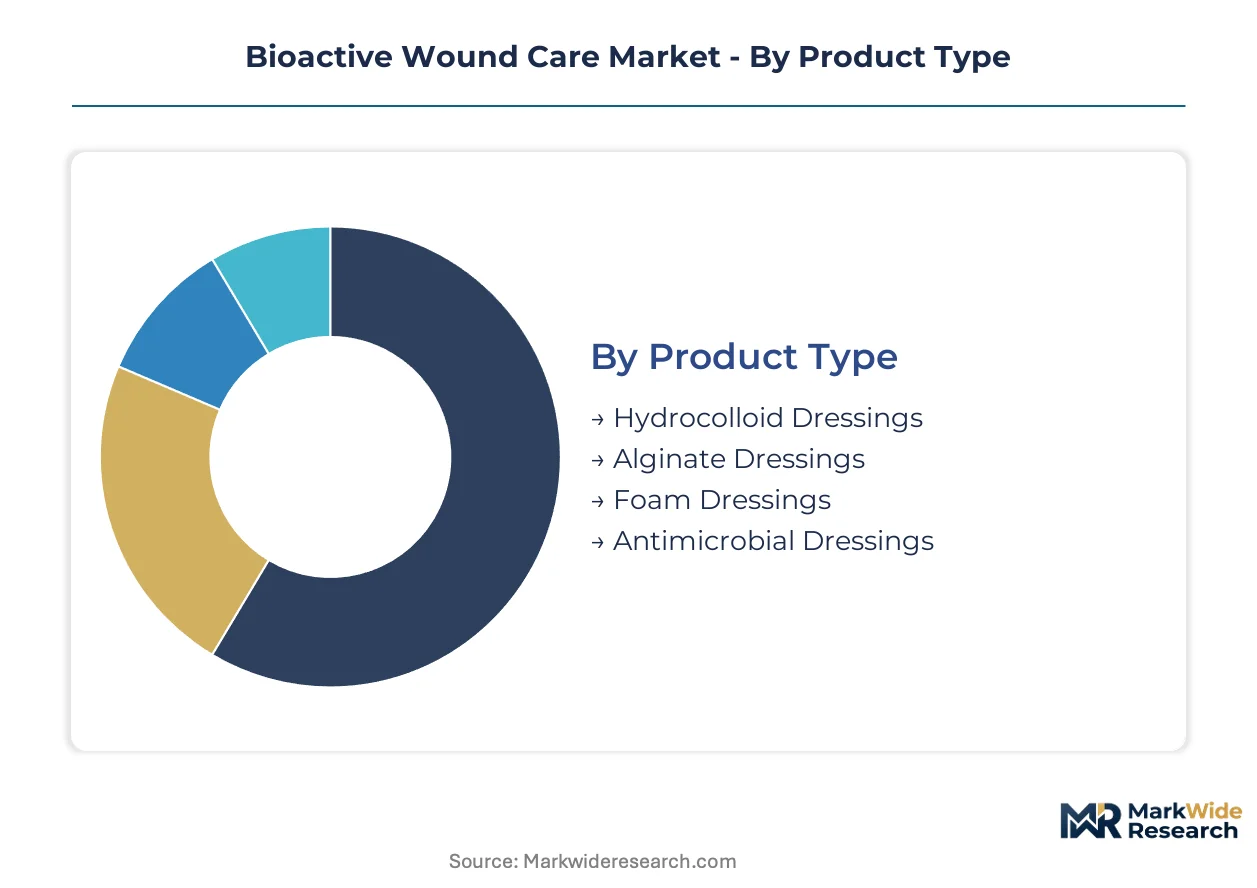
Bioactive wound care purchasing pivots on clinical evidence thresholds and reimbursement tiering rather than unit cost alone. Manufacturers structure portfolio depth across product categories to capture hospital formulary inclusion and Medicare Advantage contracting cycles.
Product Type:
Hospital procurement committees weight antimicrobial efficacy and moisture management performance when selecting dressing categories for formulary placement.
- Antimicrobial Dressings:Silver-ion and iodine-impregnated matrices deliver sustained bacterial load reduction in infected or high-risk wounds. Demand concentrates in United States acute care settings where CMS hospital-acquired infection penalties drive protocol standardization around antimicrobial barriers.
- Alginate Dressings:Calcium-sodium alginate fibers derived from brown seaweed form gel matrices upon exudate contact, maintaining moist healing environments for moderately to heavily draining wounds. Norwegian coastal supply concentration exposes manufacturers to marine ecosystem variability and harvest seasonality constraints.
- Hydrocolloid Dressings:Carboxymethylcellulose and gelatin composites absorb exudate while forming occlusive barriers suitable for autolytic debridement in low-exudate wounds.
- Foam Dressings:Polyurethane foam structures wick moisture vertically away from wound beds, serving pressure ulcer prevention protocols in long-term care facilities.
Antimicrobial dressings lead on scale; alginate dressings lead on momentum in European chronic wound protocols.
Technology:
Technology selection tracks wound complexity tier and payer reimbursement for advanced intervention codes.
- Hydrogel Technology:Cross-linked polymer networks maintain 90% water content to hydrate necrotic tissue and support autolytic debridement in dry wounds. Burn centers in Germany and Japan deploy amorphous and sheet hydrogels for partial-thickness thermal injuries where cooling and moisture retention accelerate re-epithelialization.
- Phototherapy:LED arrays delivering specific wavelengths stimulate cellular ATP production and modulate inflammatory cytokine profiles in recalcitrant chronic wounds. Swiss private insurers are piloting reimbursement for light-activated platforms in diabetic foot ulcer protocols, creating precedent for broader European payer adoption.
- Biogel Technology:Living cell-embedded matrices derived from human fibroblasts or keratinocytes secrete endogenous growth factors directly at wound sites.
- Nanotechnology:Silver nanoparticles and electrospun nanofibers enhance antimicrobial surface area and controlled release kinetics in advanced dressing architectures.
Hydrogel platforms anchor current revenue concentration; phototherapy applications are climbing the fastest as evidence generation accelerates.
Application:
Application segmentation aligns with epidemiological burden and procedure volume trajectories across healthcare systems.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries constitute the structurally dominant segment driven by aging demographics and diabetes prevalence expansion. United States Medicare expenditure on chronic wound management is redirecting toward bioactive interventions as bundled payment models penalize prolonged healing timelines.
- Surgical Wounds:Post-operative incision management represents high-volume, lower-margin utilization where antimicrobial dressings prevent surgical site infections in orthopedic and cardiovascular procedures. Ambulatory surgery center growth in Australia and outpatient migration in the United States are shifting surgical wound dressing procurement toward disposable, protocol-driven SKUs.
- Burns:Partial and full-thickness thermal injuries require specialized moisture management and infection control in dedicated burn center networks.
- Traumatic Wounds:Acute mechanical injuries from accidents or combat demand rapid hemostasis and contamination control in emergency department settings.
Chronic wounds dominate absolute volume; surgical wounds are gaining share fastest through outpatient procedure expansion.
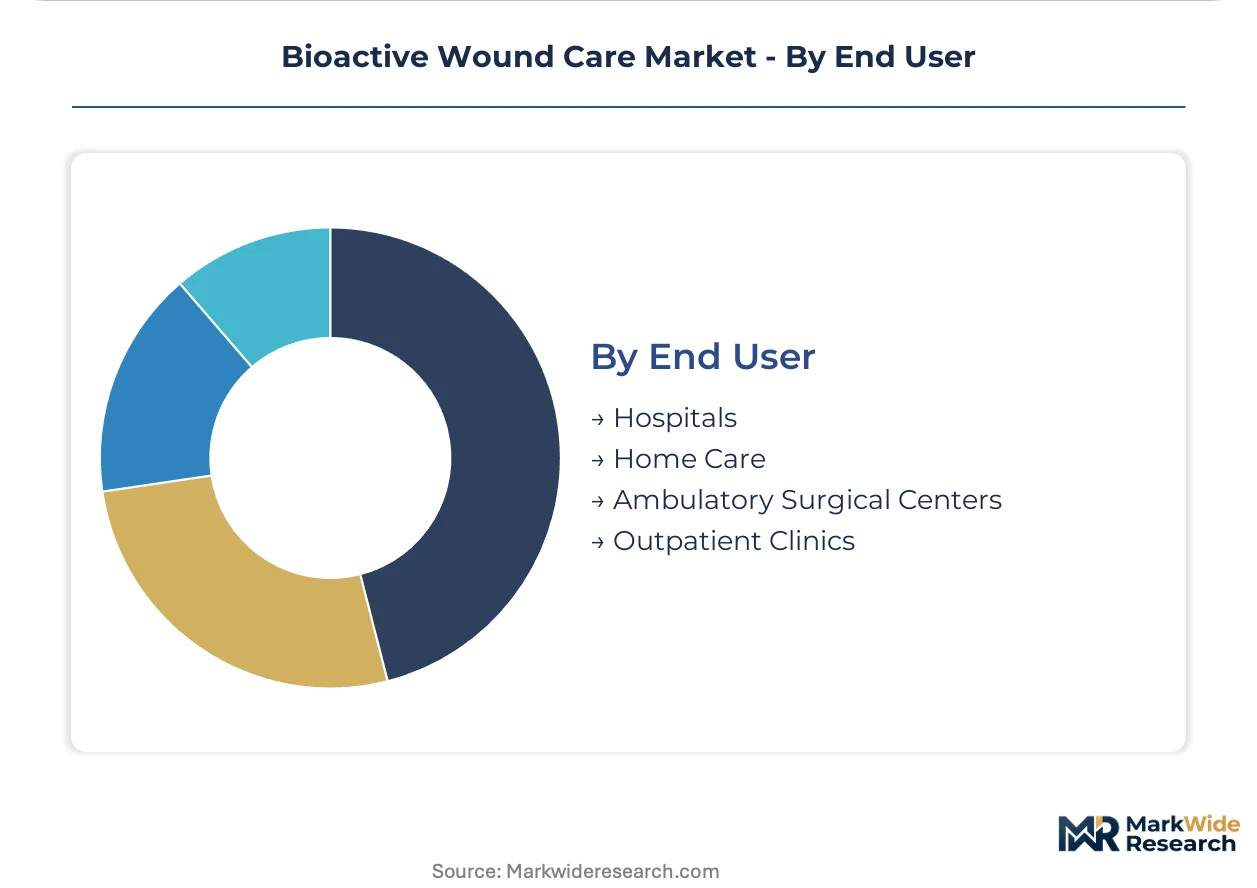
End User:
End user channel structure determines pricing architecture and clinical support service requirements.
- Hospitals:Integrated delivery networks and academic medical centers command premium pricing for bioactive dressings backed by randomized trial evidence and dedicated wound care specialist support. United States hospital procurement consolidation into centralized supply chain functions is compressing vendor panels to manufacturers with comprehensive formulary coverage and outcomes data infrastructure.
- Home Care:Skilled nursing facilities and home health agencies represent the expanding channel as payers push chronic wound management outside institutional settings. Australian rural health systems are deploying direct-to-patient distribution models that bypass traditional hospital procurement intermediaries entirely.
- Ambulatory Surgical Centers:Freestanding surgical facilities prioritize cost-efficient, protocol-standardized dressing selections for post-operative care.
- Outpatient Clinics:Wound care centers and dermatology practices manage complex chronic cases with moderate procedure volumes.
Hospitals retain the steepest expansion trajectory in absolute dollar terms; home care channels are restructuring distribution economics most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cell culture technicians cluster in Boston, Basel, and Singapore, anchoring bioactive manufacturing expertise. These talent pools attract contract development organizations and specialized dressing manufacturers seeking proximity to academic medical centers and regenerative medicine research institutes.
United States
Medicare Advantage bundled payment models accelerate hospital procurement of antimicrobial dressings over standard coverings. The FDA's regenerative medicine advanced therapy designation streamlines clinical trial pathways for skin substitutes in Boston and Durham research corridors. Smith+Nephew maintains orthobiologics manufacturing presence in Memphis while Organogenesis anchors human cell-based production in Canton, Massachusetts.
Germany
Diabetic foot ulcer prevalence among aging populations expands addressable patient pools for alginate and hydrogel dressings. The EMA's Medical Device Regulation imposes five-year post-market surveillance requirements on collagen-based manufacturers. Mölnlycke Health Care dominates hospital procurement channels from its Gothenburg headquarters, serving German burn centers in Berlin and Hamburg with advanced moisture management platforms.
Japan
PMDA guidance on combination product classification creates regulatory timeline certainty for living cell dressings. METI funding for regenerative medicine commercialization supports academic-industry partnerships in Kobe and Osaka biotech clusters. Domestic manufacturers leverage hyaluronic acid innovation from Shiseido's material science heritage to supply burn centers in Tokyo and Nagoya.
Australia
Rural health systems deploy direct-to-patient distribution models that bypass traditional hospital procurement intermediaries entirely. The TGA's evolving framework on biological medicines aligns with FDA pathways, reducing dual-registration burden for multinational manufacturers. Home care channel expansion concentrates in Queensland and Western Australia where geographic isolation necessitates remote wound management protocols.
Switzerland
Swiss private insurers pilot reimbursement for phototherapy platforms in diabetic foot ulcer protocols, creating precedent for broader European payer adoption. Swissmedic's streamlined biological product review attracts developers seeking rapid market entry for LED-activated healing systems. Basel's pharmaceutical talent density supports specialty dressing innovation while Zurich anchors private payer negotiation headquarters.
Bioactive Wound Care Market Vendor Landscape
Top-tier vendors anchor integrated delivery network contracting, while mid-scale specialists occupy regional hospital formulary niches. The competitive structure stratifies across three tiers: multinational conglomerates with diversified medtech portfolios, pure-play wound care specialists with vertical manufacturing control, and contract manufacturers supplying private-label dressings. Market consolidation accelerates through hospital procurement panel compression and outcomes-based contracting mandates.
Within the pure-play specialist tier, Organogenesis Inc. and Mölnlycke Health Care AB exemplify divergent strategic positioning. Organogenesis occupies a position representing human cell-based manufacturing archetypes with captive bioprocessing infrastructure. Mölnlycke anchors European procurement channel dominance through broad dressing portfolio coverage. Among diversified conglomerates, 3M and Smith+Nephew sit within the premium-tier vector, leveraging orthobiologics heritage and material science capabilities to sustain margin positions in antimicrobial and composite matrix categories.
| Leading Market Players |
|---|
| 3M |
| Integra LifeSciences |
| Smith+Nephew |
| B. Braun SE |
| Medline Industries, LP |
| ConvaTec Group PLC |
| Coloplast Corp |
| Organogenesis Inc. |
| Mölnlycke Health Care AB |
| Others |
Supply Flow & Price Mechanics
Brown seaweed harvest costs from Norwegian coastal waters cascade through alginate dressing manufacturing into three-tier pricing structures across premium, standard, and economy levels. Cell culture technician wages in Boston and Basel biotech clusters anchor premium pricing for living cell matrices, while commodity hydrocolloid dressings compete on unit economics in price-sensitive long-term care channels.
Pricing Analysis
Bundled service contracts combining dressing procurement with outcomes accountability clauses dominate United States hospital procurement, while unbundled transactional pricing persists in European long-term care. Price differentiation hinges on clinical evidence depth and FDA regenerative medicine designation status, with antimicrobial dressings commanding premiums over standard coverings. Pricing pressure stems from Medicare Advantage capitated models penalizing prolonged healing timelines. Ambulatory surgery centers exhibit highest price sensitivity; integrated delivery networks least.
Supply Chain Analysis
Freight costs for temperature-controlled cell-based products from Canton, Massachusetts to United States distribution hubs compress margins on human skin substitutes. Supply concentrates in Norway for alginate raw materials, the United States for collagen matrices, and Japan for hyaluronic acid innovations. Brown seaweed harvesting, specialized bioprocessing equipment, and living cell culture media constitute critical input dependencies. Single-source vulnerability in Norwegian coastal ecosystems threatens alginate supply stability. Distribution runs through integrated delivery network direct contracts and traditional hospital procurement intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory milestones, with the FDA's regenerative medicine advanced therapy designation accelerating clinical trial pathways and reimbursement validation for qualified developers.
For Market Incumbents: Acquire captive cell culture manufacturing capacity to defend against commodity substitution in alginate and hydrocolloid segments. Secure five-year post-market surveillance infrastructure to meet EMA Medical Device Regulation requirements for antimicrobial dressings. Deepen backward integration into brown seaweed harvesting through long-term Norwegian coastal concessions.
For New Entrants and Emerging Players: Launch via direct-to-patient distribution models targeting Australian rural health systems and United States home care channels bypassing hospital procurement gatekeepers. Penetrate phototherapy platforms where Swiss private insurers pilot reimbursement for diabetic foot ulcer protocols. Anchor go-to-market strategy around LED-activated healing systems with companion software for remote monitoring.
For Investors and Strategic Acquirers: Consolidation pressure builds where hospital procurement panel compression eliminates mid-scale distributors lacking formulary breadth or outcomes data infrastructure. Long-term viability favors pure-play specialists with vertical manufacturing control over diversified conglomerates exposed to commodity margin erosion. Target acquisition archetype: cell-based manufacturers with captive bioprocessing and FDA regenerative medicine designation pipeline. Watch for inflection when Medicare Advantage bundled payment models expand antimicrobial dressing coverage thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Regenerative Medicine Designation | Accelerates clinical trial pathways for Organogenesis and Smith+Nephew skin substitute portfolios. |
| Hospital System Partnership | Mölnlycke secures integrated delivery network formulary inclusion through outcomes accountability clauses. |
| Backward Integration | Alginate manufacturers secure Norwegian brown seaweed harvesting concessions against marine climate volatility. |
| CE Marking Pathway | European antimicrobial dressing developers navigate EMA five-year post-market surveillance requirements. |
| Reimbursement Strategy | Phototherapy platform developers negotiate Swiss private payer coverage for diabetic foot ulcer protocols. |
Methodological Framework
Coverage spans the United States, Germany, Japan, Australia, and Switzerland, with primary inputs from each market cluster validating demand trajectories. Primary interviews with hospital procurement managers, wound care clinicians, biomedical engineers, and GPO contracts directors combined with secondary validation from FDA filings, EMA submissions, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across the analysis window disaggregated growth into chronic wound epidemiology expansion, reimbursement policy shifts, and technology substitution effects. Segmentation dimensions modeled include product category, technology platform, wound application type, and end-user channel structure. CAGRs derived from weighted average of historical procedure volume trends and forward-looking payer policy scenarios, with regenerative medicine designation timelines and antimicrobial protocol adoption curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA combination product reclassification or Norwegian alginate harvest disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Collagen Dressings Market
Wound Care
Autologous Wound Patches Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Wound Closure Strips Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Biopatches Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Wound Healing Supplement Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Global Burn Care Market
Wound Care
Australia Wound Care Management Devices Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Europe Compression Bandages Market