
 Global Traditional Wound Management Market | 2026-2036
Global Traditional Wound Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Traditional Wound Management Market Intelligence
The bundling of gauze dressings and surgical tapes into single-use, procedure-specific kits is expanding procurement choices for large hospital networks. Johnson & Johnson leverages its vast global distribution network to supply these kits, particularly in the United States and Europe. B. Braun Melsungen AG competes by focusing on integrated solutions for surgical applications, including pre-packaged wound closure sets. In contrast, Medline Industries differentiates through its supply chain efficiency, catering to high-volume institutional buyers.
Traditional wound management encompasses passive dressings designed to cover and protect injuries, maintaining a dry environment for healing. Composed of materials like woven cotton, these products primarily absorb exudate and provide a barrier against external contamination. Gauze dressings and adhesive bandages represent mature product categories, essential for treating postoperative wounds and minor trauma. Hospitals dominate consumption, but ambulatory surgical centers are an expanding channel for cost-effective, single-use items.
Product classification and market access are shaped by regulatory bodies such as the FDA in the United States, which oversees medical device clearance. In Europe, the CE marking under the Medical Device Regulation (MDR) imposes stringent clinical evidence requirements, while China's NMPA controls device registration. Future success depends on navigating these diverse regulatory landscapes while managing production costs for these price-sensitive commodities.
Market Dynamics
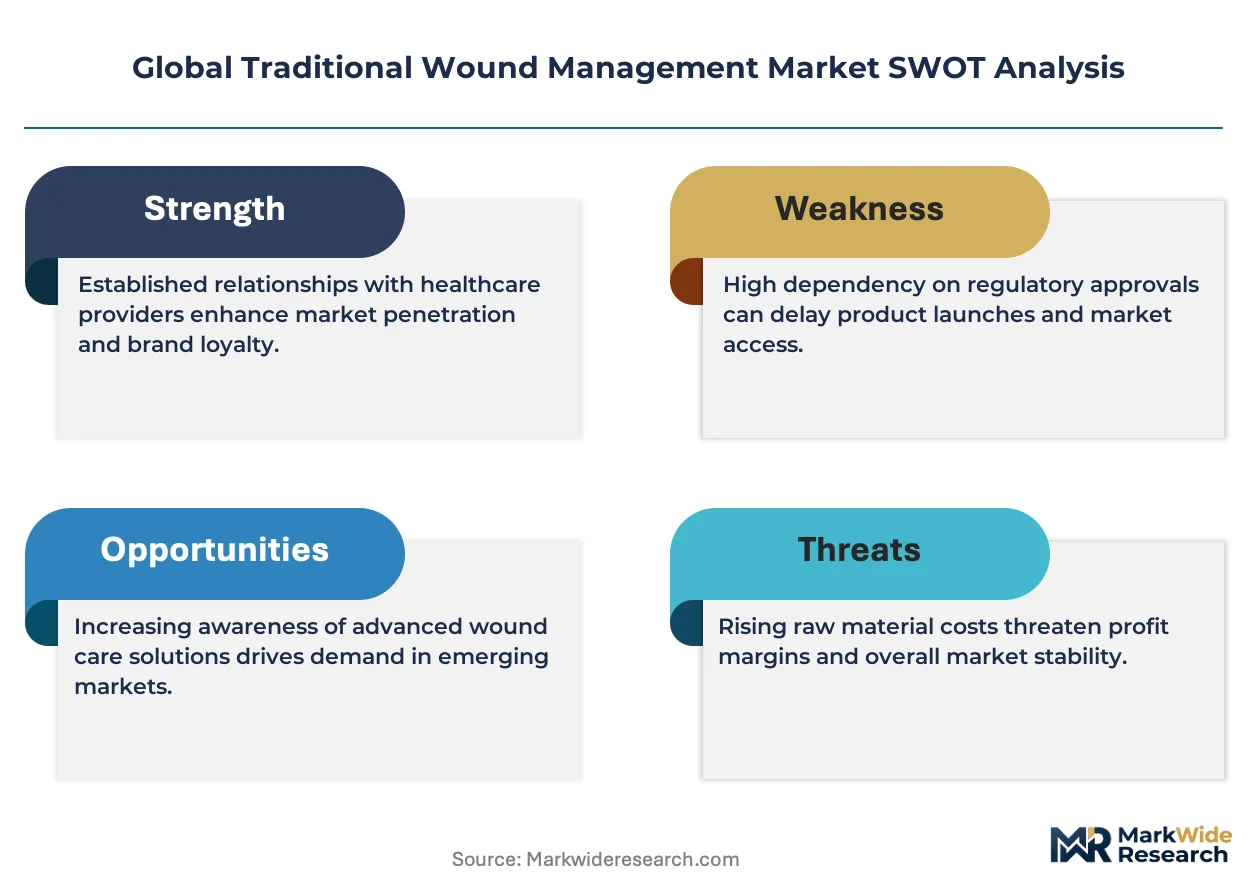
The traditional wound management market is defined by the tension between its status as a high-volume commodity business and escalating regulatory demands. The implementation of frameworks like the EU's MDR is forcing manufacturers to invest in clinical data for mature products, complicating cost structures for price-sensitive items.
Growth Catalysts
- Homecare Expansion:An aging global population and a shift toward treating chronic conditions like diabetic foot ulcers in home settings create sustained demand for accessible, easy-to-use wound dressings and tapes.
- Chinese Healthcare Investment:Government initiatives to expand and modernize China's national healthcare system are significantly increasing the consumption of basic medical supplies, including traditional wound care products in hospitals and clinics.
- Ambulatory Surgical Centers:The rising number of procedures performed in ambulatory surgical centers, which prioritize cost-effective, single-use sterile products, is opening a significant volume-driven channel for manufacturers.
Market Restraints
- Substitution by Advanced Products:The growing clinical acceptance of advanced wound care technologies for managing complex and chronic wounds poses a direct substitution threat to traditional passive dressings in certain applications.
- Raw Material Price Volatility:The market's profitability is sensitive to fluctuations in the price of key inputs, particularly woven cotton, which can compress margins for manufacturers of gauze and bandages.
- Regulatory Scrutiny:Increasingly stringent clinical evidence requirements from bodies like the FDA and under the EU's MDR create barriers to entry and increase compliance costs for what are often viewed as commodity products.
Strategic Opportunities
- Procedure-Specific Kits:Bundling gauze, tapes, and other dressings into single-use kits tailored for specific surgical procedures offers a value-added service that simplifies procurement for large hospital networks.
- Emerging Market Penetration:Focusing on healthcare systems in Southeast Asia and Latin America, where infrastructure is expanding but cost remains a primary concern, presents a major geographic growth opportunity.
- Private Label Partnerships:Collaborating with large distributors and institutional buyers to create private-label product lines can secure high-volume contracts and expand market access without extensive marketing investment.
Industry Challenges
- Regulatory Navigation:Managing the complex and divergent submission processes for medical device registration across key markets, including the FDA in the US, the EU (CE mark), and China's NMPA, requires significant specialized expertise.
- Logistical Efficiency:Maintaining a cost-effective and reliable supply chain for high-volume, low-margin goods is a persistent operational challenge, particularly in the face of global shipping disruptions and rising transport costs.
- Sterilization Compliance:Adhering to evolving standards for product sterilization and ensuring the integrity of sterile barriers throughout the supply chain demands continuous investment in quality control and validation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Traditional Wound Management Market |
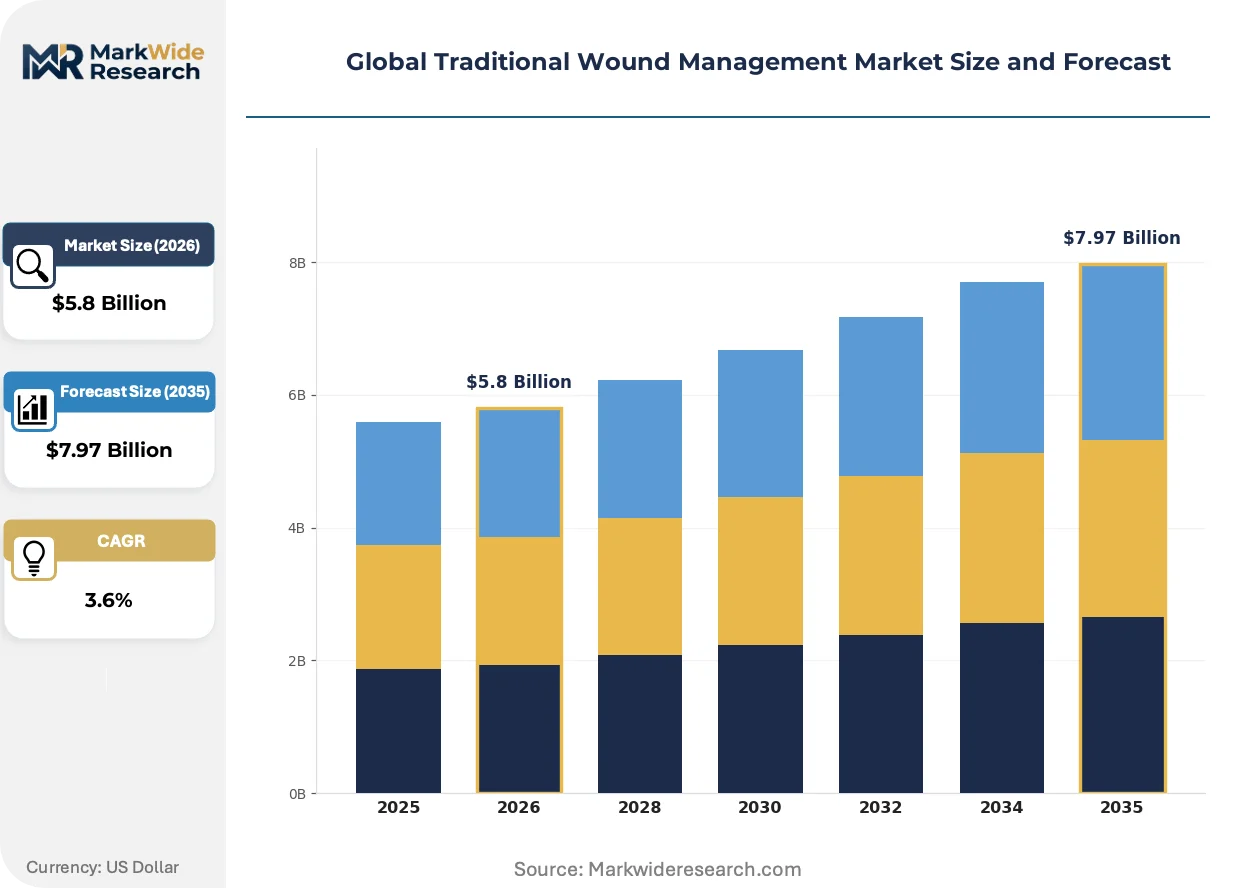
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $7.97 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gauze Dressings, Adhesive Bandages, Cotton Pads, Surgical Tapes, Compression Bandages Application: Postoperative Wounds, Chronic Ulcers, Traumatic Wounds, Burns, Diabetic Foot Ulcers End User: Hospitals, Ambulatory Surgical Centers, Homecare Settings, Specialty Clinics Distribution Channel: Pharmacies, Medical Supply Stores, Online Retailers, Wholesale Distributors |
| Companies Covered | Smith & Nephew plc, Cardinal Health, 3M Company, B. Braun Melsungen AG, Johnson & Johnson, Mölnlycke Health Care, Medtronic Plc, Medline Industries, ConvaTec Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Traditional Wound Management Market Strategic Shifts & Innovations
Product formats are evolving to meet the procurement demands of large-scale healthcare providers, emphasizing efficiency and procedural convenience. This shift is occurring alongside a stricter global regulatory environment that elevates compliance costs for even the most basic wound care items.
The bundling of wound care items into procedure-specific kits represents a key packaging innovation. Adopted primarily by large hospital networks and ambulatory surgical centers, these kits simplify inventory management and streamline clinical workflows. This approach is consolidating the procurement of numerous individual components, such as gauze and tape, into a single orderable unit, reducing administrative overhead for institutional buyers.
Europe's Medical Device Regulation (MDR) has introduced a significant compliance shift for the industry. The regulation mandates more rigorous clinical evaluation and post-market surveillance, even for long-established Class I devices like adhesive bandages. This change directly affects manufacturers supplying the European market, necessitating substantial investment in updating technical documentation and labeling to maintain CE marking and market access.
Centralized purchasing by group purchasing organizations (GPOs) and integrated delivery networks (IDNs) is altering how products are sold. This model increasingly replaces direct sales to individual hospitals, concentrating buying power with fewer, larger entities. The shift is most visible in the United States healthcare market, where GPOs leverage their scale to negotiate pricing and standardize product selection across their member facilities.
Global Traditional Wound Management Market Segmentation
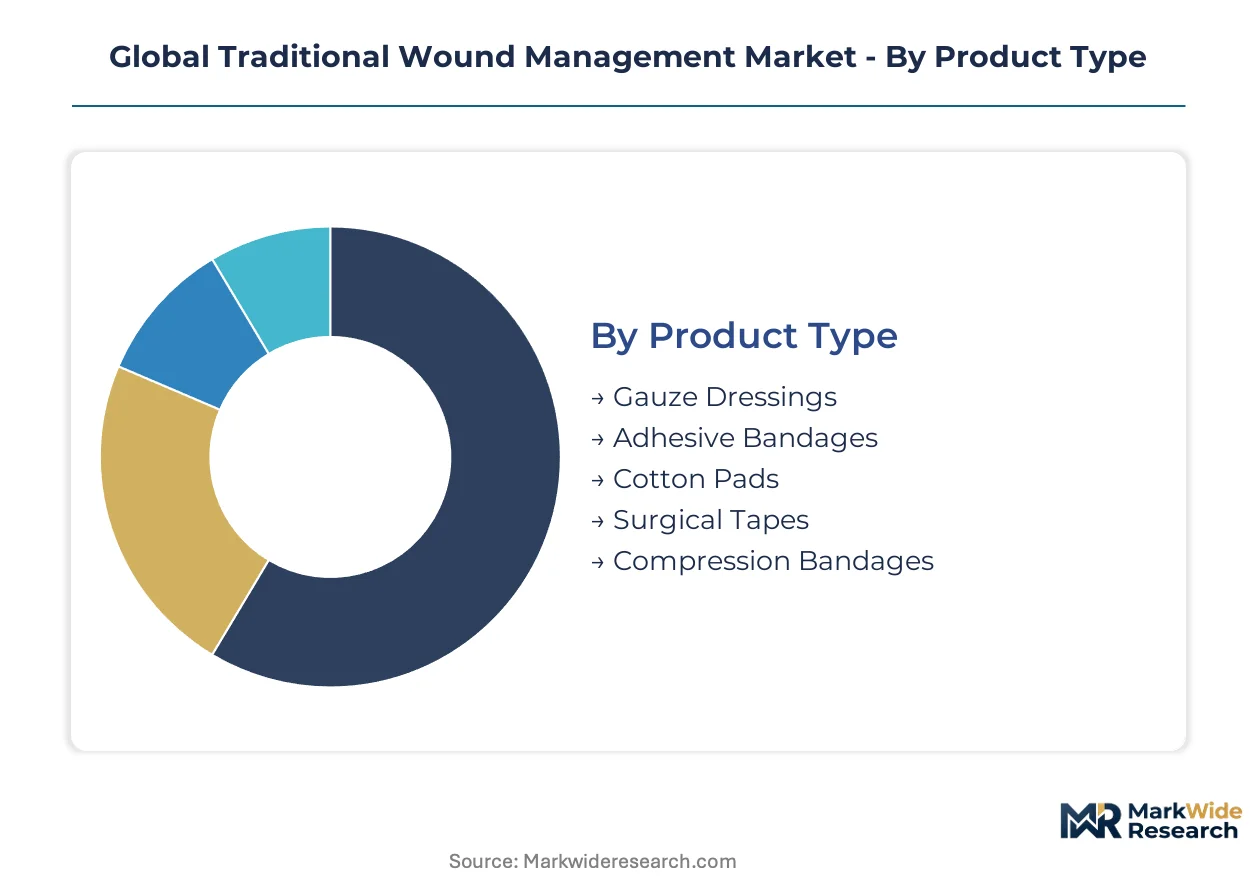
The traditional wound management market categorizes products and their usage to understand diverse procurement needs. This analysis highlights how different product types address varying wound complexities and end-user requirements. Understanding these segments reveals specific demand patterns across healthcare settings.
Product Type:
The product type segmentation reveals a clear distinction between high-volume, cost-sensitive commodities and specialized items requiring specific material properties.
- Gauze Dressings:These products consist of woven cotton or synthetic fibers, designed for absorption and wound protection. Demand remains high in hospital settings for managing postoperative wounds and general trauma care across North America and Europe.
- Adhesive Bandages:Comprising a sterile pad attached to an adhesive strip, these are used for minor cuts and abrasions. Homecare settings and ambulatory surgical centers drive consumption due to their convenience and ease of application in China and India.
- Cotton Pads:Absorbent pads primarily for cleaning and applying topical agents, widely used in clinics.
- Surgical Tapes:Used to secure dressings and medical devices, essential for wound closure protocols.
- Compression Bandages:Applied to reduce swelling and provide support, particularly for chronic leg ulcers.
Mature deployment sits with Gauze Dressings. Newer deployment is concentrated in Adhesive Bandages.
Application:
Application segments delineate the specific clinical needs that traditional wound management products address, influencing product design and material selection.
- Postoperative Wounds:These wounds result from surgical incisions and require sterile dressings for protection and exudate management. Hospitals and ambulatory surgical centers represent the primary care settings for these applications in countries like Germany and the United States.
- Chronic Ulcers:This category includes pressure ulcers, venous leg ulcers, and arterial ulcers, demanding sustained wound care over extended periods. Homecare settings and specialty clinics in Japan and Canada see significant consumption for these conditions.
- Traumatic Wounds:Injuries resulting from accidents or external forces, often requiring immediate and basic wound coverage. Emergency rooms and general practitioners utilize these products frequently.
- Burns:Wounds caused by heat, chemicals, or electricity, which need protective and absorbent dressings.
- Diabetic Foot Ulcers:A common complication of diabetes, these ulcers require careful management to prevent infection and promote healing.
The most prevalent application is Postoperative Wounds. The most specialized application is Diabetic Foot Ulcers.
End User:
End-user segments highlight the diverse healthcare environments where traditional wound management products are consumed, each with distinct procurement processes and volume requirements.
- Hospitals:These institutions represent the largest volume consumers, requiring a broad range of sterile dressings and tapes for surgical and inpatient care. Centralized purchasing departments manage large-scale procurement for hospital networks in France and the UK.
- Homecare Settings:An expanding segment driven by an aging population and a shift towards outpatient care, demanding user-friendly and accessible products. Patients or caregivers manage wound care at home in Australia and Brazil.
- Ambulatory Surgical Centers:These facilities prioritize cost-effective, single-use, pre-packaged sterile items for minor surgical procedures. Their demand profile favors bulk purchases of kits.
- Specialty Clinics:These include dermatology, podiatry, and wound care clinics, focusing on specific wound types and requiring specialized traditional dressings.
The largest purchasing power resides with Hospitals. The fastest-growing end-user segment is Homecare Settings.
Distribution Channel:
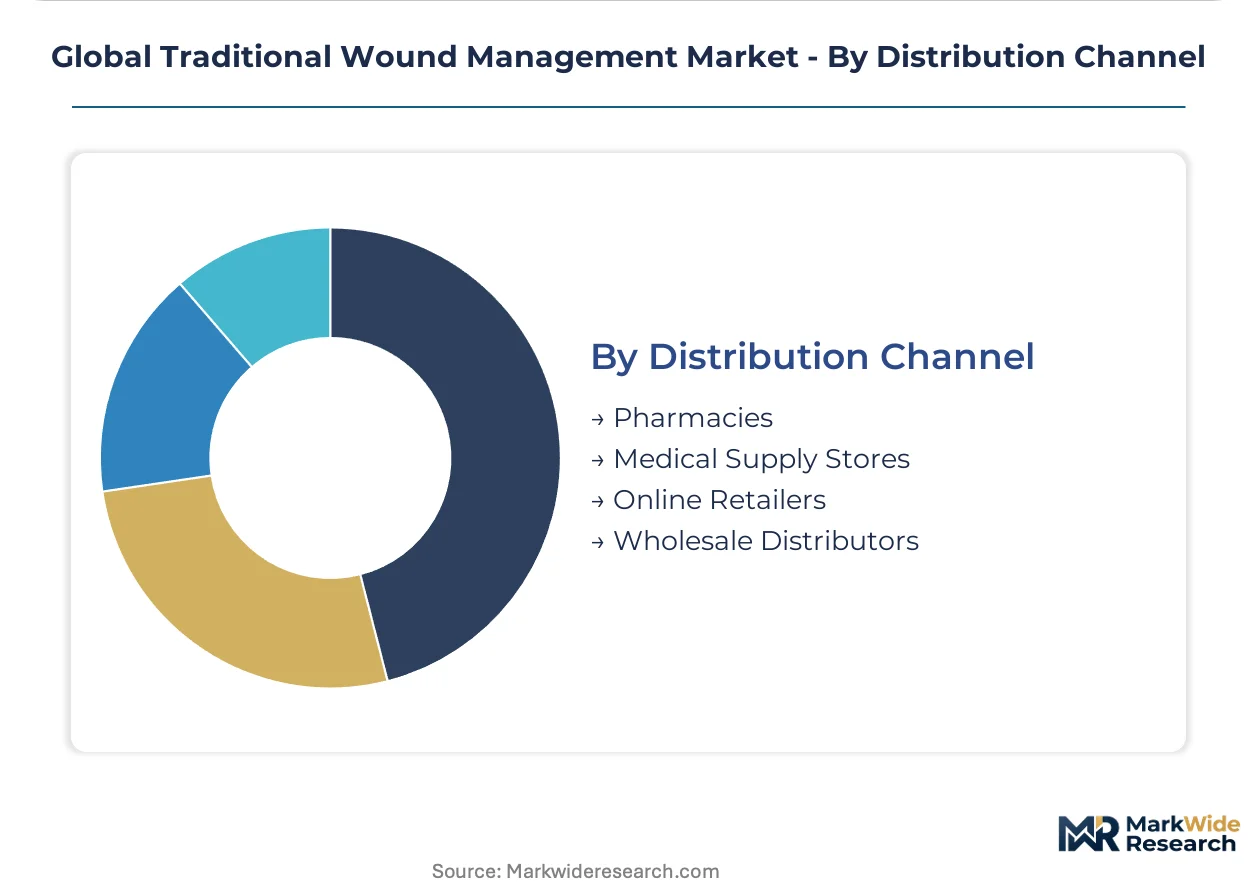
Distribution channels define how traditional wound management products reach end-users, influencing market access and pricing strategies.
- Pharmacies:These retail outlets provide convenient access to over-the-counter wound care products for minor injuries and general home use. Pharmacies in India and Mexico serve a vast consumer base.
- Medical Supply Stores:Specialized stores offering a wider range of medical products, including traditional wound dressings, often catering to professional healthcare providers and long-term care facilities. These stores serve clinics and individual practitioners.
- Online Retailers:E-commerce platforms offer a growing channel for direct-to-consumer sales and bulk purchases by smaller clinics due to convenience and competitive pricing. This channel is gaining traction in the United States and China.
- Wholesale Distributors:These entities supply large volumes of products to hospitals, group purchasing organizations, and other institutional buyers. They form the backbone of supply chains for major healthcare networks.
Direct consumer access is primarily through Pharmacies. Institutional procurement is dominated by Wholesale Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The traditional wound management market exhibits a clear divide between established production hubs and regions experiencing accelerating consumption. Demand across various geographies reflects specific healthcare infrastructure developments and demographic shifts. Regulatory frameworks like the EU's MDR and China's NMPA significantly influence market access and product compliance across these regions.
United States
Large hospital networks and an expanding number of ambulatory surgical centers drive consistent demand for traditional wound care products. The FDA ensures medical device safety and efficacy, shaping product clearance and market entry. Major medical device manufacturing clusters in states like Minnesota and Massachusetts focus on innovation and high-volume production.
China
Government investment in its national healthcare system significantly boosts consumption of basic medical supplies, including traditional wound care. The NMPA regulates device registration, influencing market access for both domestic and international manufacturers. Major urban centers like Shanghai and Beijing are rapidly expanding their hospital and homecare infrastructure.
Germany
Hospitals and specialty clinics maintain high consumption of postoperative wound dressings and compression bandages. The EU's Medical Device Regulation (MDR) imposes stringent clinical evidence requirements for products sold within the country. Medical technology clusters in regions such as Tuttlingen contribute to advanced manufacturing capabilities for wound care devices.
India
The expanding homecare sector and accessibility through pharmacies drive demand for adhesive bandages and general wound care items. The CDSCO oversees medical device regulations, impacting product approvals and market distribution. Major healthcare hubs in cities like Mumbai and Delhi are increasing the uptake of traditional wound management solutions.
Japan
An aging population creates sustained demand for traditional wound care, particularly for chronic ulcers managed in homecare settings. The PMDA regulates medical devices, ensuring product quality and market entry standards. Healthcare infrastructure development in metropolitan areas like Tokyo and Osaka supports widespread product availability.
Global Traditional Wound Management Market Key Industry Players
The competitive structure tilts toward established global players with extensive distribution networks, alongside regional specialists focusing on specific market niches. This market features a tiered landscape where scale-driven manufacturers coexist with agile providers of integrated solutions. Dominant competitive moves include strategic bundling of products into procedure-specific kits and optimizing complex global supply chains.
At the scale-driven end, Johnson & Johnson leverages its vast global distribution network to supply traditional wound care kits, particularly in North America and Europe. B. Braun Melsungen AG, a German-based company, exemplifies a focus on integrated solutions for surgical applications, including pre-packaged wound closure sets. Medline Industries, an American company, differentiates through its supply chain efficiency, catering to high-volume institutional buyers across various healthcare settings.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Cardinal Health |
| 3M Company |
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Mölnlycke Health Care |
| Medtronic Plc |
| Medline Industries |
| ConvaTec Group |
| Others |
Cost & Logistics Intelligence
The bundling of wound care items into procedure-specific kits is reshaping cost economics by reducing administrative overhead for institutional buyers. This shift simultaneously concentrates procurement power with large group purchasing organizations.
Pricing Analysis
Cost-down pressure on traditional wound care items intensifies as regulatory compliance costs rise for commodity products. The market largely operates on a per-unit transactional model, transitioning to contract-based long-term off-take for institutional buyers. Price differentiation stems from volume scale and critical certification levels like FDA clearance or CE marking. Hospitals and ambulatory surgical centers exhibit high price sensitivity due to bulk purchasing, while homecare settings prioritize accessibility for basic items.
Supply Chain Analysis
Stringent certification and qualification processes, particularly under the EU's MDR, gate market access and shape supply chain configurations. Manufacturing capability concentrates in regions like the United States and Germany, while China emerges as a significant demand hub. The supply chain draws from key inputs such as woven cotton and adhesive materials. Raw material price volatility presents a structural risk, compressing margins for manufacturers of commodity items, with distribution primarily through wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The traditional wound management market is fundamentally a cost-of-compliance story, where the EU's Medical Device Regulation creates a significant barrier-to-entry moat for manufacturers able to meet stringent clinical evidence requirements.
For Market Incumbents:Acquire specialized regulatory expertise to navigate diverging global medical device registration processes. Incumbents must also invest in advanced supply chain efficiency to counter raw material price volatility and maintain margins on commodity products. Expanding procedure-specific kit offerings leverages existing channel control with large hospital networks, defending against substitution by advanced wound care technologies. Continuous certification investment under frameworks like the EU's MDR solidifies market access.
For New Entrants and Emerging Players:China's NMPA registration pathway, coupled with expanding national healthcare investment, opens a window for new entrants focusing on high-volume, basic wound care products. Target homecare settings in Southeast Asia and Latin America, where infrastructure is expanding and cost remains a primary concern. Private label partnerships with large distributors or institutional buyers offer a cost-effective go-to-market angle, securing volume without extensive marketing investment. Ambulatory surgical centers also represent a penetrable segment for single-use, pre-packaged items.
For Investors and Strategic Acquirers:Exit pathways concentrate in mid-cap specialists with robust regulatory compliance and efficient supply chains for commodity wound care products. Long-term viability is anchored in sustained demand from an aging global population and the rising prevalence of chronic conditions like diabetic foot ulcers. Acquisition targets should possess strong relationships with group purchasing organizations and integrated delivery networks. The expansion of homecare reimbursement policies for traditional wound care solutions signals a critical inflection point for market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Regulatory Compliance Infrastructure | Ensures continued market access in Europe under the stringent Medical Device Regulation. |
| Expand Procedure-Specific Kit Offerings | Simplifies procurement for large hospital networks and ambulatory surgical centers, streamlining clinical workflows. |
| Optimize Global Supply Chain Logistics | Mitigates raw material price volatility and reduces transport costs for high-volume, low-margin goods. |
| Forge Private Label Partnerships | Secures high-volume contracts with institutional buyers and expands market access in emerging economies. |
| Penetrate Homecare Distribution Channels | Addresses the sustained demand from an aging population requiring accessible solutions for chronic ulcers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, complemented by primary interviews. Conversations with GPO contracts managers, hospital procurement leads, regulatory affairs specialists, and medical device engineers provided critical insights. This approach facilitated bottom-up validation of market size and top-down triangulation of growth forecasts using FDA filings, CE marking databases, and NMPA registrations.
Market volume and value were modeled at a granular level across product type, application, end user, and distribution channel, further segmented by regional regulatory framework. Compound annual growth rates were derived from historical trends and projected forward across the analysis window. Key forecast inputs included global aging population demographics and country-specific healthcare infrastructure investment.
The model assumes a particular technology adoption path for traditional wound care; alternative pathways for advanced wound care products would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and raw material pricing. A model refresh is warranted upon material change in global healthcare spending or medical device regulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Healing Supplement Market
Wound Care
Infectious Wound Care Management Market
Wound Care
South Korea Wound Care Market
Wound Care
Wound Care Sealants Market
Wound Care
Wound Evacuators Market
Wound Care
Italy Wound Care Market
Wound Care
Negative Pressure Wound Therapy Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Acute Wound Care Market
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Wound Debridement Products Market
Wound Care
Wound Measurement Devices Market
Wound Care
Next Generation Wound Closure Device Market
Wound Care
Wound Contact Layer Dressing Market