
 Hydrocolloid Sponges Market | 2026-2036
Hydrocolloid Sponges Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocolloid Sponges Market Insights
Biomedical polymer engineering talent is rotating toward absorbent wound matrix development as healthcare systems prioritize moisture-balanced healing environments. Smith & Nephew leverages its vertically integrated alginate supply chain to dominate hospital procurement channels across Western Europe. 3M Company anchors its position through proprietary adhesive polymer science that extends wear time in exuding wounds. Coloplast A/S specializes in ostomy-adjacent wound portfolios, competing on clinician training depth rather than commodity pricing.
Hydrocolloid sponges comprise cross-linked carboxymethylcellulose, gelatin, and pectin matrices that form a cohesive gel upon contact with wound exudate, maintaining a moist healing interface with absorption capacities typically ranging from five to twenty times their dry weight. Their primary commercial purpose centers on partial-thickness wounds, pressure ulcers, and donor sites where autolytic debridement accelerates granulation tissue formation. The wound care application segment leads volume absorption due to chronic ulcer epidemiology, while post-operative care represents the fastest-growing application as ambulatory surgical centers adopt disposable absorbent formats to reduce nursing labor. Foam-composite product types command margin concentration because lamination with polyurethane layers addresses shear stress in immobile patients.
FDA 510(k) premarket notification requirements govern hydrocolloid sponge clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for absorbent wound dressings sold under CE marking. Japan's PMDA enforces QMS ministerial ordinances that foreign manufacturers must satisfy through in-country designated marketing authorization holders. Stakeholders must monitor reimbursement code consolidation across Medicare Advantage plans and Japan's long-term care insurance system, as bundled payment shifts will determine whether premium composite formats sustain price premiums over standard adhesive sponges.
Market Dynamics
Hospital procurement consolidation and reimbursement code bundling are compressing margins for standard hydrocolloid formats while favoring composite products with demonstrated cost-of-care reductions. This structural pressure is redirecting R&D investment toward performance-differentiated platforms.
Growth Catalysts
- Japan's long-term care insurance expansion:Reimbursement broadening for self-administered wound management in homecare settings is accelerating retail channel penetration of adhesive sponge formats.
- FDA 510(k) pathway compression:Streamlined premarket notification for absorbent wound devices is shortening development-to-commercialization timelines for hydrocolloid innovators.
- Alginate-hydrocolloid hybrid matrices:Biomedical polymer engineering advances are enabling next-generation dressings with enhanced exudate handling for diabetic ulcer protocols.
Market Restraints
- Carboxymethylcellulose feedstock volatility:Pharmaceutical-grade cellulose derivative supply concentrates among limited European chemical processors, creating input cost instability.
- EU MDR clinical evidence thresholds:Stricter documentation requirements for CE-marked absorbent dressings are extending regulatory timelines and compliance expenditures.
- Silver-impregnated foam substitution:Antimicrobial polyurethane alternatives are capturing hospital procurement share in heavily exuding wound categories.
Strategic Opportunities
- Germany's diabetic population wound burden:Chronic ulcer epidemiology in aging cohorts is expanding hospital procurement of advanced moisture-balanced dressings.
- Ambulatory surgical center disposable adoption:Same-day procedure growth is creating demand for labor-reducing absorbent formats in post-operative protocols.
- Digital wound monitoring integration:Sensor-embedded hydrocolloid platforms represent convergence between absorbent matrix technology and remote patient monitoring systems.
Industry Challenges
- Biomedical polymer engineering talent scarcity:Specialized formulation expertise for cross-linked gel matrices remains concentrated among limited academic and industrial research clusters.
- Multinational QMS ministerial compliance:Japan's PMDA ordinance requirements for foreign manufacturers necessitate in-country designated marketing authorization holder relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocolloid Sponges Market |
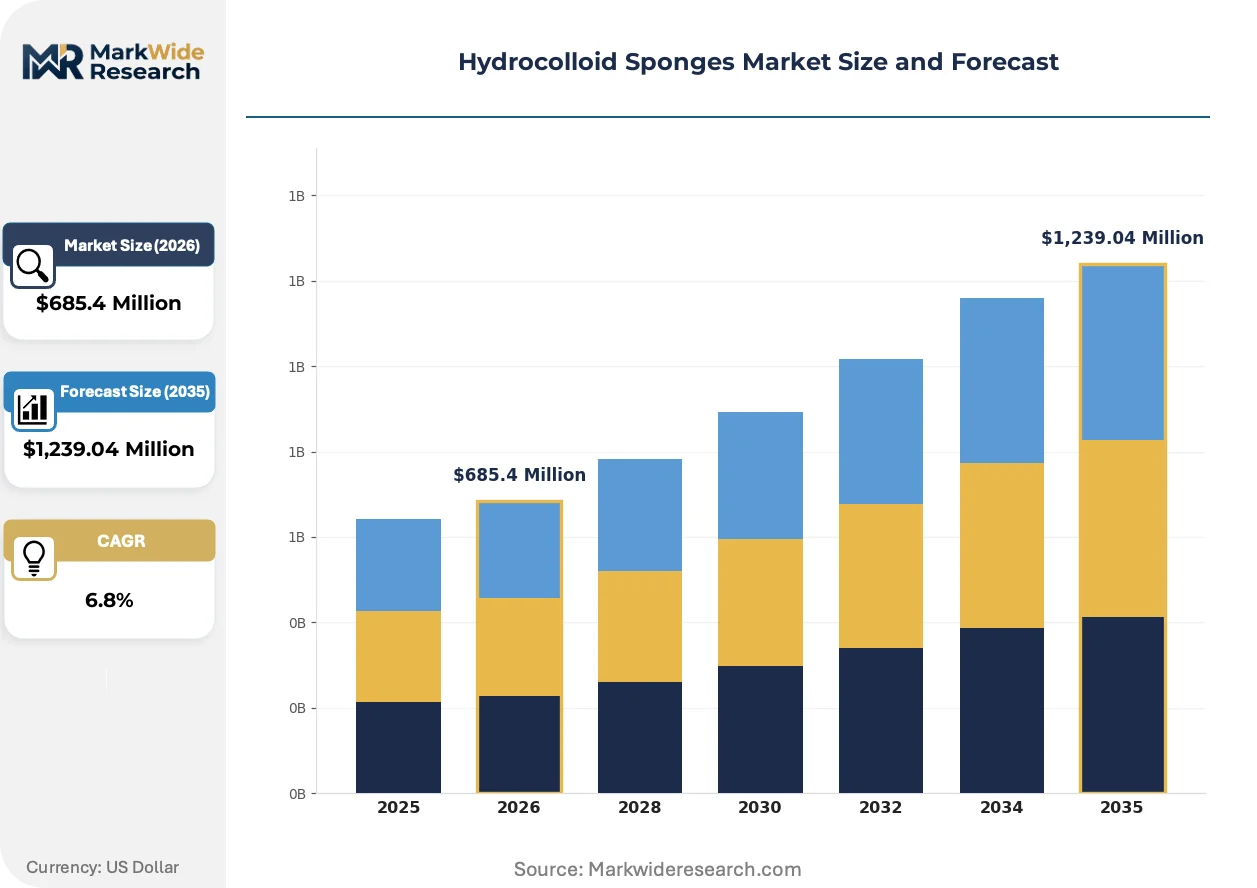
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Foam, Adhesive, Foam-Composite Application: Wound Care, Post-operative Care, Pain Management, Scab Treatment End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Distribution Channel: Pharmacies, Online Retail, Direct Sales, Medical Supply Distributors |
| Companies Covered | Smith & Nephew, 3M Company, Coloplast A/S, ConvaTec Group PLC, Cargill, Kerry Group, CP Kelco, Paul Hartmann, Avery Dennison, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocolloid Sponges Market Trends and Innovations
Material science convergence and regulatory pathway evolution are reshaping competitive differentiation in absorbent wound care. Innovation centers on extending wear duration, integrating monitoring capabilities, and compressing total cost of treatment.
Multilaminate foam-composite constructions are fragmenting the traditional hydrocolloid category by addressing shear stress management in immobile patient populations. Long-term care facilities and hospital systems managing pressure ulcer protocols are adopting these formats at accelerating rates. The technology is fragmenting procurement decisions previously dominated by single-layer adhesive sponges, creating tiered performance categories.
EU Medical Device Regulation implementation is elevating clinical evidence requirements for absorbent wound dressings seeking CE marking renewal. Manufacturers must now generate prospective performance data where predicate-based submissions previously sufficed. Western European hospital procurement committees are demanding documented cost-of-care outcomes, favoring suppliers with robust clinical portfolios.
Homecare channel expansion is altering traditional distribution economics for wound management products. Retail pharmacy and direct-to-patient models are displacing institutional procurement as the primary volume pathway in Japan's aging demographic segments. Germany's statutory health insurance system is adapting reimbursement mechanisms to accommodate this channel migration.
Hydrocolloid Sponges Market Segmentation
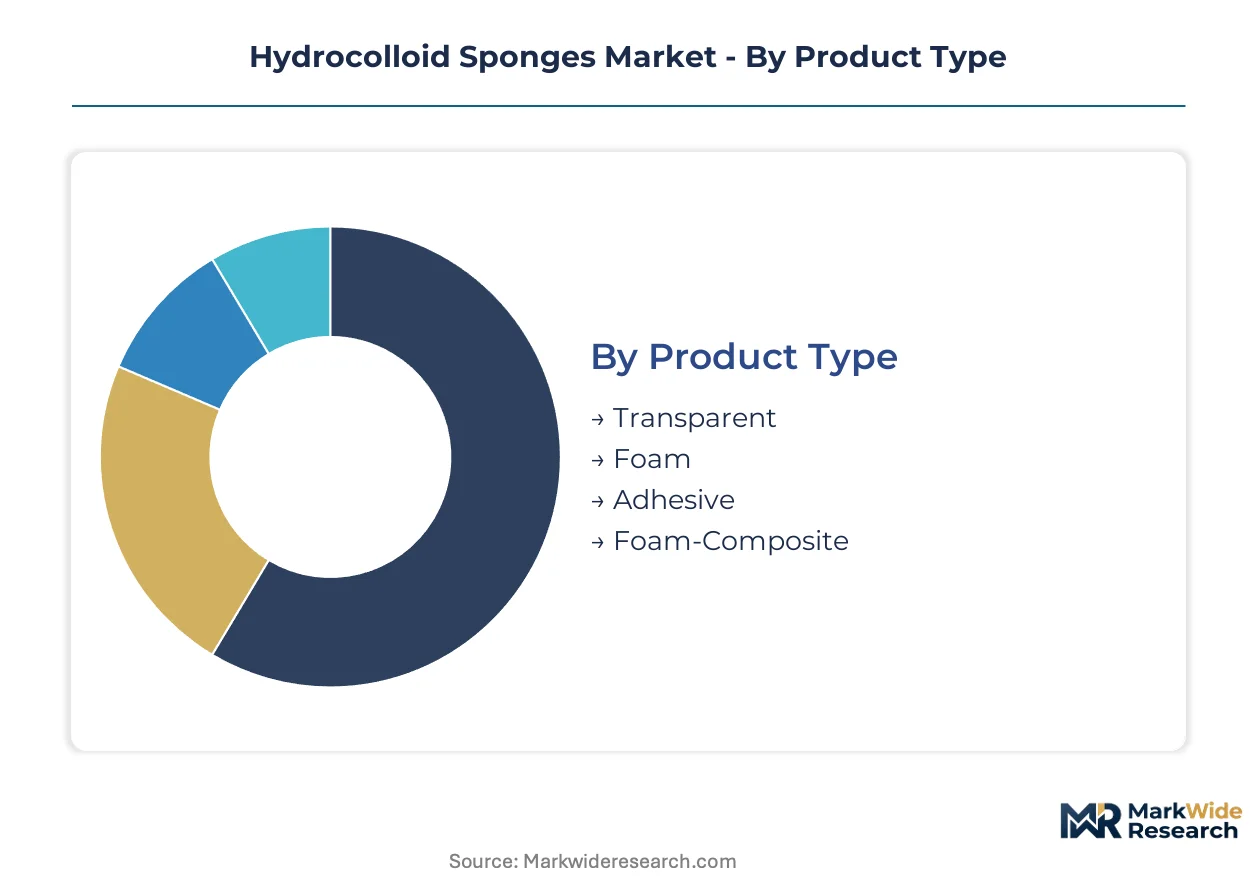
Segmentation in hydrocolloid sponges reveals how product architecture, clinical setting, and procurement channel interact to determine margin capture. Manufacturers configure portfolios across these dimensions to align with reimbursement mechanics and wound care protocol evolution.
Product Type:
Geographic concentration varies sharply by format sophistication—standard adhesive variants dominate domestic hospital procurement in developed markets, while foam-composite and transparent formats skew toward export-led premium positioning.
- Transparent:Polyurethane film backing enables wound visualization without dressing removal, reducing nursing labor in outpatient clinics. Demand concentrates in ambulatory surgical centers across Germany and Japan where protocol efficiency drives procurement decisions.
- Foam-Composite:Laminated polyurethane layers manage shear stress in immobile patients with pressure ulcer risk. Hospital systems in aging demographics favor this format for long-term care reimbursement optimization, though raw material costs compress margins versus standard alternatives.
- Adhesive:Cross-linked carboxymethylcellulose matrices with proprietary polymer backing dominate high-volume hospital contracts.
- Foam:Non-laminated absorbent structures serve cost-sensitive procurement segments and emerging market entry.
Adhesive formats command the established base. The steepest expansion runs through foam-composite variants.
Application:
Cost tier stratification separates acute inpatient protocols from self-administered outpatient management, with reimbursement codes determining which segments absorb R&D investment.
- Wound Care:Chronic ulcer management leverages autolytic debridement properties of gelatin-pectin matrices. Hospital procurement in Germany's diabetic population segments absorbs the majority of volume, with dressing change frequency driving total cost-of-care calculations.
- Post-operative Care:Same-day surgical discharge protocols favor disposable absorbent formats that reduce nursing assessment burden. Ambulatory surgical centers in Japan's metropolitan clusters are expanding adoption fastest as procedure volumes shift from inpatient settings.
- Pain Management:Hydrocolloid carrier matrices for topical analgesic delivery occupy niche therapeutic positioning.
- Scab Treatment:Cosmetic and minor trauma applications serve retail pharmacy channels with lower clinical validation requirements.
Wound care commands the established base. Post-operative care shows the steepest climb.
End User:
Customer type determines regulatory pathway complexity—institutional procurement demands 510(k) or CE-marked clinical evidence, while homecare channels prioritize packaging simplicity and reimbursement accessibility.
- Hospitals:Centralized procurement committees negotiate multi-year contracts based on cost-per-procedure metrics. Western European hospital systems increasingly require documented pressure ulcer prevention outcomes to justify premium composite format selection.
- Homecare:Japan's long-term care insurance expansion has created the fastest-expanding demand pool, with self-administered wound management reimbursement broadening retail channel penetration of adhesive sponge formats designed for patient or caregiver application.
- Clinics:Outpatient wound centers balance protocol standardization with inventory flexibility.
- Long-term Care Facilities:Pressure ulcer prevention protocols drive absorbent dressing consumption in immobile patient populations.
Hospitals command the established base. Homecare channels are gaining share fastest.
Distribution Channel:
Supply concentration among medical supply distributors is fragmenting as direct-to-patient models and pharmacy retail gain regulatory accommodation for reimbursement processing.
- Medical Supply Distributors:Institutional procurement consolidation favors distributors with logistics networks capable of just-in-time delivery to hospital systems. Contracts bundle hydrocolloid formats with broader wound care portfolios, locking out specialized manufacturers without full-line capability.
- Online Retail:Direct-to-patient platforms are capturing homecare segment growth in Japan where long-term care insurance reimbursement mechanisms have adapted to accommodate digital channel verification. Regulatory compliance for medical device e-commerce remains uneven across prefectural implementations.
- Pharmacies:Community and hospital outpatient dispensaries serve acute prescription needs.
- Direct Sales:Manufacturer field forces target large hospital system contracts with clinical training support.
Medical supply distributors command the established base. Online retail channels show the steepest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's hospital procurement channels exceeds that in Japan's retail pharmacy networks, creating divergent margin structures for identical hydrocolloid formats. Western European regulatory compliance costs elevate entry thresholds, while East Asian reimbursement expansion accelerates volume absorption. Regulatory pathway complexity fragments competitive positioning across jurisdictions.
United States
Ambulatory surgical center expansion and Medicare Advantage bundling drive demand for labor-reducing absorbent formats. FDA 510(k) premarket notification pathways compress development timelines for wound care innovators. The Minneapolis-St. Paul corridor concentrates biomedical polymer engineering talent and adhesive technology development.
Germany
Chronic ulcer prevalence among diabetic populations expands hospital procurement of advanced moisture-balanced dressings. EU Medical Device Regulation imposes stricter clinical evidence thresholds for CE-marked absorbent wound dressings. The Rhine-Ruhr industrial cluster hosts pharmaceutical-grade carboxymethylcellulose processing capabilities.
Japan
Aging demographics and long-term care insurance expansion accelerate homecare channel penetration of self-administered wound management products. PMDA QMS ministerial ordinances require foreign manufacturers to establish in-country designated marketing authorization holders. Tokyo metropolitan clusters concentrate retail pharmacy distribution networks for direct-to-patient models.
United Kingdom
NHS procurement consolidation favors suppliers with documented pressure ulcer prevention outcomes and cost-of-care reductions. MHRA post-Brexit regulatory alignment creates transitional compliance complexity for absorbent dressing manufacturers. The Cambridge-Oxford-London triangle concentrates biomedical research and wound matrix development expertise.
China
Domestic wound care protocol standardization and hospital tier classification systems create segmented demand for adhesive sponge formats. NMPA medical device registration requirements intensify for imported absorbent dressings. The Yangtze River Delta manufacturing corridor concentrates hydrocolloid raw material processing and contract fabrication capacity.
Hydrocolloid Sponges Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics in hydrocolloid sponge supply. The vendor base fragments across multinational healthcare conglomerates with vertically integrated alginate supply chains, specialized wound care pure-plays competing on clinician training depth, and regional chemical processors supplying pharmaceutical-grade cellulose derivatives. Three archetypes dominate: adhesive polymer science specialists, ostomy-adjacent portfolio builders, and biomedical polymer engineering consultancies. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturers securing captive feedstock arrangements and licensing proprietary cross-linking technologies.
Among the established healthcare conglomerates, Smith & Nephew, 3M Company, and Coloplast A/S exemplify divergent strategic positioning within the hydrocolloid sponge category. Smith & Nephew represents the vertically integrated archetype with upstream control over alginate raw material sourcing. 3M Company occupies a position anchored in proprietary adhesive polymer science and extended wear-time engineering. Coloplast A/S sits within the specialized portfolio tier, competing through clinician training infrastructure rather than commodity pricing. These three entities collectively illustrate how technology differentiation, supply chain configuration, and customer relationship depth create distinct competitive moats in absorbent wound care.
| Leading Market Players |
|---|
| Smith & Nephew |
| 3M Company |
| Coloplast A/S |
| ConvaTec Group PLC |
| Cargill |
| Kerry Group |
| CP Kelco |
| Paul Hartmann |
| Avery Dennison |
| Others |
Pricing and Supply Chain Analysis
Silver-impregnated foam substitution in heavily exuding wound categories simultaneously redraws procurement geography toward antimicrobial polyurethane suppliers and compresses pricing premiums for standard hydrocolloid formats in hospital contracts.
Pricing Analysis
Germany commands price premiums exceeding Japan's retail pharmacy networks for identical hydrocolloid formats. Three-tier pricing structure across premium composite, standard adhesive, and economy foam levels stratifies by certification grade and volume scale. Cost compression in standard adhesive tiers is intensifying because hospital procurement consolidation demands documented cost-of-care outcomes. Ambulatory surgical centers exhibit highest price sensitivity; Western European hospital systems with pressure ulcer prevention mandates show lowest.
Supply Chain Analysis
Pharmaceutical-grade carboxymethylcellulose processing concentrates among limited European chemical processors in the Rhine-Ruhr corridor. Raw material dependencies span pharmaceutical-grade cellulose derivatives, gelatin from bovine and porcine sources, and pectin from citrus processing. Single-source vulnerability in carboxymethylcellulose feedstock creates input cost instability when pharmaceutical-grade specifications tighten. Distribution runs through medical supply distributors bundling hydrocolloid formats with broader wound care portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation across Western Europe and Japan's long-term care insurance expansion have shifted buyer power toward institutional purchasing committees and retail pharmacy networks.
For Market Incumbents: Fortify upstream control over alginate raw material sourcing through captive supply arrangements with seaweed harvesting operations in Ireland and Norway. Deepen clinician training infrastructure to differentiate beyond commodity pricing as silver-impregnated foam alternatives capture share in exuding wound categories. For New Entrants and Emerging Players: Digital wound monitoring integration represents an underserviced layer where incumbents lack sensor-embedded platform capabilities. Penetrate Japan's homecare channel through direct-to-patient models with packaging simplicity designed for self-administered wound management reimbursement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wound care pure-plays competing on clinician training depth rather than manufacturing scale. Five-to-ten year viability hinges on regulatory pathway efficiency for CE marking renewal under EU MDR. Watch for FDA 510(k) clearance compression as inflection signal for development-to-commercialization timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence thresholds demand prospective performance data for absorbent dressing renewal. |
| Hospital System Partnership | Multi-year contracts with Western European procurement committees lock in volume through cost-per-procedure metrics. |
| Backward Integration | Captive alginate supply from seaweed harvesting operations secures raw material cost stability against pharmaceutical-grade cellulose volatility. |
| Software Companion Development | Sensor-embedded hydrocolloid platforms converge absorbent matrix technology with remote patient monitoring systems. |
| Reimbursement Strategy | Japan's long-term care insurance expansion enables retail channel penetration of adhesive sponge formats for homecare. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical polymer engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions driving volume and value estimates. Primary interviews combined with secondary validation against FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up product-type segmentation triangulated against top-down regional demand aggregation.
Product type, application, end user, and distribution channel dimensions structured the analytical framework across the analysis window. CAGRs derived from segment-level growth trajectory modeling incorporating chronic wound epidemiology shifts, ambulatory surgical center expansion rates, and reimbursement code consolidation patterns. Forecast inputs included diabetic population projections, long-term care insurance enrollment curves, and biomedical polymer engineering talent pipeline assessments.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR implementation timelines, and Japan's PMDA QMS ministerial ordinances; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as silver-impregnated foam substitution rates and carboxymethylcellulose feedstock volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Custom Procedure Packs (CPT) Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Compression Socks Market
Medical Supplies
Skin Tac Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Emesis Bag Market