
 Workflow Automation Market | 2026-2036
Workflow Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Workflow Automation Market Intelligence
Subscription-based orchestration of multi-step business processes is shifting how vendors monetize workflow automation. ServiceNow leverages its enterprise IT service management heritage to anchor premium deployments in regulated industries. Zapier competes on breadth of pre-built application connectors for mid-market users. Microsoft Power Automate extends its position through native integration with Office 365 and Azure ecosystems.
Workflow automation encompasses software platforms that execute, manage, and optimize sequences of tasks across disparate systems through rule-based logic, API connectivity, and conditional branching with sub-second response thresholds. Its primary commercial purpose is to reduce manual handoffs, minimize error rates, and accelerate cycle times in repetitive operational processes. Cloud-based deployment leads in new customer acquisition due to lower infrastructure overhead and faster implementation timelines. Robotic process automation commands the largest share of solution spending, though low-code development is expanding fastest as business units gain direct authoring capabilities. Integration platforms capture disproportionate margin pools through recurring data-volume fees and premium connector tiers.
The EU AI Act imposes risk-classification requirements on automated decision workflows, compelling vendors to embed audit trails and human-in-the-loop checkpoints. The US FDA and HIPAA frameworks shape automation design in healthcare claims processing and patient data routing, mandating access controls and breach notification protocols. ISO 27001 certification has become a baseline qualification for enterprise procurement evaluations. Stakeholders must monitor how emerging algorithmic accountability rules in multiple jurisdictions redefine liability allocation between platform providers and their customers.
Market Dynamics
The EU AI Act's risk-classification framework is forcing vendors to rearchitect automated decision systems with embedded audit trails and human-in-the-loop checkpoints, compressing implementation timelines and elevating compliance costs across procurement cycles.
Growth Catalysts
- Compliance automation mandates:Financial services firms in Germany's industrial corridor are expanding adoption of tracking solutions as the EU AI Act reshapes procurement criteria for automated decision systems.
- Low-code democratization:Business units are gaining direct authoring capabilities through visual workflow builders, accelerating deployment velocity without IT dependency.
- API ecosystem density:Pre-built connector libraries spanning enterprise SaaS platforms are reducing integration friction for mid-market process orchestration.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dependency creates single-point-of-failure exposure for multi-tenant orchestration platforms during regional outages.
- Technical debt accumulation:Legacy system integration requires brittle custom middleware that fragments data lineage and complicates governance audits.
- Regulatory fragmentation:Divergent algorithmic accountability rules across US state jurisdictions and EU member states multiply compliance engineering overhead.
Strategic Opportunities
- Healthcare claims automation:HIPAA-compliant workflow engines for patient data routing remain underpenetrated relative to financial services adoption curves.
- Edge-to-cloud orchestration:Convergence of IoT device management with centralized process automation opens industrial manufacturing verticals previously served by siloed SCADA systems.
- ISO 27001 certification arbitrage:Vendors achieving baseline enterprise qualification faster than competitors capture procurement evaluations in regulated industries.
Industry Challenges
- Workflow architect scarcity:Professionals capable of mapping complex business logic into rule-based automation with sub-second response thresholds command premium compensation.
- Integration complexity:Conditional branching across disparate systems requires sustained engineering investment to maintain API compatibility through vendor upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workflow Automation Market |
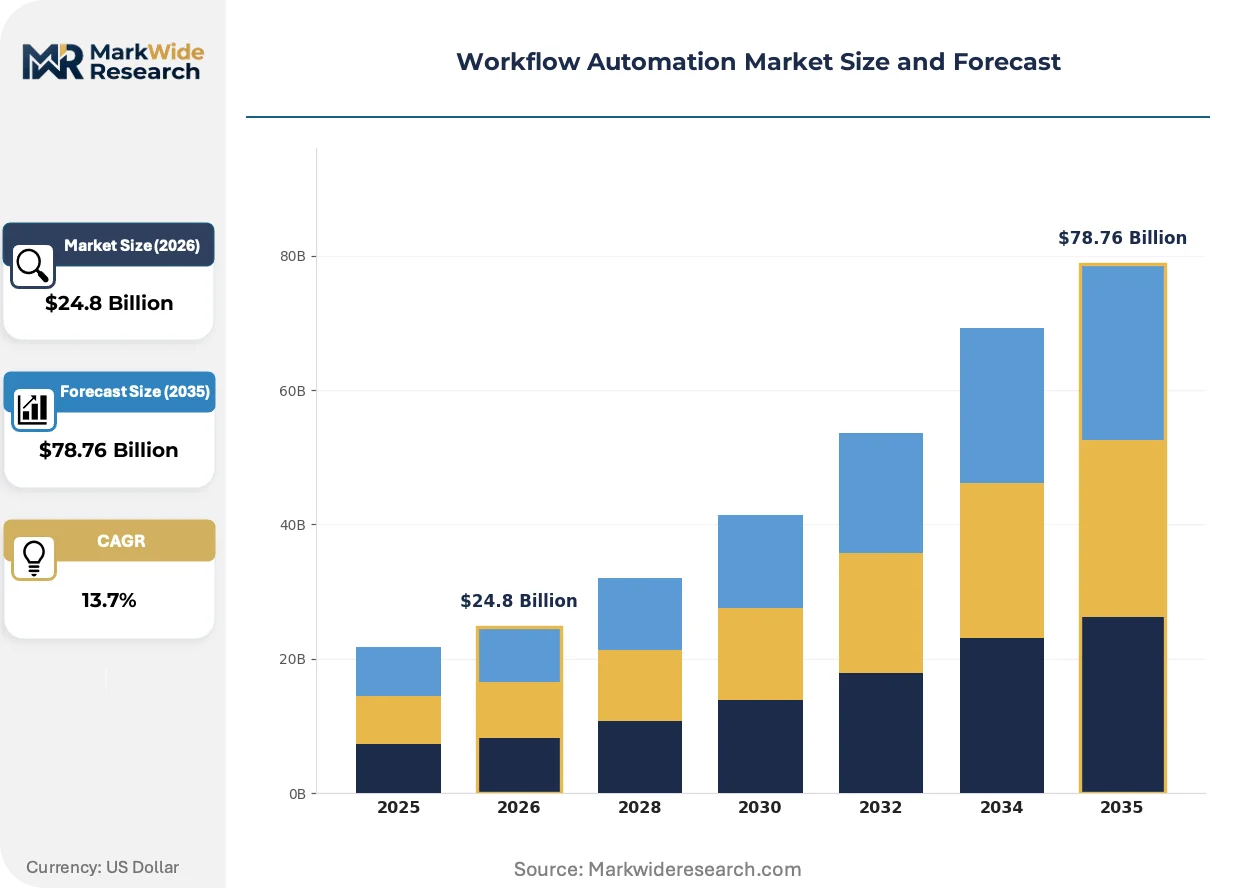
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $78.76 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution/Offering: Robotic Process Automation, Business Process Management, Integration Platform, Low-Code Development, Decision Management, Document Management Application: Invoice Processing, Employee Onboarding, Customer Support, Compliance Tracking, Order Management End User/Industry Vertical: BFSI, Telecommunications, Manufacturing, Education, Logistics & Transportation |
| Companies Covered | Workato, n8n, Zapier, Getint, ServiceNow, Make, Tray.io, Jira Automation, Microsoft Power Automate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workflow Automation Market Strategic Shifts & Innovations
Generative AI is embedding natural language interfaces into workflow design tools, collapsing the technical barrier between process documentation and executable automation. This convergence is compressing time-to-deployment while expanding the addressable user base beyond traditional IT departments.
Agentic AI systems are automating multi-step decision sequences previously requiring human judgment in exception handling. Insurance underwriting teams in London and Singapore are piloting autonomous claim routing with embedded confidence scoring. The technology is automating variance detection in document-heavy processes that previously stalled in manual queues.
The EU AI Act's high-risk system designation is compelling healthcare automation vendors to reconstruct audit architectures for patient data workflows. EMA-aligned documentation requirements are propagating through pharmaceutical supply chain automation procurements. German medical device manufacturers are front-loading compliance engineering to preempt certification delays.
Subscription orchestration is displacing perpetual licensing for enterprise workflow deployments. Buyers in financial services are negotiating consumption-based pricing tied to transaction volumes rather than seat counts. This shift is most visible in US and UK markets where procurement functions have consolidated vendor evaluation authority.
Workflow Automation Market Segmentation
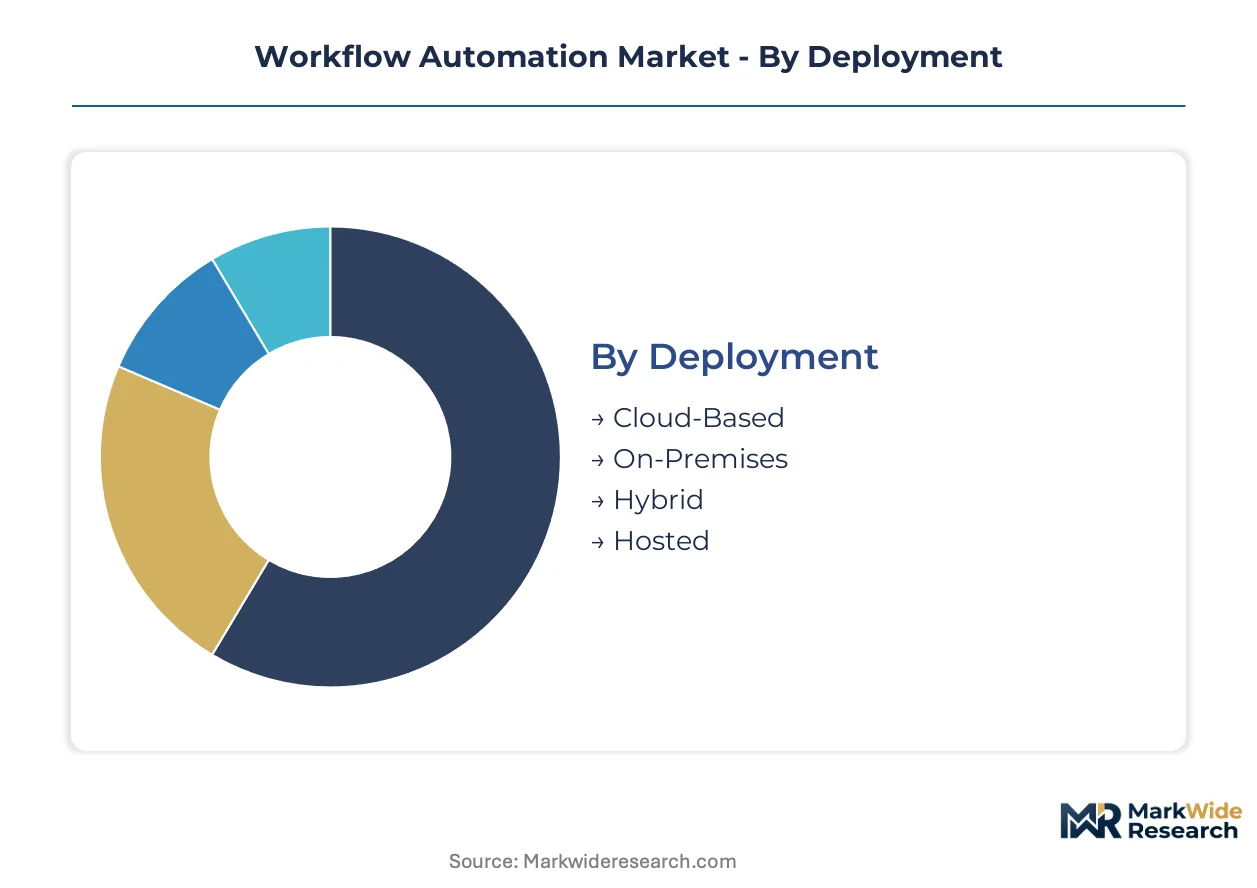
Workflow automation segmentation reveals how deployment architecture, solution depth, and industry-specific compliance requirements reshape procurement priorities. Buyers select configuration patterns based on data sovereignty mandates, legacy system entanglement, and the technical maturity of their integration teams.
Deployment:
Cloud-based configurations dominate new customer acquisition where infrastructure overhead reduction accelerates procurement cycles, while on-premises and hybrid architectures persist in regulated environments requiring data residency controls.
- Cloud-Based:Multi-tenant architectures with API-first connectivity eliminate capital expenditure for orchestration infrastructure. German financial services firms in Frankfurt and Munich are standardizing on cloud deployments as the EU AI Act's audit trail requirements become embedded in procurement checklists.
- On-Premises:Dedicated hardware installations with air-gapped network segments maintain complete data sovereignty. Healthcare providers in the US route patient records through on-premises workflow engines to satisfy HIPAA breach notification protocols and FDA access control mandates.
- Hybrid:Split-load architectures process sensitive data locally while pushing analytics to cloud substrates. Japanese manufacturers along the Tokyo-Osaka industrial corridor deploy hybrid models to balance METI data localization guidance with supply chain visibility requirements.
- Hosted:Single-tenant cloud instances managed by vendor operations teams reduce internal IT burden. Mid-market enterprises in Singapore select hosted deployments to satisfy MAS financial sector technology risk management guidelines without building internal DevOps capabilities.
Cloud-based deployments lead volumes today; hybrid configurations are gaining share fastest as sovereignty-conscious buyers seek architectural compromise.
Solution/Offering:
Solution selection tracks the technical sophistication of buyer organizations, with code-heavy platforms commanding premium pricing and visual builders expanding the addressable user base.
- Robotic Process Automation:Software bots executing repetitive UI interactions across legacy applications without API access. BFSI operations teams in London and New York deploy RPA for invoice processing where core banking systems lack modern integration endpoints.
- Business Process Management:End-to-end process modeling with human task orchestration and SLA monitoring. Telecommunications carriers in South Korea use BPM suites to manage customer support escalation workflows with MFDS-aligned documentation for quality audits.
- Integration Platform:Middleware hubs normalizing data flows across heterogeneous SaaS and on-premises systems. Logistics providers in the Netherlands connect warehouse management with customs declaration APIs through integration platforms to satisfy EU customs union requirements.
- Low-Code Development:Visual workflow builders enabling business analysts to construct automation without engineering support. Manufacturing quality teams in India's industrial corridors deploy low-code tools for defect tracking automation under BIS quality management standards.
- Decision Management:Rule engines executing complex business logic with explainable decision trees. Insurance underwriters in Switzerland embed decision management for claims routing to satisfy Swissmedic pharmacovigilance reporting timelines.
- Document Management:Intelligent capture and routing systems extracting structured data from unstructured files. Education institutions in Canada process student enrollment documentation through automated extraction pipelines aligned with provincial privacy commissioners' data handling directives.
Robotic Process Automation leads volumes today; Low-Code Development is climbing the fastest as business units gain direct authoring autonomy.
Application:
Application focus determines integration complexity, with document-heavy processes requiring specialized capture technologies and transaction workflows demanding sub-second response reliability.
- Invoice Processing:Automated extraction of line-item data from supplier documents with three-way matching against purchase orders. Manufacturing procurement teams in Germany's automotive supply chain deploy invoice automation to compress payment cycles under KBA supplier financing pressure.
- Employee Onboarding:Orchestrated provisioning across HR, IT, and facilities systems with compliance documentation tracking. Technology firms in Ireland sequence onboarding workflows to satisfy GDPR data processor agreement requirements for EU-based hires.
- Customer Support:Ticket routing, sentiment analysis, and resolution prediction across omnichannel interaction histories. Telecommunications operators in Brazil deploy support automation to manage ANVISA-mandated service quality metrics for healthcare-critical communications infrastructure.
- Compliance Tracking:Automated evidence collection and regulatory reporting with audit-ready documentation trails. Financial services firms in Singapore implement compliance tracking to satisfy MAS technology risk management and cyber resilience requirements.
- Order Management:End-to-end orchestration from quote-to-cash with inventory allocation and fulfillment sequencing. Retail logistics providers in the US route orders through automated fulfillment logic to meet FTC mail order rule delivery commitment disclosures.
Invoice Processing leads volumes today; Compliance Tracking is expanding most quickly as regulatory audit frequency intensifies across jurisdictions.
End User/Industry Vertical:
Vertical selection reflects regulatory exposure and process standardization maturity, with highly regulated industries prioritizing audit architectures and manufacturing emphasizing OT-IT convergence.
- BFSI:Banking, insurance, and capital markets operations with stringent audit and data protection requirements. German private banks automate MiFID II suitability documentation through workflow engines with embedded EBA guideline compliance checkpoints.
- Telecommunications:Network operations, customer lifecycle management, and regulatory reporting at scale. South Korean carriers automate network fault escalation workflows under KCC service continuity mandates for critical infrastructure designation.
- Manufacturing:Production scheduling, quality management, and supply chain coordination across plant-floor and enterprise systems. Industrial automation corridors in Germany integrate workflow platforms with SCADA systems to satisfy CE marking documentation requirements for machinery safety.
- Education:Student lifecycle management, research administration, and alumni engagement orchestration. Australian universities deploy workflow automation for research ethics approvals aligned with NHMRC and ARC funding compliance timelines.
- Logistics & Transportation:Freight routing, customs documentation, and fleet maintenance scheduling across multimodal networks. UAE logistics hubs automate customs clearance workflows to satisfy MOHAP pharmaceutical import permit synchronization with Dubai Customs declarations.
BFSI leads volumes today; Manufacturing is gaining share fastest as Industry 4.0 investments accelerate OT-IT integration roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping procurement geography as vendors relocate compliance engineering resources toward jurisdictions with clearer algorithmic accountability frameworks. The cost-of-compliance gap between the EU AI Act's high-risk system requirements and emerging market regimes is concentrating platform development investment in specific regulatory corridors.
United States
Financial services automation procurement concentrates in New York and Chicago as HIPAA and FDA frameworks shape healthcare claims processing investments. The SEC's disclosure requirements for algorithmic trading systems are elevating audit architecture specifications in capital markets technology procurement. Silicon Valley clusters dominate low-code platform development for enterprise SaaS integration.
Germany
Industrial automation corridors in Bavaria and Baden-Württemberg drive manufacturing workflow adoption as KBA supplier financing pressures compress payment cycle automation timelines. The EU AI Act's risk-classification framework is embedding compliance checkpoints in procurement evaluations across Frankfurt's banking sector. German medical device manufacturers front-load certification engineering to preempt EMA-aligned documentation delays.
United Kingdom
Insurance underwriting automation pilots in London deploy autonomous claim routing with embedded confidence scoring. The Financial Conduct Authority's operational resilience requirements are mandating sub-second response thresholds for critical business process automation. Edinburgh-Glasgow financial services clusters expand compliance tracking solution adoption.
Singapore
MAS technology risk management guidelines are standardizing hosted deployment procurement for mid-market enterprises lacking internal DevOps capabilities. The city-state's logistics hub automation satisfies MOHAP pharmaceutical import permit synchronization with customs declarations. Regional headquarters concentration drives multi-jurisdiction compliance orchestration platform demand.
Japan
Tokyo-Osaka industrial corridor manufacturers deploy hybrid architectures balancing METI data localization guidance with supply chain visibility requirements. PMDA pharmacovigilance reporting timelines shape pharmaceutical workflow automation specifications. Kanto region telecommunications carriers automate network fault escalation under KCC service continuity mandates.
Workflow Automation Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with enterprise IT heritage anchoring premium positioning in regulated industries while connector breadth drives mid-market penetration. The vendor base organizes around three strategic archetypes: platform incumbents leveraging cloud ecosystem integration, pure-play orchestration specialists competing on workflow design velocity, and legacy IT service management extenders. Dominant competitive moves include API ecosystem expansion through partner marketplaces and compliance certification acceleration to capture procurement evaluations in financial services and healthcare verticals.
Among pure-play orchestration specialists, n8n and Make exemplify the open-source and visual-builder archetypes respectively, while ServiceNow and Microsoft Power Automate occupy positions as platform incumbents extending from adjacent enterprise software domains. Tray.io sits within the integration-platform tier competing on data-volume pricing models. These five companies represent the competitive spectrum from developer-centric workflow tooling to business-user-accessible orchestration layers.
| Leading Market Players |
|---|
| Workato |
| n8n |
| Zapier |
| Getint |
| ServiceNow |
| Make |
| Tray.io |
| Jira Automation |
| Microsoft Power Automate |
| Others |
Cost & Logistics Intelligence
ISO 27001 certification requirements gate qualified supply access for enterprise procurement evaluations while anchoring premium-tier pricing for vendors serving regulated industries. Buyers in financial services and healthcare verticals absorb higher subscription rates to satisfy audit architecture mandates embedded in HIPAA and EU AI Act compliance frameworks.
Pricing Analysis
Capacity additions in cloud infrastructure regions are reshaping price floors for multi-tenant orchestration platforms as hyperscaler competition intensifies. Subscription-based SaaS tiers dominate, with pricing stratifying across enterprise, professional, and starter levels based on API call volumes and connector library depth. Cost compression in the mid-market tier is intensifying because Zapier and Make compete aggressively on visual-builder accessibility. Small and medium enterprises exhibit highest price sensitivity; regulated BFSI buyers show lowest sensitivity due to compliance-driven procurement authority.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for ServiceNow and Microsoft Power Automate deployments, while self-service digital routes serve mid-market adopters. Engineering talent concentrates in the United States, Germany, and India for workflow platform development. Cloud compute capacity draws from hyperscaler regions in Virginia, Frankfurt, and Singapore. Single-source vulnerability in API connector maintenance creates supply chain risk when third-party SaaS vendors deprecate endpoints. Distribution runs through vendor-managed marketplaces and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The workflow automation market functions as a geographic-arbitrage play where vendors relocate compliance engineering resources toward jurisdictions with clearer algorithmic accountability frameworks, exploiting the cost differential between EU AI Act high-risk system requirements and emerging market regimes.
For Market Incumbents: Anticipate margin compression from low-code democratization by accelerating ISO 27001 certification timelines to capture procurement evaluations before competitors achieve baseline enterprise qualification. Defend position through deeper vertical integration into healthcare claims processing workflows where HIPAA-compliant engines remain underpenetrated relative to financial services saturation.
For New Entrants and Emerging Players: Partner marketplace routes offer the fastest path to scaling API connector breadth without engineering the full integration stack internally. Target manufacturing quality teams in India's industrial corridors deploying low-code defect tracking tools under BIS standards. Pursue edge-to-cloud orchestration pilots with German automotive suppliers seeking SCADA convergence.
For Investors and Strategic Acquirers: Roll-up economics work for pure-play orchestration specialists because enterprise buyers consolidate vendor relationships under procurement function centralization. Platform consolidation targeting sub-scale integration-platform vendors offers viable exit pathways. Watch MAS technology risk management guideline expansions across ASEAN markets as inflection indicator for hosted deployment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Pre-built connector libraries reduce integration friction for mid-market process orchestration in Germany's banking corridor. |
| Compliance Certification Acceleration | ISO 27001 achievement ahead of competitors captures procurement evaluations in HIPAA-regulated healthcare verticals. |
| Vertical Workflow Specialization | Healthcare claims automation engines address underpenetrated patient data routing relative to financial services adoption curves. |
| Hybrid Architecture Development | Split-load models balance METI data localization with supply chain visibility for Japanese manufacturers. |
| Generative AI Interface Integration | Natural language workflow builders collapse technical barriers between process documentation and executable automation. |
Research Approach
Bottom-up enterprise deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists informed demand-side validation. Secondary sources include SEC filings, hyperscaler capex disclosures, and EU regulatory impact assessments. Triangulation across these inputs ensures segmentation accuracy.
Input-output matrices map deployment architecture, solution depth, and vertical application to derive volume and value estimates across the projection horizon. Modeled dimensions span cloud versus on-premises configuration, RPA through low-code solution tiers, and BFSI through manufacturing end-use industries. CAGRs emerge from regression analysis against technology adoption curves and regulatory compliance expenditure patterns. Agentic AI pilot penetration in insurance underwriting serves as a key forecast sensitivity input.
The model assumes a particular technology adoption path; alternative pathways for generative AI interface deployment would alter the outlook. Forecasts reflect documented assumptions about EU AI Act implementation timelines and HIPAA enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Voice Picking Solutions Market
Automation
Pneumatic Tube System Market
Automation
Workload Scheduling and Automation Market
Automation
Home Automation System Market
Automation
Network Automation Market
Automation
Global Business Process Automation Software Market
Automation
Middle East and Africa Workforce Management Market
Automation
Workload Automation Software Market
Automation
Postal Automation System Market
Automation
Italy Marketing Automation Software Market
Automation
Home Automation Market
Automation
Europe Marketing Automation Software Market
Automation
Escalator Control Systems Market
Automation
Terminal Automation Systems Market
Automation
Parcel Sorting System Market
Automation
Lab Automation Market