
 Terminal Automation Systems Market | 2026-2036
Terminal Automation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Terminal Automation Systems Market Analytics
API 2350 overfill protection certification is reorganizing procurement standards across liquid storage terminals. Honeywell Process Solutions leverages its distributed control system heritage to anchor large-scale refinery terminal projects in North America. Yokogawa competes through precision instrumentation integration, while ABB specializes in electrification-automation bundles that reduce commissioning cycles for brownfield upgrades.
Terminal automation systems encompass hardware controllers, supervisory software, and communication networks that manage product flow, tank gauging, and safety interlocks in bulk liquid handling facilities; these installations typically operate with SIL-rated safety loops and real-time inventory reconciliation to prevent spills and optimize throughput. Hardware and integrated solutions segments lead current revenue as terminals replace obsolete relay logic with PLC-SCADA architectures, while cloud computing deployments represent the fastest-expanding technology category as operators seek remote diagnostics and predictive maintenance capabilities across geographically dispersed assets. The oil and gas end user segment sustains the dominant share of installed base, though chemical industry adoption is accelerating as multiproduct terminals require flexible batch handling and automated blending controls.
EPA spill prevention regulations under 40 CFR 112 and OSHA process safety management standards shape US terminal automation specifications, while EU F-Gas Regulation and ATEX directives mandate leak detection and explosion-proof instrumentation for European facilities. IEC 61511 functional safety standards govern safety instrumented system design across international projects, creating compliance-driven replacement cycles for legacy installations. Stakeholders must weigh cybersecurity certification against operational technology integration timelines as IT-OT convergence exposes terminal networks to evolving threat landscapes.
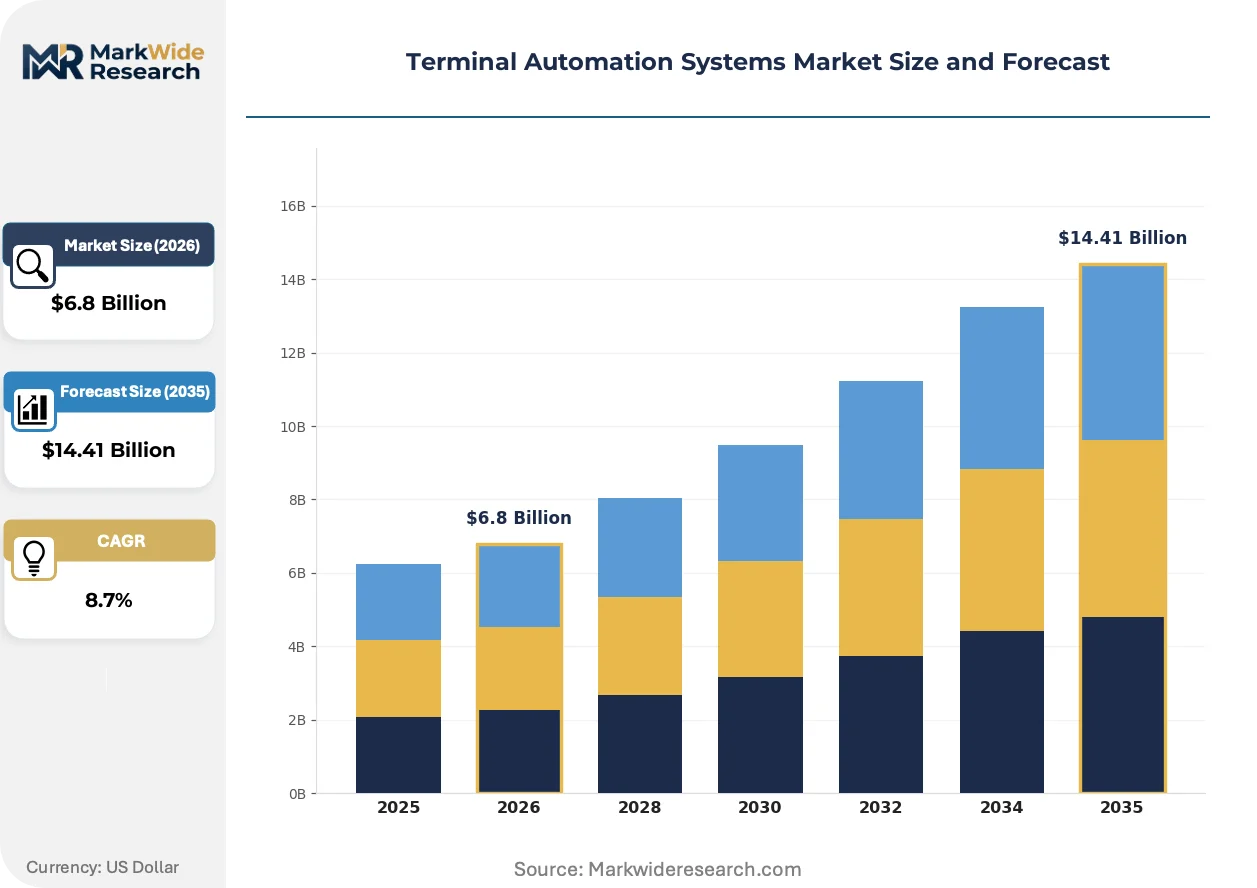
Market Dynamics
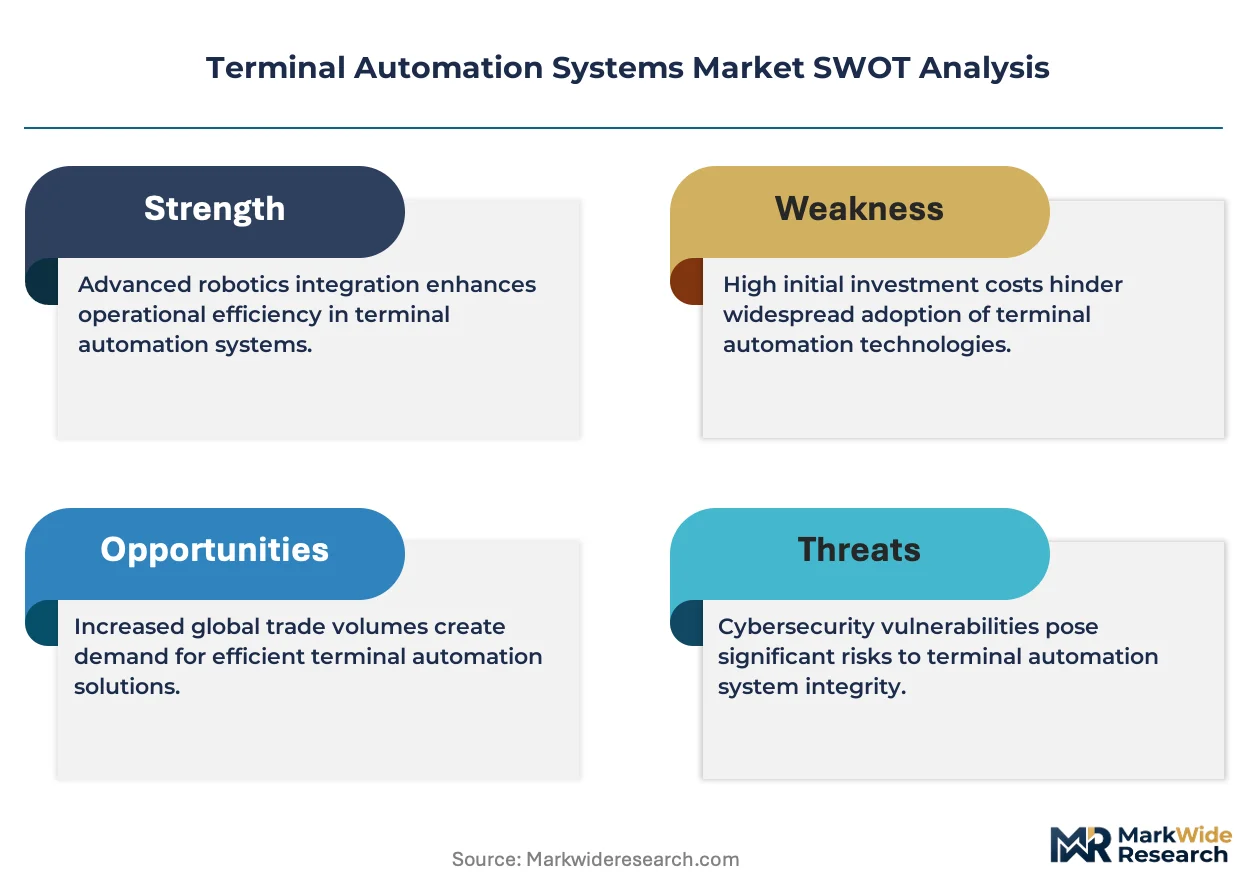
IT-OT convergence is redefining terminal automation architectures as operators replace air-gapped legacy systems with networked intelligence platforms that expose critical infrastructure to escalating cyber threats.
Growth Catalysts
- EPA 40 CFR 112 spill prevention mandates:US liquid storage facilities face intensified inspection schedules and documentation requirements, forcing wholesale replacement of manual tank gauging with automated overfill protection systems.
- Multiproduct chemical terminals:European and Asian chemical distributors require flexible batch handling and automated blending controls to manage expanding product portfolios through shared infrastructure.
- Cloud-native predictive maintenance:Remote diagnostics platforms reduce unplanned downtime across geographically dispersed assets, particularly for operators managing coastal refining clusters and inland distribution networks simultaneously.
Market Restraints
- Specialized engineering talent scarcity:Functional safety certification for IEC 61511 compliance requires scarce control systems engineers, extending project timelines and inflating implementation costs.
- Proprietary protocol fragmentation:Legacy vendor lock-in around fieldbus architectures restricts interoperability, complicating brownfield upgrades and multi-vendor integration.
- Extended capital recovery cycles:Large-scale terminal automation investments require 7-10 year payback horizons, constraining adoption among independent storage operators with limited balance sheet capacity.
Strategic Opportunities
- India's petroleum product hub expansion:Jawaharlal Nehru Port Trust and Hazira terminal developments create greenfield demand for integrated automation platforms without legacy system baggage.
- EU F-Gas Regulation leak detection requirements:Refrigerated storage terminals for LNG and petrochemical gases must deploy automated monitoring systems, opening specialized instrumentation markets.
- Edge-to-cloud hybrid architectures:Convergence of time-sensitive networking with containerized analytics enables real-time optimization while maintaining deterministic safety loop performance.
Industry Challenges
- SIL-rated system recertification complexity:Updating safety instrumented systems without triggering full process hazard analyses demands specialized validation expertise that outstrips current consultant availability.
- Obsolescent PLC migration:Relay logic replacement projects frequently uncover undocumented interlock dependencies, inflating commissioning timelines and requiring reverse engineering of decades-old control narratives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terminal Automation Systems Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
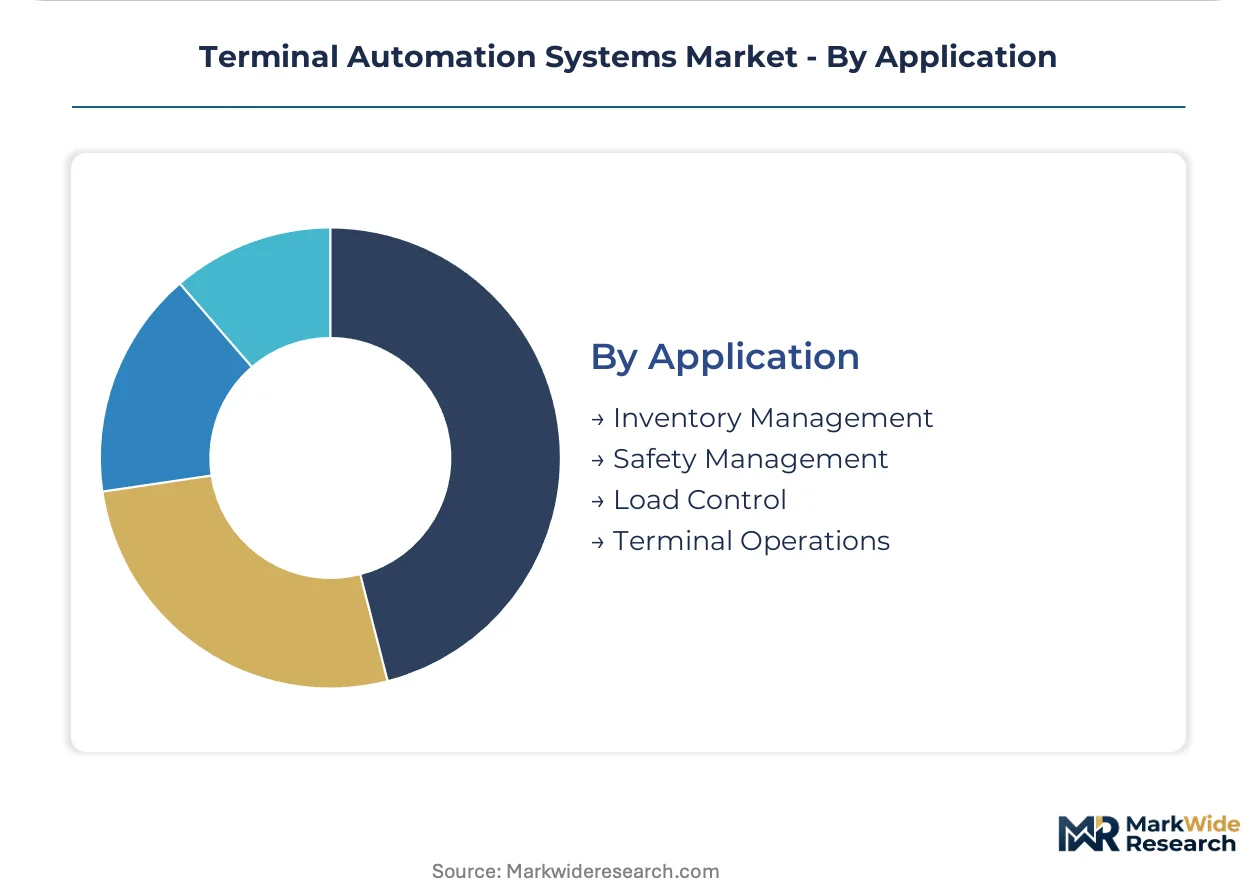
| Segmentation | Product Type: Hardware, Software, Services, Integrated Solutions End User: Oil & Gas, Chemical Industry, Shipping, Utilities Technology: SCADA, PLC, DCS, Cloud Computing Application: Inventory Management, Safety Management, Load Control, Terminal Operations |
| Companies Covered | Siemens, Yokogawa, Honeywell Process Solutions, Rockwell Automation, Endress+Hauser, ABB, Schneider Electric, Cimation, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terminal Automation Systems Market Evolving Landscape
Digital twin technology is compressing commissioning timelines while AI-driven anomaly detection reshapes maintenance economics across bulk liquid handling facilities worldwide.
Edge-native analytics platforms are fragmenting the traditional SCADA hierarchy by embedding machine learning inference directly within field controllers. Mid-scale independent terminals in the US Gulf Coast and Rotterdam-Antwerp corridor are deploying these architectures fastest. Real-time pattern recognition at the edge reduces central infrastructure dependency while enabling sub-second safety responses that cloud-reliant systems cannot match.
EU F-Gas Regulation phase-down schedules are forcing refrigerated terminal operators to retrofit automated leak detection and refrigerant recovery systems. Facilities storing cryogenic liquids or compressed gases face stepped compliance deadlines through 2030. German and Dutch terminal operators are consolidating sensor networks with existing fire and gas detection infrastructure to minimize incremental wiring costs.
Outcome-based service contracting is displacing traditional hardware-procurement-plus-maintenance agreements among integrated oil companies. Shell, BP, and TotalEnergies now demand guaranteed availability metrics with vendor penalties for unplanned downtime. Automation suppliers respond with remote operations centers that assume 24/7 monitoring responsibility, transferring operational risk from terminal operators to technology providers.
Terminal Automation Systems Market Segmentation
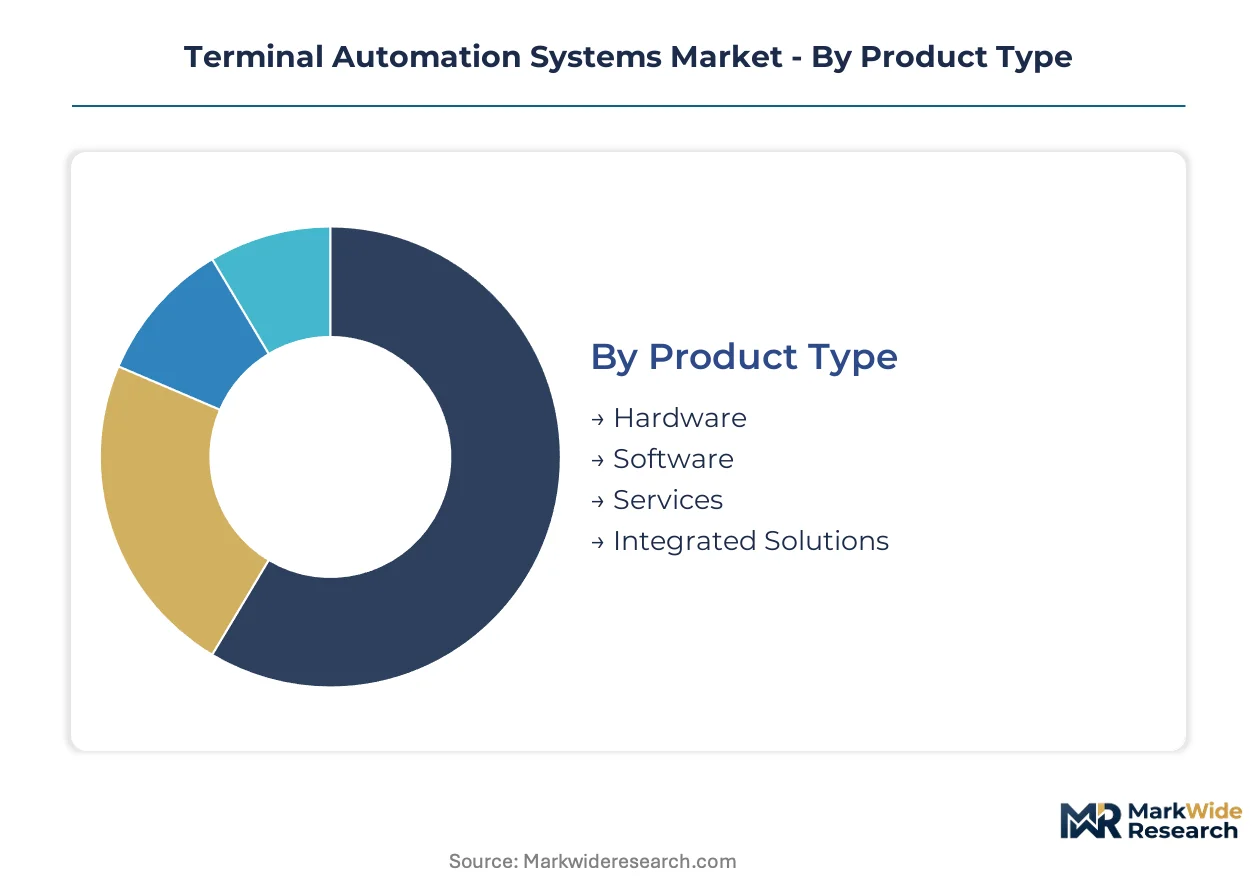
Terminal automation procurement channels vary sharply by segment maturity. Hardware and integrated solutions flow through established distributor networks with long lead times, while software and cloud deployments increasingly route through direct vendor relationships with subscription terms.
Product Type:
Channel economics favor different procurement models across product categories.
- Hardware:Controllers, instrumentation, and field devices constitute the physical layer of terminal automation. Demand concentrates in US Gulf Coast refining clusters where EPA 40 CFR 112 mandates are forcing wholesale replacement of obsolete relay logic with SIL-rated safety systems.
- Integrated Solutions:Bundled hardware-software packages reduce commissioning complexity for brownfield upgrades. European terminals along the Rotterdam-Antwerp corridor favor these packages to minimize vendor coordination overhead during F-Gas Regulation compliance retrofits.
- Software:Supervisory platforms and inventory reconciliation systems enable real-time tank farm visibility.
- Services:Engineering, commissioning, and ongoing maintenance support extend system lifecycles.
Hardware dominates installed base. Integrated solutions are where expansion concentrates.
End User:
Application requirements differ substantially across terminal operator types.
- Oil & Gas:Refinery terminals and bulk storage facilities require high-availability systems for continuous product movement. US operators face intensified EPA inspection schedules that prioritize automated overfill protection and spill prevention documentation.
- Chemical Industry:Multiproduct terminals need flexible batch handling and automated blending controls. Asian chemical distributors in Singapore and South Korea are expanding shared infrastructure for expanding specialty chemical portfolios.
- Shipping:Marine loading terminals require integration with vessel cargo systems.
- Utilities:Power generation fuel terminals prioritize supply security.
Oil & Gas commands the largest installed base. Chemical industry adoption is climbing the fastest.
Technology:
Architecture choices determine cybersecurity exposure and operational flexibility.
- SCADA:Supervisory control and data acquisition systems provide centralized monitoring across dispersed tank farms. Indian greenfield terminals at Jawaharlal Nehru Port Trust deploy SCADA without legacy protocol baggage.
- Cloud Computing:Remote diagnostics and predictive maintenance platforms reduce unplanned downtime. Mid-scale independent terminals are adopting these fastest where IT-OT convergence risks are manageable.
- PLC:Programmable logic controllers execute deterministic control sequences.
- DCS:Distributed control systems anchor large-scale integrated operations.
SCADA anchors current deployments. Cloud computing is gaining share fastest.
Application:
Functional priorities shift with regulatory pressure and operational scale.
- Safety Management:Safety instrumented systems and fire-gas detection prevent catastrophic releases. EU refrigerated storage terminals for LNG must deploy automated monitoring under stepped F-Gas Regulation deadlines through 2030.
- Inventory Management:Real-time tank gauging and product reconciliation optimize working capital. US terminals replacing manual measurements with automated systems to satisfy intensified documentation requirements.
- Load Control:Automated loading and unloading sequences prevent spills.
- Terminal Operations:Integrated workflow management coordinates multiple terminal activities.
Safety management commands regulatory-driven investment. Inventory management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terminal automation equipment flows disproportionately toward import-dependent refining economies with aging infrastructure. Export-oriented petrochemical hubs generate retrofit demand, while greenfield port developments in emerging markets absorb integrated system shipments.
United States
Gulf Coast refining clusters drive replacement cycles for obsolete relay logic systems. EPA 40 CFR 112 mandates intensify inspection schedules and documentation requirements. Houston and Corpus Christi terminals deploy SIL-rated overfill protection to satisfy spill prevention regulations.
Germany
Refrigerated storage terminals for LNG and industrial gases require automated leak detection retrofits. EU F-Gas Regulation phase-down schedules impose stepped compliance deadlines through 2030. Rotterdam-Antwerp corridor operators consolidate sensor networks with fire-gas detection infrastructure.
India
Petroleum product hub expansion at Jawaharlal Nehru Port Trust and Hazira creates greenfield demand. Central Electricity Authority guidelines shape fuel terminal specifications for power sector supply security. Western coast terminals adopt SCADA architectures without legacy protocol constraints.
Singapore
Multiproduct chemical terminals require flexible batch handling for expanding specialty chemical portfolios. Maritime Port Authority regulations govern marine loading system integration with vessel cargo controls. Jurong Island storage complexes automate blending controls for shared infrastructure optimization.
Saudi Arabia
Crude export terminals modernize loading automation to sustain throughput competitiveness. Saudi Aramco engineering standards influence regional procurement specifications for safety instrumented systems. Ras Tanura and Yanbu facilities anchor large-scale distributed control system deployments.
Terminal Automation Systems Market Competitive Landscape
Concentration sits with diversified industrial automation conglomerates possessing process control heritage. Siemens, ABB, and Emerson Electric anchor the premium tier through integrated hardware-software bundles. Honeywell Process Solutions and Yokogawa occupy specialized positions in safety-critical applications. Competitive moves center on electrification-automation bundling and outcome-based service contracting with guaranteed availability metrics.
Among diversified automation providers, Honeywell Process Solutions and ABB exemplify the integrated solutions archetype, leveraging distributed control system expertise to anchor large-scale refinery terminal projects. Yokogawa represents precision instrumentation specialists competing through deterministic measurement integration. Schneider Electric and Rockwell Automation occupy positions in programmable automation controller architectures for mid-scale independent terminals. Cimation sits within the systems integration tier, bridging multi-vendor protocol fragmentation for brownfield upgrade complexity.
| Leading Market Players |
|---|
| Siemens |
| Yokogawa |
| Honeywell Process Solutions |
| Rockwell Automation |
| Endress+Hauser |
| ABB |
| Schneider Electric |
| Cimation |
| Emerson Electric |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Japanese precision instrumentation plants shapes both supply concentration and price floors for SIL-rated safety systems. Scale advantages in integrated controller manufacturing allow tier-one suppliers to maintain margin structures while mid-scale competitors face cost compression.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across terminal automation procurement. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Price differentiation centers on IEC 61511 SIL certification tier and geographic delivery scope. Cost compression in mid-tier hardware is intensifying because European F-Gas Regulation compliance retrofits absorb engineering capacity. Independent storage operators exhibit highest price sensitivity; integrated oil companies prioritize availability guarantees over unit cost.
Supply Chain Analysis
Germany and Japan anchor precision instrumentation and safety controller fabrication. The United States sources specialized PLC modules and edge computing hardware. China feeds enclosure manufacturing and copper-intensive cable assemblies. Supply chains draw from rare earth magnet suppliers for actuator motors and semiconductor foundries for industrial-grade processors. Single-source vulnerability sits with legacy fieldbus protocol chipsets. Distribution runs through authorized system integrators and direct vendor relationships for cloud-native platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats as EPA 40 CFR 112 and EU F-Gas Regulation mandates force recurring compliance-driven replacement cycles. Switching costs escalate once safety instrumented systems achieve site-wide integration.
For Market Incumbents: Shield installed base relationships through outcome-based service contracting with guaranteed availability metrics. Deepen backward integration into edge-native analytics software to capture predictive maintenance revenue streams. Emerging cloud-native entrants threaten traditional hardware-procurement margins. Certification investment in IEC 61511 functional safety expertise extends consultant-dependent validation moats. For New Entrants and Emerging Players: Anchor in India's greenfield petroleum product hub expansion at Jawaharlal Nehru Port Trust and Hazira terminal developments. Mid-scale independent terminals in the US Gulf Coast present underpenetrated demand for subscription-based remote diagnostics. Target multiproduct chemical terminals in Singapore and South Korea requiring flexible batch handling automation. Go-to-market through systems integration partnerships with established EPC contractors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automation suppliers with remote operations center deployments assuming 24/7 monitoring responsibility. Long-term viability favors vendors bundling electrification with automation to reduce commissioning cycles. Acquisition targets include precision instrumentation specialists with deterministic measurement integration capabilities. Watch cloud-native predictive maintenance adoption rates at mid-scale independent terminals as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Service Contracting | Shell and BP now demand guaranteed availability metrics with vendor penalties for downtime. |
| Backward Integration into Edge Analytics | Honeywell and ABB embed machine learning inference directly within field controllers. |
| Electrification-Automation Bundling | ABB reduces commissioning cycles for brownfield upgrades through combined offerings. |
| Remote Operations Center Deployment | Technology providers assume 24/7 monitoring responsibility from terminal operators. |
| IEC 61511 Certification Investment | Scarce functional safety engineers extend project timelines and inflate implementation costs. |
Research Methodology
Cross-validation between primary interviews with terminal operations managers and secondary regulatory filing analysis anchors the qualitative findings. Control systems engineers, safety instrumented system consultants, EPC contractors, and procurement leads at integrated oil companies provided operational perspective. EPA enforcement databases, EU F-Gas Regulation compliance schedules, IEC standards documentation, and customs trade data furnished external validation. Bottom-up project pipeline tracking and top-down terminal capacity modeling were reconciled.
Sensitivity analysis around regulatory enforcement intensity and capital expenditure cycles shapes the analytical framework. Segmentation dimensions span product type, end user industry, technology architecture, and application function across the projection horizon. CAGRs derive from installed base replacement rates and greenfield capacity additions. Forecast inputs incorporate SIL-rated system recertification complexity and IT-OT convergence adoption curves.
Material uncertainties — regulatory deadline extensions, cybersecurity incident frequency, engineering talent availability — sit outside the modeled envelope. Forecasts reflect assumptions about compliance enforcement continuity and technology substitution timelines. Recalibration cycles align with material shifts in EPA inspection schedules and EU F-Gas phase-down milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Laboratory Automation Market
Automation
Asia-Pacific Data Center Automation Market
Automation
Postal Automation System Market
Automation
Global Direct Mail Automation Software Market
Automation
Playout Automation Market
Automation
Recruiting Automation Software Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Global Field Force Automation Market
Automation
Intelligent Remote Terminal Unit Market
Automation
Global Water Automation and Instrumentation Market
Automation
Parcel Sorting System Market
Automation
Smart Home Automation Market
Automation
Global Door and Window Automation Market
Automation
Global Business Process Automation Software Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
Lab Automation Market