
 Home Automation Market | 2026-2036
Home Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Home Automation Market Insights
Buyer concentration across the residential property sector is rebalancing as institutional landlords and build-to-rent operators displace individual homeowners as the primary volume purchasers of integrated automation suites. Amazon leverages its Alexa ecosystem to control voice-first installation channels across multifamily deployments. Schneider Electric anchors its position through deep electrical infrastructure relationships that sustain recurring service contracts. Google competes by extending Nest hardware into utility-sponsored demand-response programs.
Home automation encompasses networked systems that coordinate lighting, climate, security, and entertainment devices through centralized controllers using protocols such as Zigbee mesh networking with 2.4 GHz spectrum allocation and sub-100ms latency requirements for real-time occupancy response. Its commercial purpose centers on reducing operational expenditures for property operators while generating behavioral data for energy and insurance providers. Security Systems and HVAC Control command the dominant margin pools due to insurance premium discounts and utility rebate eligibility, while Smart Sensors represent the fastest-expanding category as leak detection and air quality monitoring penetrate mid-market housing stock. Thread protocol adoption is accelerating among new construction segments where Matter interoperability eliminates ecosystem lock-in risks.
FCC Part 15 rules govern unlicensed radio emissions for Wi-Fi and Zigbee devices in the US market, while the EU AI Act imposes risk classification requirements on biometric access control systems. The CSRD disclosure framework pressures European property owners to document building energy performance, directly stimulating automated metering and climate control upgrades. Stakeholders must monitor whether utility regulators in target markets will mandate open APIs for demand-response interoperability, as this policy choice determines which communication technology layers capture long-term platform value.
Market Dynamics
Institutional rental portfolios are digitizing operations faster than owner-occupied residential segments, compressing sales cycles and forcing vendors to reconfigure service models around property management platforms rather than direct consumer channels.
Growth Catalysts
- EU CSRD disclosure mandates:European property owners must document building energy performance, directly stimulating automated metering and climate control upgrades across commercial and multifamily assets.
- Utility-linked thermostat mandates in Germany:Regulatory pressure accelerates retrofit cycles for smart HVAC systems, creating concentrated demand spikes in Europe's largest housing market.
- Zigbee mesh networking with sub-100ms latency:Technical maturation enables real-time occupancy response for lighting and climate systems, expanding viable use cases beyond early adopters.
Market Restraints
- Silicon supply concentration in East Asian foundries:Semiconductor fabrication for smart sensors and controllers remains geographically concentrated, exposing automation vendors to input volatility and logistics disruption.
- EU AI Act biometric risk classification:Facial recognition and voice-print access systems face heightened compliance burdens and potential prohibition in residential settings, constraining product roadmaps.
- Copper and rare earth magnet costs:Electromechanical actuators for smart HVAC dampers and motorized blinds depend on materials with structurally volatile pricing, compressing hardware margins.
Strategic Opportunities
- Thread protocol and Matter interoperability:Ecosystem lock-in risks diminish as new construction segments adopt open standards, enabling vendor-neutral platform plays.
- Leak detection in mid-market housing:Insurance premium discounts for water damage prevention are penetrating below luxury segments, expanding addressable unit economics.
- FCC Part 15 unlicensed spectrum expansion:US regulatory accommodation for additional 2.4 GHz and sub-GHz channels supports denser device deployments in multifamily properties.
Industry Challenges
- Legacy electrical infrastructure integration:Retrofit installations in pre-1990s housing stock require specialized labor for neutral wire provisioning and load panel upgrades, constraining deployment velocity.
- GDPR-compliant voice data architecture:Cloud-dependent voice assistants must implement edge processing and localized storage to satisfy European data residency requirements, complicating engineering roadmaps.
- Interoperability certification timelines:Matter compliance testing creates bottlenecks as multiple certification bodies queue hardware submissions, delaying product launches.
Report Scope
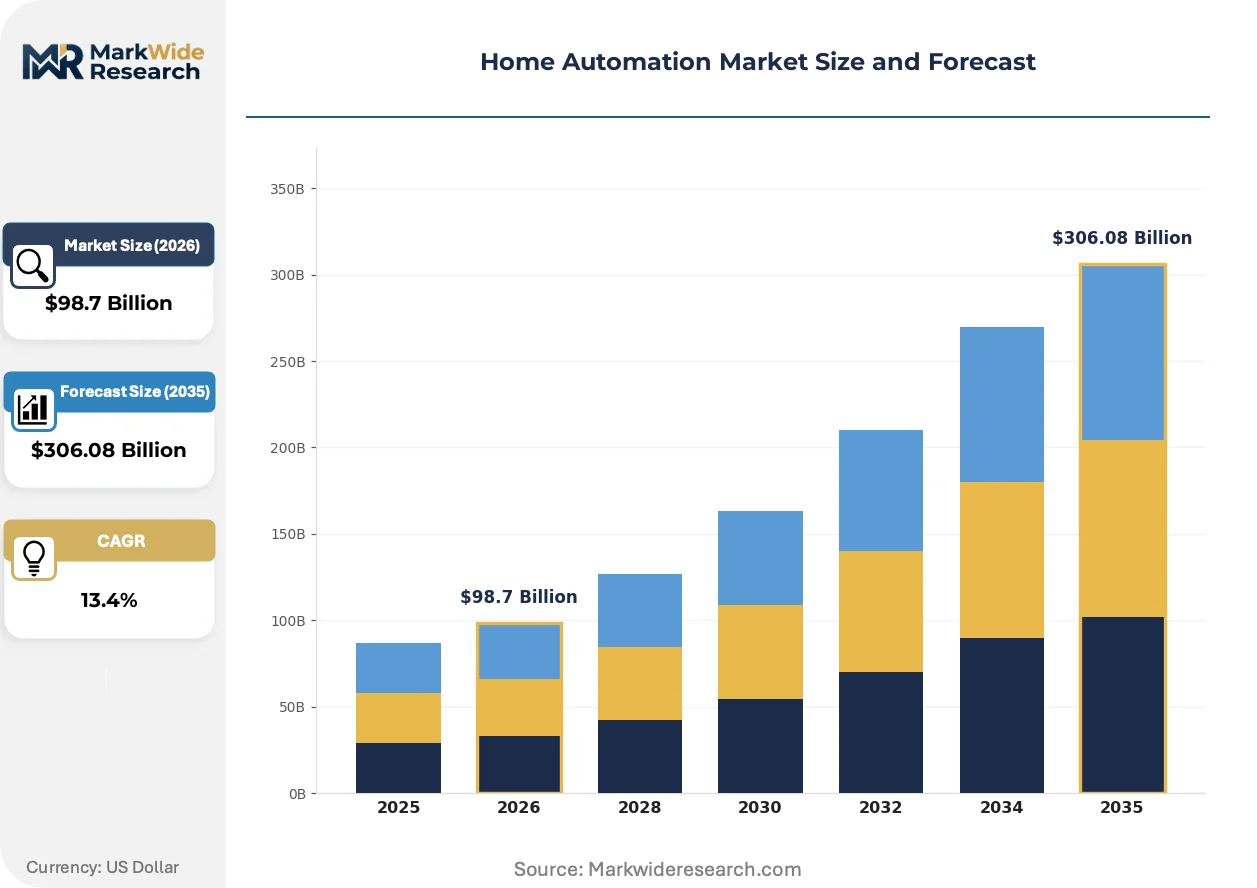
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Automation Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $306.08 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Security Systems, HVAC Control, Smart Sensors, Entertainment Systems Communication Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth, Thread Use Case: Energy Management, Surveillance, Access Control, Comfort Enhancement, Appliance Automation Customer Type: Homeowners, Property Managers, Rental Operators, Technology Enthusiasts |
| Companies Covered | ABB, ADT, Amazon, Apple, Google, Honeywell International, Johnson Controls, Legrand, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Automation Market Trends and Innovations
Protocol convergence and regulatory data mandates are compressing technology refresh cycles while redistributing value capture from hardware toward recurring service layers.
Edge AI inference chips embedded in smart thermostats and security hubs are automating occupancy prediction and anomaly detection without cloud dependency. Build-to-rent operators in the United Kingdom and Netherlands are deploying these systems at scale to reduce utility pass-through disputes. This architecture is automating the shift from reactive maintenance toward predictive intervention models.
The EU AI Act's risk-based classification system imposes documentation and human-oversight requirements on biometric access control deployed in residential settings. Hardware vendors must redesign product lines to exclude facial recognition or implement local processing with audit trails. German and French property developers are prioritizing keypad and mobile-credential systems to preempt compliance exposure.
Property management platforms are consolidating vendor relationships into single-source automation contracts that bundle installation, monitoring, and maintenance. Traditional retail channels and direct-to-consumer sales are losing share in multifamily new construction. This concentration is most pronounced in Scandinavian markets where institutional landlords control majority rental stock.
Home Automation Market Segmentation
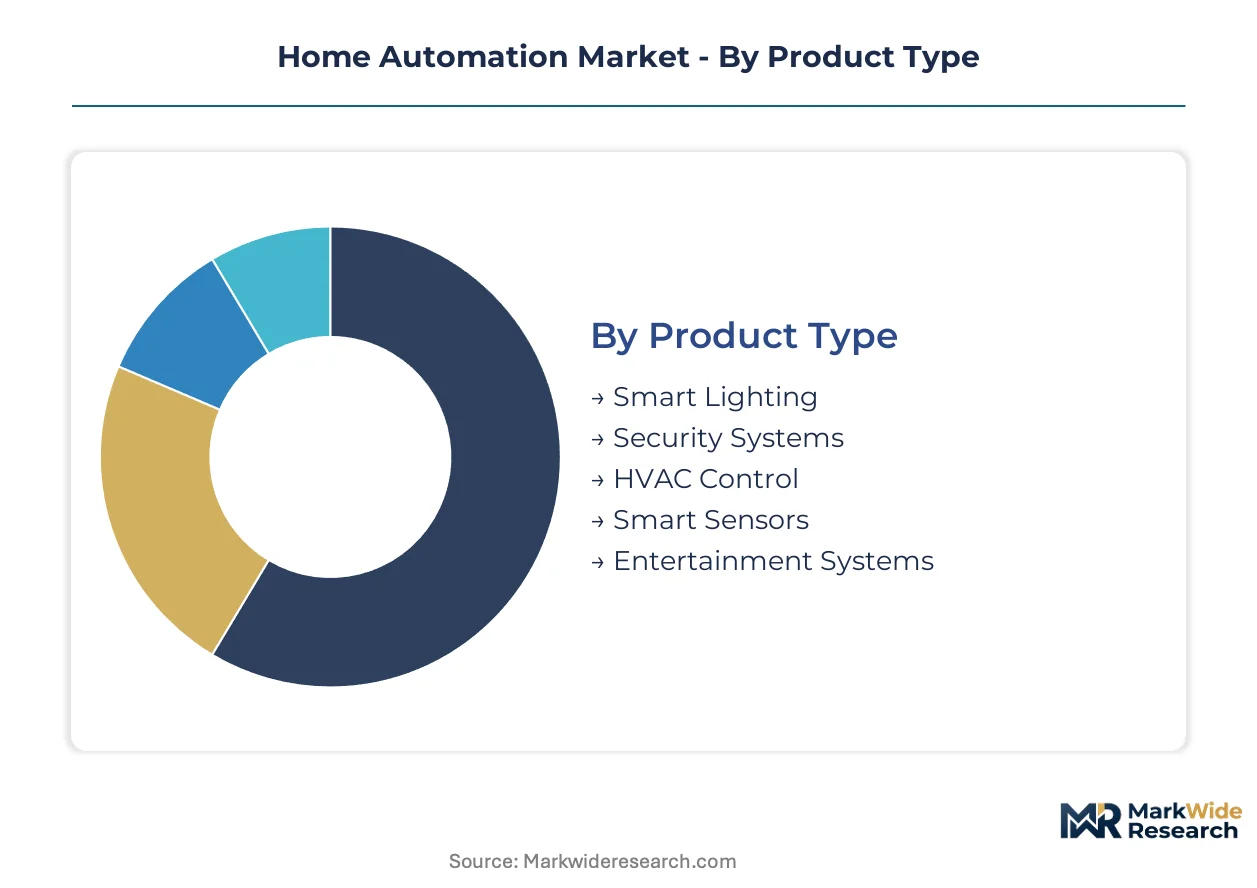
Segmentation in home automation reveals how procurement authority is shifting from retail consumers to institutional buyers, while protocol choices determine long-term platform viability. Understanding these divisions exposes where margin pools concentrate and which technology layers capture recurring revenue.
Product Type:
Purchase decisions pivot on insurance premium reductions and utility rebate eligibility, not gadget appeal.
- Security Systems:Integrated intrusion detection, video verification, and remote monitoring architectures command premium pricing through underwriting discounts. Demand concentrates among US and German property insurers mandating certified installations for multi-unit portfolios.
- HVAC Control:Smart thermostats with utility-linked demand-response capability reduce operational expenditure for rental operators. German regulatory mandates for connected heating controls accelerate retrofit cycles across Europe's largest housing stock.
- Smart Lighting:LED-integrated dimming and circadian scheduling systems reduce energy draw in commercial and multifamily assets.
- Smart Sensors:Leak detection and air quality monitoring penetrate mid-market housing through insurance incentives, expanding fastest among below-luxury segments.
- Entertainment Systems:Distributed audio and unified media control remain discretionary purchases concentrated in owner-occupied luxury residential.
Security Systems leads on scale; Smart Sensors leads on momentum.
Communication Technology:
Protocol selection locks in ecosystem compatibility and determines interoperability certification burdens.
- Zigbee:Mesh networking with 2.4 GHz spectrum allocation and sub-100ms latency requirements enables real-time occupancy response. Demand concentrates in retrofit installations where legacy infrastructure requires reliable penetration through walls and floors.
- Thread:IPv6-native mesh protocol with Matter interoperability eliminates vendor lock-in risks. New construction segments in Scandinavia and Netherlands adopt this standard for build-to-rent deployments seeking platform neutrality.
- Wi-Fi:High-bandwidth protocol dominates video-heavy security and entertainment applications despite power consumption tradeoffs.
- Z-Wave:Sub-GHz mesh alternative with strong presence in legacy North American security installations.
- Bluetooth:Low-energy protocol serves proximity-based access control and initial device provisioning workflows.
Wi-Fi dominates current installed base; Thread climbs fastest among new construction specifications.
Use Case:
Operational priority determines hardware specification and integration depth.
- Energy Management:Automated metering, climate optimization, and load scheduling reduce utility pass-through disputes. EU CSRD disclosure mandates drive adoption across commercial and multifamily assets requiring documented building performance.
- Surveillance:Video analytics and cloud storage integration serve liability reduction for property operators. GDPR compliance requirements constrain cloud-dependent architectures in European deployments.
- Access Control:Biometric and mobile-credential entry systems face EU AI Act risk classification constraints, pushing developers toward keypad alternatives.
- Comfort Enhancement:Lighting scenes, automated shading, and climate personalization remain secondary priorities for institutional buyers.
- Appliance Automation:Coordinated white goods control delivers marginal operational savings compared to HVAC and security investments.
Energy Management leads on scale; Surveillance leads on momentum.
Customer Type:
Procurement volume and service model requirements diverge sharply between consumer and institutional channels.
- Property Managers:Institutional rental portfolios digitize operations through bundled installation, monitoring, and maintenance contracts. Scandinavian markets concentrate demand where landlords control majority rental stock.
- Rental Operators:Build-to-rent developers in United Kingdom and Netherlands deploy predictive maintenance systems at scale to reduce utility disputes and tenant churn.
- Homeowners:Retail channel dependence and DIY installation preference constrain margin capture for integrated suite vendors.
- Technology Enthusiasts:Early adopter segment drives protocol experimentation but represents limited volume for standardized deployments.
Property Managers leads on scale; Rental Operators leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates utility-linked thermostat demand while the United States drives security system procurement through insurance channel incentives. Both markets illustrate how regulatory architecture shapes automation deployment velocity differently across jurisdictions.
United States
Property insurers in Florida and Texas mandate certified security installations for multifamily portfolios, compressing sales cycles for integrated intrusion detection systems. FCC Part 15 rules govern unlicensed spectrum allocation for Zigbee and Wi-Fi device emissions. Installation activity clusters in Phoenix and Atlanta where build-to-rent operators digitize new construction specifications at scale.
Germany
Utility-linked smart thermostat mandates accelerate retrofit cycles across Europe's largest housing stock, creating concentrated demand spikes for HVAC control systems. The EU AI Act imposes risk classification requirements on biometric access control, forcing redesigns of voice-activated entry systems. Engineering activity concentrates in Munich and Stuttgart where electrical infrastructure vendors sustain recurring service contracts with institutional landlords.
United Kingdom
Build-to-rent developers deploy predictive maintenance systems to reduce utility pass-through disputes and tenant churn across London and Manchester portfolios. CSRD disclosure mandates pressure property owners to document building energy performance, stimulating automated metering upgrades. Technology procurement concentrates in the Southeast where institutional landlords control majority rental stock.
Netherlands
Thread protocol adoption accelerates among new construction segments where Matter interoperability eliminates ecosystem lock-in risks for property developers. GDPR compliance requirements constrain cloud-dependent voice architectures, pushing edge processing investments. Smart housing deployment concentrates in Amsterdam and Eindhoven where build-to-rent operators prioritize platform-neutral automation specifications.
China
MIIT standards govern sub-GHz spectrum allocation for smart home mesh networks in high-density residential developments. Domestic manufacturers integrate edge AI inference chips into security hubs for localized anomaly detection without cloud dependency. Manufacturing and deployment activity concentrates in Shenzhen and Hangzhou where electronics supply chains support rapid hardware iteration cycles.
Home Automation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across layered technology stacks. The vendor base organizes around electrical infrastructure incumbents, consumer technology platforms, and security service providers with distinct channel access. Three strategic archetypes dominate: ecosystem orchestrators leveraging voice-first installation channels, infrastructure anchors controlling recurring service contracts, and security specialists capturing insurance-linked procurement. Competitive moves center on protocol standardization alliances and property management platform integrations.
Within the electrical infrastructure tier, ABB, Schneider Electric, and Legrand occupy positions that exemplify how deep contractor relationships translate into sustained recurring revenue streams. These European-anchored conglomerates represent the archetype of vendors that bundle installation, monitoring, and maintenance into single-source contracts with institutional property operators. Their positioning illustrates how hardware margins compress while service layers capture long-term platform value in digitized rental portfolios.
| Leading Market Players |
|---|
| ABB |
| ADT |
| Amazon |
| Apple |
| Honeywell International |
| Johnson Controls |
| Legrand |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Institutional rental portfolios in Germany and Scandinavia are consolidating procurement authority, shifting vendor pricing power toward bundled service contracts and away from per-unit hardware margins. This buyer concentration compresses transactional pricing while elevating recurring revenue streams for vendors with embedded installation and maintenance capabilities.
Pricing Analysis
Capacity additions in China's semiconductor foundries are reshaping price floors for Zigbee mesh controllers and edge AI inference chips. Pricing stratifies across premium certified installations, standard retrofit packages, and economy DIY hardware tiers, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression in mid-market sensor hardware is intensifying because of copper and rare earth magnet volatility. Property managers exhibit the highest price sensitivity due to portfolio-scale procurement, while luxury homeowners show the least.
Supply Chain Analysis
Returns and refurbishment flows for smart thermostats and security hubs are expanding as European property operators extend hardware lifecycles to meet CSRD disclosure timelines. Manufacturing concentration centers on China, Taiwan, and South Korea for semiconductor fabrication, with Vietnam and Mexico emerging for final assembly of electromechanical actuators. The supply chain draws from copper wiring, rare earth magnets, and silicon wafers as critical inputs. Single-source vulnerability in East Asian foundries poses structural risk. Distribution runs through electrical contractor networks and property management platform integrations rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where institutional buyers prioritize Matter-certified, GDPR-compliant specifications over lowest-cost alternatives. Demand is migrating toward predictive maintenance platforms that bundle hardware with recurring analytics services.
For Market Incumbents: Lock in property management platform integrations to defend against pure-play software entrants. Deepen electrical infrastructure relationships through certified installer networks as a margin protection lever. Prioritize edge AI chip development to reduce cloud dependency exposure from GDPR and EU AI Act compliance costs. For New Entrants and Emerging Players: Thread protocol-native hardware stacks offer the most penetrable wedge against Zigbee-entrenched incumbents. Target Netherlands and UK build-to-rent developers seeking platform-neutral, Matter-interoperable specifications. Pursue utility-sponsored demand-response certification as the primary go-to-market channel bypassing traditional contractor networks. For Investors and Strategic Acquirers: Electrical infrastructure conglomerates are the most active acquirer in this space, seeking recurring service contract capabilities to offset hardware margin compression. Long-term viability favors vendors with captive installer networks and utility regulatory relationships. Monitor FCC Part 15 spectrum expansion proceedings and EU open API mandate developments as inflection indicators for communication technology layer value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Interoperability Certification | Eliminates vendor lock-in risks for build-to-rent developers in Netherlands and Scandinavia. |
| Edge AI Chip Integration | Enables GDPR-compliant voice processing without cloud dependency for German deployments. |
| Utility Demand-Response Partnership | Captures thermostat mandate-driven retrofit volume in Germany's housing stock. |
| Installer Network Acquisition | Secures recurring service contract access with institutional property managers. |
| Predictive Maintenance Platform Launch | Reduces utility pass-through disputes for UK rental operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with property technology directors, electrical contractor procurement leads, utility demand-response program managers, and smart home platform engineers with secondary validation. Regulatory filings from FCC, EU AI Act documentation, and CSRD disclosure frameworks anchored policy analysis. Trade data from customs records, utility rebate program databases, and Matter certification registries supplemented demand estimation. Bottom-up unit economics and top-down market sizing triangulated volume figures.
Historical reference periods spanning installed base accumulation and retrofit cycle timing anchored the projection horizon. Segmentation modeling captured product type, communication technology, use case priority, and customer procurement channel across the analysis window. CAGRs derived from logistic diffusion curves for protocol adoption and regulatory mandate implementation schedules. Zigbee-to-Thread transition velocity and EU AI Act compliance cost pass-through served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to utility regulator open API mandates and rare earth supply disruptions. Practitioners should monitor FCC spectrum allocation proceedings and German Bundesnetzagentur thermostat mandate enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Self Bag Drop Machine Market
Automation
Global Database Automation Systems Market
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
Indonesia Automation and Control System Market
Automation
Distribution Automation Solutions Market
Automation
AR Automation Market
Automation
Marketing Automation Solutions Market
Automation
Global Door and Window Automation Market
Automation
Europe Laboratory Automation Market
Automation
Lab Automation Market
Automation
Playout Automation Market
Automation
Automated Cell Block Systems Market
Automation
Workload Automation Software Market
Automation
Computer Numerical Control Market
Automation
Recruiting Automation Software Market
Automation
Global Field Force Automation Market