
 Global Business Process Automation Software Market | 2026-2036
Global Business Process Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Process Automation Software Market Foresight
Multi-source platform procurement is consolidating around vendors offering integrated workflow automation and robotic process automation stacks. UiPath Inc. anchors the European RPA channel with specialized partner ecosystems. Microsoft Corporation leverages its Azure cloud infrastructure to bundle automation tools with enterprise productivity suites. Salesforce.com, Inc. competes by embedding workflow engines directly within its CRM architecture.
Business process automation software orchestrates repetitive operational tasks through configurable rules engines, API integrations, and machine-learning-driven decision nodes, typically deployed via cloud-native architectures with containerized microservices. Its primary commercial purpose is reducing manual processing latency while enforcing audit-compliant execution paths across finance, HR, and customer operations. Cloud-based deployment now captures the dominant margin pool as enterprises abandon capital-intensive server maintenance. Robotic process automation represents the fastest-expanding solution type as attended and unattended bots displace manual data entry in invoice processing and compliance management.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that shape product roadmaps for vendors serving European enterprises. The SEC in the United States enforces financial reporting controls that drive demand for auditable workflow automation in banking and insurance. India's RBI operational guidelines for digital banking infrastructure create compliance tailwinds for process automation adoption among Mumbai and Bangalore financial institutions. Stakeholders must evaluate how emerging AI governance frameworks in multiple jurisdictions will reshape platform certification requirements and cross-border deployment architectures.
Market Dynamics
Cloud-native orchestration platforms are compressing deployment cycles from quarters to weeks, forcing incumbent vendors to abandon monolithic architectures or cede enterprise accounts to API-first challengers.
Growth Catalysts
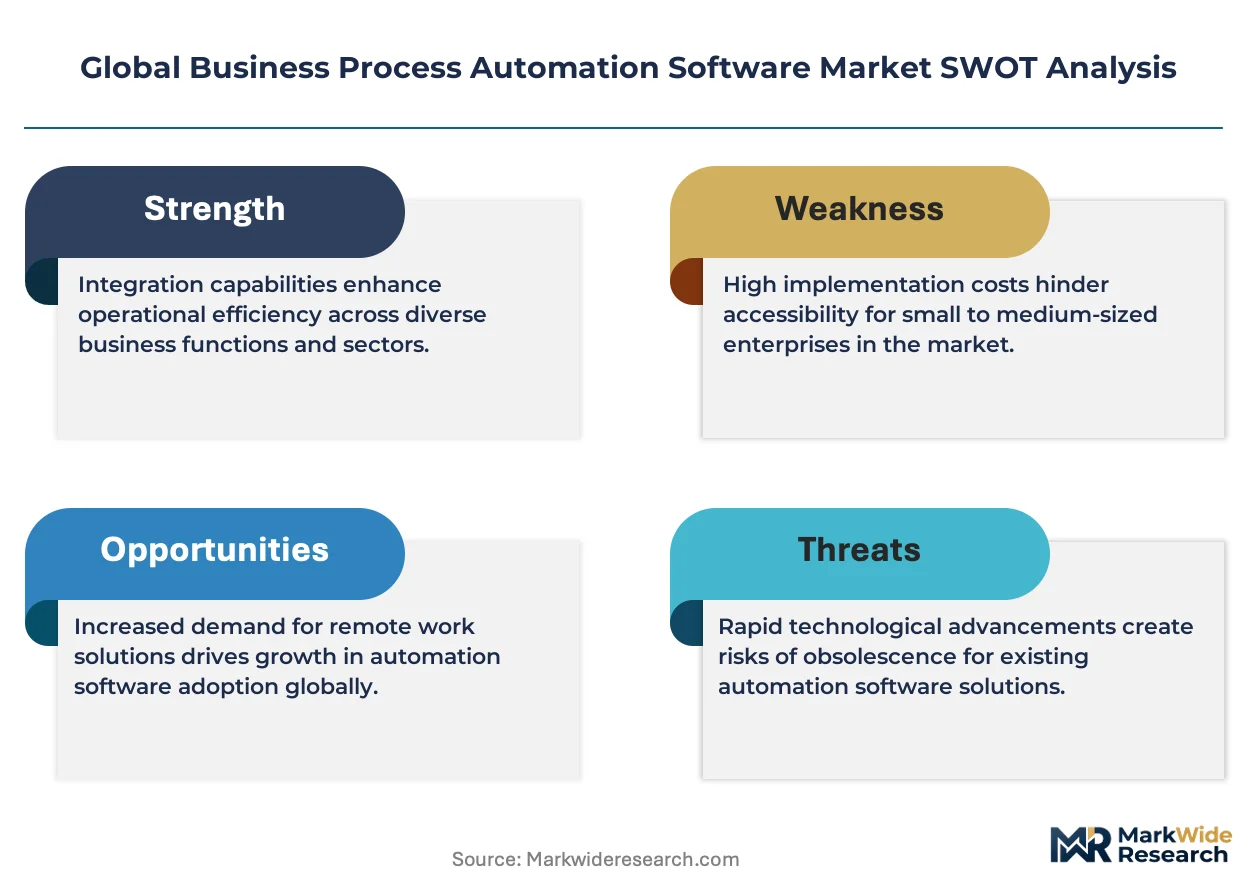
- EU AI Act compliance mandates:Algorithmic transparency requirements under the EU AI Act are compelling European banks and insurers to replace opaque legacy systems with auditable workflow automation stacks.
- India's digital banking infrastructure:RBI operational guidelines for Mumbai and Bangalore financial institutions are accelerating process automation procurement for compliance and customer onboarding.
- Attended bot deployment:Human-in-the-loop RPA configurations are expanding automation coverage into exception-heavy processes previously deemed too complex for full automation.
Market Restraints
- Specialized talent scarcity:Shortages of certified automation architects and process mining specialists are inflating implementation costs and extending project timelines.
- Data residency fragmentation:Conflicting sovereignty requirements across Germany, India, and the United States are forcing vendors to maintain redundant infrastructure footprints.
- Legacy system entrenchment:COBOL-dependent core banking platforms in established financial institutions resist API-based integration without expensive middleware layers.
Strategic Opportunities
- Process mining convergence:Integration of process discovery engines with execution platforms is creating unified value chains from diagnosis through automation deployment.
- SEC audit trail mandates:Enhanced financial reporting controls in the United States are driving replacement of spreadsheet-dependent workflows with system-of-record automation.
- Small and mid-market penetration:Pre-configured industry templates are lowering adoption barriers for manufacturers and healthcare providers outside the Fortune 500.
Industry Challenges
- Cross-functional change management:Automation initiatives frequently stall when finance, operations, and IT stakeholders fail to align on success metrics and governance structures.
- Bot maintenance overhead:Unattended RPA deployments require continuous monitoring and reconfiguration as target application interfaces update, consuming unbudgeted operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Process Automation Software Market |
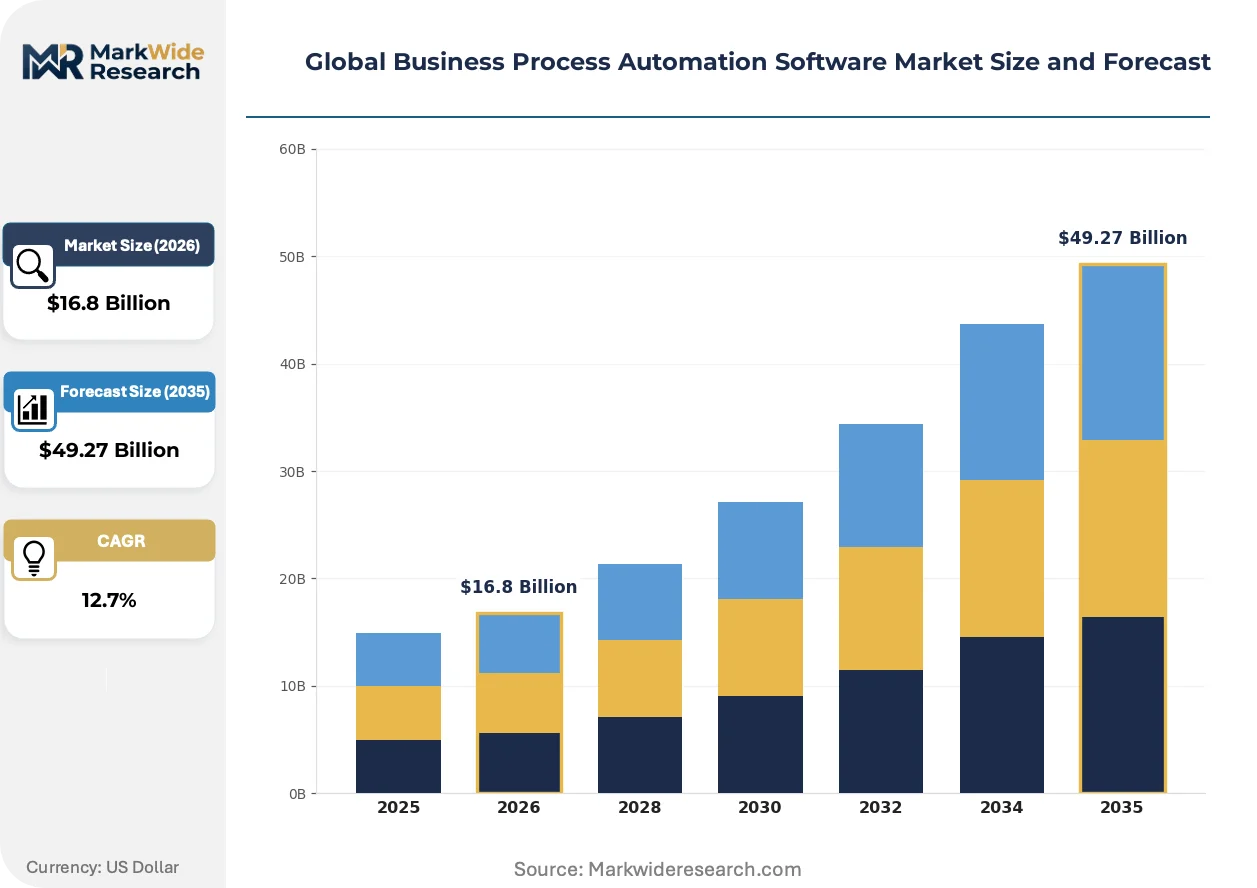
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $49.27 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Hosted, Managed Solution Type: Workflow Automation, Robotic Process Automation, Business Rules Management, Integration Platforms, Analytics & Reporting Use Case: Invoice Processing, Customer Service Automation, Human Resources Management, IT Service Management, Compliance Management End User Industry: Information Technology, Manufacturing, Telecommunications, Logistics & Transportation, Education |
| Companies Covered | Pegasystems, Inc., Salesforce.com, Inc., Microsoft Corporation, UiPath Inc., Nintex, Inc., IBM Corporation, Oracle Corporation, Automation Anywhere Inc., Appian Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Process Automation Software Market Shifts & Advancements
Agentic AI architectures are dissolving the boundary between decision support and autonomous execution, enabling software to initiate multi-step workflows without human triggering.
Large language model integration into workflow engines is decentralizing automation design authority from centralized IT teams to domain specialists who configure processes through natural language prompts. Procurement and HR departments at German automotive suppliers and US healthcare systems are deploying these tools to build department-specific automations without coding expertise. This shift is compressing the traditional vendor-consultant-IT triad into direct business-user platform relationships.
The EU AI Act's risk-based classification system is forcing vendors serving European enterprises to embed explainability modules and human-override mechanisms into high-stakes automation workflows. Banking and insurance deployments now require documented algorithmic decision trails that satisfy national financial regulators in Frankfurt and Paris. Product roadmaps are prioritizing compliance-by-design over pure efficiency optimization.
Subscription-based platform economics are displacing perpetual license models as buyers prioritize operational expenditure flexibility over capital commitments. Mid-market enterprises in India and the United States are driving this transition, demanding consumption-aligned pricing that scales with transaction volume rather than user seats. Channel partners are restructuring compensation to capture recurring revenue streams rather than upfront implementation fees.
Global Business Process Automation Software Market Segmentation
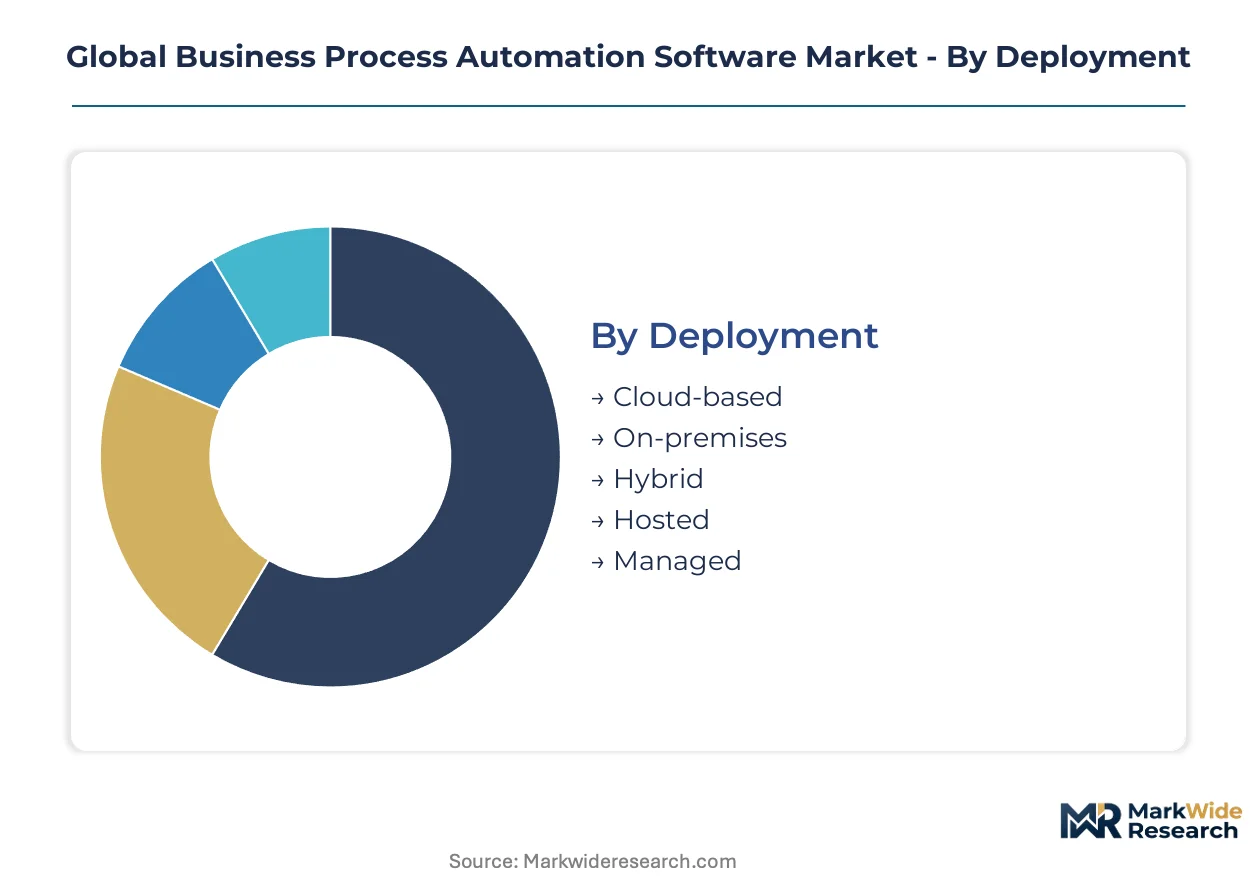
Segmentation in business process automation software reveals how deployment architecture, solution depth, and industry specificity determine procurement patterns. Buyers select configurations based on integration complexity, regulatory exposure, and existing IT estate constraints.
Deployment:
Cloud-native architectures embed automation engines within containerized microservices stacks, while legacy on-premises installations persist where data sovereignty mandates dominate procurement decisions.
- Cloud-based:Multi-tenant SaaS platforms deliver elastic compute for seasonal transaction spikes. German automotive suppliers and US healthcare systems prioritize these configurations for rapid scaling without capital expenditure.
- On-premises:Dedicated hardware installations maintain air-gapped environments for classified government workflows and core banking systems in Mumbai financial institutions subject to RBI data localization directives.
- Hybrid:Split architectures route sensitive operations to private infrastructure while leveraging public cloud burst capacity for non-critical workloads.
- Hosted:Single-tenant deployments in vendor-managed data centers offer middle-ground control for mid-market enterprises lacking internal infrastructure teams.
- Managed:Fully outsourced operations where vendors assume responsibility for platform maintenance, patch management, and SLA compliance.
Cloud-based configurations lead volumes today; hybrid deployments are gaining share fastest as enterprises navigate conflicting sovereignty requirements across operating jurisdictions.
Solution Type:
Functional depth ranges from deterministic rule engines to adaptive systems incorporating machine-learning inference layers, with procurement concentrating where ROI measurement is most straightforward.
- Workflow Automation:Sequential task orchestration through visual design interfaces enables finance departments to map approval hierarchies without coding expertise.
- Robotic Process Automation:Software bots replicate human keystrokes and mouse movements to extract data from legacy applications lacking API connectivity. Invoice processing at Bangalore shared service centers and insurance claims handling in Frankfurt drive concentrated demand for both attended and unattended configurations.
- Business Rules Management:Centralized decision logic engines separate policy definitions from execution code, allowing compliance teams to update regulatory calculations without IT deployment cycles.
- Integration Platforms:API gateways and message brokers connect disparate SaaS applications, on-premises databases, and partner systems through pre-built connectors.
- Analytics & Reporting:Process intelligence modules mine execution logs to identify bottlenecks, predict SLA breaches, and quantify automation ROI for executive dashboards.
Workflow Automation anchors current revenue; Robotic Process Automation exhibits the steepest expansion trajectory as bot deployment extends beyond back-office into customer-facing operations.
Use Case:
Process complexity and exception frequency determine which workflows merit full automation versus human-in-the-loop augmentation.
- Invoice Processing:Optical character recognition combined with three-way matching algorithms eliminates manual data entry for accounts payable teams at manufacturing conglomerates.
- Customer Service Automation:Chatbots and case routing engines deflect tier-one support inquiries while escalating exceptions to specialized agents.
- Human Resources Management:Onboarding workflows orchestrate background checks, system provisioning, and compliance training across distributed workforces. US healthcare systems and Indian IT services firms deploy these extensively for high-volume hiring cycles.
- IT Service Management:Incident triage, change approval, and asset lifecycle automation reduce mean-time-to-resolution for enterprise technology operations.
- Compliance Management:Audit trail generation, regulatory reporting, and control testing automation address SEC financial controls and EU AI Act algorithmic transparency mandates.
Invoice Processing dominates transaction volumes; Compliance Management is climbing the fastest as regulatory pressure intensifies across banking and insurance sectors.
End User Industry:
Industry-specific templates accelerate deployment by embedding pre-configured connectors and regulatory workflows tailored to sector operating models.
- Information Technology:Internal IT operations and product development pipelines consume automation for software deployment, testing orchestration, and infrastructure provisioning. Bangalore and Hyderabad technology campuses represent concentrated demand clusters.
- Manufacturing:Supply chain visibility, quality management, and shop-floor integration drive adoption among German automotive suppliers and industrial equipment producers.
- Telecommunications:Network operations, customer provisioning, and billing reconciliation automation address high transaction volumes and complex product bundles.
- Logistics & Transportation:Shipment tracking, customs documentation, and fleet management workflows coordinate multi-modal supply chains across ports and distribution centers.
- Education:Student enrollment, financial aid processing, and alumni engagement automation serves universities and corporate training providers expanding digital service delivery.
Information Technology leads current deployment scale; Manufacturing is expanding most quickly as Industry 4.0 investments converge with back-office modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley technology campuses anchor enterprise automation procurement, with financial services firms in New York and healthcare systems in Boston driving concentrated demand for compliance-oriented workflow platforms.
United States
SEC audit trail mandates and HIPAA data handling requirements propel banking and healthcare automation investments. The IRA's digital infrastructure provisions accelerate cloud migration for mid-market manufacturers. Chicago and Dallas financial institutions deploy robotic process automation for mortgage processing and claims management.
Germany
Automotive suppliers and industrial machinery producers demand shop-floor integration with back-office workflows. EU AI Act risk classifications and GDPR data residency rules reshape vendor certification requirements. Stuttgart and Munich manufacturing clusters prioritize process mining convergence for supply chain visibility.
India
RBI operational guidelines for digital banking infrastructure mandate auditable automation stacks. Mumbai and Bangalore financial institutions replace legacy core systems with API-first orchestration platforms. PLI scheme incentives attract automation vendors to establish captive development centers in Hyderabad.
United Kingdom
Financial services regulators in London enforce algorithmic transparency for trading and risk management workflows. CSRD sustainability reporting requirements drive ESG data automation across FTSE-listed enterprises. Manchester and Edinburgh shared service centers expand attended bot deployments for customer onboarding.
Japan
METI Industry 4.0 initiatives converge with aging workforce constraints to accelerate manufacturing automation. PMDA pharmaceutical traceability requirements reshape quality management workflows. Osaka and Nagoya industrial corridors integrate robotic process automation with legacy MES systems.
Global Business Process Automation Software Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and specialized vertical expertise. The vendor landscape stratifies into three tiers: hyperscale platform providers bundling automation with productivity suites, pure-play RPA specialists with deep partner ecosystems, and vertical-focused workflow vendors embedding industry-specific compliance logic. Consolidation pressures intensify as API-first challengers compress implementation timelines. Strategic moves concentrate on M&A for process mining capabilities and strategic partnerships to embed automation within existing enterprise software relationships.
Within the pure-play RPA tier, UiPath Inc. and Automation Anywhere Inc. exemplify the attended-to-unattended bot expansion model. Microsoft Corporation occupies a position anchoring the hyperscale integration strategy, leveraging Azure infrastructure to bundle automation tools with enterprise productivity suites. These three represent distinct competitive archetypes: specialized bot deployment, cloud-native bundling, and platform ecosystem dominance.
| Leading Market Players |
|---|
| Pegasystems, Inc. |
| Salesforce.com, Inc. |
| Microsoft Corporation |
| UiPath Inc. |
| Nintex, Inc. |
| IBM Corporation |
| Oracle Corporation |
| Automation Anywhere Inc. |
| Appian Corporation |
| Others |
Supply & Pricing Matrix
Containerized microservices deployment is compressing infrastructure costs for cloud-native automation vendors while simultaneously concentrating compute supply among hyperscale providers in the United States, Germany, and India. This dual compression reshapes how platform economics flow through subscription pricing and partner margin structures.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers dominates subscription pricing dynamics for SaaS automation platforms. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration complexity and compliance certification grade, with EU AI Act-aligned explainability modules commanding substantial premiums. Cost compression in the mid-market tier is intensifying because Indian and US buyers demand consumption-aligned models over seat-based licensing. Small and mid-market enterprises exhibit highest price sensitivity, while Fortune 500 financial institutions prioritize audit-trail capabilities over per-unit economics.
Supply Chain Analysis
Freight and data transit costs for cross-border cloud infrastructure are rising as German, Indian, and US regulators impose conflicting data residency mandates. Software supply chains draw from development centers in India, cloud infrastructure in the United States, and specialized process mining talent in Germany. Single-source vulnerability concentrates in hyperscale cloud providers, with distribution running through value-added resellers and systems integrators who bundle implementation services with platform subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Business Process Automation Software Market functions as a regulatory compounder where compliance mandates from the EU AI Act, SEC audit controls, and RBI operational guidelines generate sustained replacement demand for legacy systems.
For Market Incumbents: Acquire process mining and agentic AI specialist firms to close capability gaps against API-first challengers. Hyperscale bundling from Microsoft Azure threatens pure-play RPA margins, making backward integration into workflow intelligence essential for defending enterprise accounts. Invest in EU-certified explainability modules to capture Frankfurt and Paris banking procurement.
For New Entrants and Emerging Players: Channel partners specializing in mid-market manufacturing and healthcare represent the fastest path to revenue. White-space opportunity concentrates in Indian digital banking infrastructure and US healthcare systems outside major metropolitan clusters. Lead with pre-configured industry templates that compress implementation timelines from quarters to weeks.
For Investors and Strategic Acquirers: Valuations sit cheapest among vertical-focused workflow vendors embedding compliance-by-design logic for specific regulators. Long-term viability hinges on recurring revenue durability and cross-selling depth into existing customer bases. Watch for inflection when process mining convergence accelerates from diagnostic tool to execution platform.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Process mining engines create unified value chains from diagnosis through deployment for European banks. |
| Platform Integration | Embedding workflow automation within CRM architectures captures customer-facing operations at Salesforce-scale deployments. |
| Geographic Expansion | Captive development centers in Hyderabad leverage PLI scheme incentives for RBI-compliant digital banking stacks. |
| Strategic Partnership | Azure cloud bundling with productivity suites locks in enterprise accounts across Chicago and Dallas financial institutions. |
| Product Launch | Agentic AI architectures dissolve boundaries between decision support and autonomous execution for German automotive suppliers. |
Research Methodology
Direct dialogue with CTOs, IT procurement officers, platform engineers, and channel partners grounded qualitative findings in operational reality. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU regulatory filings, and RBI operational guidelines. Bottom-up and top-down triangulation cross-checked segment-level demand against macroeconomic indicators across the analysis window.
Bottom-up modeling aggregated deployment-scale estimates by organization size, vertical, and integration complexity, while top-down approaches validated against aggregate cloud software spending trends. CAGRs were derived from regression analysis of historical adoption curves and regulatory milestone timing. Forecast inputs incorporated EU AI Act implementation phases, SEC audit trail mandate expansion, and RBI digital banking infrastructure deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to algorithmic governance framework evolution and cross-border data sovereignty negotiations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Water Automation and Instrumentation Market
Automation
Industrial Vending Machines Market
Automation
Database Automation Market
Automation
Escalator Control Systems Market
Automation
Global Cloud Automation Market
Automation
Window Automation Market
Automation
Cognitive Process Automation Market
Automation
Automation Lifecycle Services Market
Automation
Europe Data Center Automation Market
Automation
Workload Automation Software Market
Automation
Global Database Automation Systems Market
Automation
Global Field Force Automation Market
Automation
AR Automation Market
Automation
Distributed Control System Market
Automation
IoT Home Automation Market
Automation
Home Automation and Controls Market