
 Postal Automation System Market | 2026-2036
Postal Automation System Market Size, Share, and Industry Trends Forecast 2026-2036
Postal Automation System Market Intelligence
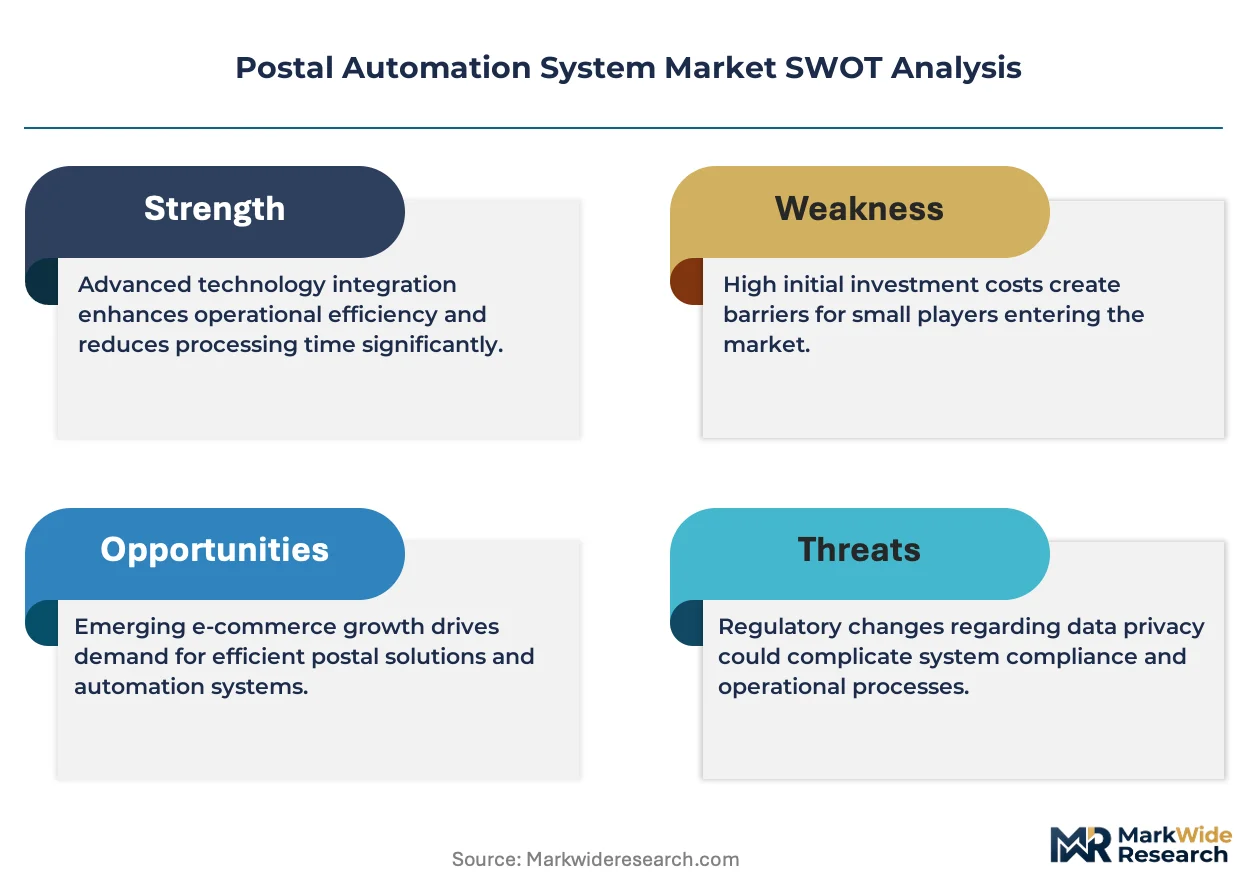
The capability gap between conveyor-scale integrators and standalone equipment vendors is unwinding as full-system contracts dominate procurement. Siemens AG leverages its industrial automation portfolio to anchor large postal hub projects across Europe. BEUMER Group specializes in high-throughput parcel sorting architecture for courier companies. NEC Corporation competes through image recognition and optical character recognition modules that embed into third-party lines.
A postal automation system integrates mechanical sorting, barcode reading, weighing, and conveyor transport to process mail and parcels with minimal human intervention; modern installations achieve throughput exceeding 40,000 items per hour through tilt-tray or cross-belt sorter configurations. Sorting machines represent the most capital-intensive component category, with tilt-tray sorters commanding premium pricing for e-commerce fulfillment center deployments. Machine learning algorithms within the technology dimension are displacing rule-based sorting logic, enabling dynamic route optimization that reduces misdirected parcels. Robotics automation is gaining share in last-mile preparation, though optical character recognition remains the dominant address-reading standard.
The EU Green Deal and F-Gas Regulation shape equipment efficiency mandates for European postal operators, while the EPA guides emissions standards for diesel-powered material handling fleets in the United States. CE marking requirements under the EU Machinery Directive constrain market access for non-compliant Asian equipment suppliers. Stakeholders must weigh cloud-based deployment models against on-premises infrastructure as cybersecurity frameworks from ISO and national regulators tighten data governance for parcel tracking systems.
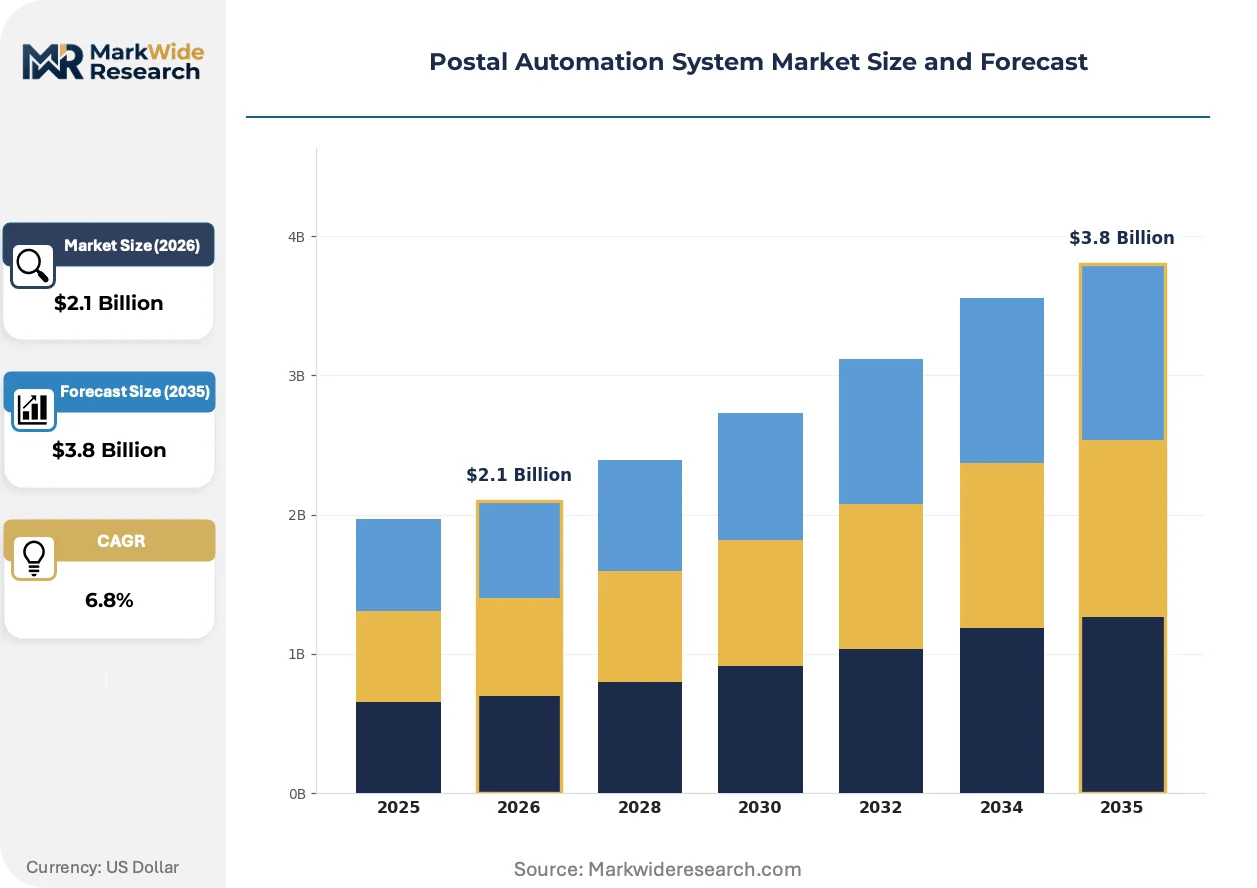
Market Dynamics
Machine learning algorithms are displacing rule-based sorting logic across postal automation systems, compressing misdirected parcel rates while elevating capital intensity for infrastructure upgrades.
Growth Catalysts
- EU Green Deal efficiency mandates:European postal operators face binding energy-efficiency targets for sorting infrastructure, accelerating procurement of next-generation tilt-tray and cross-belt sorter configurations.
- E-commerce fulfillment center expansion:Parcel volume surges from online retail are forcing courier companies to automate last-mile preparation facilities with high-throughput sorting architecture.
- Cloud-based deployment models:Postal operators are migrating parcel tracking systems to cloud infrastructure, creating demand for cybersecurity-compliant automation software stacks.
Market Restraints
- Steel and aluminum input volatility:Conveyor-scale integrators face margin pressure from fluctuating raw material costs for mechanical sorting components.
- CE marking compliance barriers:Non-compliant Asian equipment suppliers confront market access constraints under the EU Machinery Directive.
- Legacy system integration complexity:Brownfield postal hubs struggle to embed optical character recognition modules into decades-old mechanical infrastructure without full line replacement.
Strategic Opportunities
- Robotics automation in last-mile preparation:Unpenetrated deployment of robotic parcel handling creates white space for integrators targeting courier company micro-fulfillment nodes.
- ISO cybersecurity framework adoption:Tightening data governance standards for parcel tracking systems favor vendors with certified cloud-native architectures.
- Dynamic route optimization software:Convergence of machine learning algorithms with real-time barcode reading enables predictive sorting that reduces hub dwell times.
Industry Challenges
- Mechatronics engineering talent scarcity:Postal automation vendors compete for limited specialists capable of integrating mechanical sorting with AI-driven vision systems.
- F-Gas Regulation retrofit timelines:European operators must phase out refrigerants in temperature-controlled parcel handling, forcing accelerated capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postal Automation System Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Sorting Machines, Barcode Scanners, Letter Envelope Openers, Weighing Scales, Labeling Devices, Conveyors Technology: Optical Character Recognition, Radio Frequency Identification, Image Recognition, Machine Learning Algorithms, Robotics Automation, Voice Recognition End User: Postal Operators, Courier Companies, Logistics Providers, E-commerce Fulfillment Centers, Third-party Distribution, Government Agencies Delivery Model: On-premises Installation, Cloud-based Solutions, Hybrid Deployment, Software-as-a-Service, Managed Automation Services, Consulting Services |
| Companies Covered | Toshiba Corporation, BEUMER Group, Vanderlande Industries B.V., Dematic, Lockheed Martin Corporation, Siemens AG, NEC Corporation, Zebra Technologies Corp., Pitney Bowes Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postal Automation System Market Strategic Shifts & Innovations
Three intersecting forces are restructuring postal automation procurement: algorithmic sorting intelligence, emissions-driven equipment standards, and compressed buyer decision cycles for full-system contracts.
Optical character recognition is bifurcating into two performance tiers. High-speed address-reading modules now embed machine learning inference engines that handle degraded or handwritten labels. E-commerce fulfillment centers are adopting premium OCR configurations at twice the pace of legacy postal hubs. The technology is bifurcating vendor margins, separating image-recognition specialists from commodity barcode scanner suppliers.
The EU F-Gas Regulation is forcing refrigerant transitions in temperature-controlled parcel infrastructure. Postal operators must retrofit or replace sorting lines using hydrofluorocarbon-based cooling systems. German and French hub operators are most affected, accelerating procurement of air-cooled tilt-tray sorters that eliminate refrigerant dependency entirely.
Buyer concentration around full-system contracts is compressing vendor negotiation leverage. Postal operators now demand turnkey solutions spanning mechanical sorting, weighing, conveyor transport, and software integration from single integrators. This pattern is most visible in Germany, where Deutsche Post's modernization programs have consolidated procurement around conveyor-scale specialists rather than standalone equipment vendors.
Postal Automation System Market Segmentation
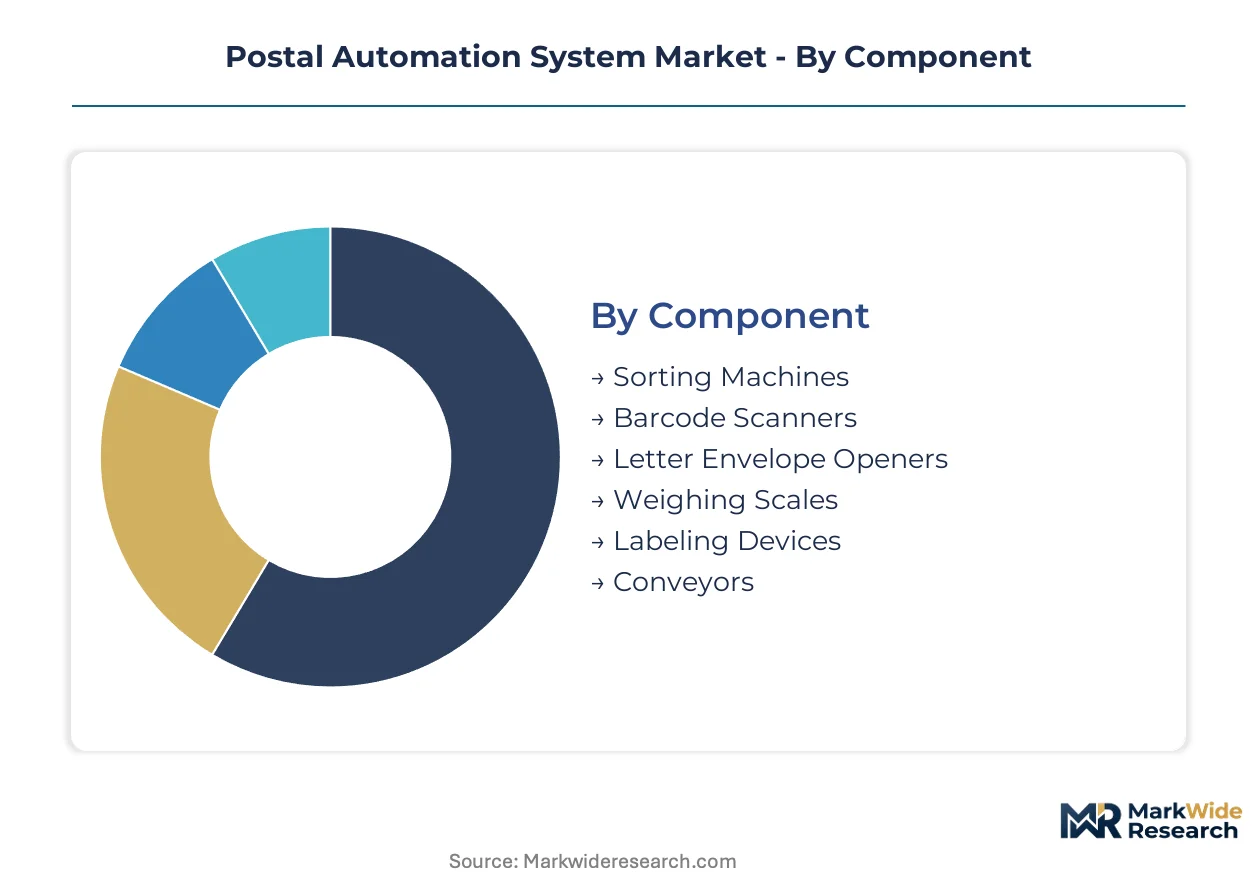
Segmentation in postal automation reveals how procurement decisions flow through distinct technical and commercial channels. Component selection determines integration complexity, while technology choices reshape competitive positioning among vendors.
Component:
Channel mix varies sharply by component category, with conveyor-scale integrators capturing full-system contracts while standalone equipment vendors serve retrofit markets.
- Sorting Machines:Tilt-tray and cross-belt configurations process over 40,000 items hourly in high-volume hubs. Deutsche Post's German modernization programs anchor regional demand for premium sorter installations, driven by EU Green Deal efficiency mandates that phase out legacy mechanical systems.
- Barcode Scanners:High-speed linear and area-imaging readers capture parcel data at conveyor speeds exceeding 3 meters per second. E-commerce fulfillment centers in Germany and France are replacing legacy laser scanners with machine learning-enhanced imagers to handle degraded label conditions.
- Letter Envelope Openers:Automated extraction systems process flat mail streams in postal operator primary sorting facilities. Government agencies maintain steady replacement demand for these specialized units.
- Weighing Scales:In-motion dynamic scales integrate with conveyor lines for real-time parcel dimensioning and weight capture. Courier companies deploy these at micro-fulfillment nodes for last-mile cost optimization.
- Labeling Devices:Print-and-apply systems generate shipping labels at induction points. Third-party distribution centers favor modular units that integrate with existing warehouse management software.
- Conveyors:Belt, roller, and accumulation conveyor segments form the physical backbone of automated lines. Logistics providers specify heavy-duty configurations for irregular parcel handling.
Sorting machines dominate installed base. Barcode scanners represent where expansion concentrates.
Technology:
Cost tier stratification separates premium AI-enabled modules from commodity hardware, with pricing spreads widening as machine learning capabilities become standard in high-end configurations.
- Optical Character Recognition:Address-reading engines parse printed and handwritten label data at sorting speeds. The technology bifurcates into two performance tiers, with premium OCR configurations embedding machine learning inference engines that handle degraded labels.
- Radio Frequency Identification:Passive UHF tags and readers enable non-line-of-sight parcel tracking in closed-loop logistics networks. Courier companies in France and Germany pilot RFID for high-value shipment authentication.
- Image Recognition:Camera-based systems detect parcel dimensions, damage, and orientation for automated handling decisions. E-commerce fulfillment centers adopt these modules at twice the pace of legacy postal hubs.
- Machine Learning Algorithms:Dynamic route optimization software reduces misdirected parcels by predicting sorting outcomes from real-time data streams. Cloud-based deployment models are expanding access to these capabilities for mid-sized operators.
- Robotics Automation:Articulated and collaborative robots handle irregular parcels in last-mile preparation. Unpenetrated deployment in micro-fulfillment nodes creates white space for integrators targeting courier companies.
- Voice Recognition:Hands-free operator interfaces support manual sorting exceptions and quality verification. Third-party distribution centers test these systems for ergonomic compliance.
Optical character recognition dominates installed base. Machine learning algorithms are where expansion concentrates.
End User:
Application intensity varies by end user, with e-commerce fulfillment centers demanding highest throughput density while government agencies prioritize reliability over speed.
- Postal Operators:National mail services operate the largest installed bases of automation equipment, with Deutsche Post, La Poste, and Royal Mail driving European procurement cycles. These entities face binding F-Gas Regulation retrofit timelines for temperature-controlled infrastructure.
- Courier Companies:Express parcel networks require flexible sorting architecture that adapts to volatile volume patterns. DHL Express and FedEx European hubs anchor demand for high-throughput tilt-tray configurations.
- Logistics Providers:Third-party operators integrate postal automation into broader supply chain offerings. Kuehne+Nagel and DSV specify modular systems that reconfigure for seasonal demand swings.
- E-commerce Fulfillment Centers:Amazon, Zalando, and Otto Group facilities are expanding automation procurement as parcel volumes surge from online retail. These buyers demand premium OCR and machine learning configurations.
- Third-party Distribution:Regional parcel consolidators and last-mile specialists deploy mid-scale sorting for interline handoffs. These operators favor hybrid deployment models that blend on-premises hardware with cloud software.
- Government Agencies:Military postal services and customs inspection facilities require certified automation for secure mail handling. CE marking compliance under the EU Machinery Directive constrains supplier selection.
Postal operators dominate installed base. E-commerce fulfillment centers are where expansion concentrates.
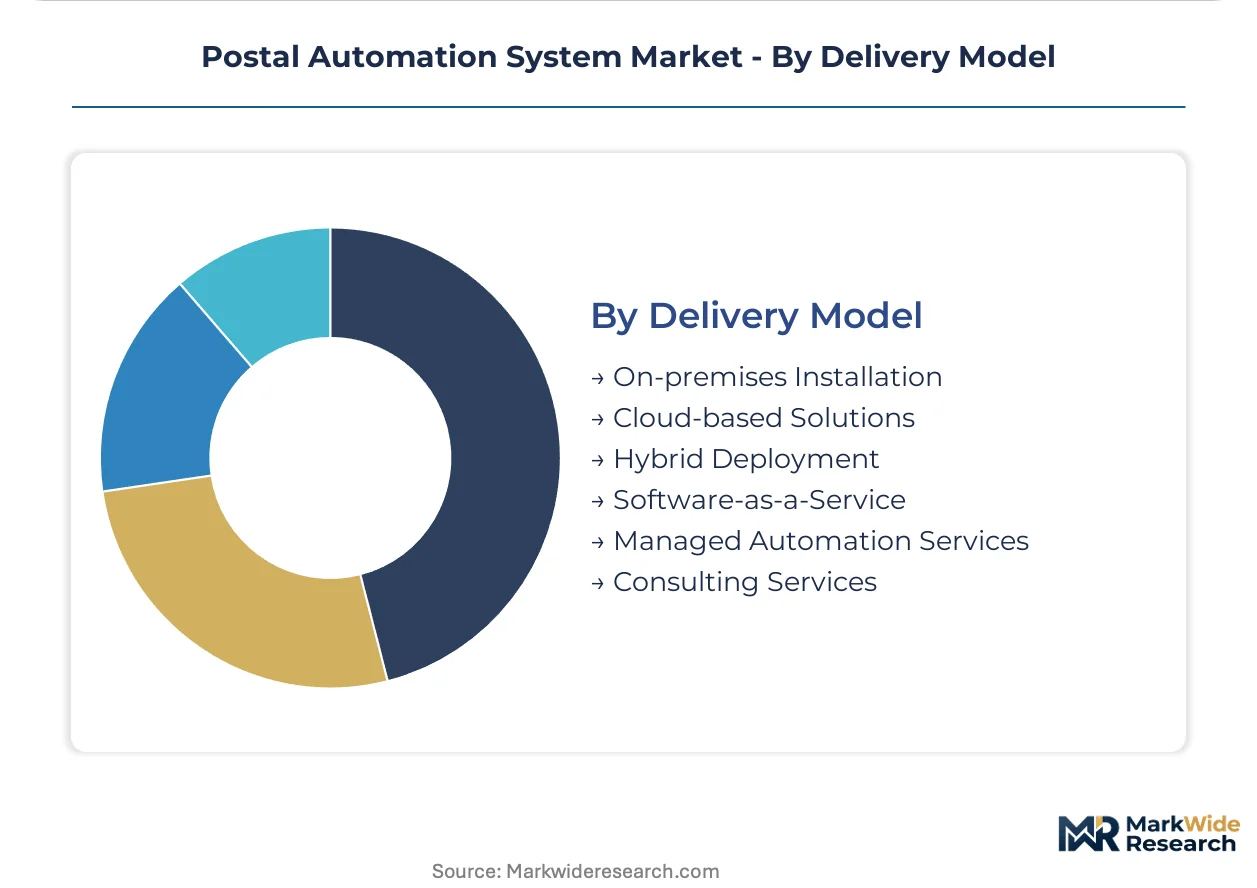
Delivery Model:
Customer type shapes delivery model selection, with large postal operators favoring capital-intensive on-premises installations while mid-tier buyers migrate toward operational expenditure models.
- On-premises Installation:Traditional capital expenditure model places full hardware and software ownership with the operator. German postal hubs anchor European demand for this model, driven by data sovereignty requirements and cybersecurity frameworks from ISO.
- Cloud-based Solutions:Software-defined automation enables remote monitoring, predictive maintenance, and dynamic route optimization from vendor-hosted infrastructure. Tightening GDPR and national data governance standards favor vendors with certified cloud-native architectures.
- Hybrid Deployment:Critical control systems remain on-premises while analytics and optimization layers migrate to cloud. French and Dutch operators pilot this architecture for parcel tracking systems.
- Software-as-a-Service:Subscription pricing for automation software reduces upfront capital requirements. Third-party distribution and regional courier companies favor this model for rapid deployment.
- Managed Automation Services:Vendors assume operational responsibility for equipment performance and uptime. Logistics providers contract these services for seasonal volume spikes.
- Consulting Services:System design, integration planning, and efficiency audits support brownfield modernization. Legacy postal hubs engage these services to navigate complex retrofit timelines.
On-premises installation dominates installed base. Cloud-based solutions are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Postal automation pricing power concentrates in Germany and France, where EU Green Deal mandates accelerate premium equipment procurement. Buyers in North America face less regulatory pressure but confront higher integration costs for legacy hub modernization.
Germany
Deutsche Post's nationwide modernization programs anchor European demand for tilt-tray and cross-belt sorter installations. The F-Gas Regulation forces accelerated retrofit timelines for temperature-controlled parcel infrastructure. North Rhine-Westphalia hosts the densest cluster of automated postal hubs, with DHL Express facilities in Cologne and Bonn driving high-throughput architecture procurement.
United States
USPS network rationalization and private courier hub expansion sustain demand for conveyor-scale integration. EPA emissions standards guide diesel-powered material handling fleet procurement decisions. The Chicago-Indianapolis corridor concentrates Midwest automation deployment, with FedEx and UPS ground hubs anchoring regional investment cycles.
France
La Poste's efficiency targets under EU Green Deal commitments drive energy-efficient sorting infrastructure replacement. ANSM and CNIL data governance frameworks shape cybersecurity requirements for parcel tracking systems. The Île-de-France region dominates procurement volume, with Roissy-Charles de Gaulle logistics zones hosting the highest concentration of automated parcel handling.
China
E-commerce fulfillment center expansion from Alibaba and JD.com sustains demand for high-speed barcode scanning and image recognition modules. MIIT industrial upgrading guidelines and GB standards constrain equipment certification pathways. The Yangtze River Delta cluster around Shanghai anchors domestic automation manufacturing, with Suzhou and Hangzhou emerging as sorting equipment integration centers.
Japan
Japan Post's aging workforce demographics accelerate robotics automation procurement for last-mile preparation facilities. METI energy efficiency benchmarks and JIS standards constrain equipment selection for brownfield hub upgrades. The Kanto region surrounding Tokyo concentrates installed base modernization, with Sagawa Express and Yamato Transport hubs driving premium OCR configuration demand.
Postal Automation System Market Key Industry Players
Concentration sits with conveyor-scale integrators capable of delivering turnkey full-system contracts. The vendor base separates into three functional tiers: industrial conglomerates with automation portfolios, specialized material handling fabricators, and component technology suppliers. Competitive dynamics revolve around strategic partnerships for software integration and geographic expansion through localized service networks.
Among diversified industrial conglomerates, Siemens AG and NEC Corporation exemplify contrasting positioning archetypes. Siemens leverages its industrial automation portfolio to anchor large postal hub projects, while NEC competes through image recognition and optical character recognition modules that embed into third-party sorting lines. BEUMER Group occupies a specialist position in high-throughput parcel sorting architecture, particularly for courier company fulfillment center deployments. These three companies represent the dominant competitive vectors: full-system integration, embedded software components, and specialized mechanical architecture.
| Leading Market Players |
|---|
| Toshiba Corporation |
| BEUMER Group |
| Vanderlande Industries B.V. |
| Dematic |
| Lockheed Martin Corporation |
| Siemens AG |
| NEC Corporation |
| Zebra Technologies Corp. |
| Pitney Bowes Inc. |
| Others |
Cost & Logistics Intelligence
Capacity utilization rates above 85% at German conveyor-scale integrators create pricing power asymmetries that favor full-system contractors over component vendors. This scale concentration elevates price floors for tilt-tray sorter configurations while compressing margins for standalone barcode scanner suppliers competing on commodity specifications.
Pricing Analysis
Configured-to-order pricing for full-system postal hub installations commands spreads of 40-60% above standard equipment catalog pricing. Project-based contracting dominates procurement, with price differentiation resting on CE marking certification tier and after-sales service bundling. Cost compression in mid-tier OCR modules is intensifying because Asian suppliers are circumventing machinery directive compliance through modular kit exports. E-commerce fulfillment centers exhibit lowest price sensitivity due to throughput-driven ROI calculations, while third-party distribution operators negotiate aggressively on hardware margins.
Supply Chain Analysis
Extended lead times for precision-machined aluminum frame components now stretch 16-22 weeks, constraining integrator delivery schedules. Manufacturing concentrates in Germany, China, and Japan, with production draws from steel conveyor belting, servo motor drives, and machine vision sensors. Single-source vulnerability sits with Japanese suppliers of high-speed linear barcode imagers. Distribution runs through direct OEM channels for large postal operators and regional distributor networks for retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postal automation is entering a cyclical upswing driven by EU F-Gas Regulation retrofit deadlines that compress replacement timelines. Equipment procurement cycles that stretched 36-48 months during the 2018-2022 period have contracted to 18-24 months.
For Market Incumbents: Secure long-term service contracts attached to full-system installations before cloud-native competitors displace on-premises maintenance revenue. Deepen backward integration into machine vision sensor production to offset Japanese supplier concentration risk. Anchor capacity expansion in North Rhine-Westphalia to capture Deutsche Post's sustained modernization demand.
For New Entrants and Emerging Players: Predictive maintenance software layers represent the most penetrable white space, as Siemens and BEUMER under-serve mid-tier courier companies with legacy on-premises architectures. Target French regional parcel consolidators with SaaS-tiered automation software that bypasses capital expenditure approval cycles. Lead with ISO-certified cybersecurity frameworks to differentiate against non-compliant Asian hardware vendors.
For Investors and Strategic Acquirers: Image-recognition specialists with embedded machine learning inference engines offer the strongest acquisition target archetype for platform consolidation plays. Monitor German postal hub automation award announcements as the inflection indicator for regional pricing power shifts. Long-term viability rests on software recurring revenue attachment rates rather than hardware shipment volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Full-System Integration Partnership | Consolidates procurement around single integrators as Deutsche Post's modernization programs demonstrate. |
| Machine Learning Inference Engine Development | Enables dynamic route optimization that reduces misdirected parcels in high-throughput e-commerce hubs. |
| CE Marking Certification Investment | Unlocks EU market access for Asian suppliers facing machinery directive compliance barriers. |
| Cloud-Native Architecture Migration | Captures mid-tier operators shifting from on-premises installations to subscription software models. |
| Air-Cooled Sorter Configuration Launch | Eliminates F-Gas refrigerant dependency for temperature-controlled parcel infrastructure retrofits. |
Research Approach
A standing panel of postal operations directors, conveyor-scale integrator project managers, e-commerce fulfillment center engineers, and logistics procurement leads provided ongoing calibration across the analysis window. Primary interview findings were cross-validated against secondary sources including EU Machinery Directive compliance databases, EPA emissions filings for material handling fleets, and customs trade data for steel and aluminum conveyor component flows. Bottom-up equipment shipment tallies were reconciled with top-down postal operator capital expenditure disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning component category, technology tier, end-user archetype, and delivery model complexity. CAGRs were derived from logistic curve fitting to equipment replacement cycles and e-commerce parcel volume elasticity coefficients. Forecast inputs incorporated F-Gas Regulation phase-out schedules and EU Green Deal efficiency mandate compliance timelines.
Forecasts assume regulatory continuity in EU machinery safety and emissions regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Home Automation and Controls Market
Automation
Voice Picking Solutions Market
Automation
Automation Testing Market
Automation
Process Automation Market
Automation
Global Process Automation and Instrumentation Market
Automation
Escalator Control Systems Market
Automation
Hyperautomation Market
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
Distribution Automation Solutions Market
Automation
Automatic Message Handling System Market
Automation
AR Automation Market
Automation
Global Field Force Automation Market
Automation
Computer Numerical Control Market
Automation
Italy Marketing Automation Market
Automation
Home Automation Market
Automation
Micro Fulfillment Market