
 Workload Automation Software Market | 2026-2036
Workload Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Workload Automation Software Market Outlook
Enterprise-grade SLA guarantees is collapsing the tolerance for manual job scheduling failures across Fortune 500 data centers. IBM Corporation leverages its mainframe heritage and hybrid cloud orchestration stack to anchor high-availability workloads in regulated industries. BMC Software, Inc. competes through Control-M's deep integration with SAP and Oracle ERP ecosystems, sustaining renewal rates among existing enterprise accounts. Stonebranch Inc. specializes in cloud-native workload automation, differentiating its Universal Automation Platform for Kubernetes and containerized pipelines.
Workload automation software orchestrates the execution, monitoring, and dependency management of batch processes, event-driven workflows, and real-time data pipelines across heterogeneous IT environments, typically interfacing with REST APIs, message queues, and mainframe JCL scripts to ensure deterministic completion within defined service windows. The primary commercial purpose is to eliminate manual intervention in repetitive computational sequences, thereby reducing operational expenditure and error rates in mission-critical systems. Cloud-based deployment is capturing the fastest expansion as organizations retire on-premises data centers, while hybrid configurations retain the largest margin pools due to complex integration requirements spanning legacy and modern infrastructure. Among end users, finance institutions generate the highest absolute spending on workload automation, driven by end-of-day reconciliation and regulatory reporting obligations that demand zero-fault execution.
The National Institute of Standards and Technology (NIST) and the Federal Risk and Authorization Management Program (FedRAMP) shape procurement standards for U.S. federal adopters, mandating continuous monitoring and encrypted credential vaulting that elevates vendor qualification barriers. The EU AI Act and GDPR impose algorithmic transparency and data residency constraints on automation platforms processing personal information within European member states, compelling vendors to deploy region-isolated control planes. Stakeholders must monitor how generative AI copilots integrate with legacy scheduler APIs, as this convergence threatens to commoditize basic orchestration while creating premium tiers for autonomous remediation capabilities.
Market Dynamics
Cloud-native deployment architectures are displacing legacy mainframe schedulers as financial services and healthcare sectors modernize mission-critical batch processing infrastructure. This structural migration is compressing vendor margins while elevating compliance requirements across regulated industries.
Growth Catalysts
- FedRAMP Authorization Requirements:United States federal procurement mandates continuous monitoring and encrypted credential vaulting, elevating vendor qualification barriers and consolidating demand around authorized providers.
- End-of-Day Reconciliation Workloads:Financial institutions generate sustained demand for zero-fault execution in regulatory reporting and settlement systems, anchoring premium pricing for high-availability orchestration.
- Kubernetes-Native Pipelines:Containerized microservices adoption in enterprise IT departments creates pull for event-driven automation that interfaces with REST APIs and message queues.
Market Restraints
- Legacy Integration Complexity:Hybrid configurations spanning mainframe JCL scripts and modern cloud APIs require specialized engineering talent that commands premium compensation.
- GDPR Data Residency Constraints:European algorithmic transparency mandates compel vendors to deploy region-isolated control planes, fragmenting R&D investment across duplicate infrastructure stacks.
- Generative AI Copilot Commoditization:Autonomous remediation capabilities threaten to erode pricing power for basic orchestration functions as large language models integrate with scheduler APIs.
Strategic Opportunities
- EU AI Act Compliance Services:Auditable policy-driven automation pipelines represent premium service tiers as European enterprises seek deterministic execution with full traceability.
- Real-Time Data Pipeline Orchestration:Event-driven workflow adoption in streaming analytics creates expansion potential beyond traditional batch processing use cases.
- Healthcare IT Modernization:HIPAA-compliant workload automation for electronic health record reconciliation remains underpenetrated relative to financial services saturation.
Industry Challenges
- Mainframe-to-Cloud Skill Migration:Organizations struggle to retain expertise in both COBOL-era job control language and contemporary container orchestration paradigms.
- Multi-Cloud Credential Vaulting:Cross-platform encryption key management across AWS, Azure, and GCP environments introduces operational complexity and audit surface area.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workload Automation Software Market |
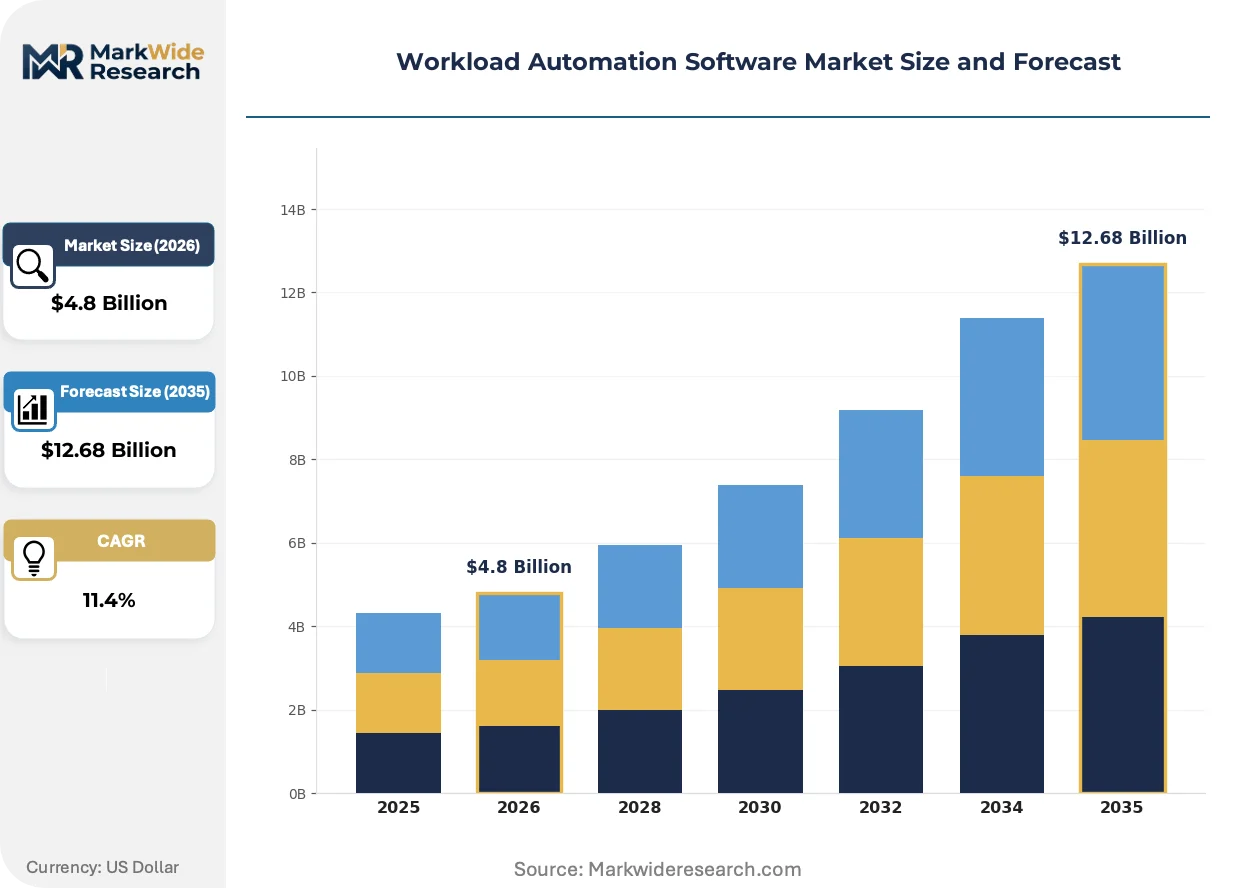
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: IT Departments, Finance Institutions, Retail Chains, Telecom Providers Use Case: Data Backup, Report Generation, Task Scheduling, Resource Allocation Industry Vertical: Healthcare, Manufacturing, Energy, Education |
| Companies Covered | IBM Corporation, BMC Software, Inc., CA Technologies, Redwood Software, Inc., VMWare Inc., Oracle Corporation, ServiceNow, Stonebranch Inc., ActiveBatch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workload Automation Software Market Strategic Shifts
Agentic AI capabilities are converging with legacy scheduler APIs, creating bifurcation between commodity orchestration and premium autonomous remediation tiers. This technological inflection is reshaping how vendors structure product roadmaps and pricing architectures.
Event-driven automation is fragmenting the traditional batch-processing paradigm as streaming data pipelines displace fixed-window scheduling. Capital markets firms and real-time fraud detection systems are adopting continuous workflow triggers that respond to message queue depth rather than clock-based initiation. This shift is fragmenting vendor R&D priorities between maintaining legacy scheduler compatibility and building cloud-native reactive engines.
The EU AI Act's algorithmic transparency requirements are compelling workload automation vendors to deploy immutable audit logs and explainable decision trees for every automated action. Industrial consequence includes mandatory documentation of dependency chains and failure remediation logic for systems processing personal data. Financial services institutions in Germany and France are responding by demanding policy-as-code configurations that encode regulatory rules directly into execution pipelines.
Enterprise buyers are consolidating vendor relationships around platforms offering unified visibility across on-premises data centers and multi-cloud environments. Systems integrators and managed service providers are displacing direct software licensing as the primary procurement channel, particularly among mid-market organizations lacking specialized automation engineering teams. This concentration is most visible in United States healthcare networks, where IT modernization budgets favor outsourced operational responsibility over in-house platform deployment.
Workload Automation Software Market Segmentation
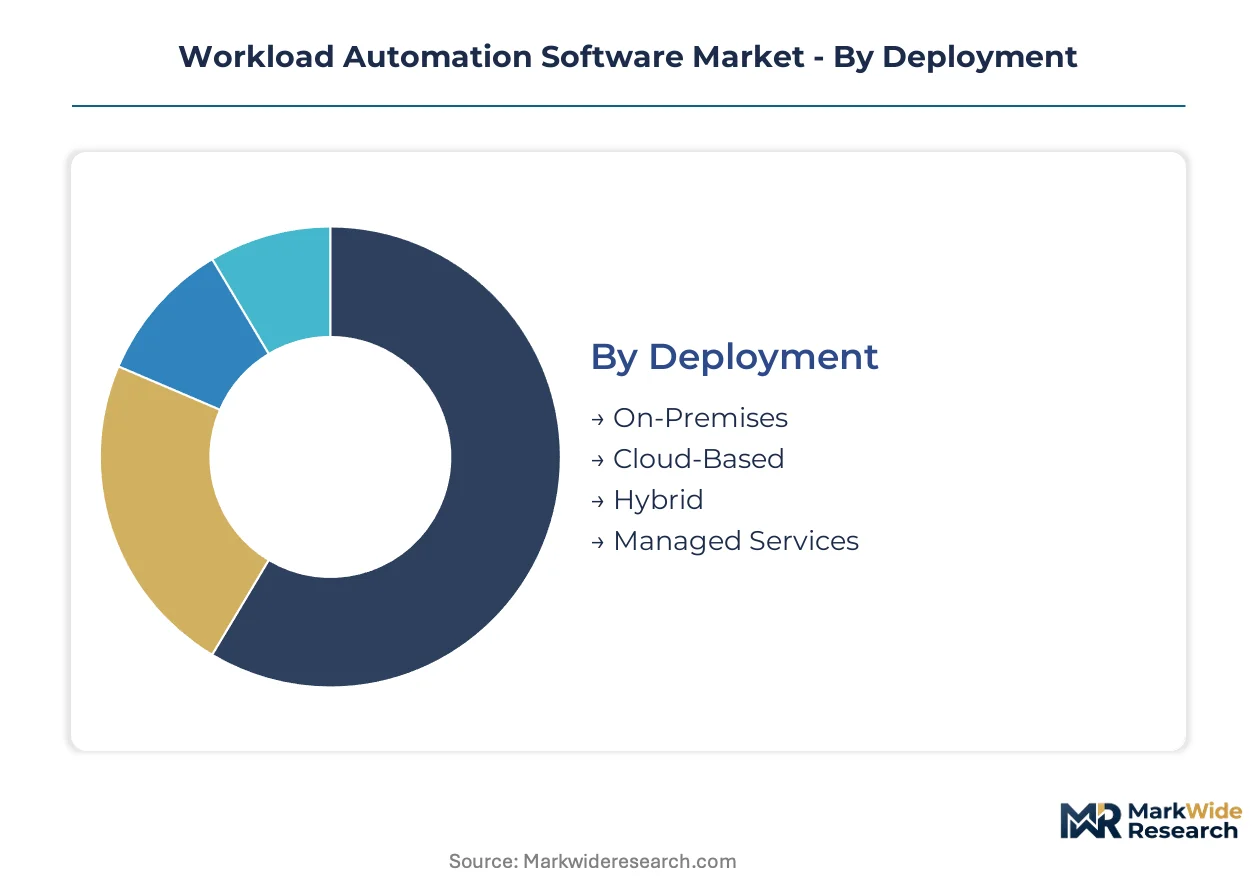
Workload automation software segments diverge sharply across deployment models and compliance postures. Regulatory mandates from FedRAMP and GDPR reshape which configurations command premium pricing versus commodity positioning.
Deployment:
FedRAMP authorization and GDPR data residency rules fragment procurement criteria across deployment modes.
- On-Premises:Legacy mainframe schedulers retain dominance in financial services end-of-day reconciliation workflows where deterministic execution within fixed service windows remains non-negotiable. United States federal agencies and German financial institutions sustain demand for air-gapped infrastructure meeting encrypted credential vaulting mandates.
- Cloud-Based:Kubernetes-native orchestration platforms capture expansion as healthcare networks and retail chains retire on-premises data centers. Containerized microservices adoption in United States enterprise IT departments accelerates event-driven automation interfacing with REST APIs.
- Hybrid:Configurations spanning mainframe JCL scripts and cloud APIs command the largest margin pools due to complex integration requirements. United Kingdom banking consortiums and French insurance groups prioritize unified visibility across legacy and modern infrastructure.
- Managed Services:Outsourced operational responsibility appeals to mid-market organizations lacking specialized automation engineering teams. United States healthcare networks favor procurement through systems integrators over direct platform licensing.
Established volume favors On-Premises; emerging adoption favors Cloud-Based.
End User:
Customer sophistication and regulatory exposure determine automation investment intensity.
- IT Departments:Centralized platform procurement across heterogeneous environments drives standardization efforts. United States federal agencies mandate continuous monitoring capabilities that elevate vendor qualification barriers.
- Finance Institutions:Zero-fault execution requirements in regulatory reporting and settlement systems anchor premium pricing. German and French banking groups demand policy-as-code configurations encoding EU AI Act transparency rules directly into execution pipelines.
- Retail Chains:Seasonal demand spikes and supply chain synchronization create pull for elastic workload scheduling. Inventory reconciliation across distributed warehouse networks in the United States and United Kingdom dominates use cases.
- Telecom Providers:Network operations center automation for billing cycle processing and service provisioning drives adoption. Real-time fraud detection systems in Japanese and South Korean markets adopt continuous workflow triggers responding to message queue depth.
Finance Institutions concentrate the highest absolute spending; Retail Chains expand most quickly.
Use Case:
Functional automation requirements stratify across batch versus event-driven paradigms.
- Data Backup:Immutable audit logs and encrypted credential vaulting satisfy HIPAA and GDPR mandates for healthcare and financial data protection. United States hospital networks and German insurance groups prioritize deterministic completion within defined recovery windows.
- Report Generation:End-of-day reconciliation and regulatory filing automation sustains demand in capital markets. French and German financial institutions require explainable decision trees documenting dependency chains for every automated action.
- Task Scheduling:Clock-based initiation retains dominance in legacy mainframe environments. COBOL-era job control language expertise scarcity constrains migration timelines in United States federal systems.
- Resource Allocation:Dynamic workload placement across multi-cloud environments responds to cost optimization pressures. Cross-platform encryption key management across AWS, Azure, and GCP introduces operational complexity for United Kingdom enterprises.
Report Generation anchors renewal revenue; Resource Allocation gains share fastest.
Industry Vertical:
Sector-specific compliance frameworks reshape automation platform requirements.
- Healthcare:HIPAA-compliant workload automation for electronic health record reconciliation remains underpenetrated relative to financial services saturation. United States hospital networks drive demand for FedRAMP-authorized platforms with encrypted credential vaulting.
- Manufacturing:Supply chain synchronization and IoT data pipeline orchestration create pull for event-driven automation. German industrial conglomerates adopt policy-as-code configurations meeting EU AI Act algorithmic transparency requirements.
- Energy:Grid balancing and trading settlement systems demand zero-fault execution in deregulated markets. United Kingdom and German utility regulators mandate immutable audit logs for automated dispatch decisions.
- Education:Student information system batch processing and financial aid reconciliation represent lower-complexity use cases. United States public university systems favor managed services procurement to offset limited IT engineering capacity.
Healthcare concentrates regulatory premium; Manufacturing climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workload automation software flows predominantly from US and European vendors toward Asia-Pacific financial centers, with net imports concentrated in emerging markets modernizing legacy infrastructure. Cross-border procurement patterns reflect regulatory divergence between FedRAMP-authorized US platforms and GDPR-compliant European alternatives.
United States
Federal IT modernization budgets and FedRAMP authorization requirements drive procurement concentration among defense contractors and healthcare networks. NIST cybersecurity frameworks mandate encrypted credential vaulting that elevates vendor qualification barriers. New York financial institutions and Washington DC federal agencies anchor demand for zero-fault reconciliation systems.
Germany
Industrial conglomerates and banking groups generate sustained demand for auditable automation pipelines under EU AI Act transparency mandates. BSI federal cybersecurity standards enforce immutable audit logs for critical infrastructure operators. Frankfurt's financial district and Munich's industrial corridor concentrate deployment of policy-as-code configurations.
United Kingdom
Post-Brexit regulatory autonomy has fragmented procurement between domestic standards and EU alignment pressures. Financial Conduct Authority operational resilience rules compel banking groups to maintain deterministic execution capabilities. London's capital markets firms and Edinburgh's insurance sector drive hybrid cloud orchestration adoption.
Japan
Real-time fraud detection systems in capital markets create pull for event-driven automation responding to message queue depth. METI digital transformation subsidies accelerate retirement of legacy mainframe schedulers in regional banks. Tokyo's financial district and Osaka's manufacturing clusters lead Kubernetes-native pipeline deployment.
India
IT service providers and banking modernization programs generate import demand for orchestration platforms supporting multi-cloud environments. RBI guidelines on operational continuity mandate automated failover systems for systemically important financial institutions. Mumbai's financial services sector and Bangalore's technology corridor concentrate enterprise automation adoption.
Workload Automation Software Market Competitive Environment
Concentration sits with heritage technology conglomerates that anchor high-availability workloads through hybrid cloud orchestration stacks. The vendor landscape exhibits tiered stratification between mainframe-anchored incumbents, cloud-native specialists, and cross-platform integrators. Dominant competitive moves include strategic partnerships with systems integrators and portfolio diversification into adjacent IT service management categories.
Within the heritage technology tier, IBM Corporation and Oracle Corporation exemplify vendors leveraging decades of enterprise relationships to sustain renewal rates in regulated industries. BMC Software, Inc. occupies a position bridging legacy scheduler compatibility with modern API-driven orchestration. Stonebranch Inc. represents the cloud-native specialist archetype, anchoring differentiation around containerized pipeline expertise. These three vendors collectively illustrate the competitive tension between defending incumbent positions and capturing cloud-migration expansion.
| Leading Market Players |
|---|
| IBM Corporation |
| BMC Software, Inc. |
| CA Technologies |
| Redwood Software, Inc. |
| VMWare Inc. |
| Oracle Corporation |
| ServiceNow |
| Stonebranch Inc. |
| ActiveBatch |
| Others |
Value Chain & Pricing Dynamics
Cloud-native container orchestration displacing legacy mainframe schedulers simultaneously redistributes supply geography toward Kubernetes engineering talent pools and compresses pricing power for on-premises licensing models. This substitution dynamic forces vendors to rebundle value around FedRAMP compliance and EU AI Act auditability rather than perpetual license maintenance.
Pricing Analysis
Finance institutions anchor pricing stratification across premium, standard, and economy tiers based on SLA guarantees and encrypted credential vaulting certification levels. FedRAMP-authorized deployments command substantial premiums over unauthorized alternatives, while mid-market healthcare networks exhibit acute price sensitivity favoring managed services procurement. Cost compression in standard-tier SaaS offerings intensifies as generative AI copilots erode differentiation for basic orchestration functions.
Supply Chain Analysis
Inbound logistics costs for specialized compliance engineering talent concentrate supply chain value capture in the United States, Germany, and the United Kingdom where FedRAMP assessors and EU AI Act auditors cluster. Platform development draws from open-source Kubernetes communities, proprietary mainframe compatibility layers, and cloud hyperscaler API ecosystems. Single-source vulnerability in FedRAMP authorization pathways creates concentration risk for federal procurement channels. Distribution runs through systems integrators and managed service providers rather than direct licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
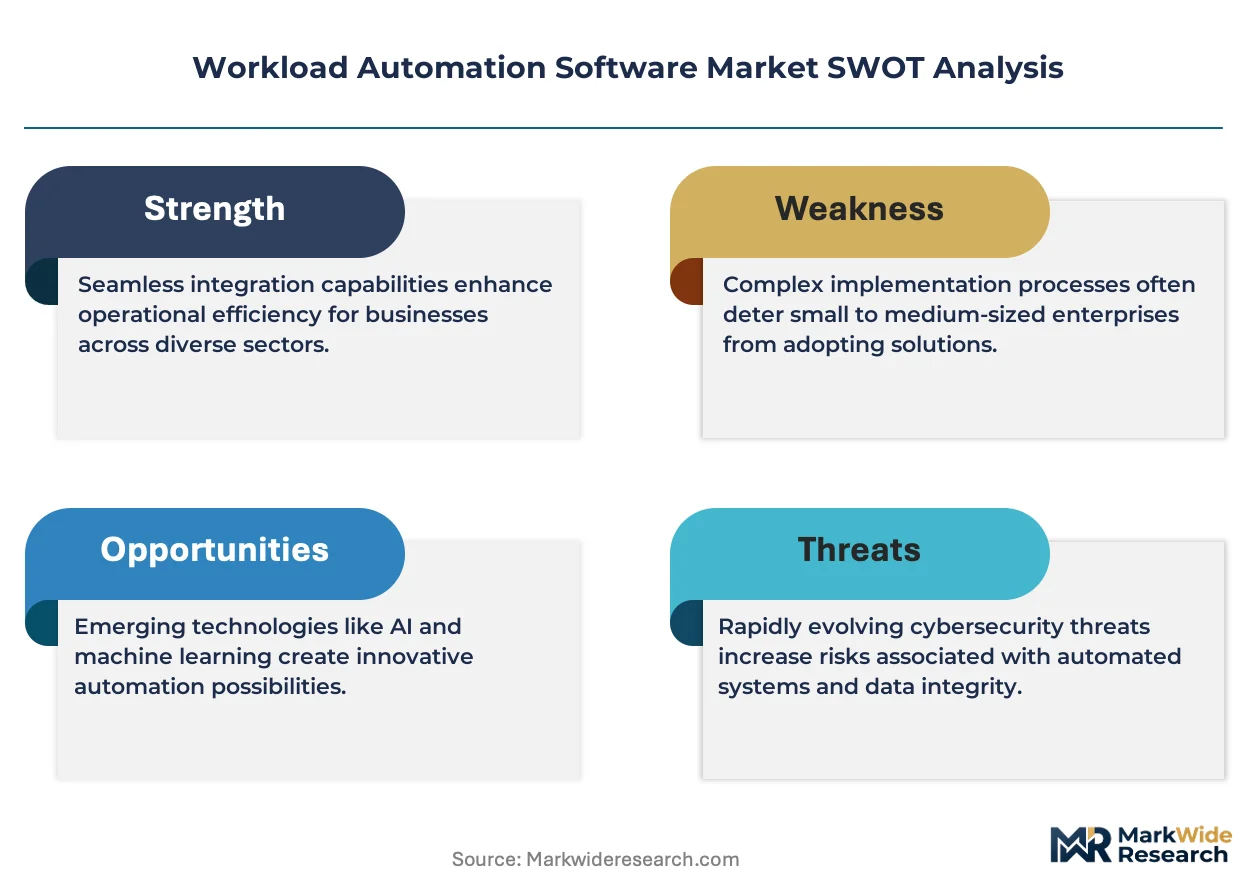
This market presents a defensive-moat story anchored in regulatory entrenchment. Switching costs for mission-critical batch workflows create sticky revenue bases that resist competitive displacement.
For Market Incumbents: Secure FedRAMP authorization renewals ahead of federal procurement consolidation waves. Invest in policy-as-code configuration engines that encode EU AI Act transparency requirements directly into execution pipelines, neutralizing cloud-native specialist threats through compliance depth that emerging players cannot replicate.
For New Entrants and Emerging Players: Lead with Kubernetes-native orchestration for healthcare IT modernization where HIPAA-compliant electronic health record reconciliation remains underpenetrated relative to financial services saturation. Target mid-market United States hospital networks through managed services partnerships that offset limited in-house automation engineering capacity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud-native workload automation specialists possessing container orchestration expertise but lacking mainframe integration depth. Long-term viability hinges on hybrid cloud positioning that bridges legacy JCL environments with modern API-driven pipelines. Watch for inflection signals in generative AI copilot integration velocity that could commoditize basic orchestration tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Unlocks United States federal procurement channels with continuous monitoring mandates. |
| Policy-as-Code Platform Development | Encodes EU AI Act algorithmic transparency requirements directly into automation pipelines. |
| Healthcare Managed Services Expansion | Captures mid-market hospital networks lacking specialized automation engineering teams. |
| Kubernetes-Native Pipeline Integration | Interfaces with containerized microservices adoption in enterprise IT departments. |
| Mainframe Compatibility Layer Acquisition | Secures COBOL-era job control language expertise for hybrid cloud orchestration. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with workload automation vendors, systems integrators, and IT procurement officers at financial institutions and healthcare networks; and secondary validation through SEC 10-K filings, FedRAMP authorization databases, hyperscaler capex disclosures, and EU regulatory filings. Bottom-up deployment model sizing triangulated against top-down vertical spending estimates across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning deployment architecture, end-user sophistication, functional use case, and industry vertical compliance posture. CAGRs derived from historical vendor revenue trajectories, cloud migration velocity indicators, and regulatory mandate implementation timelines. Forecast inputs incorporated Kubernetes adoption curves in enterprise IT and FedRAMP authorization pipeline throughput.
The analysis sits within stated boundaries; outcomes outside sustained cloud migration momentum or accelerated generative AI commoditization would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement consistency and federal IT modernization budget continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Form Automation Software Market
Automation
Data Center Automation Market
Automation
Industrial Vending Machines Market
Automation
Universal Process Control Market
Automation
Global Field Force Automation Market
Automation
Dropshipping Automation Software Market
Automation
Modular Laboratory Automation Market
Automation
Italy Process Orchestration Market
Automation
Europe Data Center Automation Market
Automation
Europe Laboratory Automation Market
Automation
Italy Marketing Automation Market
Automation
Terminal Automation Systems Market
Automation
Home Automation and Controls Market
Automation
Smart Home Automation Market
Automation
IoT Home Automation Market
Automation
Automated Cell Block Systems Market