
 Robotic Welding Market | 2026-2036
Robotic Welding Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Welding Market Intelligence
Buyer concentration among automotive OEMs is repositioning procurement leverage toward contract manufacturers and tier-1 suppliers seeking flexible automation. FANUC sustains dominance through its integrated controller and servo motor ecosystem. YASKAWA Electric Corporation anchors Asian supply chains with deep manufacturing scale in arc welding robots. Lincoln Electric differentiates through captive wire and consumables production paired with robotic system integration.
Robotic welding encompasses programmable multi-axis manipulators that direct welding torches or guns along prescribed joint paths, typically achieving positional repeatability within 0.1 mm and operating at payloads from 6 kg to over 700 kg for heavy fabrication. These systems serve primarily to automate fusion joining of metals in high-volume or hazardous environments where manual consistency proves difficult. Articulated robots occupy the dominant product position due to six-axis flexibility reaching complex joint geometries, while laser welding technology captures expanding share in battery tray and aerospace applications demanding minimal heat-affected zones. Spot welding retains mature saturation in automotive body-in-white lines, though margin pools increasingly shift toward integrated vision-guided seam tracking and adaptive process control.
FDA oversight of welding in medical device fabrication, OSHA exposure limits for welding fumes, and ISO 10218 safety standards for industrial robot integration collectively shape product design and facility compliance costs across manufacturing jurisdictions. The EU Machinery Directive and CE marking requirements further constrain market access for non-compliant robotic welding equipment imported into Europe. Stakeholders must monitor evolving carbon border adjustments and local content rules that threaten to fragment supply chain configurations for welding automation hardware.
Market Dynamics
The automotive industry's pivot toward electric vehicle architectures is compressing welding cycle times and demanding precision tolerances that legacy manual processes cannot sustain. This structural pressure is redistributing capital allocation across the entire fabrication equipment supply base.
Growth Catalysts
- EU Green Deal carbon intensity mandates:European OEMs face binding emissions reduction targets that favor automated welding's energy efficiency over manual operations with higher rework rates.
- Battery tray laser welding:EV manufacturers require heat-minimized joining techniques for aluminum-intensive battery enclosures that arc welding cannot reliably deliver.
- China's dual carbon goals:Provincial industrial policies in Jiangsu and Guangdong subsidize robotic welding retrofits to reduce energy consumption per unit of output.
Market Restraints
- Controller and servo motor supply concentration:Japanese and German component suppliers dominate precision motion control hardware, creating single-source vulnerability for system integrators.
- Skilled welding technician shortage:The gap between available certified programmers and deployed robot density limits utilization rates in North American job shops.
- Copper and rare earth magnet cost volatility:Motor winding materials and permanent magnet inputs expose equipment margins to commodity price swings.
Strategic Opportunities
- Indian automotive component manufacturing:PLI scheme incentives for domestic auto parts production create first-mover advantage for welding automation suppliers establishing local integration capability.
- Vision-guided seam tracking convergence:Integration of structured light scanning with adaptive torch control opens premium pricing in aerospace and medical device fabrication.
- Rental and lease channel development:Pay-per-part financing models lower entry barriers for mid-tier contract manufacturers in Mexico and Vietnam.
Industry Challenges
- ISO 10218-1 safety certification timelines:Validation protocols for collaborative welding cells extend product launch schedules by 8-14 months.
- Legacy PLC integration complexity:Retrofitting robotic welding stations into existing automotive body shop lines requires custom middleware development.
- Welding procedure qualification transfer:Migrating certified manual weld specifications to automated parameters demands extensive destructive testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Welding Market |
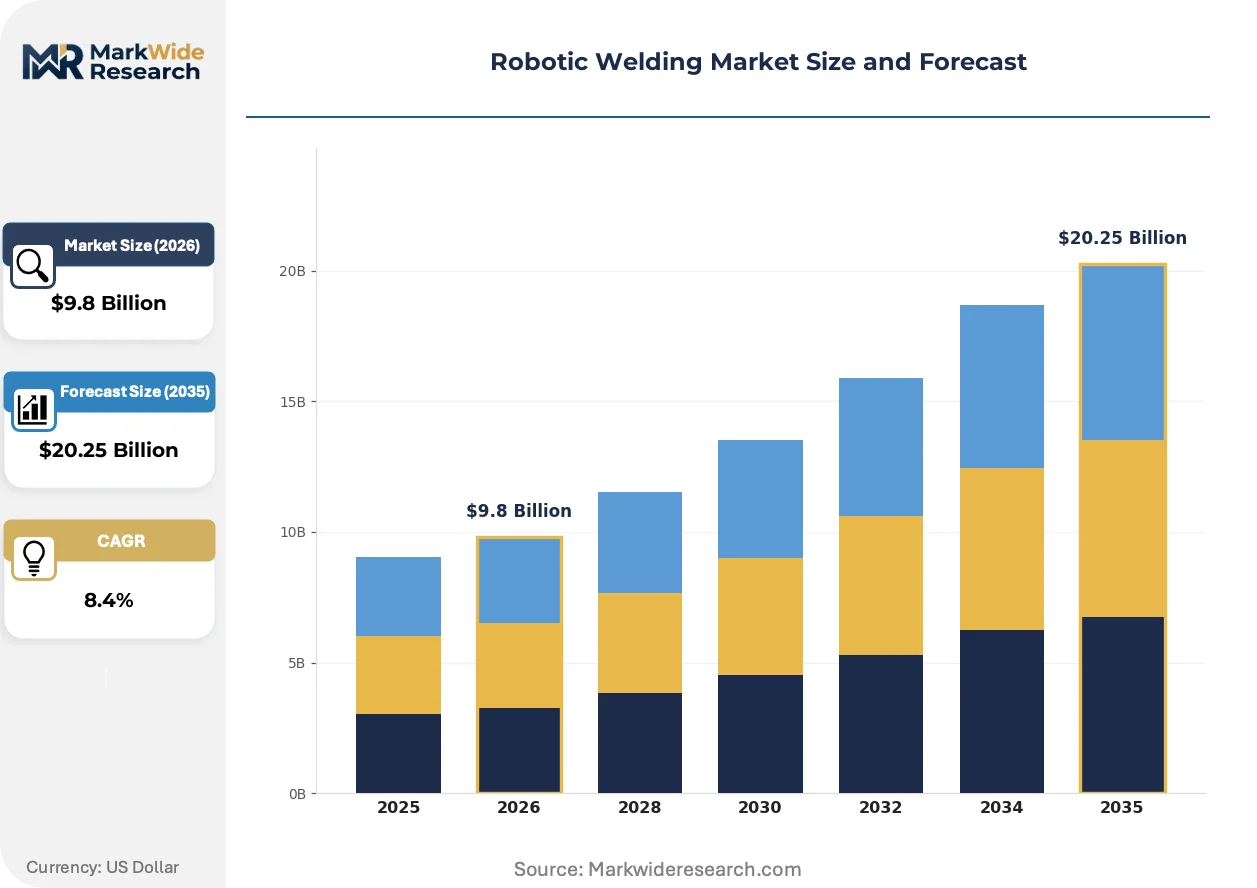
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, Cartesian Robots, SCARA Robots, Cylindrical Robots, Parallel Robots Technology: MIG Welding, TIG Welding, Spot Welding, Laser Welding, Plasma Arc Welding Application: Shipbuilding, Aerospace Manufacturing, General Manufacturing, Metal Fabrication, Defense Equipment End User: OEMs, Contract Manufacturers, Job Shops, Tier-1 Suppliers, Aftermarket Providers |
| Companies Covered | ABB, Panasonic Corporation, FANUC, Lincoln Electric, DAIHEN Corporation, YASKAWA Electric Corporation, Kawasaki Heavy Industries, Hyundai Robotics, KUKA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Welding Market Strategic Shifts & Innovations
Process sensing and real-time adaptive control are converging to eliminate post-weld inspection bottlenecks. This capability shift is compressing the traditional separation between fabrication and quality assurance functions.
Laser-arc hybrid welding systems combine fiber laser keyhole penetration with gas metal arc fill metal deposition. Automotive battery tray manufacturers in Germany and South Korea are adopting these cells at pilot scale. The technology is electrifying throughput expectations for aluminum joining applications previously constrained by porosity defects.
REACH authorization requirements for hexavalent chromium compounds in anti-spatter agents are forcing reformulation of welding consumables. European fabricators must validate alternative ceramic-based spatter prevention by 2026. The regulatory pressure is concentrating procurement decisions on consumables suppliers with captive regulatory affairs capabilities.
Automotive OEMs are unbundling after-sales service contracts from initial equipment purchases. Tier-1 suppliers now procure welding robots without mandatory multi-year maintenance agreements. This purchasing pattern shift is most visible in North American stamping and assembly operations where in-house maintenance groups have matured technical competency.
Robotic Welding Market Segmentation
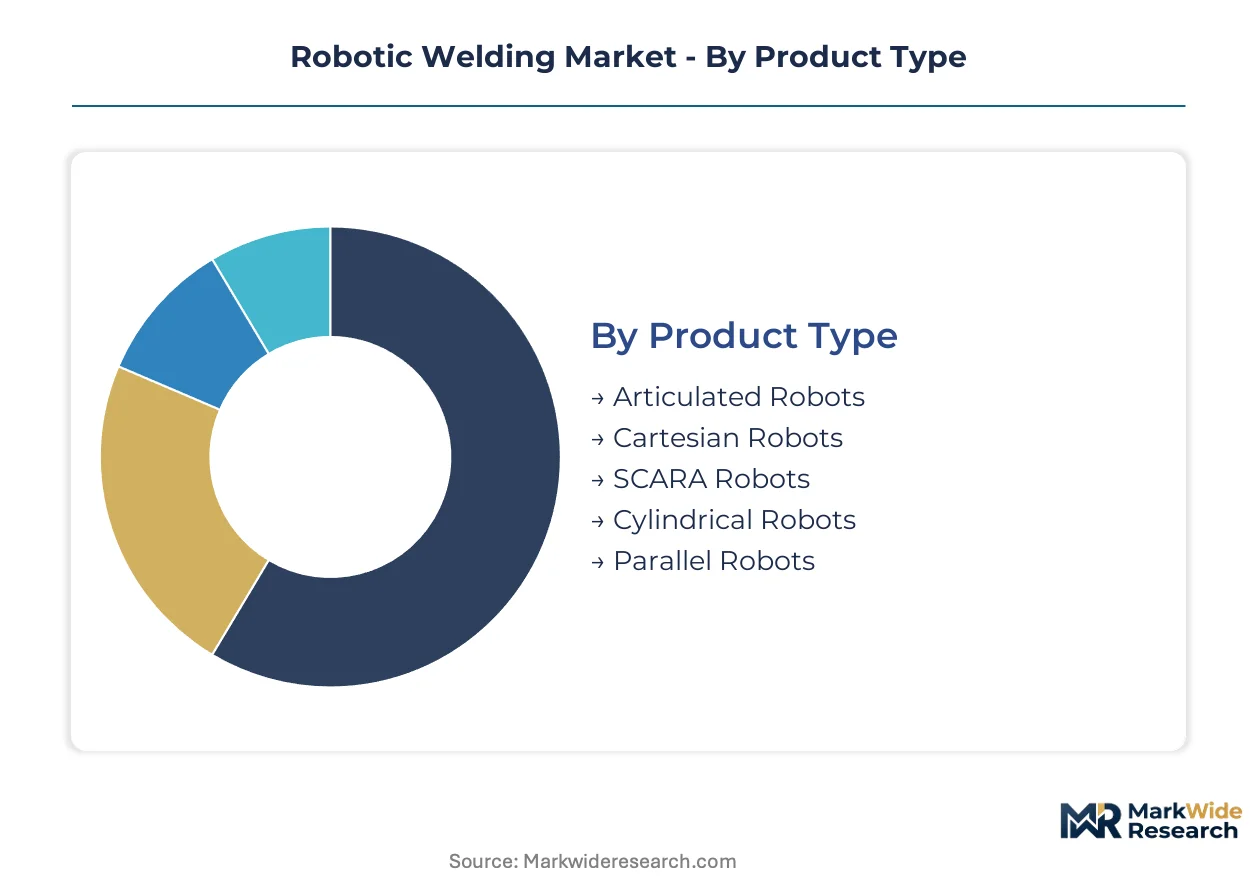
Segmentation in robotic welding reveals how capital allocation priorities diverge across equipment specifications, joining technologies, and buyer sophistication levels. Upgrade cycles vary dramatically by segment, with some categories replacing systems every 7-10 years while others extend to 15-year horizons.
Product Type:
Replacement urgency concentrates in configurations where six-axis flexibility has become non-negotiable for new part geometries, while legacy linear systems persist in stable high-volume lines.
- Articulated Robots:Six-axis kinematic chains with rotational joints enabling complex seam access in automotive body-in-white and aerospace structural assemblies. Automotive OEMs in Germany and Japan dominate procurement for new greenfield EV battery tray lines where reach envelopes must accommodate varying enclosure dimensions. FANUC and YASKAWA controller ecosystems lock in upgrade continuity.
- Cartesian Robots:Linear motion systems with orthogonal prismatic joints delivering high positional accuracy across large work envelopes. Metal fabrication shops in China's Pearl River Delta favor these for gantry-mounted plasma cutting and straight-line welding where part variety remains limited. Lower capital cost extends replacement cycles versus articulated alternatives.
- SCARA Robots:Selective compliance articulated arms optimized for planar assembly tasks with limited vertical reach.
- Cylindrical Robots:Revolute-prismatic hybrid configurations offering rotational sweep with radial extension.
- Parallel Robots:Closed-loop kinematic chains with high stiffness-to-weight ratios for precision spot welding.
Articulated Robots sits at the top of the volume ranking, with Parallel Robots climbing the fastest.
Technology:
Process selection tracks directly to material thickness, joint accessibility, and heat input tolerance specifications that vary by end-use certification requirements.
- MIG Welding:Consumable electrode processes using continuous wire feed and shielding gas for high-deposition joining of carbon steels. General manufacturing facilities in Mexico's Bajío automotive corridor deploy these for chassis component production where throughput outweighs cosmetic requirements. Spatter generation remains the primary quality constraint.
- Laser Welding:Concentrated coherent beam energy achieving narrow heat-affected zones with minimal distortion in aluminum and high-strength steel alloys. Battery tray manufacturers in South Korea and Germany specify fiber laser cells for EV enclosure joining where porosity control determines IP67 sealing validation. Capital intensity limits deployment to OEM-owned facilities.
- TIG Welding:Non-consumable tungsten electrode processes with precise amperage control for exotic alloys.
- Spot Welding:Resistance welding through copper alloy electrodes for overlapping sheet metal in body-in-white construction.
- Plasma Arc Welding:Constricted arc processes with keyhole penetration capability for thick-section materials.
MIG Welding commands the largest installed base, though Laser Welding is expanding most quickly in EV-related capital expenditure.
Application:
Industry-specific certification regimes and production batch characteristics fragment procurement specifications across verticals.
- Aerospace Manufacturing:Precision joining of titanium, nickel superalloys, and aluminum-lithium structures subject to NADCAP and AS9100 quality mandates. Tier-1 aerostructures suppliers in Toulouse and Wichita invest in vision-guided seam tracking for airframe stringer-to-skin welds where radiographic inspection reject rates must stay below 0.5 percent. Process qualification timelines extend 18-24 months.
- Shipbuilding:Heavy-section steel fabrication with thick-plate groove welding in panel lines and block assembly. Korean and Chinese shipyards automate panel welding for container vessel construction where distortion control reduces fairing labor. Sublime arc and electroslag processes dominate over robotic alternatives for ultra-thick sections.
- General Manufacturing:Diverse production environments with mixed batch sizes and material specifications.
- Metal Fabrication:Job shop environments with high part variety and short lead time requirements.
- Defense Equipment:Armored vehicle and weapons system fabrication with classified process specifications.
Aerospace Manufacturing leads in average system value per installation, with Shipbuilding showing the steepest expansion trajectory in absolute unit terms.
End User:
Technical competency depth and capital access determine whether buyers self-integrate or outsource programming and maintenance functions.
- OEMs:Original equipment manufacturers with captive engineering teams managing multi-vendor robot fleets across global production networks. Automotive OEMs in Stuttgart and Detroit standardize on specific controller platforms to minimize spare parts proliferation and technician training overhead. These buyers unbundle service contracts and self-perform preventive maintenance.
- Tier-1 Suppliers:Direct component providers to OEM assembly plants with dedicated welding cells for single-customer programs. Seating and exhaust system manufacturers in Ontario and Lower Saxony deploy robotic welding to meet OEM traceability requirements while maintaining pricing competitiveness against in-house alternatives. Program volume commitments drive automation timing.
- Contract Manufacturers:Multi-customer fabrication services with flexible equipment configurations.
- Job Shops:Small-batch producers with intermittent automation utilization and limited programming staff.
- Aftermarket Providers:Repair and remanufacturing services with specialized reclamation welding processes.
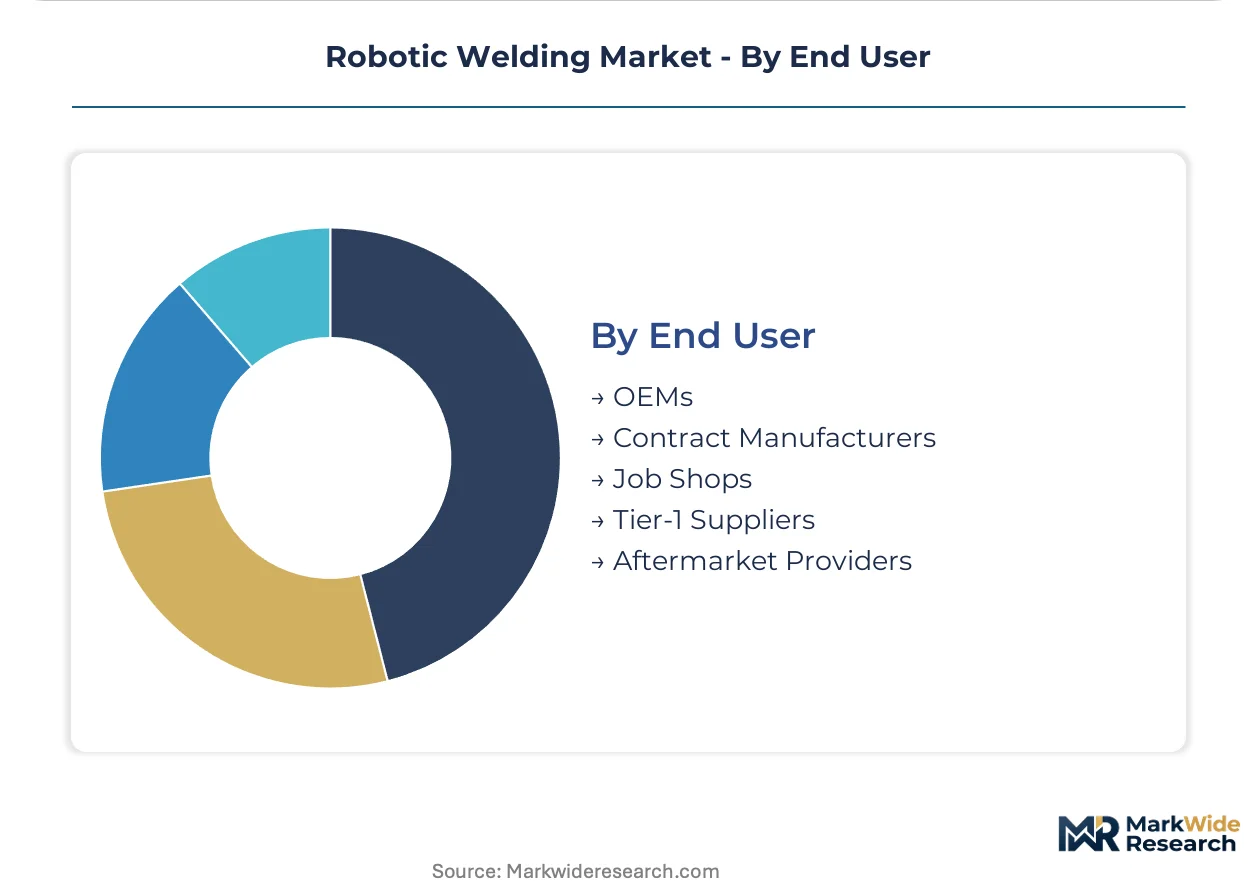
OEMs sit at the top of the volume ranking, with Tier-1 Suppliers climbing the fastest as outsourcing pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welding technicians and robotics engineers concentrate in Germany, Japan, and the United States, anchoring the technical workforce that enables advanced automation deployment. These talent pools sustain innovation clusters where equipment manufacturers co-locate with demanding end-users.
China
Provincial governments in Jiangsu and Guangdong subsidize robotic welding retrofits under national dual carbon goals to reduce industrial energy intensity. MIIT mandates drive automation adoption across state-owned automotive enterprises. The Yangtze River Delta cluster around Shanghai hosts the densest concentration of battery tray laser welding installations for domestic EV manufacturers.
Germany
Automotive OEMs in Stuttgart and Wolfsburg standardize on specific controller platforms to minimize spare parts proliferation across multi-plant networks. The EU Green Deal carbon intensity mandates favor automated welding's energy efficiency over manual operations with higher rework rates. Bavaria's industrial corridor anchors precision system integration capabilities serving aerospace and medical device fabricators.
Japan
Controller and servo motor suppliers dominate precision motion control hardware, creating concentrated supply chain leverage for system integrators worldwide. METI industrial policy supports next-generation welding robot development through collaborative research programs. The Chubu region around Nagoya maintains deep manufacturing scale in arc welding robots serving Asian automotive supply chains.
United States
Tier-1 seating and exhaust system manufacturers in Michigan and Ontario deploy robotic welding to meet OEM traceability requirements while maintaining pricing competitiveness. OSHA exposure limits for welding fumes shape facility compliance costs and automation investment decisions. The Southeast automotive corridor spanning Tennessee and South Carolina attracts new welding automation capacity as transplant OEMs expand EV production.
South Korea
Battery tray manufacturers specify fiber laser cells for EV enclosure joining where porosity control determines IP67 sealing validation. MFDS oversight of medical device fabrication extends to welding process validation requirements. The Busan-Ulsan industrial complex hosts shipyard automation programs automating panel welding for container vessel construction.
Robotic Welding Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure where scale advantages concentrate in integrated motion control ecosystems. Japanese and German equipment manufacturers anchor the premium tier through captive controller and servo motor production. Mid-tier competitors differentiate through regional service density and application-specific integration expertise. Consolidation pressure intensifies as automotive OEMs unbundle after-sales service contracts and standardize on fewer supplier platforms.
Among the established industrial robot manufacturers, FANUC and YASKAWA Electric Corporation represent the integrated ecosystem archetype with captive controller production, while Lincoln Electric exemplifies the consumables-coupled systems approach. These three anchors occupy positions that reflect distinct strategic bets on how welding automation value pools will evolve.
| Leading Market Players |
|---|
| ABB |
| Panasonic Corporation |
| FANUC |
| Lincoln Electric |
| DAIHEN Corporation |
| YASKAWA Electric Corporation |
| Kawasaki Heavy Industries |
| Hyundai Robotics |
| KUKA AG |
| Others |
Cost & Logistics Intelligence
Captive controller and servo motor production by Japanese and German equipment manufacturers anchors both supply security and pricing power across the robotic welding value chain. This backward integration into precision motion control hardware insulates tier-1 suppliers from commodity volatility while enabling premium positioning against mid-tier competitors dependent on outsourced components.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for entry-level articulated systems. Three-tier pricing structure across premium, standard, and economy levels reflects controller ecosystem lock-in, ISO 10218 certification grade, and bundled after-sales service intensity. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are scaling six-axis production for local automotive retrofits. Contract manufacturers in Mexico's Bajío corridor exhibit the highest price sensitivity, while German automotive OEMs prioritize controller platform standardization over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Detroit orchestrate hub-and-spoke patterns for spare parts fulfillment. Controller and servo motor production concentrates in Japan and Germany, while China dominates aluminum battery tray fabrication and laser welding cell assembly. Rare earth magnet feedstock for motor windings draws from Chinese processing facilities, creating single-source vulnerability for European system integrators. Distribution runs through authorized integrator networks rather than direct OEM-to-end-user channels, preserving technical commissioning margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotic welding market functions as a regulatory compounder where EU Green Deal carbon intensity mandates and REACH authorization timelines mechanically expand compliant automation demand. These binding frameworks transform energy efficiency and consumables reformulation from competitive differentiators into baseline market access requirements.
For Market Incumbents: Anchor controller platform ecosystems through multi-year spare parts availability commitments that extend replacement cycle capture. Deepen backward integration into servo motor production to defend margin position against Chinese entrants scaling in the Pearl River Delta. Prioritize ISO 10218-2 collaborative cell certification investment to preempt safety validation bottlenecks in European automotive body shop retrofits.
For New Entrants and Emerging Players: REACH authorization requirements in Europe open a window for ceramic-based anti-spatter formulation specialists to displace legacy hexavalent chromium suppliers. Target India's PLI scheme-subsidized automotive component manufacturing clusters where domestic integration capability remains scarce. Pursue pay-per-part financing models for mid-tier contract manufacturers in Vietnam to circumvent capital barrier constraints.
For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with captive welding procedure qualification expertise because automotive OEM unbundling of service contracts fragments incumbent maintenance revenue pools. Five-to-ten year viability hinges on exposure to EV battery tray laser welding capital expenditure cycles rather than mature spot welding replacement demand. Monitor provincial dual carbon subsidy renewal timelines in Jiangsu and Guangdong as inflection indicators for Chinese domestic demand trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Controller Platform Standardization | Reduces spare parts proliferation across multi-plant automotive networks in Stuttgart and Wolfsburg. |
| Laser Welding Cell Integration | Captures EV battery tray fabrication demand where IP67 sealing validation requires fiber laser precision. |
| Consumables Regulatory Affairs Investment | Secures REACH authorization continuity for ceramic-based anti-spatter agents by 2026 deadlines. |
| Regional Integration Capability Buildout | Positions for India's PLI scheme automotive component manufacturing incentives in Tamil Nadu and Gujarat. |
| Vision-Guided Seam Tracking Convergence | Opens premium pricing in aerospace NADCAP-qualified fabrication where radiographic reject rates must stay below 0.5 percent. |
Research Approach
Bottom-up automotive and aerospace manufacturing modeling reconciled against top-down welding automation equipment production tracking forms the analytical core. Primary interviews with maintenance directors at Tier-1 seating suppliers, plant engineers in Korean shipyards, biomedical welding technicians, and aftermarket service heads at European system integrators combined with secondary validation from SEC 10-K filings, MIIT automation subsidy disclosures, customs trade data, and ISO certification registries. Triangulation across these sources validates installed base estimates and replacement cycle assumptions.
Input-output matrices map controller and servo motor production volumes to downstream robotic welding system assembly across the projection horizon. Segmentation dimensions include robot kinematic configuration, joining technology process type, end-use industry certification regime, and buyer technical competency tier. CAGRs derive from welding robot density ratios relative to automotive production volumes, adjusted for EV architecture transition impacts and provincial subsidy program trajectories. Forecast inputs incorporate battery tray laser welding adoption curves and hexavalent chromium replacement timelines.
Revisions become necessary when EU carbon border adjustment mechanisms expand scope, Chinese dual carbon subsidy programs lapse, or rare earth magnet export restrictions materialize. Forecasts reflect documented assumptions regarding technician availability constraints and controller ecosystem continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Nanorobots in Healthcare Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market