
 AGV Intelligent Management Systems Market | 2026-2036
AGV Intelligent Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
AGV Intelligent Management Systems Market Insights
The EU Green Deal is rebalancing procurement criteria for automated material handling systems across European manufacturing plants. Daifuku leverages its deep integration with automotive assembly lines to anchor premium fleet contracts in Japan and Europe. KION Group competes through vertical control over lift truck and AGV hardware, sustaining margin capture across warehouse automation deployments. Geekplus Technology specializes in vision-based robotics for e-commerce fulfillment, dominating high-throughput sorting environments in Asia.
AGV Intelligent Management Systems coordinate autonomous vehicle fleets through real-time software layers, navigation sensor arrays, and battery optimization algorithms that maintain operational continuity across multi-shift industrial schedules. Fleet Management Software commands the largest installed base by value, while Vision-Based technology represents the fastest-expanding segment as camera-lidar fusion replaces legacy magnetic tape guidance in brownfield retrofits. Warehouse Automation absorbs the majority of new system deployments, though Cold Storage Facilities are emerging as a concentrated margin pool due to environmental sealing requirements and specialized lithium battery thermal management.
FDA facility validation standards shape pharmaceutical distribution center requirements for traceable vehicle movement logs, while OSHA workplace safety rules mandate collision-avoidance certification for mixed human-robot environments. The EU AI Act introduces conformity obligations for autonomous decision-making systems that will filter into AGV software procurement specifications. Stakeholders must monitor how regulatory divergence between OSHA-mandated North American safety zones and CE-marked European interoperability standards affects cross-border fleet standardization strategies.
Market Dynamics
Camera-lidar fusion guidance systems are compressing retrofit timelines for brownfield automotive plants, while EU industrial decarbonization mandates redirect capital toward energy-efficient fleet platforms. This technological-regulatory intersection is restructuring procurement criteria across European and North American manufacturing corridors.
Growth Catalysts
- EU Green Deal industrial mandates:Binding decarbonization targets for manufacturing facilities are redirecting automation budgets toward energy-efficient AGV platforms with regenerative braking and smart charging algorithms.
- E-commerce fulfillment density:Sortation hub operators in Germany and the United States are deploying vision-guided vehicle networks to sustain throughput during multi-shift operations without proportional labor expansion.
- Pharmaceutical cold chain expansion:FDA validation requirements for traceable vehicle movement logs are accelerating specialized fleet deployments in temperature-controlled distribution centers.
Market Restraints
- Lithium battery thermal management costs:Specialized sealing and heating-cooling subsystems for cold storage AGVs add 15-25% to unit capex compared to ambient-temperature equivalents.
- Navigation sensor supply concentration:High-precision lidar module production clusters in East Asian manufacturing zones create geographic vulnerability for European and North American system integrators.
- EU AI Act conformity timelines:Autonomous decision-making validation protocols for fleet management software are extending procurement cycles by 6-12 months for first-mover deployments.
Strategic Opportunities
- India automotive corridor:PLI scheme incentives for advanced manufacturing are creating first-mover advantage for vision-guided AGV suppliers establishing local assembly partnerships.
- OSHA mixed-environment certification:Collision-avoidance system validation for human-robot workspaces opens premium pricing tiers in North American warehousing contracts.
- Battery-swapping infrastructure convergence:Integration of automated exchange stations with fleet management software enables 24/7 operational continuity without charging downtime.
Industry Challenges
- Multi-protocol integration complexity:Brownfield plants require simultaneous support for magnetic tape legacy guidance and camera-lidar fusion systems during phased retrofits.
- Functional safety engineer scarcity:ISO 13849 and IEC 61508 certification expertise for autonomous mobile robot deployments remains concentrated among a limited pool of specialized consultants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AGV Intelligent Management Systems Market |
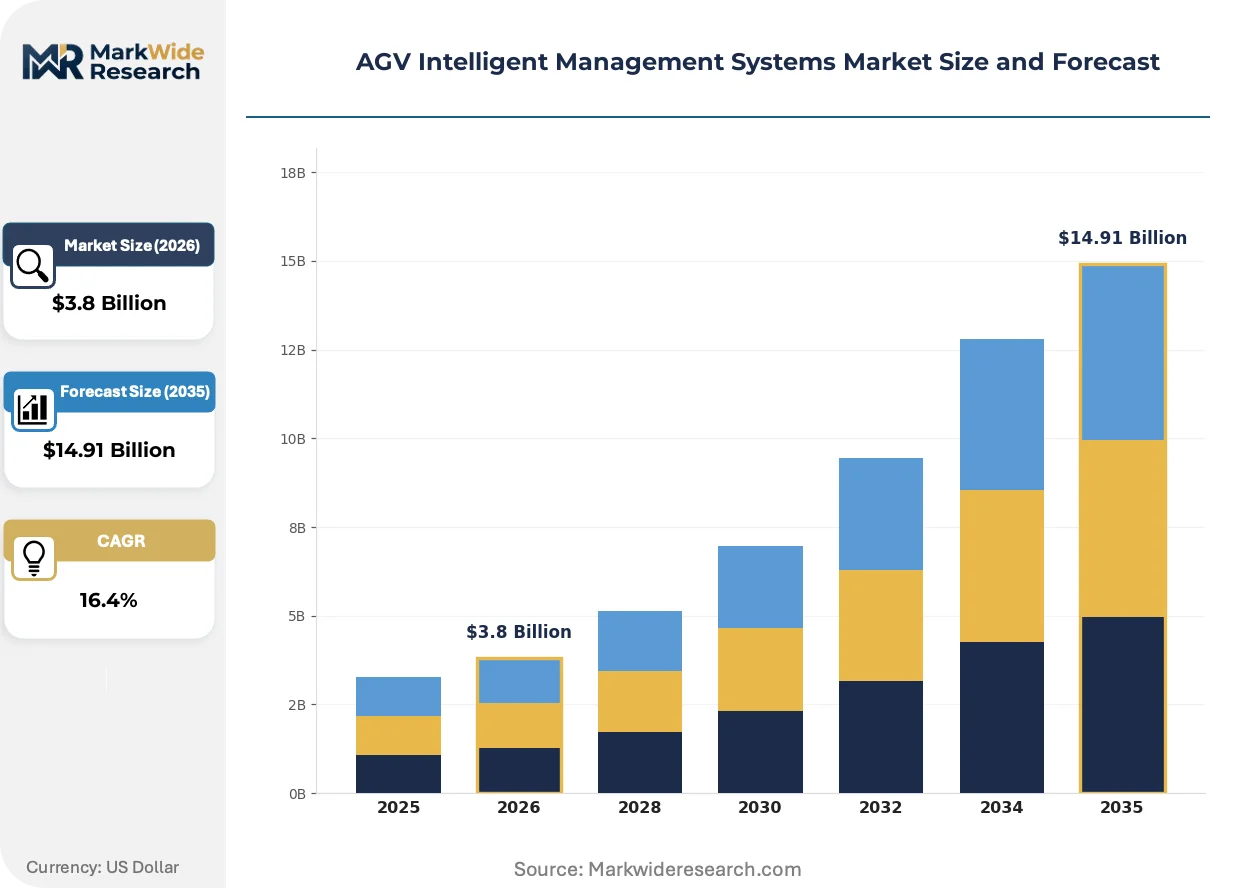
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vehicle Guidance System, Fleet Management Software, Navigation Sensors, Communication Modules, Battery Management System Technology: Laser Guidance, Magnetic Tape, Vision-Based, Inertial Navigation, RFID Tracking Application: Warehouse Automation, Material Handling, Order Picking, Assembly Line Transport, Packaging Support End User: Manufacturing Plants, Distribution Centers, Third-Party Logistics, OEMs, Cold Storage Facilities |
| Companies Covered | Dematic, Daifuku, KION Group, Jungheinrich, Toyota Industries Corporation, Seegrid, Swisslog, KUKA, Geekplus Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AGV Intelligent Management Systems Market Trends and Innovations
Software-defined fleet coordination is displacing hardware-centric automation architectures. Three convergent developments are compressing deployment timelines and expanding addressable application spaces for autonomous vehicle management.
Camera-lidar fusion navigation is unifying environmental perception and path planning into single-sensor-stack architectures. Tier-one automotive suppliers in Germany and Japan are retrofitting assembly plants with these systems to eliminate magnetic tape infrastructure. This consolidation is compressing brownfield deployment timelines from 18 months to under 6 months for comparable throughput capacity.
The EU AI Act's conformity assessment framework for autonomous decision-making systems is mandating explainable fleet routing algorithms. Pharmaceutical distribution centers in France and Germany must now maintain auditable vehicle movement logs for regulatory inspection. Cold storage operators are responding by specifying middleware platforms with built-in traceability documentation.
Outcome-based fleet performance contracts are displacing capital purchase models in third-party logistics. Warehouse operators in the Netherlands and Belgium now specify cost-per-pallet-moved pricing with uptime guarantees. This transfer of operational risk to system integrators is most visible in temperature-controlled facilities where thermal management failures carry penalty clauses.
AGV Intelligent Management Systems Market Segmentation
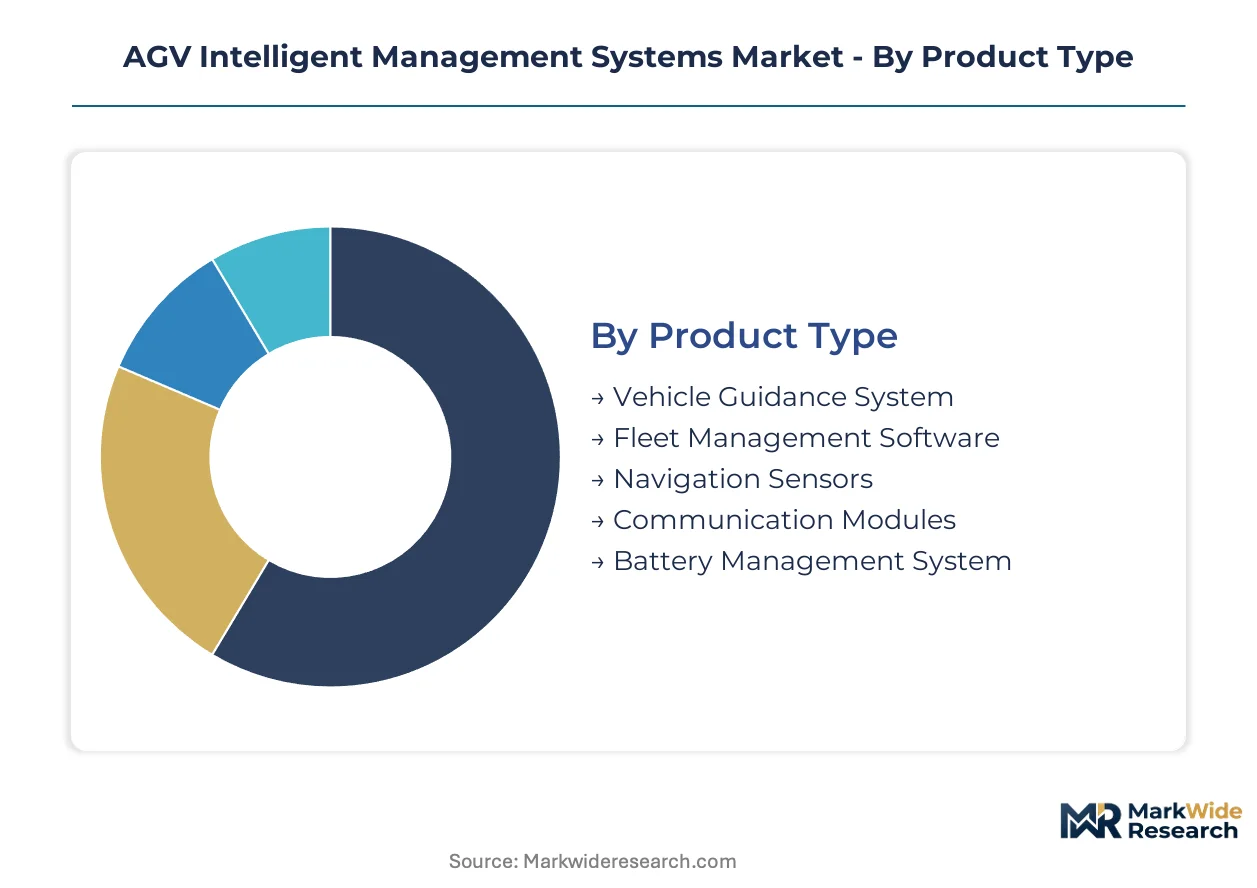
Segmentation in AGV Intelligent Management Systems reveals how software layers, sensor hardware, and application environments create distinct procurement criteria. Buyers prioritize different performance attributes based on facility age, throughput requirements, and regulatory exposure. Understanding these segment boundaries clarifies where margin concentrates and where technology transitions disrupt incumbent positions.
Product Type:
Supply concentration in navigation sensor modules and battery management subsystems shapes vendor margin structures across the five product categories.
- Fleet Management Software:Real-time coordination platforms integrate vehicle dispatch, traffic management, and battery optimization algorithms into unified control architectures. German automotive OEMs and Dutch third-party logistics operators specify these systems for multi-shift continuity, with EU AI Act traceability requirements now embedded in procurement specifications. Today's leader: Fleet Management Software. Tomorrow's challenger: Battery Management System.
- Battery Management System:Thermal regulation electronics and cell balancing circuits maintain lithium pack performance across temperature extremes. Cold storage operators in France and Belgium demand specialized heating-cooling subsystems that add substantial unit cost but prevent downtime penalties in outcome-based contracts. Expanding most quickly as electrification mandates tighten across European manufacturing.
- Vehicle Guidance System:Path planning controllers process sensor inputs to execute movement commands with millimeter positioning accuracy.
- Navigation Sensors:Lidar-camera fusion arrays and magnetic field detectors provide environmental perception for autonomous positioning.
- Communication Modules:Industrial wireless transceivers enable vehicle-to-vehicle and vehicle-to-infrastructure data exchange in dense fleet deployments.
Software value capture is climbing fastest as hardware commoditizes.
Technology:
Cost tier differentiation separates legacy retrofit solutions from premium greenfield installations across guidance modalities.
- Vision-Based:Camera-lidar fusion stacks unify environmental mapping and obstacle detection into single-sensor architectures. Tier-one automotive suppliers in Germany and Japan deploy these systems to eliminate magnetic tape infrastructure, compressing brownfield deployment timelines dramatically. Steepest expansion trajectory as brownfield retrofit demand accelerates.
- Laser Guidance:Rotating lidar emitters construct real-time 3D facility maps for path planning without floor-mounted references. High-precision manufacturing corridors in Stuttgart and Wolfsburg specify these systems for sub-millimeter assembly line positioning, though module supply concentration in East Asia creates procurement vulnerability. Mature technology with stable pricing.
- Magnetic Tape:Floor-embedded ferromagnetic strips provide low-cost guidance paths for fixed-route applications.
- Inertial Navigation:Accelerometer-gyroscope combinations supplement primary guidance in GPS-denied indoor environments.
- RFID Tracking:Radio-frequency floor tags enable zone-based positioning for simple loop configurations.
Legacy tape systems still move volume. Vision systems are capturing value.
Application:
Volume concentration in warehouse environments contrasts with margin concentration in specialized handling scenarios.
- Warehouse Automation:End-to-end material flow systems coordinate receiving, storage, retrieval, and shipping operations through unified fleet control. E-commerce sortation hubs in Germany and the United States deploy vision-guided networks to sustain throughput without proportional labor expansion. Dominant application by installed base.
- Cold Storage Facilities:Temperature-controlled vehicle fleets require sealed electronics, thermal-regulated batteries, and stainless steel construction for pharmaceutical and food distribution. FDA validation standards for traceable movement logs accelerate specialized deployments in temperature-controlled pharmaceutical distribution centers. Highest margin pool per unit.
- Material Handling:Inter-facility transport of raw materials and work-in-progress inventory between production stages.
- Order Picking:Goods-to-person automation systems bring inventory to stationary operators for fulfillment consolidation.
- Assembly Line Transport:Just-in-time component delivery to automotive and electronics manufacturing workstations.
- Packaging Support:Finished goods movement to consolidation and palletizing stations for outbound shipment.
General warehousing absorbs capital. Cold chain commands premium.
End User:
Customer type determines contract structure, with OEMs favoring capital purchase and logistics providers shifting toward performance-based arrangements.
- Third-Party Logistics:Contract operators specify outcome-based pricing with uptime guarantees, transferring operational risk to system integrators. Warehouse operators in the Netherlands and Belgium now structure cost-per-pallet-moved contracts with penalty clauses for thermal management failures in temperature-controlled facilities. Fastest-growing contract structure.
- Manufacturing Plants:Automotive and electronics producers deploy captive fleets for just-in-time material flow control.
- Distribution Centers:Retail and wholesale consolidation facilities prioritize throughput density in high-velocity operations.
- OEMs:Vehicle and equipment manufacturers integrate AGV fleets into assembly line synchronization systems.
- Cold Storage Facilities:Pharmaceutical and food distribution operators specify environmental sealing and thermal battery management.
Asset-light logistics models are reshaping procurement. Captive manufacturing fleets remain stable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AGV Intelligent Management Systems originated in German automotive assembly halls during the 1980s, where magnetic tape-guided vehicles first synchronized with just-in-time production schedules. This heritage shapes today's geographic concentration of fleet deployment expertise and navigation sensor manufacturing.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are retrofitting brownfield plants with camera-lidar fusion systems to eliminate legacy magnetic infrastructure. The EU AI Act's conformity assessment framework extends procurement cycles for autonomous fleet software validation. Bavaria's manufacturing corridor hosts the densest concentration of vision-guided vehicle networks in European automotive.
United States
E-commerce fulfillment operators deploy vision-guided sortation networks to sustain multi-shift throughput without proportional labor expansion. OSHA workplace safety rules mandate collision-avoidance certification for mixed human-robot warehousing environments. The Great Lakes automotive belt and Southeast distribution hubs absorb the majority of North American fleet capital.
China
Domestic battery management subsystem production scales rapidly to serve cold storage electrification mandates under dual carbon goals. MIIT industrial automation standards accelerate domestic certification timelines for autonomous vehicle fleets. The Yangtze River Delta concentration of lithium cell manufacturing creates integrated supply advantages for thermal-regulated AGV platforms.
Japan
Precision assembly line synchronization demands sub-millimeter positioning accuracy for automotive component delivery. METI technology roadmaps prioritize energy-efficient fleet platforms with regenerative braking algorithms. Toyota City and Nagoya manufacturing clusters anchor captive fleet deployment for tier-one supplier networks.
India
PLI scheme incentives for advanced manufacturing attract first-mover vision-guided AGV suppliers establishing local assembly partnerships. BIS certification requirements for industrial automation equipment filter procurement toward domestically integrated system providers. The Tamil Nadu and Maharashtra automotive corridors concentrate brownfield retrofit demand from multinational OEM operations.
AGV Intelligent Management Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the AGV Intelligent Management Systems value chain. The market structure consolidates around three tiers: integrated hardware-software providers, specialized navigation sensor suppliers, and pure-play fleet management platforms. Dominant competitive moves include backward integration into lithium battery thermal management subsystems and strategic partnerships with third-party logistics operators seeking outcome-based fleet performance contracts.
Within the integrated automation tier, Daifuku and KION Group exemplify divergent geographic anchoring strategies. Daifuku occupies a position tied to Japanese and European automotive assembly line integration, while KION Group represents vertical control over lift truck and AGV hardware originating from German engineering heritage. Geekplus Technology sits within the vision-based robotics specialization, exemplifying Asia-Pacific concentration in high-throughput e-commerce fulfillment environments.
| Leading Market Players |
|---|
| Dematic |
| Daifuku |
| KION Group |
| Jungheinrich |
| Toyota Industries Corporation |
| Seegrid |
| Swisslog |
| KUKA |
| Geekplus Technology |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price indices cascade through AGV manufacturing tiers, amplifying cost differentials between premium vision-guided systems and legacy magnetic-tape platforms as battery thermal management claims larger shares of unit economics.
Pricing Analysis
Outcome-based fleet performance contracts with uptime guarantees displace capital purchase models across third-party logistics. Price differentiation hinges on EU AI Act certification tier and cold storage environmental sealing grade. Cost compression in mid-tier hardware intensifies as Chinese battery management subsystems penetrate European integrator supply chains. E-commerce fulfillment operators exhibit highest price sensitivity, while pharmaceutical cold chain buyers prioritize FDA-validated traceability over unit cost.
Supply Chain Analysis
High-precision lidar module production rests on Japanese and German optical component specialists, with final assembly concentrating in Chinese Yangtze River Delta manufacturing zones. Navigation sensor arrays draw from Taiwanese semiconductor foundries and South Korean image sensor fabricators. Single-source vulnerability in solid-state lidar emitters creates procurement exposure for European system integrators. Distribution runs through captive OEM supply agreements in automotive corridors and integrator-led performance contracts in warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AGV Intelligent Management Systems market reads as a late-cycle quality story, with procurement criteria hardening around EU AI Act traceability and OSHA collision-avoidance certification as non-negotiable specifications.
For Market Incumbents: Deploy backward integration into lithium battery thermal management subsystems to defend margin capture against Chinese cost leaders. Anchor premium positioning through ISO 13849 functional safety certification depth, creating switching costs for automotive OEMs facing EU conformity assessment timelines. Consolidate channel control via exclusive performance contracts with Dutch and Belgian cold storage operators.
For New Entrants and Emerging Players: The PLI scheme in India opens a window for vision-guided AGV suppliers establishing local assembly partnerships in Tamil Nadu and Maharashtra automotive corridors. White-space concentration sits with battery-swapping infrastructure convergence for 24/7 operational continuity. Target outcome-based fleet performance contracts as the most penetrable procurement structure shift.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized navigation sensor suppliers possessing camera-lidar fusion IP and FDA validation pathway expertise. Long-term viability favors assets with embedded software-defined fleet coordination capabilities. Watch EU AI Act conformity assessment timeline extensions as the inflection signal for first-mover procurement cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Thermal Management | Captures margin pools in cold storage deployments under FDA validation requirements. |
| EU AI Act Certification Investment | Accelerates procurement cycles for pharmaceutical distribution center fleet software. |
| Vision-Guided System Platform Launch | Compresses brownfield retrofit timelines from 18 months to under 6 months. |
| Strategic Partnership with 3PL Operators | Locks in outcome-based cost-per-pallet-moved contracts with penalty clause structures. |
| Geographic Expansion into India PLI Corridors | Secures first-mover positioning in Tamil Nadu and Maharashtra automotive retrofit demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with fleet management software vendors, automotive plant engineers, cold storage facility operators, and third-party logistics procurement leads with secondary validation through SEC filings, EU regulatory submissions, customs trade data, and industrial automation certification databases. Bottom-up unit deployment estimates triangulated against top-down capital expenditure tracking across automotive and warehousing end-use segments.
Segment-weighting approaches distributed value capture across fleet management software, battery management systems, vehicle guidance controllers, and navigation sensor hardware tiers, with technology splits between vision-based, laser guidance, and legacy magnetic tape modalities. Application segmentation modeled warehouse automation, cold storage facilities, and pharmaceutical distribution center demand separately. CAGRs derived from installed base growth rates, replacement cycle compression, and average system value evolution across the projection horizon.
Revisions become necessary when EU AI Act conformity timelines extend beyond modeled procurement cycle assumptions, lithium supply disruptions alter battery cost trajectories, or OSHA rulemaking shifts collision-avoidance certification requirements. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Top Robotics Market