
 Europe Marketing Automation Software Market | 2026-2036
Europe Marketing Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Marketing Automation Software Market Analysis
First-party data infrastructure is shifting from third-party cookie dependency toward server-side tracking and consent-managed identity graphs. Salesforce leverages its Data Cloud architecture to anchor enterprise clients in unified customer profiles across European privacy jurisdictions. HubSpot competes through inbound-native automation that sustains mid-market penetration without heavy IT overhead. Adobe differentiates via real-time CDP integration that controls cross-channel journey orchestration for B2C conglomerates.
Europe marketing automation software encompasses campaign orchestration platforms that execute, measure, and optimize multi-touch customer engagement through rule-based and machine-driven triggers, typically integrating with CRM systems, data warehouses, and ad platforms via REST APIs and pre-built connectors. The primary commercial purpose is to replace manual segmentation and batch broadcasting with behavior-responsive communication that reduces customer acquisition cost and extends lifetime value. Cloud-based deployment leads segment economics due to lower upfront infrastructure burden and faster GDPR-compliant data residency configuration through EU-region hosting. Email marketing functionality remains the most mature feature category with compressed margins, while lead scoring powered by predictive models represents the fastest-expanding margin pool as sales and marketing alignment tightens.
GDPR enforcement by national data protection authorities across Germany, France, and Spain shapes product roadmaps through mandatory consent logging, data portability, and erasure automation. The EU AI Act introduces risk-classification obligations for automated decision-making in customer targeting, compelling vendors to document logic trails and human oversight mechanisms. REACH and ECHA frameworks matter indirectly through supply-chain due diligence requirements for on-premises hardware deployments. Stakeholders must monitor how regulatory fragmentation between member-state interpretations of automated profiling rules affects cross-border campaign execution and vendor liability structures.
Market Dynamics
The EU AI Act is forcing algorithmic transparency requirements into campaign orchestration platforms, compelling vendors to re-engineer logic documentation and human oversight mechanisms into real-time personalization engines.
Growth Catalysts
- First-party data infrastructure:Retail and e-commerce brands across Germany, France, and the UK are deploying server-side tracking and consent-managed identity graphs to replace third-party cookie dependency.
- GDPR enforcement patterns:National data protection authorities in Germany, France, and Spain mandate consent logging and erasure automation, creating compliance-driven upgrade cycles.
- Predictive lead scoring:Sales and marketing alignment investments are accelerating adoption of machine-driven behavioral models that compress qualification timelines.
Market Restraints
- Algorithmic audit costs:The EU AI Act's risk-classification obligations impose documentation and human-in-the-loop infrastructure expenses on automated decision-making systems.
- Cloud vendor concentration:Mid-market enterprises face limited EU-region hosting alternatives for GDPR-compliant data residency configuration.
- Email margin compression:Mature email marketing functionality faces pricing pressure as differentiation shifts toward predictive capabilities.
Strategic Opportunities
- Mid-market cloud migration:French and Spanish enterprises currently on legacy on-premises systems represent underpenetrated demand for integrated CRM-to-email workflows.
- Real-time CDP convergence:B2C conglomerates are consolidating journey orchestration and customer data platform investments into unified technology stacks.
- CSRD reporting integration:Sustainability disclosure mandates create demand for marketing automation that tracks and reports campaign carbon footprint metrics.
Industry Challenges
- Cross-border execution complexity:Fragmented member-state interpretations of automated profiling rules complicate multi-territory campaign deployment.
- Legacy system integration:On-premises CRM and data warehouse architectures in German industrial sectors create API connectivity friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Marketing Automation Software Market |
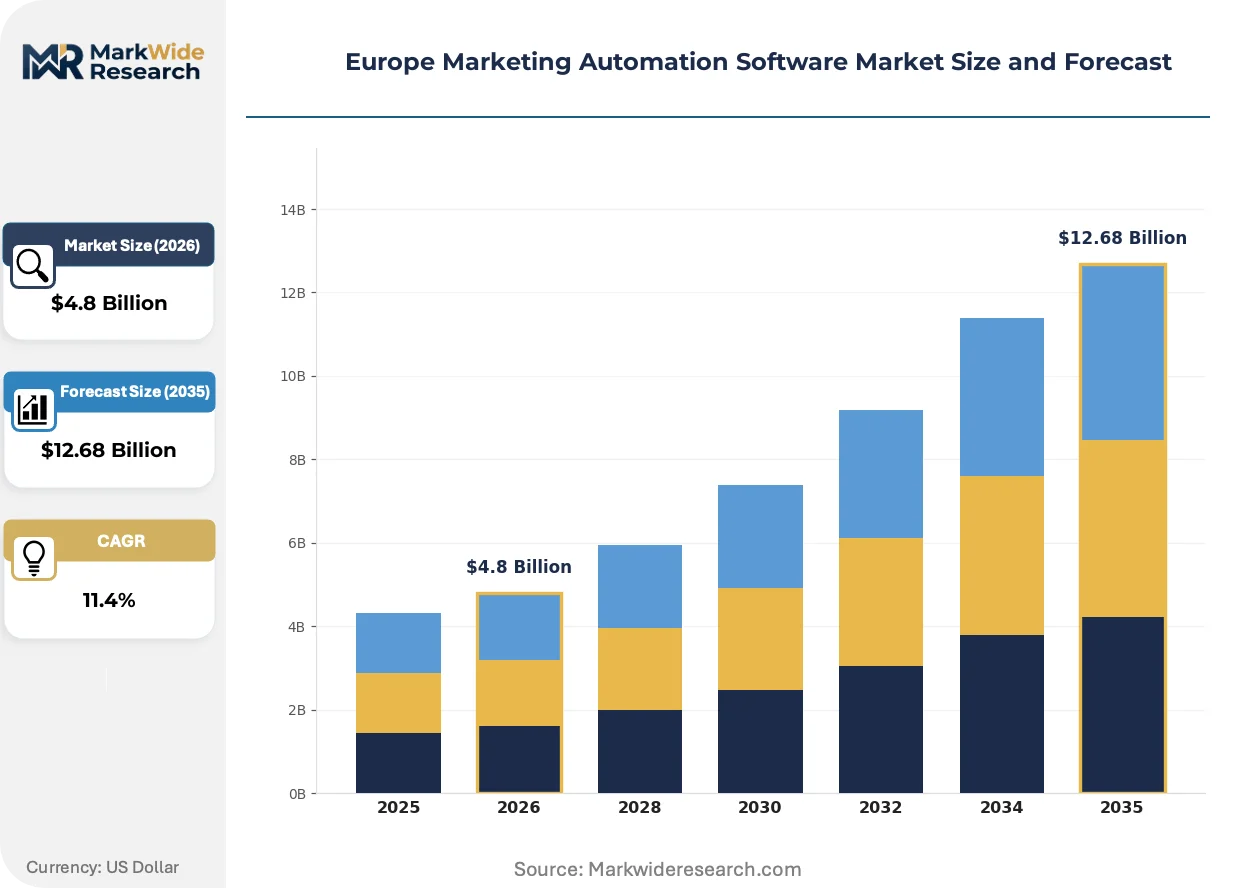
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: SMEs, Large Enterprises, Marketing Agencies, Corporations Feature: Email Marketing, Social Media Management, Lead Scoring, Analytics Solution: Campaign Management, CRM Integration, Customer Journey Mapping, Workflow Automation |
| Companies Covered | Salesforce, Adobe Systems, Oracle Corporation, HubSpot, Brevo, IBM Corporation, Microsoft Corporation, Zoho Corporation, ActiveCampaign, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Marketing Automation Software Market Emerging Trajectories
AI-powered personalization engines are expanding from batch segmentation into real-time behavioral triggers, while regulatory pressure on algorithmic transparency and first-party data architecture reconfigures competitive requirements.
Generative content engines are expanding into dynamic email and landing page creation for mid-market retailers seeking reduced creative production cycles. German fashion and consumer electronics brands are piloting these tools for seasonal campaign velocity. The technology is expanding into traditionally design-heavy workflows by compressing asset turnaround from weeks to hours.
The EU AI Act imposes risk-tier documentation obligations on automated customer targeting systems used by B2C conglomerates. Vendors must now maintain logic trails and human oversight protocols for high-risk profiling applications. French and German national regulators are interpreting these requirements most stringently, driving roadmap prioritization toward explainable model architectures.
Subscription-based pricing models are displacing perpetual license structures among mid-market buyers seeking predictable operational expenditure profiles. Cloud-native vendors capture this shift through usage-scaled tiers that align cost with contact database growth. The transition is most visible in UK and Netherlands software procurement, where finance departments favor recurring cost structures over capital allocation cycles.
Europe Marketing Automation Software Market Segmentation
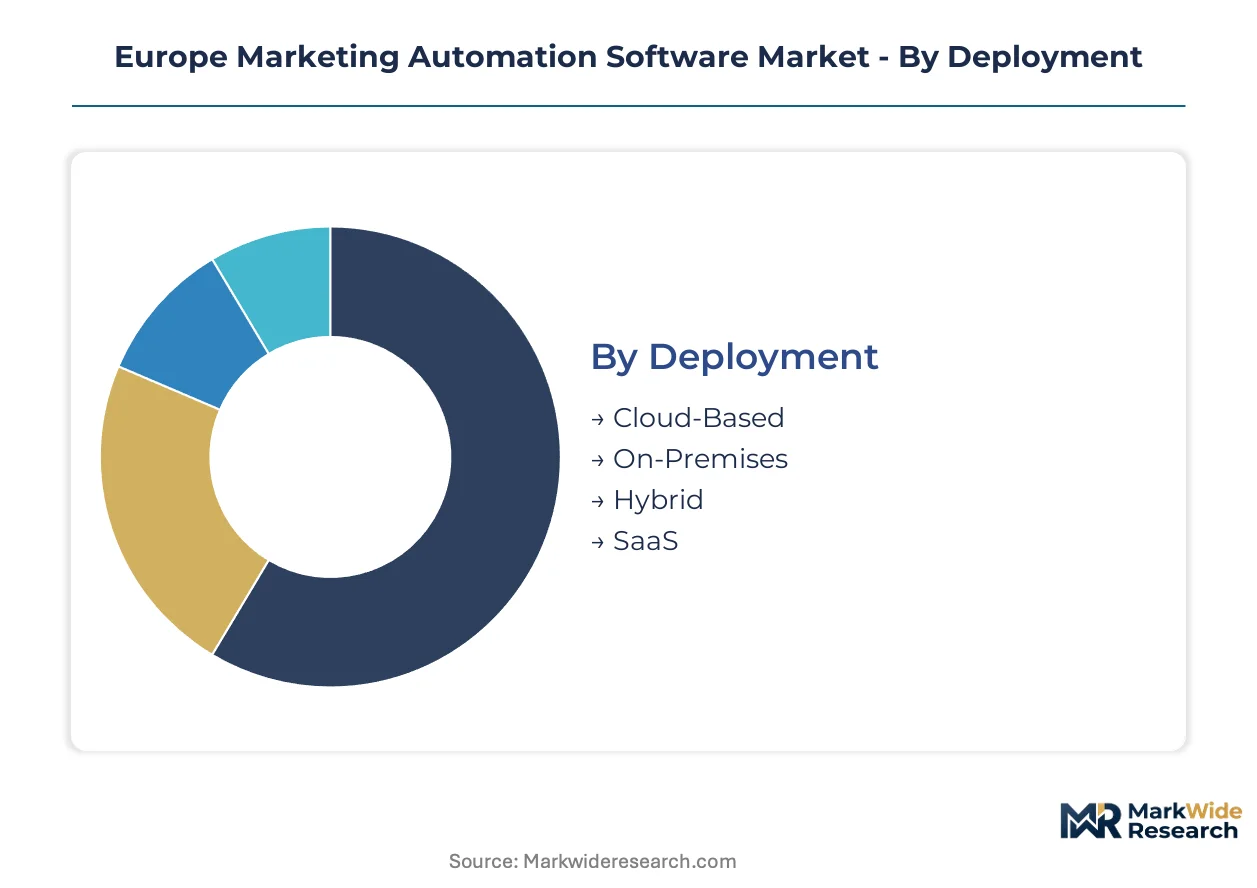
Marketing automation software segments along deployment architecture, organizational scale, functional capability, and solution scope. Each axis reflects distinct procurement priorities shaped by GDPR compliance burdens, AI Act obligations, and cloud migration timelines across European enterprises.
Deployment:
Cloud infrastructure economics and data residency requirements define how European organizations procure automation platforms.
- Cloud-Based:Multi-tenant architectures hosted in EU regions satisfy GDPR data localization mandates without capital expenditure. German and French mid-market retailers favor this model for rapid CRM-to-email integration with minimal IT overhead.
- On-Premises:Single-tenant installations within corporate data centers persist in German industrial sectors with legacy ERP dependencies and stringent internal security protocols. High upfront infrastructure costs and maintenance burdens constrain expansion beyond regulated industries.
- Hybrid:Split architectures place sensitive customer data on-premises while leveraging cloud compute for campaign execution. Spanish financial services firms adopt this pattern to reconcile compliance requirements with scalability needs.
- SaaS:Subscription-native delivery with usage-scaled pricing aligns procurement with operational expenditure preferences. UK and Netherlands finance departments drive adoption through predictable recurring cost structures versus capital allocation cycles.
Cloud-Based leads on scale; SaaS leads on momentum.
End User:
Organizational scale determines feature requirements, integration complexity, and vendor selection criteria across European markets.
- SMEs:Resource-constrained organizations prioritize low-code workflow builders and pre-built CRM connectors. French and Spanish enterprises migrating from legacy systems represent concentrated demand for integrated email-to-CRM automation without dedicated IT staff.
- Large Enterprises:Complex multi-brand operations require real-time CDP integration and cross-jurisdictional consent management. B2C conglomerates in Germany and the UK consolidate journey orchestration investments into unified technology stacks.
- Marketing Agencies:Service providers managing client portfolios demand multi-account architectures with granular permission hierarchies and white-label reporting capabilities.
- Corporations:Diversified holding structures need federated deployment models accommodating subsidiary-level autonomy with group-level analytics consolidation.
Large Enterprises dominate current revenue concentration; SMEs climb the fastest as cloud-native vendors penetrate underdigitized segments.
Feature:
Functional modules compete for platform investment based on margin structure and competitive differentiation potential.
- Email Marketing:Mature broadcast and triggered messaging capabilities face compressed pricing pressure as baseline expectations. German retail brands still deploy this functionality at scale despite margin erosion shifting vendor focus toward predictive layers.
- Social Media Management:Cross-platform publishing and engagement tools integrate with paid media workflows. UK consumer brands pilot these capabilities for seasonal campaign velocity alongside influencer coordination.
- Lead Scoring:Machine-driven behavioral models compress sales qualification timelines through predictive engagement signals. Tightening sales-marketing alignment investments accelerate adoption across B2B technology vendors in France and Germany.
- Analytics:Attribution and cohort analysis modules face integration complexity with existing data warehouse investments in enterprise accounts.
Email Marketing retains installed base dominance; Lead Scoring gains share fastest as AI Act documentation requirements reshape vendor roadmaps toward explainable model architectures.
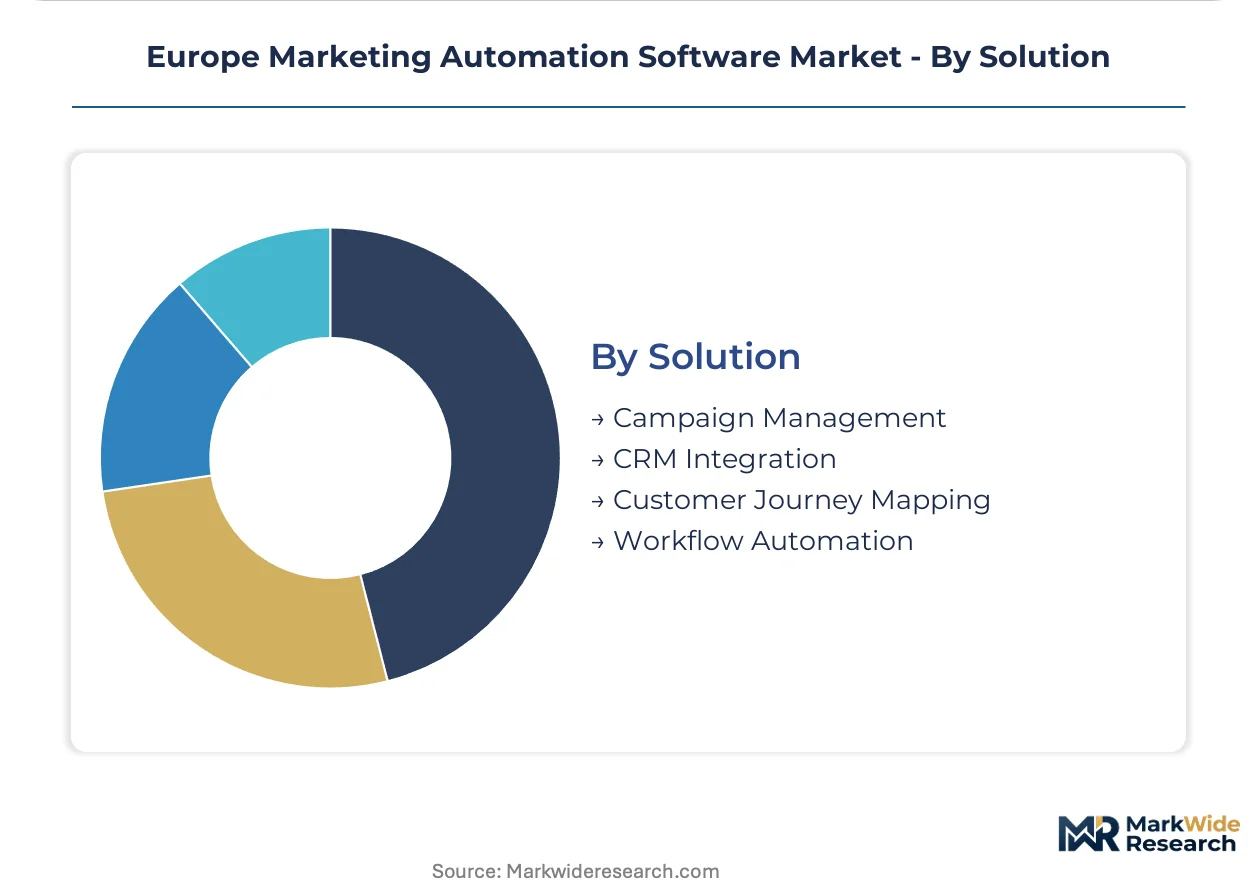
Solution:
Solution packages bundle functional modules into coherent workflow architectures addressing specific operational pain points.
- Campaign Management:End-to-end orchestration from audience segmentation through performance measurement. German fashion brands deploy these tools for seasonal velocity with generative content engines compressing asset production cycles.
- CRM Integration:Bidirectional data synchronization between automation platforms and customer relationship management systems. Mid-market enterprises across the UK prioritize this capability for unified customer profiles without heavy integration overhead.
- Customer Journey Mapping:Visual workflow designers connecting touchpoints across channels into coherent experience sequences. B2C conglomerates consolidate these investments with real-time CDP convergence strategies.
- Workflow Automation:Rule-based and AI-driven trigger systems executing multi-step processes without manual intervention. EU AI Act risk-classification obligations impose documentation requirements on high-risk profiling applications using this technology.
Campaign Management leads on current deployment scale; Customer Journey Mapping expands most quickly as real-time personalization engines displace batch segmentation approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters in North Rhine-Westphalia and Bavaria anchor European demand for marketing automation platforms, with enterprise procurement concentrated among automotive and manufacturing conglomerates seeking GDPR-compliant customer data infrastructure.
Germany
Automotive OEMs and industrial machinery manufacturers in Stuttgart and Munich drive enterprise-scale adoption of real-time CDP-integrated automation. The Federal Data Protection Authority enforces stringent consent logging requirements under GDPR. Berlin-based SaaS vendors capture mid-market migration from legacy on-premises systems.
United Kingdom
London's financial services and fintech clusters demand workflow automation with predictive lead scoring capabilities. The Information Commissioner's Office mandates erasure automation and data portability mechanisms. Manchester and Birmingham retail brands deploy cloud-native platforms for CRM-to-email integration.
France
Luxury goods houses and B2C conglomerates in Paris prioritize customer journey mapping with generative content engines. CNIL interprets EU AI Act risk-classification obligations most stringently for automated profiling systems. Lyon and Marseille mid-market enterprises represent underpenetrated demand for integrated campaign orchestration.
Netherlands
Amsterdam's e-commerce and logistics technology sectors favor subscription-scaled SaaS pricing for operational expenditure alignment. The Dutch Data Protection Authority enforces cross-border data transfer documentation. Rotterdam retail brands pilot server-side tracking infrastructure to replace third-party cookie dependency.
Spain
Barcelona and Madrid financial services firms adopt hybrid deployment models balancing on-premises data residency with cloud campaign execution. The Spanish Data Protection Agency mandates algorithmic transparency documentation under EU AI Act transposition. Mid-market retailers across Catalonia migrate from legacy systems to cloud-based email automation.
Europe Marketing Automation Software Market Vendor Landscape
Platform consolidation dominates the current landscape as enterprise vendors acquire specialized workflow and analytics capabilities to fill portfolio gaps. The vendor base organizes around three strategic archetypes: cloud-native challengers serving mid-market SMEs, legacy enterprise suites with data cloud architectures, and vertical specialists in B2C journey orchestration. M&A activity and API ecosystem expansion represent the primary competitive vectors as vendors race to embed AI-powered personalization before EU AI Act compliance deadlines.
Among US-based enterprise software conglomerates, Salesforce and Adobe Systems occupy positions anchoring the premium tier through unified customer profile architectures, while HubSpot exemplifies the inbound-native challenger archetype penetrating European mid-markets without heavy IT overhead requirements.
| Leading Market Players |
|---|
| Salesforce |
| Adobe Systems |
| Oracle Corporation |
| HubSpot |
| Brevo |
| IBM Corporation |
| Microsoft Corporation |
| Zoho Corporation |
| ActiveCampaign |
| Others |
Supply Flow & Price Mechanics
Premium-mid-economy pricing differentiation across European marketing automation vendors reflects divergent infrastructure commitments, with enterprise suites anchoring high-cost data cloud architectures while cloud-native challengers compress margins through multi-tenant EU hosting. This bifurcation shapes supplier selection, as German automotive conglomerates absorb premium pricing for on-premises compliance configurations while French mid-market retailers prioritize operational expenditure predictability.
Pricing Analysis
Input-cost pass-through from GDPR-compliant data residency infrastructure and EU AI Act documentation tooling intensifies pricing pressure at the premium tier. Subscription-scaled SaaS models dominate procurement, with tiered pricing separating enterprise CDP-integrated suites from mid-market email-centric offerings. Price differentiation centers on consent-management complexity and real-time personalization engine sophistication. Mid-market enterprises exhibit highest price sensitivity, while B2C conglomerates prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Cloud compute capacity rests on hyperscaler infrastructure concentrated in Ireland, Germany, and the Netherlands, with EU-region data center expansion determining vendor delivery timelines. Software development labor draws from engineering hubs in Berlin, London, and Paris, while specialized AI talent concentrates in Zurich and Amsterdam. Single-source vulnerability persists for GPU-accelerated model training infrastructure. Distribution runs through direct enterprise sales teams and channel partners serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European marketing automation has entered a late-cycle quality phase where vendor viability hinges on explainable AI architectures and first-party data infrastructure depth, as retail and e-commerce procurement shifts toward premium compliance-ready specifications.
For Market Incumbents: Cement market position through backward integration into consent-management infrastructure and captive development of EU AI Act documentation tooling. Defend against cloud-native challengers by embedding real-time CDP capabilities into existing enterprise installations. Prioritize certification investment for high-risk automated profiling applications under French and German regulator interpretations. For New Entrants and Emerging Players: Begin with Spanish and French mid-market enterprises migrating from legacy on-premises systems, where integration complexity has suppressed incumbent penetration. Target marketing agencies managing multi-account client portfolios with white-label workflow automation. Pursue a channel-led go-to-market anchored by system integrators serving GDPR compliance upgrade cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing pre-built connectors to European retail ERP ecosystems and proven algorithmic transparency documentation. Long-term viability favors vendors with sustainable recurring revenue bases and defensible data residency configurations. Monitor CNIL and German Federal Data Protection Authority enforcement patterns as inflection indicators for compliance-driven upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CRM-to-email workflows for GDPR-compliant customer profiles across German jurisdictions. |
| Acquisition of Specialist Firm | Fills explainable AI capability gaps before EU AI Act documentation deadlines tighten. |
| Geographic Expansion | Establishes EU-region hosting presence to satisfy French and Spanish data localization mandates. |
| Strategic Partnership | Accelerates server-side tracking deployment through consent-managed identity graph collaborations. |
| Product Launch | Introduces generative content engines compressing seasonal campaign production for Berlin fashion brands. |
Methodological Framework
Coverage spans Western and Northern Europe, with primary inputs from each major national market. The analysis combines structured interviews with marketing technology executives, IT procurement officers, platform engineers, and channel integration specialists with secondary validation from vendor SEC filings, hyperscaler capex disclosures, and EU regulatory implementation notices. Bottom-up and top-down triangulation reconciles enterprise deployment data with national cloud infrastructure capacity metrics.
Granularity-level modeling addresses deployment architecture, organizational scale, functional capability, and solution scope across the projection horizon. CAGRs derive from segment-level adoption curves weighted by GDPR enforcement intensity and AI Act implementation timelines. Industry-specific inputs include CRM integration complexity scores and real-time personalization engine penetration rates by vertical.
Several conditions sit outside the modeled scope, including potential EU AI Act enforcement divergence beyond current national regulator interpretations and unanticipated hyperscaler data center capacity constraints. Forecasts reflect documented assumptions about mid-market cloud migration velocity and sales-marketing alignment investment continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Automated Liquid Handling System Market
Automation
Digital Process Automation Market
Automation
Global Automated Liquid Handlers Market
Automation
Home Automation and Controls Market
Automation
Playout Automation Market
Automation
Postal Automation System Market
Automation
Network Automation Market
Automation
United States Laboratory Automation Market
Automation
Home Automation System Market
Automation
Window Automation Market
Automation
Global Cloud Automation Market
Automation
Global Warehouse Barcode System Market
Automation
Dropshipping Automation Software Market
Automation
Hyperautomation Market
Automation
Parcel Sorting System Market
Automation
Universal Process Control Market