
 Governed Enterprise Architecture Scenario Sandbox Market | 2026-2036
Governed Enterprise Architecture Scenario Sandbox Market Size, Share, and Industry Trends Forecast 2026-2036
Governed Enterprise Architecture Scenario Sandbox Market Insights
Enterprise architecture talent scarcity is rotating vendor selection criteria toward platforms with embedded governance automation. SAP LeanIX leverages deep SAP ecosystem integration to anchor large European manufacturing accounts. BiZZdesign specializes in visual modeling standards that dominate regulated Dutch and Belgian public sector procurement. IBM extends legacy consulting relationships into sandbox deployments through its hybrid cloud architecture practice.
A governed enterprise architecture scenario sandbox is a controlled computational environment that simulates IT system changes, policy shifts, and technology integrations against predefined compliance rules, governance frameworks, and risk thresholds before live deployment. The platform ingests enterprise metadata, applies scenario parameters, and generates impact propagation maps across application portfolios, infrastructure layers, and data flows. Cloud-based deployment models capture the dominant revenue share as financial institutions reject on-premises capital commitments in favor of elastic consumption models. Simulation engines lead solution type demand because architecture teams require high-fidelity behavioral modeling of interdependent system changes. Strategy planning use cases generate premium pricing as C-suite sponsors fund scenario exercises for M&A technology integration and cloud migration sequencing.
The EU AI Act mandates pre-deployment validation environments for high-risk automated systems, directly expanding sandbox requirements across European banking and telecommunications operators. NIST cybersecurity framework adoption in US federal contracting creates procurement specifications requiring architecture simulation capabilities for supply chain risk assessment. GDPR Article 32 technical measures push multinational corporations to model data residency and processing location changes before implementation. Stakeholders must evaluate whether their current enterprise architecture tooling stacks can absorb sandbox governance functions natively or require parallel platform investments.
Market Dynamics
Enterprise architecture teams face mounting pressure to pre-validate system changes as regulatory mandates harden across multiple jurisdictions, forcing institutions to adopt governed simulation environments before any production deployment.
Growth Catalysts
- EU AI Act:European banking and telecommunications operators must deploy pre-validation environments for high-risk automated systems, directly expanding sandbox procurement specifications.
- Cloud elasticity:Financial institutions reject on-premises capital commitments in favor of consumption-based deployment models, accelerating vendor platform migrations.
- Germany:Industrial conglomerates operating complex multi-entity technology landscapes require governed simulation capabilities for architecture stress-testing across subsidiary networks.
Market Restraints
- Enterprise architect scarcity:Talent shortages in architecture governance and simulation modeling constrain platform utilization rates and extend implementation timelines.
- Legacy system entanglement:Decades-old core banking and manufacturing execution systems resist metadata extraction needed for accurate scenario modeling.
- Input cost volatility:Cloud compute pricing fluctuations create budget uncertainty for institutions running intensive simulation workloads at scale.
Strategic Opportunities
- GDPR Article 32:Technical measures push multinational corporations to model data residency changes before implementation, creating demand for privacy-integrated sandbox modules.
- M&A technology integration:Strategy planning use cases generate premium pricing as C-suite sponsors fund scenario exercises for post-merger architecture rationalization.
- Digital twin convergence:Integration between enterprise architecture sandboxes and operational technology simulation platforms opens new industrial application verticals.
Industry Challenges
- Metadata quality gaps:Incomplete or outdated application portfolio inventories corrupt simulation outputs and erode stakeholder confidence in scenario results.
- Cross-functional alignment:Architecture, compliance, and infrastructure teams operate with conflicting success metrics, complicating sandbox governance rule definition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Governed Enterprise Architecture Scenario Sandbox Market |
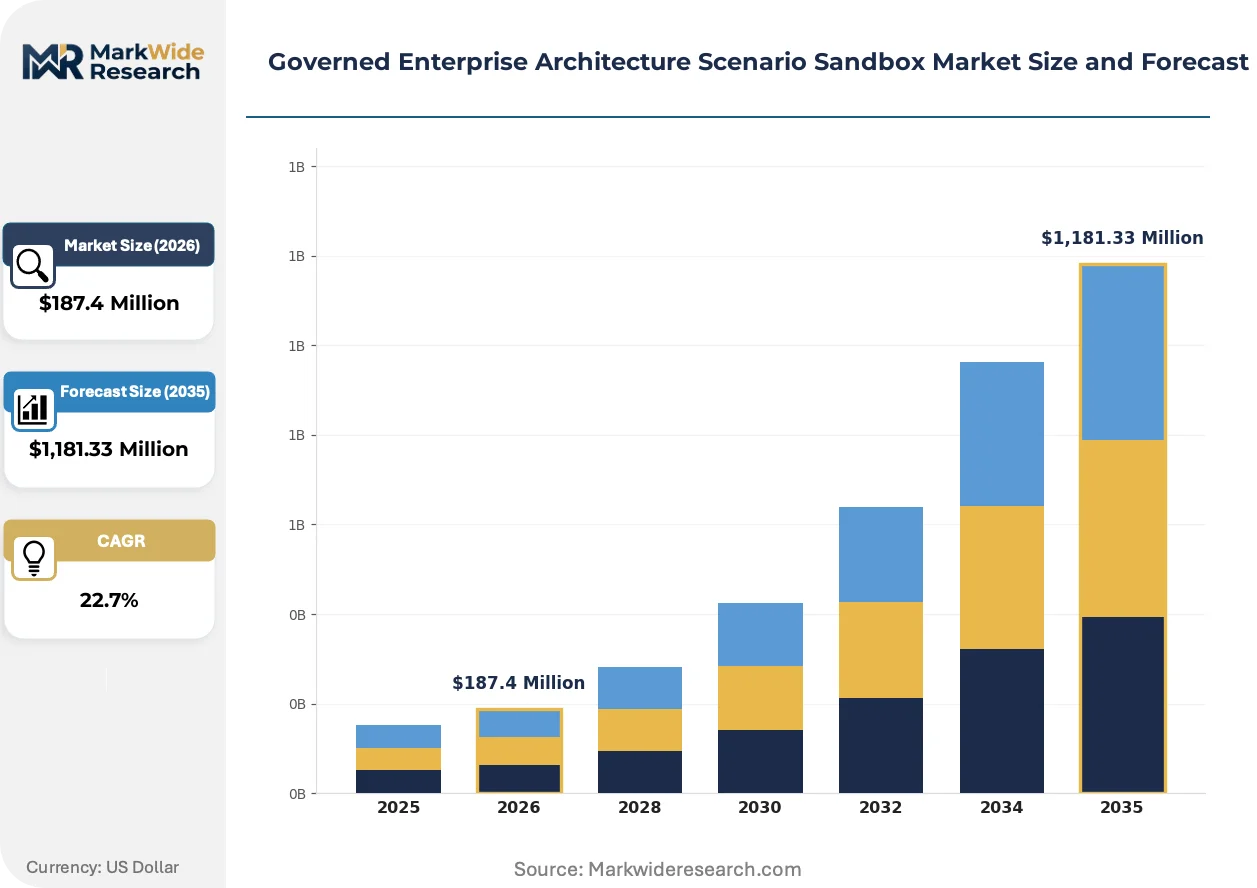
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Simulation Engines, Impact Analysis Tools, Compliance Checkers, Risk Assessment Modules, Visualization Dashboards Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing Use Case: Strategy Planning, Regulatory Compliance, Resource Optimization, Change Management, Technology Integration End User Industry: Banking Financial Services, Telecommunications, Manufacturing, Government Agencies, Energy Providers |
| Companies Covered | Ardoq, SAP LeanIX, BiZZdesign, Avolution, Orbus Software, Sparx Systems, IBM, Software AG, MEGA International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Governed Enterprise Architecture Scenario Sandbox Market Trends and Innovations
Simulation technology is bifurcating into specialized paths as buyer sophistication increases, with architectural fidelity requirements diverging sharply between compliance-driven and innovation-driven use cases.
Digital twin technology is bifurcating enterprise architecture practice by merging operational technology simulation with IT system modeling. German automotive and chemical conglomerates deploy these converged environments to validate factory automation changes against ERP system impacts. The structural consequence is compressing traditional separation between OT and IT architecture disciplines into unified governance frameworks.
REACH regulatory expansion into digital product passports is forcing European manufacturers to trace component-level data flows through architecture simulations. Industrial consequence includes mandatory pre-deployment validation of supply chain data residency configurations. Affected segments include medical device manufacturers preparing for MDR compliance and battery producers adapting to EU Green Deal traceability requirements.
Consumption-based licensing is displacing perpetual software agreements across financial services procurement functions. Subscription elasticity allows architecture teams to scale simulation capacity during merger integration peaks without capital committee approval. This pattern concentrates in Dutch and Belgian banking consortia where shared service centers aggregate procurement leverage across multiple institutions.
Governed Enterprise Architecture Scenario Sandbox Market Segmentation
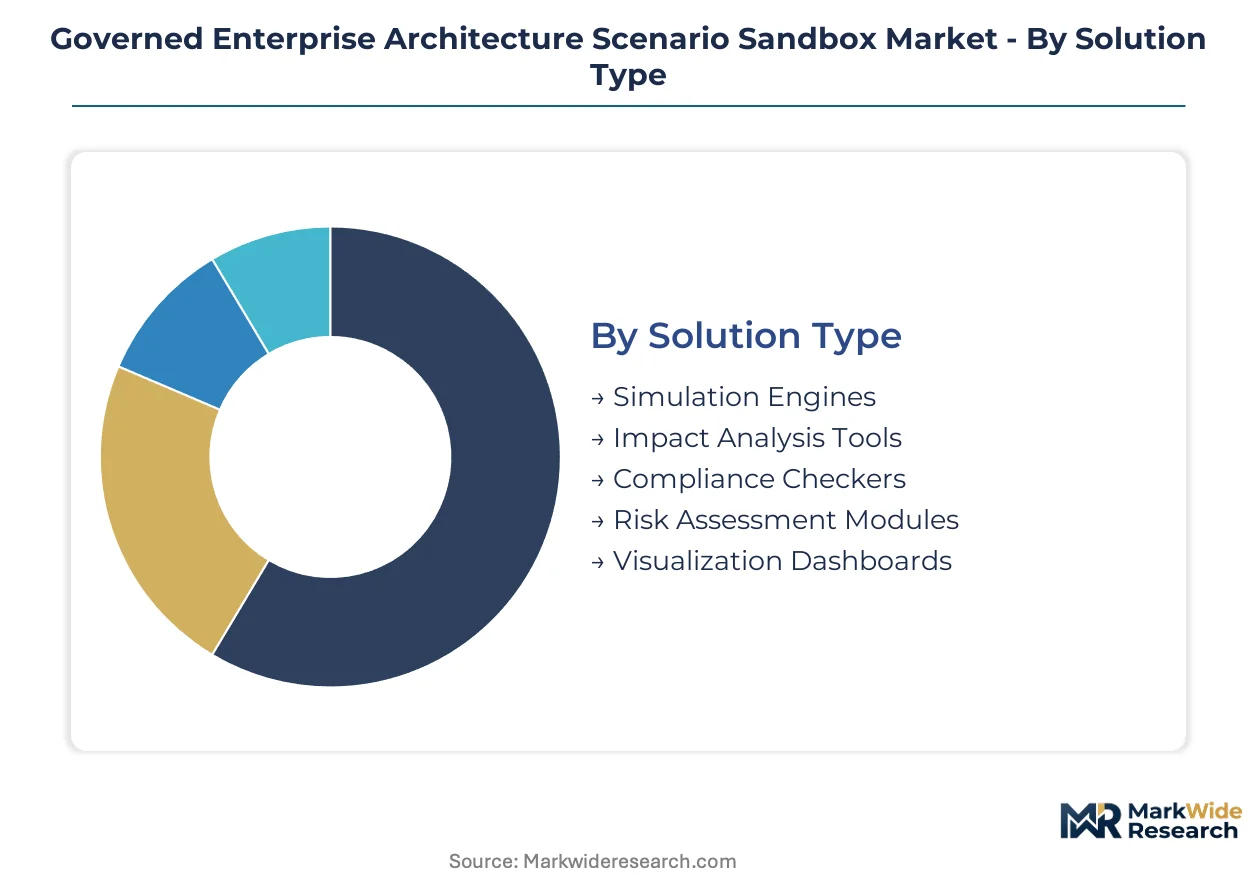
Segmentation in the governed enterprise architecture scenario sandbox market reveals how regulatory complexity drives purchasing patterns across solution types and deployment models. Architecture teams select capabilities based on specific compliance mandates rather than generic feature sets.
Solution Type:
EU AI Act pre-deployment validation requirements and GDPR technical measures create divergent capability demands across European banking and telecommunications procurement.
- Simulation Engines:High-fidelity behavioral modeling of interdependent system changes enables stress-testing of architecture modifications before production deployment. German industrial conglomerates concentrate demand for these engines to validate multi-entity technology landscape changes across subsidiary networks. Cloud compute elasticity supports intensive simulation workloads without capital commitment.
- Impact Analysis Tools:Automated propagation mapping traces consequences of policy shifts and technology integrations across application portfolios and data flows. Dutch and Belgian banking consortia deploy these tools for shared service center governance, driven by CSRD sustainability reporting requirements mandating pre-implementation impact assessment.
- Compliance Checkers:Predefined rule validation against EU AI Act high-risk system thresholds.
- Risk Assessment Modules:Quantified exposure scoring for supply chain and data residency configurations.
- Visualization Dashboards:C-suite presentation layers for M&A technology integration scenarios.
Established volume favors Simulation Engines; emerging adoption favors Impact Analysis Tools.
Deployment Model:
Cost tier differentiation separates elastic consumption from fixed infrastructure commitments, with financial institutions rejecting capital-intensive procurement patterns.
- Cloud-Based:Consumption-based licensing allows architecture teams to scale simulation capacity during merger integration peaks without committee approval. Financial institutions in the Netherlands and Belgium lead migration away from perpetual agreements, aggregating procurement leverage across banking consortia.
- Hybrid:Split workload management keeps sensitive metadata on-premises while leveraging cloud compute for simulation processing. German automotive manufacturers favor this model to satisfy both operational technology isolation requirements and IT elasticity demands.
- On-Premises:Fixed infrastructure for classified government architecture repositories.
- Edge Computing:Factory-floor simulation nodes for converged OT-IT digital twin deployments.
Cloud-Based deployments hold dominant revenue share; Hybrid configurations gain share fastest in regulated manufacturing verticals.
Use Case:
Application maturity separates strategy-driven premium pricing from operational efficiency mandates, with C-suite sponsorship determining budget allocation.
- Strategy Planning:Scenario exercises for M&A technology integration and cloud migration sequencing command premium pricing through executive sponsorship. Telecommunications operators in Europe fund these engagements to rationalize post-merger architecture portfolios.
- Regulatory Compliance:Pre-validation environments for EU AI Act high-risk automated systems and GDPR Article 32 technical measures. Banking supervisors mandate these capabilities before any production deployment of decision-automation systems.
- Resource Optimization:Infrastructure right-sizing and license consolidation modeling.
- Change Management:Stakeholder alignment workflows for architecture transformation programs.
- Technology Integration:API compatibility and data flow validation for system interoperability.
Regulatory Compliance drives baseline procurement; Strategy Planning commands pricing premiums.
End User Industry:
Customer type concentration reflects sector-specific regulatory pressure intensity and architecture complexity thresholds.
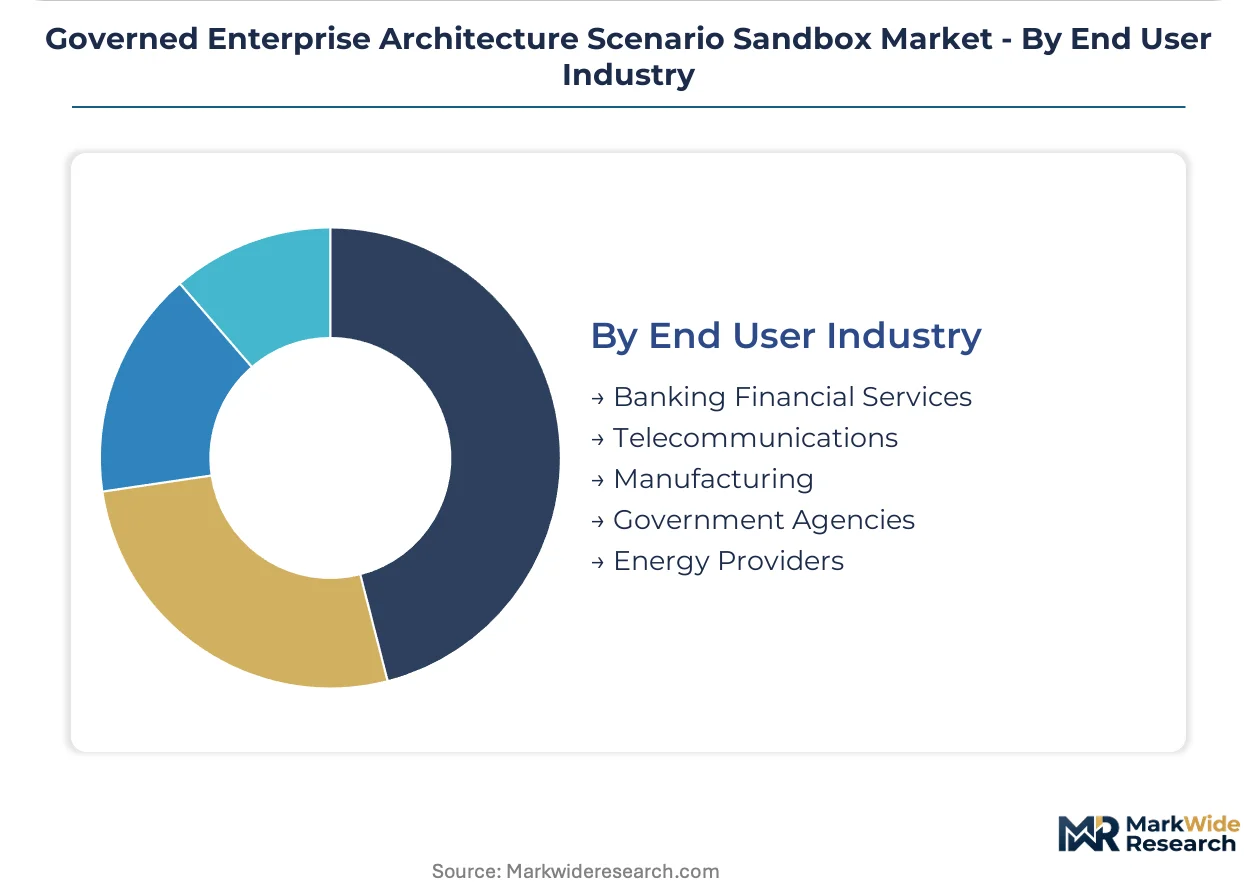
- Banking Financial Services:EU AI Act and GDPR compliance requirements force pre-validation environment adoption for automated decision systems. Stress-testing architecture changes before production deployment has become standard procurement specification.
- Manufacturing:REACH digital product passport expansion and EU Green Deal traceability requirements mandate supply chain data flow simulation. German chemical and battery producers validate component-level residency configurations before implementation.
- Telecommunications:NIS2 directive cybersecurity architecture assessment requirements.
- Government Agencies:NIST cybersecurity framework procurement specifications in federal contracting.
- Energy Providers:Critical infrastructure protection mandates for OT-IT convergence validation.
Banking Financial Services anchors current revenue; Manufacturing climbs the fastest on regulatory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors procurement specifications across European banking and telecommunications operators, while GDPR Article 32 technical measures extend demand into multinational data residency modeling. Germany, the Netherlands, and Belgium concentrate early adoption, with US federal contracting specifications and Japanese industrial digitalization programs expanding the addressable base.
Germany
Industrial conglomerates operating complex multi-entity technology landscapes drive demand for governed simulation capabilities across subsidiary networks. The EU AI Act mandates pre-validation environments for high-risk automated systems in automotive and chemical manufacturing. Stuttgart and Munich clusters anchor deployment, with factory automation changes requiring ERP system impact validation before implementation.
Netherlands
Dutch banking consortia aggregate procurement leverage across shared service centers, rejecting perpetual software agreements for consumption-based licensing models. CSRD sustainability reporting requirements mandate pre-implementation impact assessment for architecture transformations. Amsterdam's financial services hub concentrates cloud-based sandbox deployments for merger integration peaks.
Belgium
Belgian public sector procurement specifications favor visual modeling standards for regulated architecture governance. GDPR Article 32 technical measures push institutions to model data processing location changes before deployment. Brussels anchors demand from EU institutional headquarters requiring compliance-integrated simulation modules.
United States
NIST cybersecurity framework adoption in federal contracting creates procurement specifications requiring architecture simulation for supply chain risk assessment. Banking regulators stress-test automated decision systems through pre-validation mandates. New York and Boston financial centers drive cloud elasticity preferences over on-premises capital commitments.
Japan
METI industrial digitalization programs promote operational technology convergence with enterprise architecture simulation. Manufacturing execution systems require metadata extraction for accurate scenario modeling of factory automation changes. Nagoya automotive clusters and Osaka chemical producers validate OT-IT integration through hybrid deployment configurations.
Governed Enterprise Architecture Scenario Sandbox Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with specialized governance automation vendors competing against legacy consulting extensions and ecosystem-anchored platforms. The vendor base stratifies across three tiers: SAP-integrated specialists, visual modeling standards providers, and hybrid cloud architecture practices. Strategic moves concentrate on embedded governance automation, M&A technology integration scenario modules, and digital twin convergence capabilities.
Within the ecosystem-anchored tier, SAP LeanIX and Software AG represent platform strategies leveraging deep enterprise software integration to anchor large manufacturing accounts. BiZZdesign occupies a position among visual modeling specialists serving regulated European public sector procurement. IBM exemplifies the consulting-extension archetype, translating legacy relationships into hybrid cloud architecture deployments. Ardoq and Avolution sit within the emerging specialist category, while Orbus Software and Sparx Systems anchor mid-market visual standards adoption. MEGA International represents the European governance automation specialist segment.
| Leading Market Players |
|---|
| Ardoq |
| SAP LeanIX |
| BiZZdesign |
| Avolution |
| Orbus Software |
| Sparx Systems |
| IBM |
| Software AG |
| MEGA International |
| Others |
Pricing and Supply Chain Analysis
Consumption-based licensing contracts lock in multi-year simulation capacity commitments while insulating financial institutions from cloud compute price volatility. Dutch and Belgian banking consortia leverage these structures to aggregate procurement leverage across shared service centers, converting capital expenditure into predictable operational outflows.
Pricing Analysis
Price spreads between Frankfurt and Amsterdam cloud regions exceed those between London and Singapore due to EU data residency premiums. Three-tier pricing structure across premium, standard, and economy levels separates strategy planning modules from regulatory compliance baselines, with customization for M&A scenarios commanding the highest tier. Cost compression in standard-tier simulation engines intensifies because hyperscaler infrastructure commoditization erodes vendor differentiation. Mid-market manufacturing accounts exhibit highest price sensitivity; tier-one banks with EU AI Act mandates show lowest.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for specialized GPU hardware required by German automotive digital twin deployments. Cloud infrastructure concentrates in Ireland, Germany, and the Netherlands; simulation software development clusters in Estonia, Poland, and Portugal. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and liquid cooling systems. Single-source vulnerability in NVIDIA chip supply creates procurement risk for intensive workload vendors. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping vendor viability as SAP ecosystem integration and digital twin convergence create winner-take-most dynamics. Interoperability standards between operational technology and enterprise architecture simulation are compressing traditional discipline boundaries into unified procurement specifications.
For Market Incumbents: Secure SAP-anchored manufacturing accounts through embedded governance automation modules before IBM extends hybrid cloud consulting relationships into these installations. Vertical integration into metadata extraction tooling addresses legacy system entanglement that corrupts simulation outputs. Certification investment in EU AI Act pre-validation capabilities defends against emerging specialists targeting compliance-driven procurement.
For New Entrants and Emerging Players: Differentiate on privacy-integrated sandbox modules targeting GDPR Article 32 technical measures in Belgian public sector procurement. White-space concentrates in REACH digital product passport simulation for battery producers and medical device manufacturers. The most penetrable segment is mid-market Dutch manufacturing lacking SAP ecosystem lock-in. Go-to-market through hyperscaler marketplace listings accelerates procurement bypassing traditional vendor evaluation cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native simulation engine vendors with consumption-based licensing models. Long-term viability rests on digital twin convergence capabilities bridging OT-IT architecture disciplines. Acquisition target archetype: European governance automation specialists with EU regulatory certification depth. The signal to watch as inflection indicator is NIST cybersecurity framework adoption velocity in US federal contracting specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | SAP LeanIX ecosystem anchoring captures German automotive and chemical conglomerates. |
| Regulatory Certification | EU AI Act pre-validation modules unlock European banking and telecommunications procurement. |
| Digital Twin Convergence | OT-IT unified governance frameworks open industrial verticals beyond traditional IT architecture. |
| Consumption Model Transition | Subscription elasticity allows Dutch banking consortia to scale merger integration capacity. |
| Geographic Expansion | US federal NIST compliance specifications create architecture simulation procurement mandates. |
Research Methodology
Initial hypotheses were tested against primary input from enterprise architects, compliance officers, cloud procurement leads, and OT-IT integration specialists and refined through secondary validation. Primary fieldwork encompassed structured interviews across banking, manufacturing, and telecommunications verticals in Germany, the Netherlands, Belgium, and the United States. Secondary sources included SEC 10-K filings, EU regulatory impact assessments, hyperscaler capex disclosures, and architecture tooling procurement databases. Bottom-up segment sizing triangulated against top-down market envelope estimates across the analysis window.
Variance decomposition isolates growth contributions from regulatory mandate expansion, cloud elasticity adoption, and digital twin convergence across the projection horizon. Segmentation dimensions modeled encompass solution type, deployment model, use case maturity, and end-user industry regulatory intensity. CAGRs derive from scenario-weighted probability distributions applied to baseline adoption curves. Industry-specific forecast inputs include EU AI Act implementation timelines and NIST framework procurement specification velocity.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement and hyperscaler infrastructure availability; material deviation would warrant model refresh. Specific risks that could revise forecasts include cloud compute price volatility, enterprise architect talent scarcity constraining platform utilization, and legacy system metadata quality gaps corrupting simulation reliability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Online Dating Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
Social Networking App Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
AI In Packaging Design Market
Digital Solutions
Digital Twin Market
Digital Solutions
Data Governance Market
Digital Solutions
Retail Warehouse Management Systems Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Global Tag Management System Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Data Converter Market
Digital Solutions
Procure-To-Pay Solutions Market