
 Network Automation Market | 2026-2036
Network Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Network Automation Market Analysis
Subscription-based consumption models and network-as-a-service financing is tilting competitive dynamics toward vendors with scalable cloud delivery architectures. Cisco leverages its installed base of routing hardware to extend automation software attach rates across enterprise campuses. Juniper Networks specializes in intent-based networking, anchoring its differentiation around Mist AI-driven operations for wireless and wired environments. Red Hat competes through its open-source Ansible platform, which controls automation workflows across heterogeneous vendor stacks without proprietary lock-in.
Network automation encompasses software-defined methods for configuring, managing, and optimizing network infrastructure through programmatic interfaces rather than manual command-line intervention, typically employing YANG data models, NETCONF/RESTCONF protocols, and telemetry streams to enforce policy across routers, switches, and firewalls. Its primary commercial purpose is eliminating configuration drift, reducing mean-time-to-repair, and enabling elastic capacity scaling in distributed architectures. Software solutions occupy the dominant margin pool as recurring license revenue compounds with each additional managed node, while AI-driven automation represents the fastest-expanding technology segment as inference workloads move closer to network edge devices for real-time traffic engineering. Services lag in growth velocity but capture sticky integration revenue where enterprises lack internal platform engineering expertise.
The Federal Communications Commission in the United States enforces network reliability standards that elevate automation from operational convenience to regulatory necessity for critical communications infrastructure. The European Union Agency for Cybersecurity operationalizes NIS2 requirements that mandate automated threat detection and response capabilities across essential and important entities. Stakeholders must weigh the interoperability trade-offs between vendor-proprietary automation stacks and open-source frameworks when committing to multi-year infrastructure refresh cycles.
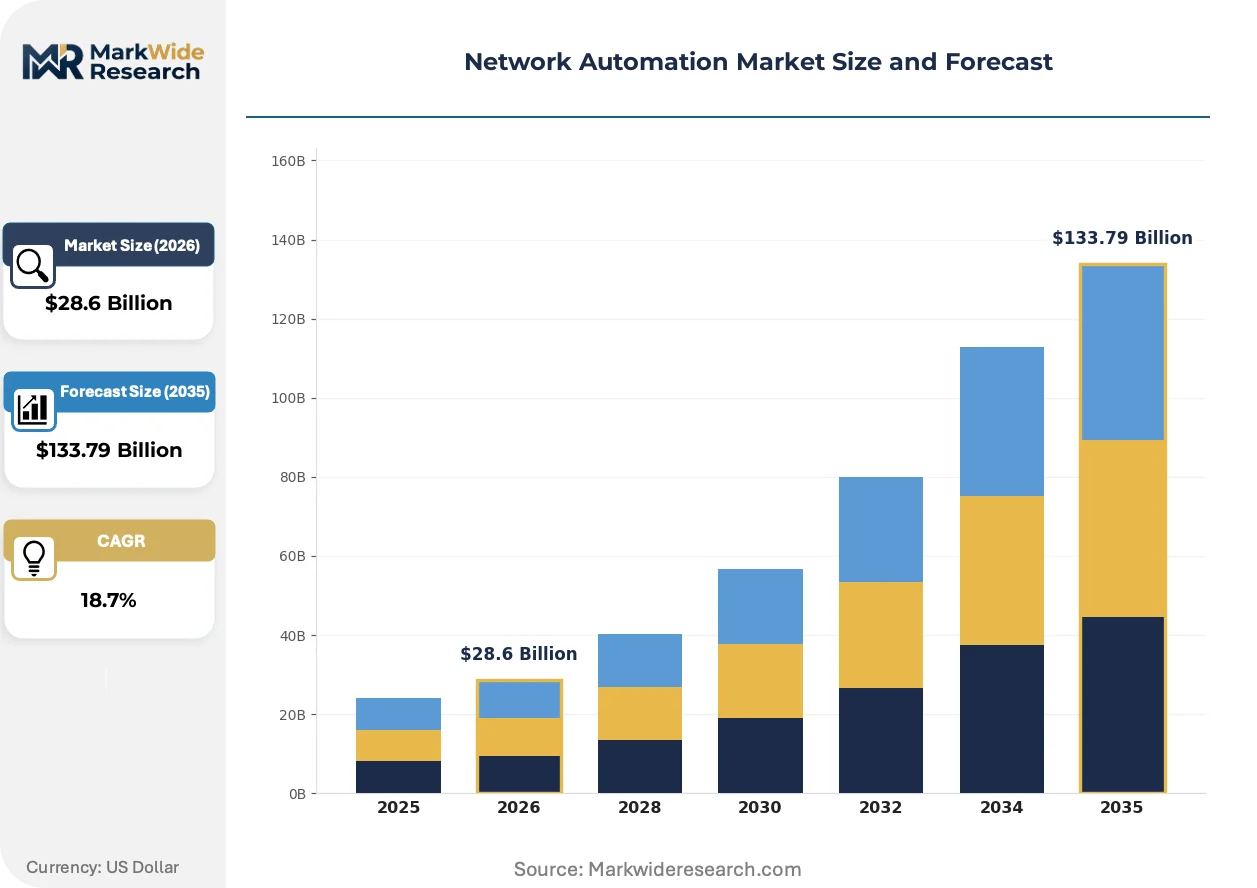
Market Dynamics
The EU AI Act's explainability mandates are forcing network orchestration vendors to rearchitect decision engines for critical infrastructure, compressing development cycles and elevating compliance costs across multi-vendor deployments.
Growth Catalysts
- EU AI Act explainability requirements:The European Union's mandatory disclosure of automated decision logic in essential infrastructure is pulling investment toward transparent orchestration platforms that audit configuration changes in real time.
- Industrial automation clusters in Germany:Carrier-neutral data center buildouts around Frankfurt and Munich are generating concentrated demand for programmable network fabrics that span heterogeneous equipment estates.
- Telemetry-driven closed-loop remediation:Streaming YANG-modeled data from routers and switches into AI inference engines is collapsing mean-time-to-repair from hours to seconds for enterprise campus networks.
Market Restraints
- Specialized platform engineering talent scarcity:Enterprises face structural shortages of engineers fluent in NETCONF, YANG modeling, and Kubernetes-based network function orchestration.
- Proprietary automation stack lock-in:Vendor-specific intent-based networking controllers create switching costs that freeze infrastructure refresh decisions and fragment operational workflows.
- Multi-year compliance certification timelines:NIS2 Directive implementation across EU member states is extending procurement cycles as essential entities validate automated threat detection capabilities.
Strategic Opportunities
- Edge inference for real-time traffic engineering:Converging 5G network slicing with containerized AI workloads at base stations is opening new service tiers for telecommunications providers.
- Open-source controller adoption in mid-market enterprises:Ansible and Terraform community editions are penetrating organizations that previously deferred automation due to proprietary licensing costs.
- Subscription-based network-as-a-service financing:Cloud-delivered automation platforms are displacing perpetual license models in distributed retail and healthcare networks.
Industry Challenges
- Configuration drift in brownfield environments:Legacy CLI-managed switches resist programmatic control, forcing parallel inventory maintenance and error-prone translation layers.
- Cross-vendor YANG model inconsistency:Incomplete standardization of data models across router manufacturers fragments policy enforcement and complicates multi-vendor telemetry correlation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Automation Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $133.79 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Devices, Services, Platforms Technology: AI-Driven Automation, Machine Learning, Cloud-Based Solutions, Open Source Application: Data Center Automation, WAN Automation, Network Management, Security Automation End User: Telecommunications, BFSI, Healthcare, Manufacturing |
| Companies Covered | Capgemini, Ciena, Cisco, VMware, IBM, Google Cloud, Hewlett Packard Enterprise, Juniper Networks, Red Hat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Automation Market Emerging Trajectories
Intent-based networking architectures are collapsing the traditional separation between design, provisioning, and assurance phases, compressing operational workflows and redefining vendor competitive positioning around AI-driven closed-loop systems.
Streaming telemetry architectures built on gRPC and Protocol Buffers are collapsing the polling-based SNMP paradigm that dominated network monitoring for three decades. Telecommunications providers in South Korea and Japan are deploying these systems at scale for 5G transport networks. The structural consequence is collapsing the data collection latency that previously obscured transient congestion events in core routers.
The FCC's reliability standards for critical communications infrastructure are elevating automation from operational convenience to regulatory necessity for public safety networks and emergency response systems. These mandates are forcing equipment vendors to embed automated failover and self-healing capabilities as baseline features rather than premium options. Rural broadband providers in the United States are responding by accelerating procurement of orchestration platforms that document compliance through immutable audit trails.
Enterprise procurement teams are unbundling professional services from software licenses, demanding à-la-carte implementation support and API documentation transparency. This pattern is displacing the traditional bundled support contracts that anchored vendor recurring revenue. The shift is most visible in financial services networks across Singapore and Australia, where internal platform engineering teams now self-implement automation controllers using open-source frameworks.
Network Automation Market Segmentation
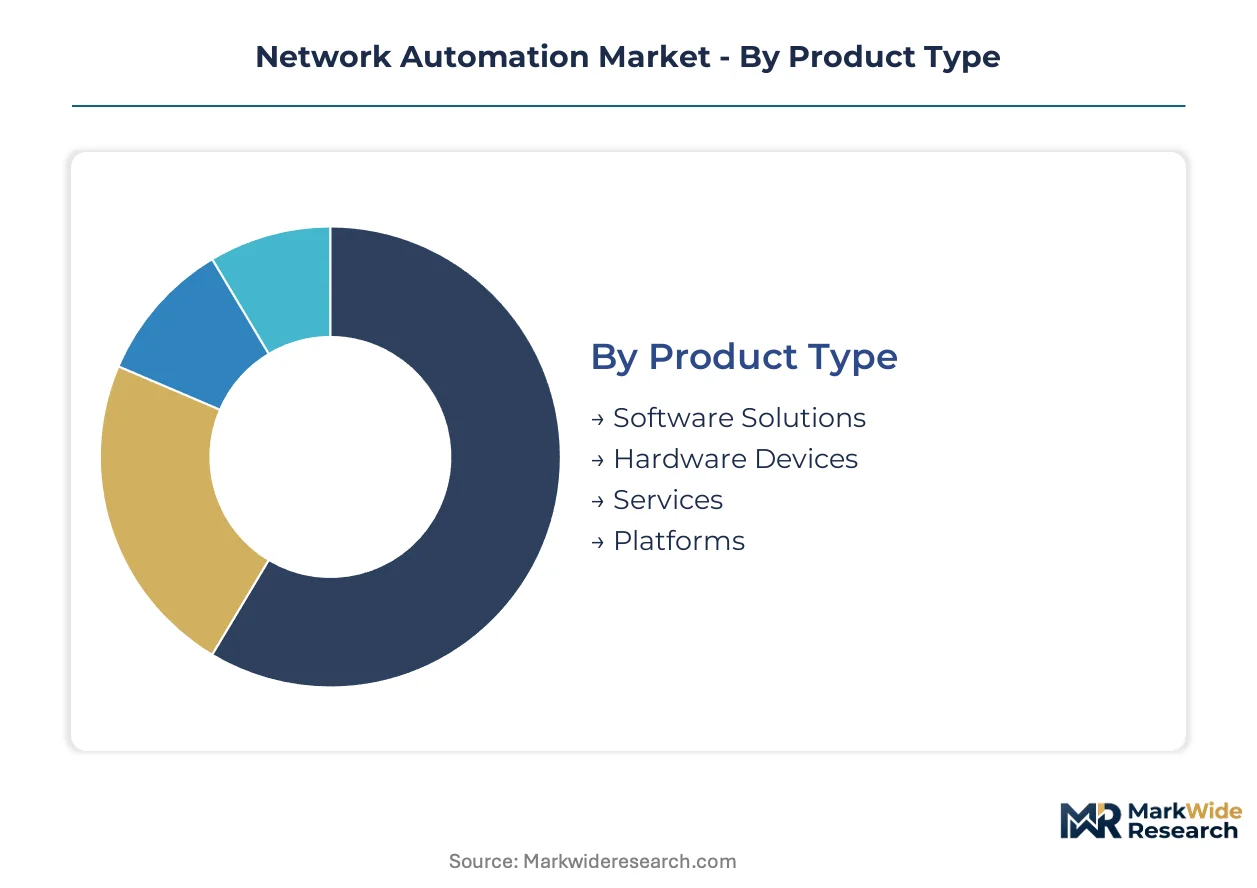
Network automation vendors architect product portfolios around distinct operational layers, from programmable hardware to cloud-delivered orchestration platforms. Each segment carries different margin profiles and integration complexity, shaping how procurement teams structure multi-year infrastructure commitments.
Product Type:
Software solutions anchor enterprise spending where recurring license revenue compounds with each managed node, while hardware devices and services occupy distinct positions in the technology lifecycle.
- Software Solutions:Programmable controllers and orchestration engines enforce policy across multi-vendor estates through YANG-modeled configurations. Financial services networks in Singapore and Australia are unbundling professional services from licenses, demanding API transparency and self-implementation capabilities.
- Hardware Devices:Programmable switches and routers with embedded automation agents handle real-time traffic engineering at the network edge. Telecommunications providers in South Korea deploy these for 5G transport networks where millisecond latency requirements preclude cloud-only control planes.
- Services:Integration and managed automation support capture sticky revenue where enterprises lack internal NETCONF and Kubernetes expertise. Brownfield environments with legacy CLI-managed equipment drive demand for migration consulting.
- Platforms:Unified automation stacks combining controller software, analytics engines, and vendor-specific hardware integrations. Mid-market enterprises favor subscription-based consumption models that displace perpetual licensing.
The dominant share belongs to Software Solutions, while Platforms is closing the gap fastest as cloud delivery architectures displace on-premises controller deployments.
Technology:
Cost tier stratification separates premium AI inference engines from commodity open-source tooling, with machine learning occupying the middle ground for predictive analytics workloads.
- AI-Driven Automation:Real-time inference engines process streaming telemetry for closed-loop remediation, collapsing mean-time-to-repair from hours to seconds. The EU AI Act's explainability mandates are forcing vendors to rearchitect decision engines for critical infrastructure, elevating compliance costs.
- Machine Learning:Predictive models trained on historical network telemetry forecast capacity exhaustion and anomaly patterns before service degradation occurs. WAN optimization use cases in Germany's industrial automation clusters concentrate demand for these capabilities.
- Cloud-Based Solutions:SaaS-delivered automation controllers eliminate capital expenditure for distributed retail and healthcare networks. The FCC's reliability standards for critical communications infrastructure elevate these from convenience to regulatory necessity.
- Open Source:Ansible and Terraform community editions penetrate mid-market enterprises that previously deferred automation due to proprietary licensing costs. Fragmented YANG model standardization across router manufacturers complicates multi-vendor policy enforcement.
AI-Driven Automation commands premium pricing, though Open Source is expanding most quickly as platform engineering talent scarcity drives adoption of community-supported tooling.
Application:
Volume concentration tracks data center buildouts and WAN refresh cycles, with security automation gaining share as NIS2 Directive implementation extends procurement timelines for automated threat detection.
- Data Center Automation:Intent-based networking collapses design, provisioning, and assurance phases for carrier-neutral facilities around Frankfurt and Munich. These programmable fabrics span heterogeneous equipment estates from multiple switch vendors.
- WAN Automation:Software-defined wide area networks optimize path selection across broadband, MPLS, and 5G transport links. Rural broadband providers in the United States accelerate procurement to document FCC compliance through immutable audit trails.
- Network Management:Streaming telemetry architectures built on gRPC and Protocol Buffers displace SNMP polling paradigms. Japanese telecommunications providers deploy these at scale for core router congestion visibility.
- Security Automation:Automated threat detection and response capabilities satisfy EU AI Act and NIS2 requirements for essential entities. Multi-year compliance certification timelines extend procurement cycles as validation processes formalize.
Data Center Automation holds the largest deployment base, while Security Automation is gaining share fastest as regulatory mandates harden automation from operational preference to compliance requirement.
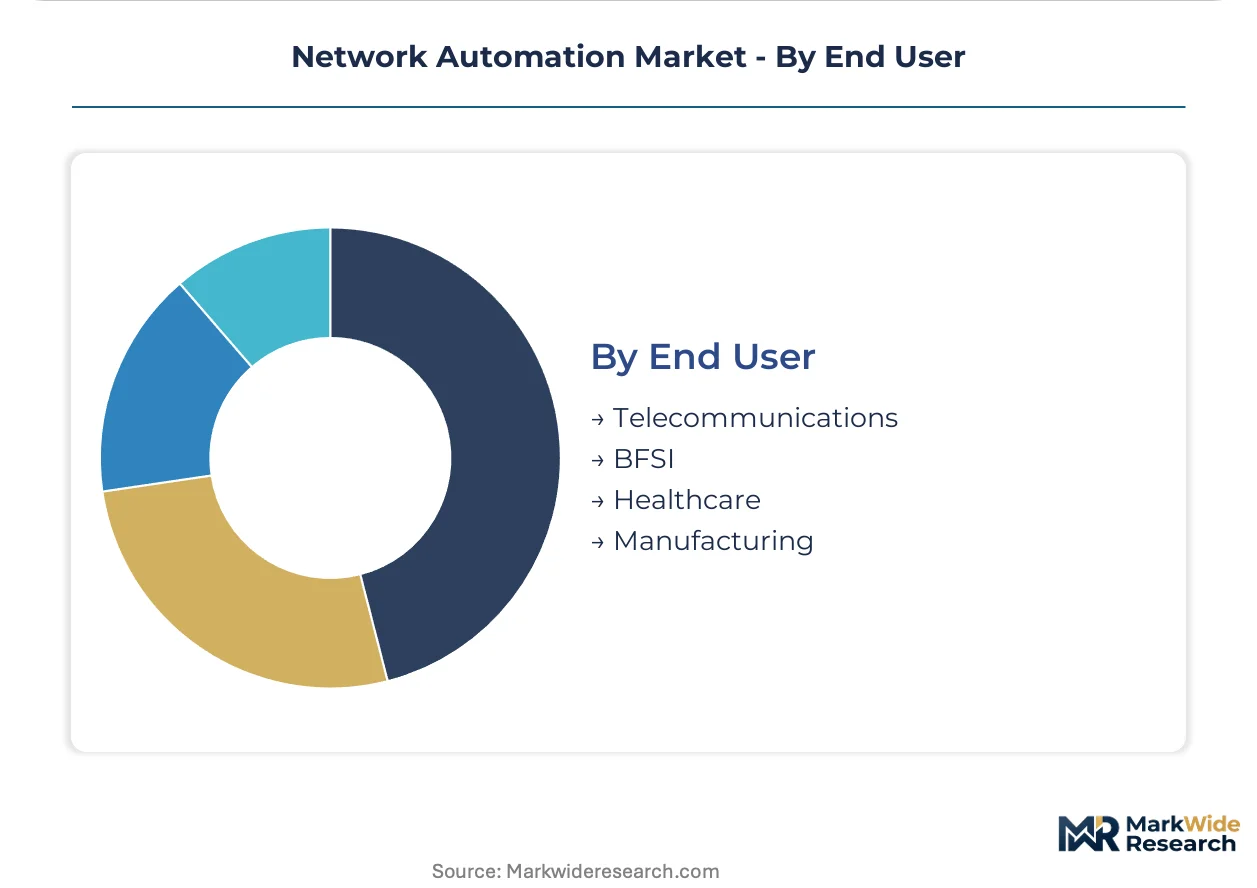
End User:
Customer type segmentation reflects divergent technical sophistication, from telecommunications providers with internal platform engineering teams to manufacturing enterprises dependent on systems integrators.
- Telecommunications:5G network slicing converges with containerized AI workloads at base stations, opening new service tiers for real-time traffic engineering. South Korean and Japanese operators lead deployment of streaming telemetry at transport network scale.
- BFSI:Financial services networks demand immutable audit trails for regulatory examination, with procurement teams unbundling services from software licenses. Singapore and Australian institutions self-implement using open-source frameworks.
- Healthcare:Distributed clinical networks prioritize subscription-based financing models that align automation spending with operational budgets rather than capital cycles. HIPAA compliance requirements shape audit and access control specifications.
- Manufacturing:Industrial automation clusters in Germany pull investment toward programmable network fabrics connecting operational technology and information technology domains. Specialized platform engineering talent scarcity constrains self-managed deployments.
Telecommunications captures the deepest automation penetration, while Manufacturing is climbing the fastest as Industry 4.0 initiatives mandate programmable infrastructure for smart factory connectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act's explainability mandates and NIS2 Directive implementation are reshaping procurement patterns for network orchestration platforms across essential infrastructure operators, with compliance timelines varying by national transposition schedules.
United States
FCC reliability standards for critical communications infrastructure mandate automated failover capabilities for public safety networks and emergency response systems. Rural broadband providers accelerate orchestration platform procurement to document compliance through immutable audit trails. Washington and California anchor demand concentration where defense contractors and cloud hyperscalers operate programmable network fabrics.
Germany
Industrial automation clusters around Frankfurt and Munich generate concentrated demand for programmable network fabrics spanning heterogeneous equipment estates. The national implementation of NIS2 Directive requirements extends procurement cycles as essential entities validate automated threat detection capabilities. Bavaria and Baden-Württemberg host manufacturing enterprises deploying intent-based networking for smart factory connectivity.
South Korea
Telecommunications providers deploy streaming telemetry architectures at scale for 5G transport networks where millisecond latency requirements preclude cloud-only control planes. The national regulator enforces network reliability benchmarks that elevate automation from operational preference to infrastructure necessity. Seoul and Busan-Ulsan metropolitan areas concentrate R&D investment for edge inference workloads converging with network slicing.
Japan
Japanese telecommunications operators lead deployment of gRPC-based telemetry systems for core router congestion visibility, displacing three-decade SNMP polling paradigms. METI industrial digitization programs subsidize programmable infrastructure adoption for operational technology networks. Tokyo and Osaka-Kansai regions host financial services networks unbundling professional services from software licenses.
Singapore
Financial services procurement teams demand API transparency and self-implementation capabilities using open-source frameworks, displacing traditional bundled support contracts. The national cybersecurity agency mandates automated threat response for systemically important financial infrastructure. The city-state's data center buildouts pull investment toward carrier-neutral programmable fabrics.
Network Automation Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: cloud-native orchestration platforms, hardware-anchored automation stacks, and open-source workflow engines. Strategic archetypes include telecommunications equipment vendors extending software attach rates, enterprise IT incumbents leveraging cloud delivery architectures, and community-supported tooling specialists capturing mid-market penetration. Dominant competitive moves encompass strategic partnerships between hardware manufacturers and AI inference providers, plus portfolio diversification into edge-native automation controllers.
Within the telecommunications equipment tier, Cisco and Juniper Networks exemplify hardware-anchored strategies, while Red Hat occupies the open-source workflow position. Cisco leverages its installed base of routing hardware to extend automation software penetration across enterprise campuses. Juniper Networks anchors its differentiation around Mist AI-driven operations for wireless and wired environments. Red Hat competes through its open-source Ansible platform, which controls automation workflows across heterogeneous vendor stacks without proprietary lock-in.
| Leading Market Players |
|---|
| Capgemini |
| Ciena |
| Cisco |
| VMware |
| IBM |
| Google Cloud |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Red Hat |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Singapore maritime corridor's container cost volatility shapes procurement economics for programmable network hardware, concentrating pricing power with semiconductor fabricators while forcing tiered SaaS subscription models that separate premium orchestration platforms from open-source alternatives.
Pricing Analysis
Certification level under the EU AI Act and NIS2 Directive creates the primary spread between premium orchestration platforms and standard automation tooling. Subscription-based SaaS tiers dominate enterprise procurement, with price differentiation anchored in compliance documentation depth and real-time explainability features. Cost compression in mid-market segments intensifies as Ansible and Terraform community editions displace proprietary licensing. Healthcare networks exhibit the highest price sensitivity due to capital budget constraints, while telecommunications providers prioritize performance over cost.
Supply Chain Analysis
Export-control restrictions on advanced AI inference chips limit flows from Taiwan and South Korea into European automation vendors, fragmenting hardware availability. Controller software draws from Indian engineering services, German industrial automation clusters, and US cloud hyperscaler infrastructure. Single-source vulnerability concentrates in specialized NETCONF/YANG modeling talent pools. Distribution runs through direct enterprise sales for large accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise infrastructure refresh cycles are recovering from procurement freezes, with telecommunications capex normalization and regulatory compliance deadlines in Europe pulling forward automation platform investments.
For Market Incumbents: Entrench through backward integration into edge-native controller silicon and captive YANG model development teams. Defend against open-source displacement by embedding compliance automation as non-negotiable features for EU AI Act adherence. Prioritize certification investment in NIS2-aligned threat detection capabilities. For New Entrants and Emerging Players: Establish a beachhead in German manufacturing automation clusters where platform engineering talent scarcity constrains incumbent response speed. Target mid-market healthcare networks with subscription-based network-as-a-service financing that eliminates upfront capital requirements. Lead with API transparency and self-implementation documentation to displace bundled professional services. For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications equipment vendors divesting non-core automation software units to focus on 5G hardware. Long-term viability hinges on cloud-native delivery architecture and multi-vendor interoperability. Watch for inflection when EU member states complete NIS2 transposition and compliance certification backlogs clear.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies YANG-modeled controllers with Kubernetes orchestration for heterogeneous vendor estates. |
| Strategic Partnership | Links AI inference providers with edge hardware manufacturers for real-time traffic engineering. |
| Acquisition of Specialist Firm | Captures NETCONF expertise and YANG modeling talent scarce in broader labor markets. |
| Geographic Expansion | Establishes localized compliance engineering for EU AI Act and NIS2 Directive variations. |
| Product Launch | Introduces subscription-tiered SaaS controllers displacing perpetual licensing in distributed networks. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with network engineering directors, automation platform product managers, telecommunications procurement officers, and EU regulatory compliance leads; and secondary validation through FCC reliability filings, EU AI Act implementation guidance, ENISA NIS2 transposition tracking, hyperscaler capex disclosures, and telecommunications equipment vendor SEC filings. Bottom-up node deployment estimates triangulated against top-down infrastructure spending projections.
Forecast inputs incorporated deployment model segmentation across on-premises controllers, cloud-delivered SaaS, and hybrid architectures, plus organization size tiers and vertical adoption patterns. Growth trajectories across the projection horizon reflect modeled elasticity between regulatory compliance deadlines and infrastructure refresh cycles. Industry-specific variables included 5G transport network buildout schedules and industrial automation cluster expansion timelines.
Sensitivities concentrate around EU member state NIS2 transposition timing, AI chip export control expansion, and telecommunications capex volatility. Forecasts assume stable regulatory interpretation and continued cloud migration momentum. Material shifts in EU AI Act enforcement stringency or semiconductor supply availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Micro Fulfillment Market
Automation
Global Automated Liquid Handlers Market
Automation
Italy Marketing Automation Market
Automation
Global Warehouse Barcode System Market
Automation
Global Door and Window Automation Market
Automation
Home Automation Market
Automation
Digital Process Automation Market
Automation
Recruiting Automation Software Market
Automation
Automation Lifecycle Services Market
Automation
United States Laboratory Automation Market
Automation
Global Database Automation Systems Market
Automation
Automated Cell Block Systems Market
Automation
Middle East and Africa Workforce Management Market
Automation
Hyperautomation Market
Automation
Computer Numerical Control Market
Automation
Distribution Automation Solutions Market