
 Italy Marketing Automation Software Market | 2026-2036
Italy Marketing Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Marketing Automation Software Market Foresight
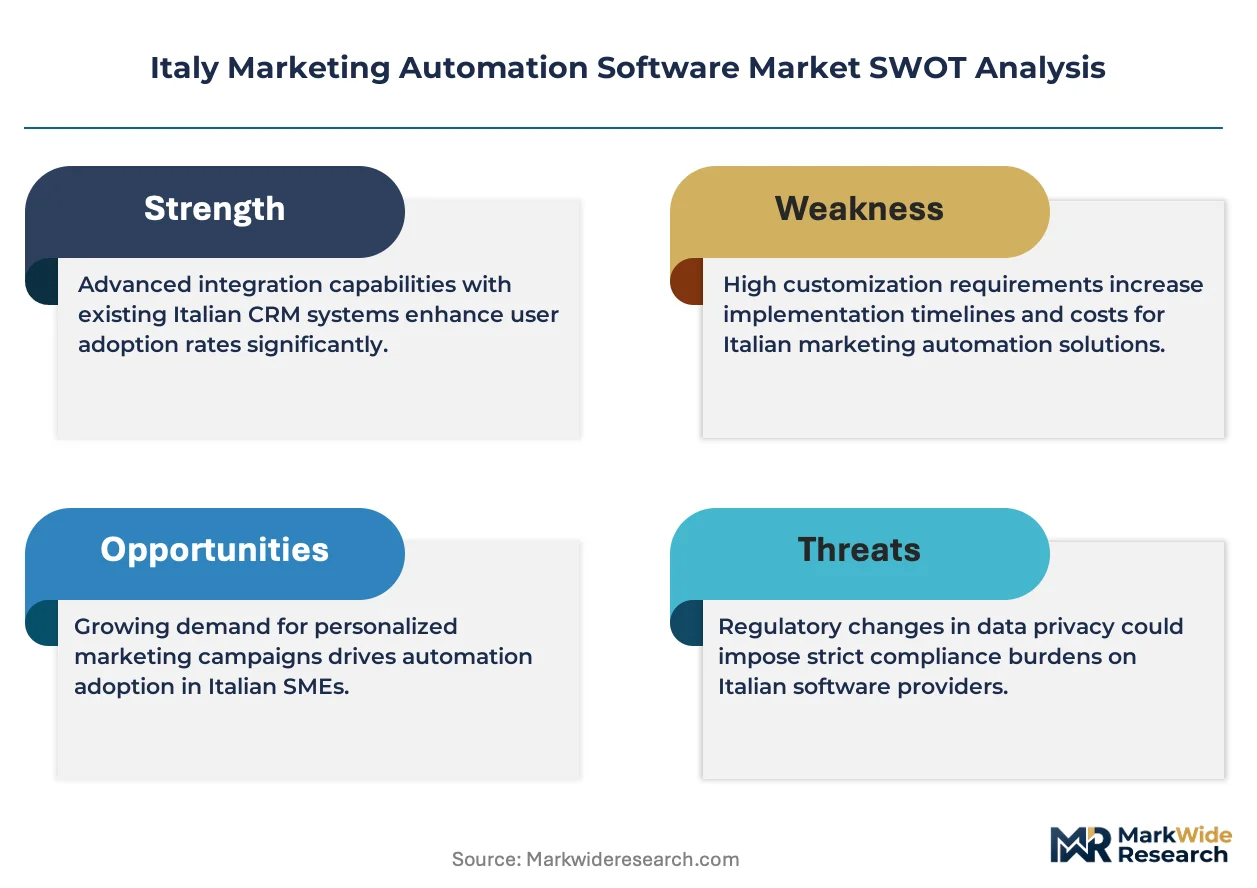
Milan's fintech corridor is rewriting how Italian enterprises evaluate automation procurement. HubSpot leverages its inbound methodology to anchor mid-market SaaS budgets across Northern Italy. Salesforce sustains enterprise dominance through CRM-native workflow depth. Contactlab competes with specialized email orchestration for luxury fashion houses headquartered in Lombardy.
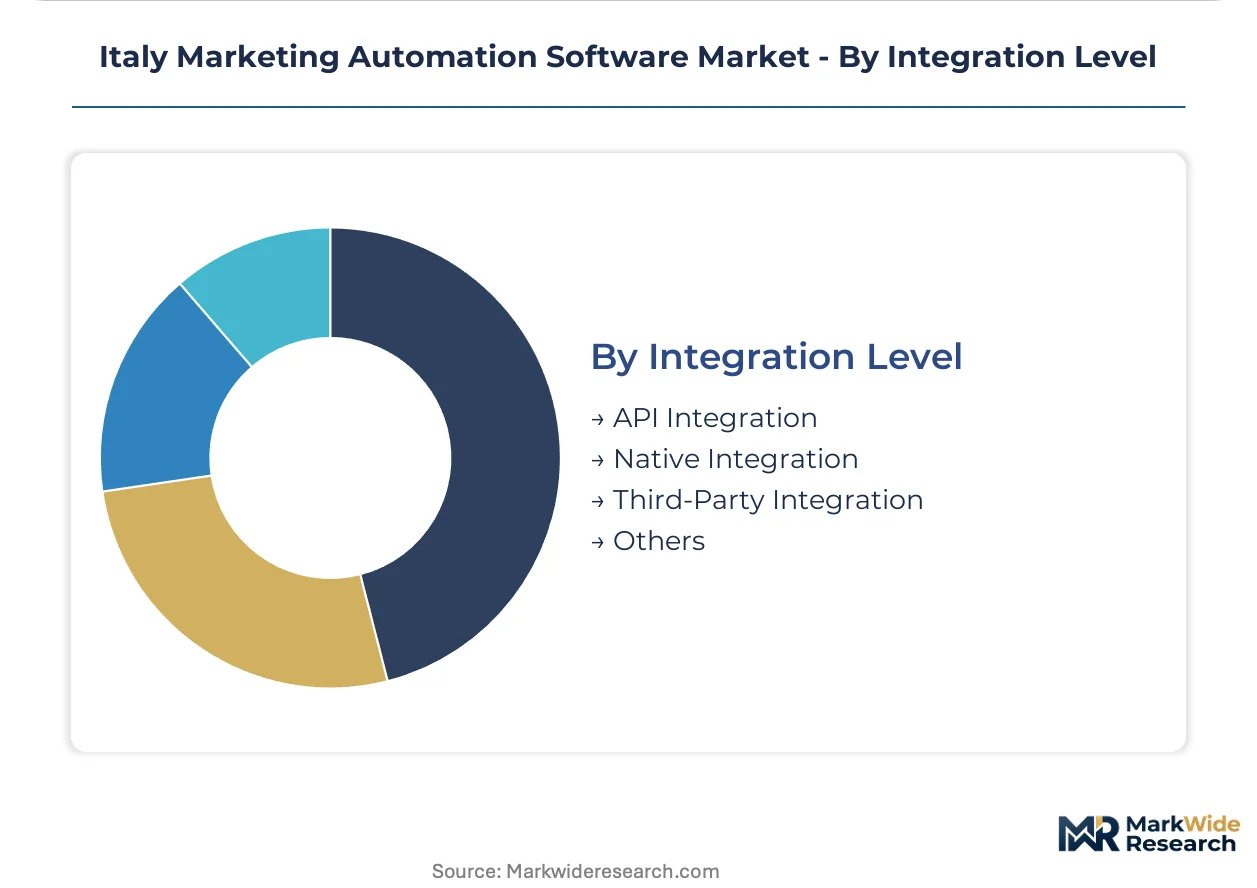
Marketing automation software comprises platforms that execute, measure, and optimize repetitive marketing tasks through rule-based triggers, machine learning scoring models, and multi-channel campaign orchestration. These systems integrate customer data platforms with execution layers across email, web, mobile, and advertising channels to deliver personalized messaging at scale. Campaign Management leads solution-type revenue as CPG and automotive brands demand cross-channel consistency. Cloud-Based deployment absorbs the fastest growth trajectory as GDPR-mandated data residency solutions mature within EU sovereign cloud frameworks. API Integration captures concentrated margin pools where enterprises stitch fragmented martech stacks into unified customer data infrastructures.
Italy's Data Protection Authority enforces GDPR Article 25 data-protection-by-design mandates that shape vendor architectural requirements. The EU AI Act's risk-classification framework for automated decision-making imposes audit obligations on lead-scoring and predictive segmentation deployments. Stakeholders must monitor how Italy's transposition of the Digital Services Act reshapes consent management and third-party cookie deprecation timelines.
Market Dynamics
The EU AI Act's risk-classification framework for automated decision-making is compressing vendor development cycles and forcing architectural redesigns across Italian marketing automation deployments.
Growth Catalysts
- GDPR Article 25 mandates:Italy's Data Protection Authority enforces data-protection-by-design requirements that push enterprises toward compliant automation platforms with native consent management.
- Lombardy manufacturing corridor:Mid-market industrial firms concentrated in the Milan-Turin axis are consolidating martech procurement around integrated customer data platforms.
- Lead-scoring algorithm adoption:Italian retail banks are deploying machine learning scoring models to automate credit product cross-selling workflows.
Market Restraints
- EU sovereign cloud infrastructure costs:GDPR-mandated data residency requirements impose premium pricing on cloud-based deployment architectures versus standard global hosting.
- Third-party cookie deprecation timeline uncertainty:Italy's transposition of the Digital Services Act creates compliance friction around consent management system investments.
- Technical debt in legacy CRM integrations:Fragmented martech stacks at established enterprises resist API-based unification without substantial middleware investment.
Strategic Opportunities
- Central and Southern Italy underpenetration:Marketing automation adoption remains concentrated in Northern industrial zones, leaving Rome-Naples corridor enterprises as expansion targets.
- Predictive segmentation convergence:Integration of generative AI content engines with existing automation workflows opens new personalization depth for luxury fashion verticals.
- CSRD reporting alignment:The EU Corporate Sustainability Reporting Directive creates demand for automation platforms that track and document marketing carbon footprint metrics.
Industry Challenges
- Machine learning operations talent scarcity:Italian enterprises face recruitment gaps for specialists capable of maintaining compliant AI-driven scoring models under EU AI Act audit requirements.
- Cross-border data flow certification complexity:Adequacy decisions between Italy and non-EU jurisdictions fragment campaign orchestration for multinational brands headquartered in Lombardy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Marketing Automation Software Market |
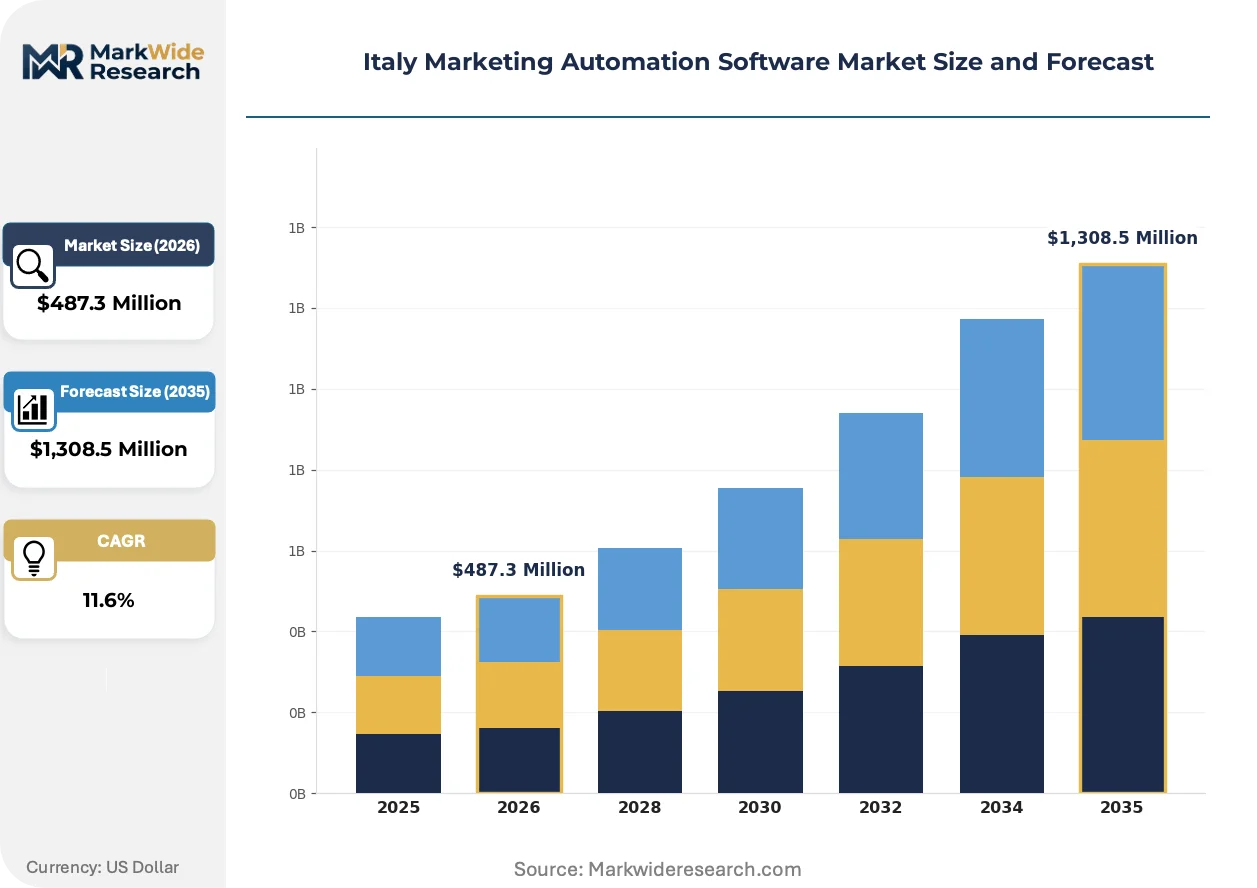
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Campaign Management, Lead Management, Email Marketing, Analytics End User: SMEs, Large Enterprises, B2B Companies, E-commerce Deployment Model: Cloud-Based, On-Premises, Hybrid, Federated Integration Level: API Integration, Native Integration, Third-Party Integration, Others |
| Companies Covered | Marketo, Contactlab, HubSpot, Adabra, SALESmanago, Adobe, Salesforce, ClickDimensions, ActiveCampaign, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Marketing Automation Software Market Shifts & Advancements
Consent-first automation architectures are displacing legacy tracking-dependent campaign models across Italian enterprise deployments.
Real-time customer data platforms with embedded identity resolution are rendering obsolete batch-processed segmentation workflows that rely on delayed data warehouse refreshes. Mid-market B2B manufacturers in Emilia-Romagna are adopting these systems at accelerated pace. The shift is compressing campaign launch timelines from weeks to hours and collapsing the competitive advantage of established email service providers.
Italy's transposition of the Digital Services Act is reshaping third-party data sourcing practices for marketing automation vendors. The regulation's strengthened consent requirements are forcing platform providers to rebuild audience targeting modules around first-party data capture. Luxury fashion houses headquartered in Milan are responding fastest, investing in zero-party data collection interfaces that bypass deprecating cookie infrastructure.
Buyer committees at Italian enterprises are consolidating vendor relationships around full-stack automation suites rather than point solutions. Specialized email orchestration providers are losing standalone procurement cycles to integrated platform vendors. This concentration is most visible among automotive and CPG brands with centralized procurement functions in Turin and Milan.
Italy Marketing Automation Software Market Segmentation
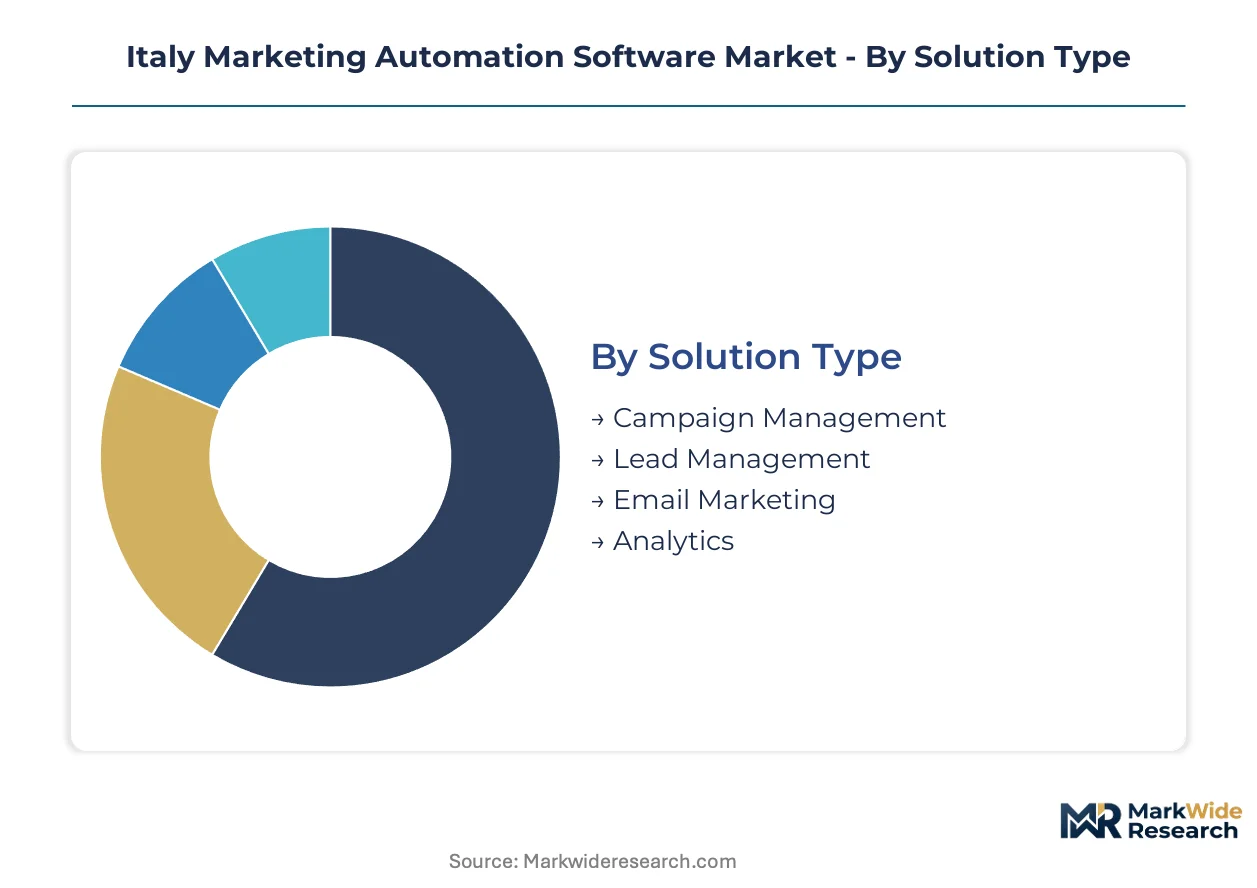
Marketing automation procurement in Italy fragments across organizational scale, technical architecture, and integration complexity. Vendors must align platform capabilities with GDPR-mandated data residency, EU AI Act audit requirements, and the concentrated industrial demand geography of Northern Italy.
Solution Type:
Italian enterprises deploy automation modules across a spectrum from campaign orchestration to predictive analytics, with procurement decisions tied to vertical-specific workflow requirements.
- Campaign Management:Cross-channel orchestration platforms coordinate messaging across email, mobile, web, and advertising touchpoints. CPG and automotive brands with centralized procurement in Turin and Milan prioritize these systems for brand consistency enforcement.
- Lead Management:Scoring algorithms and nurture workflows automate prospect progression through sales funnels. Italian retail banks concentrated in Lombardy deploy machine learning models here to automate credit product cross-selling under EU AI Act risk-classification protocols.
- Email Marketing:Specialized orchestration tools for batch and triggered messaging.
- Analytics:Attribution and performance measurement modules.
The dominant share belongs to Campaign Management, while Lead Management is closing the gap fastest.
End User:
Customer scale determines platform sophistication, with procurement authority residing in IT-security committees at large enterprises versus marketing directors at smaller firms.
- Large Enterprises:Multi-divisional organizations with centralized martech procurement functions. These buyers demand API-native architectures for stitching fragmented legacy stacks, with Lombardy-headquartered luxury fashion houses driving integration depth requirements.
- SMEs:Mid-market manufacturers concentrated in the Milan-Turin corridor. GDPR Article 25 compliance mandates push these firms toward cloud-native platforms with embedded consent management rather than custom-built solutions.
- B2B Companies:Industrial and professional services firms with long sales cycles.
- E-commerce:Digital-native retailers with real-time personalization requirements.
Large Enterprises command the installed base majority, though SME adoption is expanding most quickly.
Deployment Model:
Infrastructure choices reflect data sovereignty pressures, with EU sovereign cloud frameworks maturing to host sensitive customer data within jurisdictional boundaries.
- Cloud-Based:SaaS delivery with EU-based data residency guarantees. GDPR-mandated localization requirements accelerate Italian enterprise migration here, despite premium pricing versus global hosting alternatives.
- Hybrid:Split architectures with sensitive data on-premises and execution layers cloud-hosted. Banks and insurers facing EU AI Act audit obligations for automated decision-making favor this model for algorithmic transparency.
- On-Premises:Self-managed installations for maximum data control.
- Federated:Distributed data processing across multiple jurisdictions.
Cloud-Based deployment holds the leading position, while Hybrid configurations are gaining share fastest.
Integration Level:
Technical architecture choices determine how automation platforms connect with existing customer data infrastructures and legacy CRM investments.
- API Integration:REST and GraphQL connectivity for custom stack unification. Enterprises with fragmented martech investments concentrated in Emilia-Romagna manufacturing clusters prioritize this approach to collapse data silos without full platform replacement.
- Native Integration:Pre-built connectors to dominant CRM and ERP systems. Mid-market B2B manufacturers with standardized technology footprints favor these lower-friction deployment paths.
- Third-Party Integration:Middleware-dependent connectivity through integration-platform-as-a-service layers.
- Others:Custom development and legacy protocol bridges.
API Integration captures the highest-margin procurement cycles, with Native Integration climbing fastest among cost-conscious mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brenner Base Tunnel and Turin-Lyon high-speed rail corridor stitch Northern Italy into the trans-European transport network, cementing Lombardy's position as the peninsula's logistics and procurement command center.
Lombardy
Mid-market manufacturers concentrated in Milan's metropolitan zone are consolidating martech procurement around integrated customer data platforms. GDPR Article 25 enforcement by Italy's Data Protection Authority pushes these firms toward cloud-native solutions with embedded consent management. The Milan-Turin industrial corridor hosts the densest concentration of B2B SaaS buyers, with automotive and luxury fashion headquarters driving integration depth requirements.
Piedmont
Turin-based automotive brands with centralized procurement functions demand cross-channel campaign consistency across European markets. The EU AI Act's risk-classification framework for automated decision-making imposes audit obligations on lead-scoring deployments at these enterprises. Industrial clusters around Turin and Novara are migrating from legacy email service providers toward full-stack automation suites.
Emilia-Romagna
Manufacturing firms in Bologna and Modena are adopting real-time customer data platforms with embedded identity resolution. Italy's transposition of the Digital Services Act reshapes consent management investments across this industrial belt. The region's packaging machinery and automotive component suppliers represent an underpenetrated expansion target for API-native platform vendors.
Lazio
Rome-headquartered financial institutions and government contractors face complex cross-border data flow certification requirements. The EU Corporate Sustainability Reporting Directive creates demand for automation platforms that document marketing carbon footprint metrics. Public sector procurement concentrated in the capital remains slower to adopt cloud-based deployment due to sovereign data concerns.
Veneto
Fashion and eyewear manufacturers in the Vicenza-Padua corridor are investing in zero-party data collection interfaces. The region's mid-sized exporters require GDPR-compliant campaign orchestration for multi-jurisdictional customer bases. Venetian industrial districts show rising interest in predictive segmentation convergence with generative AI content engines.
Italy Marketing Automation Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The Italian market exhibits a bifurcated structure where full-suite vendors capture enterprise procurement cycles while niche players defend vertical-specific positions. Two strategic archetypes dominate: CRM-native workflow providers leveraging existing enterprise relationships, and specialized orchestration vendors serving luxury fashion and retail banking verticals. Competitive moves center on API ecosystem expansion and consent-first architectural redesigns to satisfy GDPR and EU AI Act mandates.
Among global platform vendors, Salesforce and HubSpot exemplify contrasting market positions. Salesforce occupies the enterprise integration tier with CRM-native workflow depth, while HubSpot anchors mid-market SaaS budgets through inbound methodology penetration. Contactlab represents the specialized orchestration archetype, serving Lombardy-headquartered luxury fashion houses with email-centric campaign management. Adobe and Marketo sit within the enterprise marketing cloud segment, competing on cross-channel personalization capabilities.
| Leading Market Players |
|---|
| Marketo |
| Contactlab |
| HubSpot |
| Adabra |
| SALESmanago |
| Adobe |
| Salesforce |
| ClickDimensions |
| ActiveCampaign |
| Others |
Supply & Pricing Matrix
The Brenner Base Tunnel and Turin-Lyon high-speed rail corridor compress logistics costs for cloud infrastructure hardware destined to Milan's data center cluster, concentrating supply-side leverage among EU sovereign cloud providers and amplifying price differentiation between GDPR-compliant and standard global hosting tiers for Italian marketing automation buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Italian marketing automation procurement, with differentiation anchored in GDPR certification grade and API integration depth. Premium tiers command substantial uplifts from Lombardy-headquartered luxury fashion houses requiring EU AI Act audit-ready lead-scoring architectures. Cost compression in the economy tier intensifies as mid-market manufacturers in Emilia-Romagna consolidate around native CRM integrations with lower customization requirements. SMEs concentrated in the Milan-Turin corridor exhibit the highest price sensitivity, while large enterprises with centralized procurement functions absorb premium pricing for compliance-guaranteed deployments.
Supply Chain Analysis
Contract manufacturing concentration for marketing automation hardware rests with German, Dutch, and Irish EMS providers holding EU-based server assembly capacity. Platform providers draw from Taiwan-sourced semiconductors, Netherlands-manufactured networking equipment, and Ireland-based data center infrastructure. Single-source vulnerability in EU sovereign cloud certification creates supply chain risk as only three member states currently operate fully compliant hosting frameworks. Distribution runs through direct enterprise sales teams for large accounts and value-added resellers serving mid-market manufacturers across Northern Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian marketing automation represents a service-attach opportunity where managed compliance services and ongoing EU AI Act audit support expand faster than core platform licensing as enterprises seek to outsource regulatory maintenance.
For Market Incumbents: Build switching-cost moats through deep API ecosystem expansion that embeds customer data platforms into fragmented legacy CRM stacks at Lombardy manufacturers. Defend against HubSpot's inbound methodology penetration by anchoring procurement committees with pre-built connectors to SAP and Oracle systems dominant in Italian automotive and CPG headquarters. Prioritize certification investment in Italy's Data Protection Authority pre-approved architectures to accelerate sales cycles. For New Entrants and Emerging Players: Pursue white-space expansion in the Rome-Naples corridor where public sector and financial institutions remain underpenetrated by cloud-native automation platforms. Target mid-sized exporters in Veneto's Vicenza-Padua fashion and eyewear districts with zero-party data collection interfaces that bypass deprecating cookie infrastructure. Lead with vertical-specific positioning around CSRD-aligned carbon footprint reporting modules for sustainability-conscious manufacturers. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy email service providers with entrenched relationships at Turin-based automotive brands seeking full-stack migration. Long-term viability hinges on platforms with native consent-management architectures that anticipate further Digital Services Act enforcement tightening. Monitor Italy's transposition timeline for third-party cookie deprecation as the critical inflection signal for first-party data infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Consent-First Architecture Redesign | Replatforming around GDPR Article 25 mandates captures procurement cycles at Garante-audited Lombardy enterprises. |
| EU Sovereign Cloud Partnership | Data residency guarantees with Irish, German, or French hosting providers unlock premium pricing from compliance-sensitive buyers. |
| Vertical API Ecosystem Expansion | Pre-built connectors to SAP S/4HANA and Oracle NetSuite defend against HubSpot's mid-market SaaS consolidation. |
| Predictive Segmentation Convergence | Generative AI content engine integration opens personalization depth for Milan-headquartered luxury fashion houses. |
| CSRD Reporting Module Development | Marketing carbon footprint tracking aligns with EU Corporate Sustainability Reporting Directive procurement requirements. |
Research Methodology
Cross-validation between primary interviews with CMOs, IT procurement officers, platform engineers, and integration specialists anchors the qualitative findings against secondary validation from SEC filings, hyperscaler capex disclosures, EU regulatory filings, and Italian Data Protection Authority enforcement records. Bottom-up sizing of vendor-reported deployments triangulates with top-down allocation from aggregate cloud infrastructure spending patterns across the analysis window.
Calibration against historical adoption curves in comparable EU markets shapes the projection framework across deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern dimensions. CAGRs derive from segmented growth rate reconciliation with macroeconomic indicators and regulatory enforcement timelines. Model inputs include EU AI Act risk-classification compliance costs and GDPR-mandated data residency infrastructure premiums specific to Italian enterprise procurement behavior.
The forecast holds incumbent behavior within observed patterns; aggressive platform bundling moves by CRM-native workflow providers would shift outcomes beyond modeled ranges. Quarterly review of Garante enforcement actions, EU sovereign cloud certification expansions, and third-party cookie deprecation timeline clarity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Global Field Force Automation Market
Automation
Playout Automation Market
Automation
Data Center Automation Market
Automation
Lab Automation Market
Automation
Industrial Vending Machines Market
Automation
Network Automation Market
Automation
North America Home Automation Systems Market
Automation
Micro Fulfillment Market
Automation
Global Water Automation and Instrumentation Market
Automation
Escalator Control Systems Market
Automation
Global Remote Monitoring and Control Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
United States Laboratory Automation Market
Automation
Laboratory Benchtop Automation Market
Automation
Workflow Automation Market