
 Parcel Sorting System Market | 2026-2036
Parcel Sorting System Market Size, Share, and Industry Trends Forecast 2026-2036
Parcel Sorting System Market Insights
Buyer concentration among top-tier e-commerce fulfillment networks is hardening, forcing sorting system vendors to tailor contract terms for fewer, larger accounts. Vanderlande leverages its airport baggage heritage to anchor high-throughput parcel hub designs in Europe. Honeywell Intelligrated sustains North American market presence through deep integration with warehouse execution software. Daifuku competes aggressively on robotic sortation density in Asian distribution centers.
A parcel sorting system comprises mechanized conveyor networks, diverters, scanners, and control software engineered to route packages by destination code at speeds exceeding three meters per second, serving the core commercial purpose of reducing manual handling cost and delivery error rates in high-volume shipping operations. Automated systems now dominate capital deployment as labor scarcity and throughput requirements intensify, while AI-driven sorting represents the fastest-expanding technology segment as vision-classification accuracy improves. Manual systems retain residual share in emerging markets with lower wage structures and irregular parcel profiles.
The European Union's CE marking and Machinery Directive enforce safety interlocks and electromagnetic compatibility standards that shape system design costs for any vendor accessing member states. China's SAMR and GB standards impose distinct certification pathways for domestic installation, creating regulatory fragmentation that complicates product platform strategies. The US FAA and OSHA maintain overlapping jurisdiction at air-cargo hubs where sorting equipment interfaces with tarmac operations. Stakeholders must weigh modular upgrade paths against full-system replacement timelines as energy-efficiency standards tighten across multiple jurisdictions.
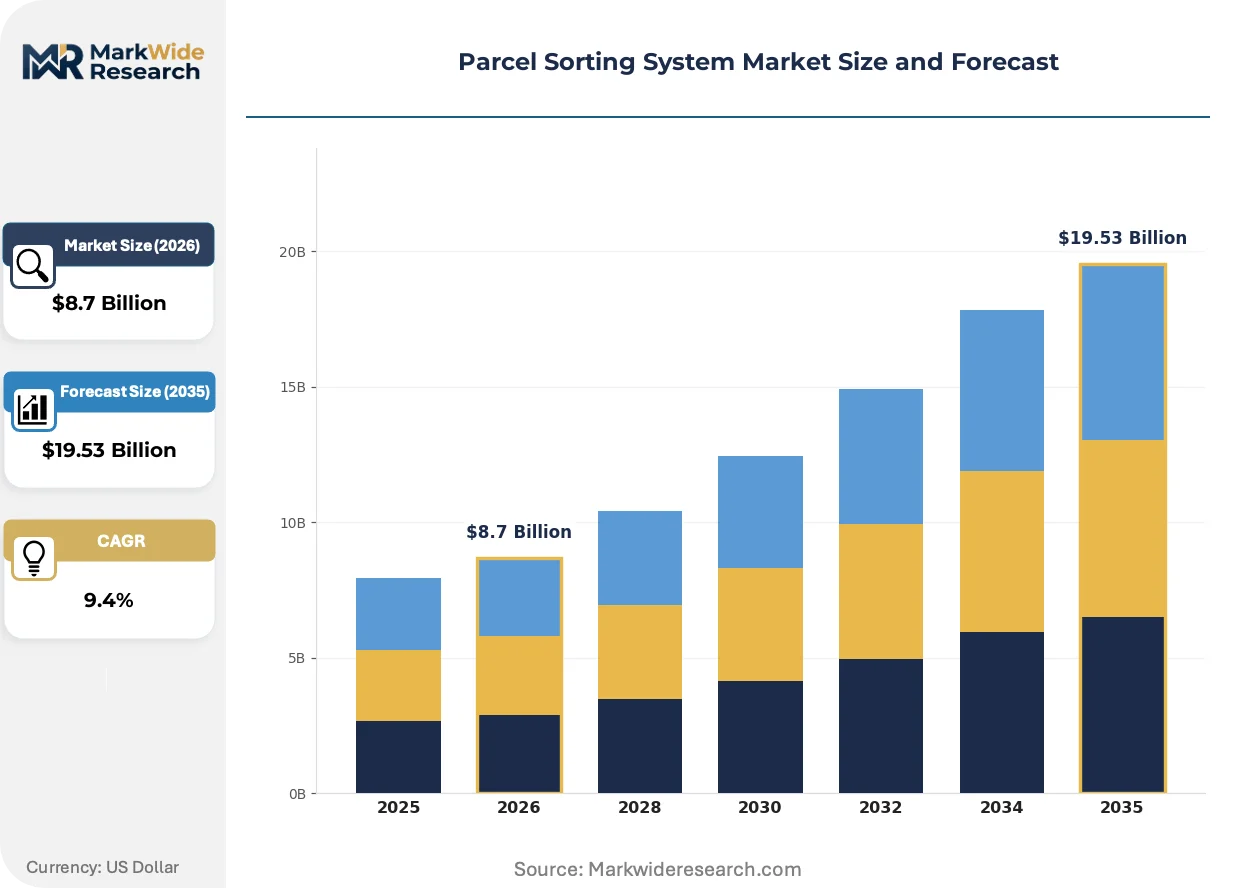
Market Dynamics
Automated sortation density is compressing hub footprints while China's SAMR accelerates domestic certification timelines, forcing vendors to choose between platform standardization and regional customization.
Growth Catalysts
- E-commerce Fulfillment Velocity Mandates:Courier networks in China now require throughput exceeding 50,000 parcels per hour at flagship hubs, driving capital deployment toward robotic sortation architectures.
- F-Gas Regulation:The European Union's phasedown of hydrofluorocarbon refrigerants in cooling systems for scanner arrays triggers retrofit demand across legacy conveyor installations in Germany and France.
- Cross-Border E-Commerce:Shein and Temu fulfillment networks are expanding automated sorting footprints in Poland and the Netherlands to meet delivery windows for European consumers.
Market Restraints
- Steel and Aluminum Input Volatility:Conveyor frame fabrication depends on commodity metals whose price swings compress vendor margins on fixed-price contracts.
- Control Software Supply Concentration:Real-time parcel routing algorithms rely on a narrow base of German and Japanese automation software houses, creating single-source risk.
- Legacy Pneumatic Diverter Obsolescence:Compressed-air actuation systems face replacement pressure from electric linear motors, stranding maintenance expertise and spare parts inventories.
Strategic Opportunities
- India Courier Network Modernization:Domestic e-commerce growth outpaces automated sorting penetration, creating white space for modular hub installations in Bangalore and Hyderabad.
- AI-Vision Classification Convergence:Machine learning parcel identification combined with dimensioning sensors enables dynamic routing without manual barcode scanning.
- EU Green Deal Funding:Energy-efficiency retrofit grants for logistics infrastructure subsidize replacement of aging belt-drive systems with regenerative motor architectures.
Industry Challenges
- Mechatronics Talent Scarcity:Integration of servo motors, vision systems, and PLC networks requires engineers with cross-disciplinary training that vocational pipelines undersupply.
- CE Marking Timeline Compression:Machinery Directive conformity assessment for multi-vendor integrated systems extends delivery schedules by four to six months.
- Legacy WCS Integration Friction:New sortation modules must interface with decades-old warehouse control software through custom middleware, inflating commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parcel Sorting System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Hybrid Systems, Software Solutions End User: E-commerce Companies, Logistics Providers, Retail Chains, Third-Party Logistics Technology: Barcode Scanning, RFID Technology, Computer Vision, AI-driven Sorting Installation Type: On-site Installation, Modular Solutions, Cloud-based Implementations, Remote Monitoring |
| Companies Covered | Vanderlande, BEUMER Group, Honeywell Intelligrated, Dematic, Interroll Group, Daifuku, Körber, Bastian Solutions, Fives Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parcel Sorting System Market Trends and Innovations
Parcel handling is pivoting from mechanical throughput maximization toward software-defined routing flexibility, with three convergent developments reshaping capital allocation and vendor positioning.
Autonomous mobile robots with parcel-carrying payloads are overtaking fixed conveyor spurs in mid-scale fulfillment centers. These AMR sortation fleets enable hub operators to reconfigure flow paths within hours rather than weeks. Amazon and JD.com deployment rates are accelerating as battery energy density improves and fleet management software matures.
REACH substance restrictions on perfluorinated compounds are forcing scanner lens manufacturers to reformulate anti-reflective coatings. Industrial consequence includes qualification delays for new optical recognition modules. Asian scanner vendors are responding fastest, accelerating domestic supply chain substitution for European coating chemistries.
Same-day delivery guarantees are compressing buyer switching cycles for sorting system vendors, with performance-based maintenance contracts displacing traditional capex-plus-service arrangements. Food and grocery delivery platforms in South Korea and the United Kingdom are driving this shift, penalizing downtime through liquidated damages clauses.
Parcel Sorting System Market Segmentation
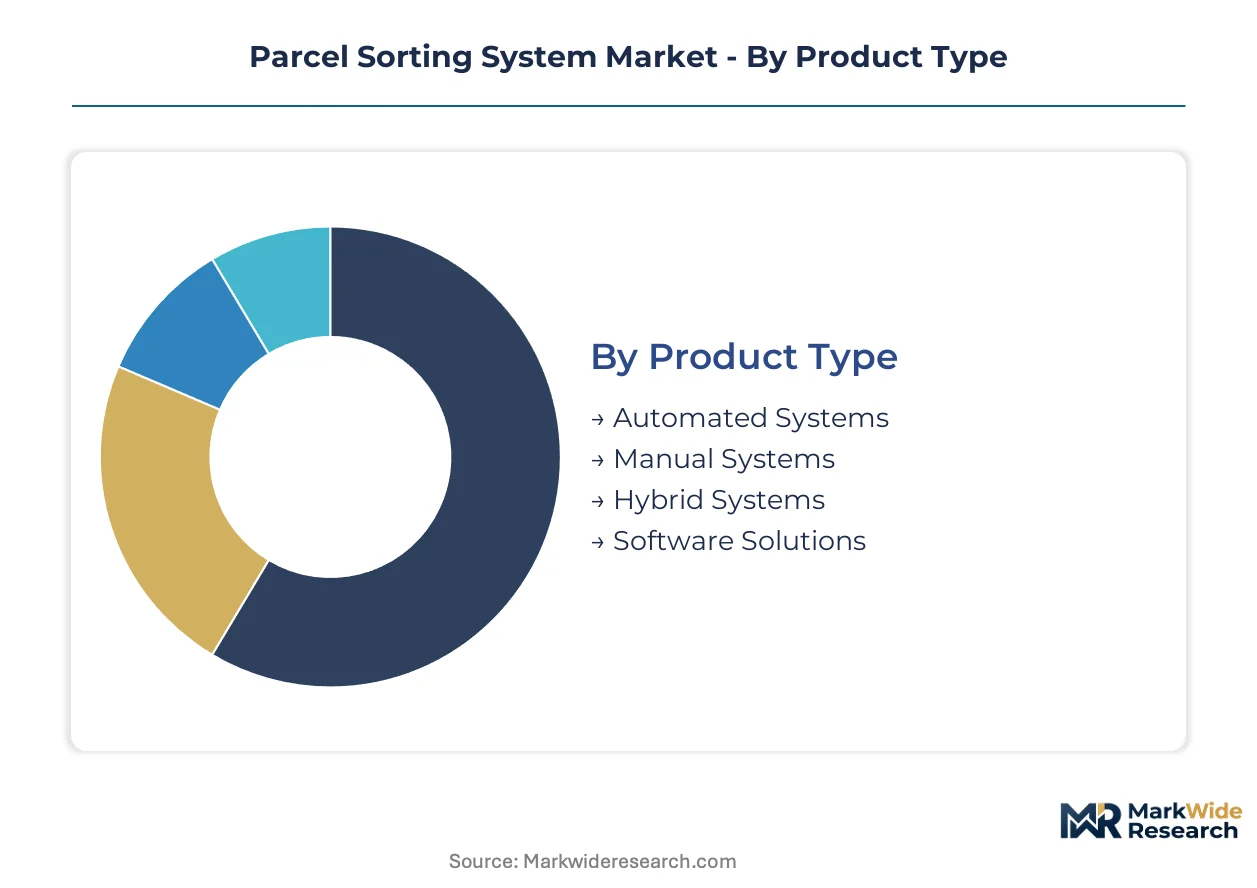
Parcel sorting system procurement patterns diverge sharply by operational scale and regulatory exposure. Buyers with high-throughput requirements prioritize capital-intensive automation, while cost-constrained operators favor modular upgrade paths that preserve legacy infrastructure.
Product Type:
Capital intensity and labor substitution rates separate procurement decisions across this category.
- Automated Systems:Robotic sortation architectures with servo-driven diverters and vision-based routing engines process parcels at velocities exceeding three meters per second. E-commerce fulfillment networks in China deploy these systems at flagship hubs exceeding fifty thousand parcels per hour, driven by delivery velocity mandates and SAMR certification timelines for domestic installation.
- Manual Systems:Human-operator-dependent configurations with basic conveyor spurs and handheld scanners retain commercial relevance in emerging markets with lower wage structures. Indian courier networks in Bangalore and Hyderabad favor these deployments where parcel profiles remain irregular and automation capital is scarce.
- Hybrid Systems:Integrated configurations blending mechanized induction with manual exception handling.
- Software Solutions:Warehouse control system modules and fleet management platforms for AMR sortation coordination.
Volume sits with Automated Systems; growth tilts toward Hybrid Systems.
End User:
Throughput requirements and in-house versus outsourced logistics strategies shape technology selection.
- E-commerce Companies:Direct-to-consumer retailers with captive fulfillment networks demand sortation density that compresses hub footprints. Shein and Temu expansion into Poland and the Netherlands drives automated sorting footprint growth to meet European delivery windows, with performance-based maintenance contracts displacing traditional capex arrangements.
- Logistics Providers:Integrated courier networks with multi-client hub operations prioritize standardization and rapid reconfiguration capability.
- Retail Chains:Omnichannel fulfillment operations balancing store replenishment with direct shipment.
- Third-Party Logistics:Contract operators serving fragmented shipper bases with variable volume profiles.
Revenue concentrates with Logistics Providers; expansion accelerates fastest among E-commerce Companies.
Technology:
Identification accuracy and integration complexity with existing warehouse control software differentiate adoption trajectories.
- AI-driven Sorting:Machine learning classification combined with dimensioning sensors enables dynamic routing without manual barcode scanning. This segment climbs the fastest as vision-classification accuracy improves and food delivery platforms in South Korea and the United Kingdom penalize downtime through liquidated damages clauses.
- Computer Vision:Optical character recognition and parcel dimensioning for non-barcoded items.
- Barcode Scanning:Laser and camera-based linear code readers for standardized parcel identification.
- RFID Technology:Radio-frequency identification for reusable container tracking and high-value shipment authentication.
Deployment scale favors Barcode Scanning; capability investment flows toward AI-driven Sorting.
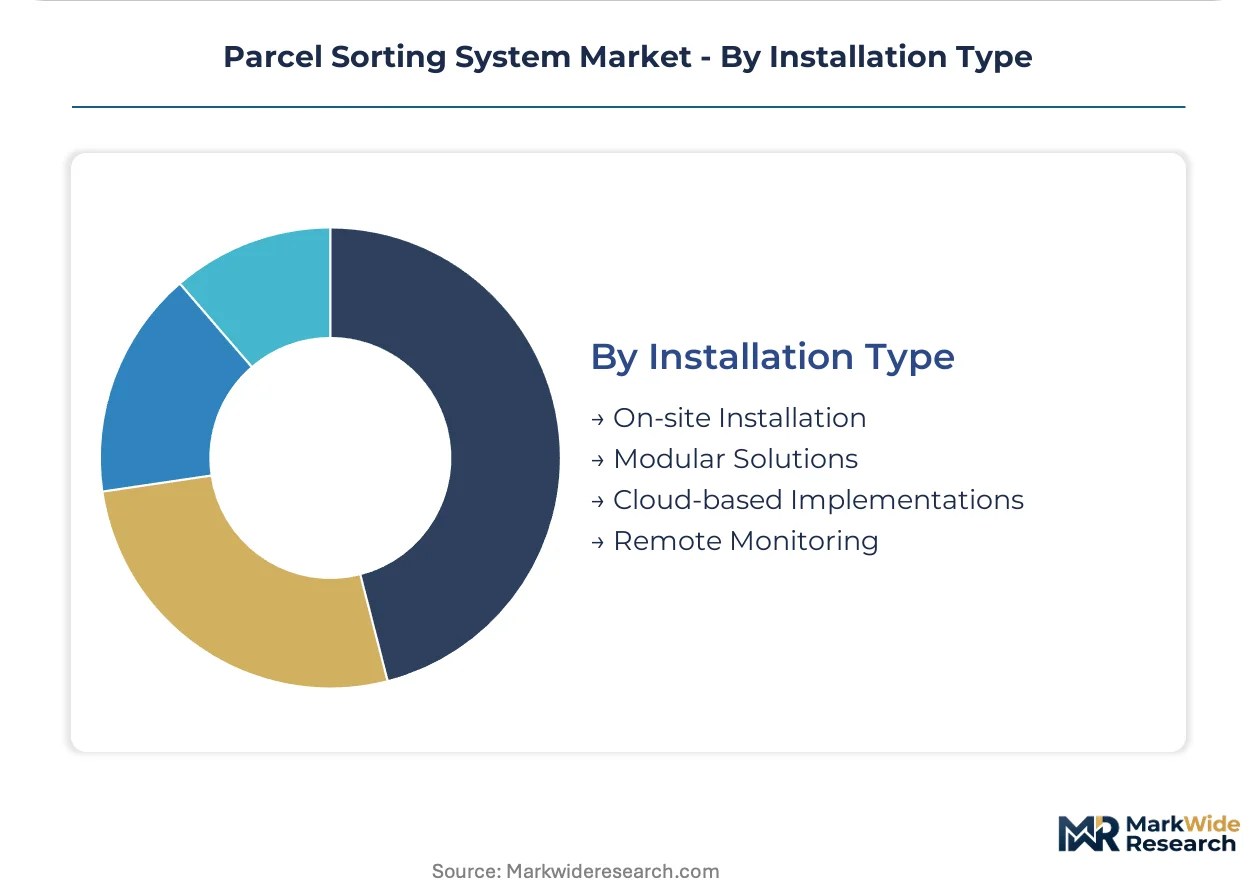
Installation Type:
Capital commitment horizon and regulatory conformity assessment timelines drive configuration choices.
- On-site Installation:Permanent fixed infrastructure with custom conveyor routing and embedded control cabinets. German and French hub operators favor these deployments where EU F-Gas Regulation retrofit requirements and CE marking under the Machinery Directive extend delivery schedules by four to six months, justifying comprehensive system replacement over modular patching.
- Modular Solutions:Pre-engineered sortation cells with standardized mechanical and electrical interfaces.
- Cloud-based Implementations:Software-defined routing with centralized algorithm updates and predictive maintenance analytics.
- Remote Monitoring:Telemetry-enabled condition monitoring for distributed equipment fleets.
Installed base accumulates in On-site Installation; flexibility demand elevates Modular Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the most acute demand strain as domestic courier volumes overwhelm existing hub capacities, while European retrofit cycles and North American warehouse automation sustain multi-regional capital deployment.
China
Flagship hubs now process over fifty thousand parcels per hour, forcing operators toward robotic sortation architectures. SAMR accelerates domestic certification timelines for automated installations. Yangtze River Delta logistics clusters around Shanghai deploy high-density systems to meet delivery velocity mandates from e-commerce platforms.
Germany
Legacy conveyor installations face replacement pressure from F-Gas Regulation phasedowns affecting scanner cooling systems. CE marking under the Machinery Directive extends delivery schedules by four to six months for integrated systems. North Rhine-Westphalia hub operators favor comprehensive replacement over modular patching to satisfy conformity assessments.
United States
Air-cargo hubs drive specialized demand where sorting equipment interfaces with tarmac operations under FAA and OSHA overlapping jurisdiction. Warehouse execution software integration shapes vendor selection criteria. Chicago and Memphis logistics corridors anchor automated footprint expansion for integrated courier networks.
India
Domestic e-commerce growth outpaces automated sorting penetration, creating white space for modular hub installations. BIS standards govern equipment certification for domestic deployment. Bangalore and Hyderabad logistics clusters favor hybrid configurations where irregular parcel profiles limit full automation.
Netherlands
Cross-border fulfillment networks from Asian e-commerce platforms expand automated sorting footprints to meet European delivery windows. EU Green Deal funding subsidizes energy-efficiency retrofits for aging belt-drive systems. Rotterdam and Venlo logistics hubs concentrate regenerative motor architecture deployments.
Parcel Sorting System Market Competitive Landscape
European producers anchor one tier; Japanese and North American specialists hold differentiated positions in software-integrated and high-throughput segments. Market structure consolidates around conglomerate-owned automation divisions with captive access to airport baggage and warehouse heritage. Three archetypes dominate: conveyor heritage players with retrofit expertise, robotics-native entrants from adjacent automation sectors, and software-anchored integrators with warehouse execution platform control. Competitive moves center on strategic partnerships for regional certification support and selective M&A to fill AMR sortation capability gaps.
Within the European heritage tier, Vanderlande and BEUMER Group occupy positions shaped by airport baggage system lineage applied to parcel hub design. Daifuku represents the robotics-native archetype competing on sortation density in Asian distribution centers. Honeywell Intelligrated anchors the software-integrated segment through warehouse execution platform relationships in North America.
| Leading Market Players |
|---|
| Vanderlande |
| BEUMER Group |
| Honeywell Intelligrated |
| Dematic |
| Interroll Group |
| Daifuku |
| Körber |
| Bastian Solutions |
| Fives Group |
| Others |
Pricing and Supply Chain Analysis
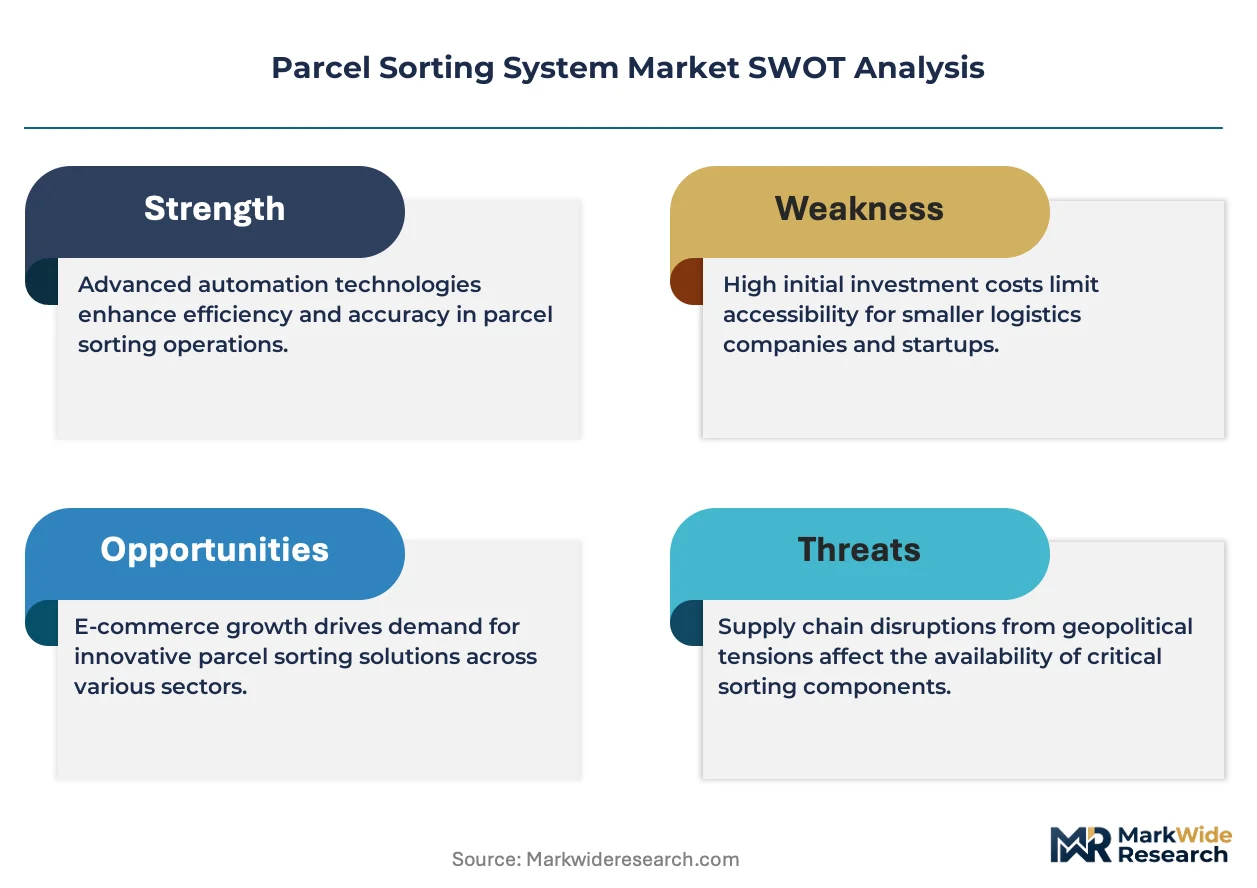
Steel and aluminum frame fabrication costs cascade through three distinct pricing tiers, with commodity metal volatility compressing margins on fixed-price contracts for European conveyor retrofits while regenerative motor architectures command premium positioning under EU Green Deal subsidy eligibility.
Pricing Analysis
Volume concentrates with standardized belt-drive systems while margins accrue to AI-vision modules with dynamic routing capability. Price differentiation separates CE-marked integrated systems from modular retrofit cells. Cost compression in pneumatic-actuated legacy tiers intensifies because electric linear motor substitution accelerates. Third-party logistics operators exhibit highest price sensitivity; e-commerce fulfillment networks with liquidated damages clauses prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese automation software houses supplying real-time parcel routing algorithms. Control system fabrication draws from Germany, Japan, and South Korea. Conveyor frame production rests on Chinese steel mills and European aluminum processors. Tariff exposure on servo motors from Japan threatens margin stability. Distribution runs through OEM-direct project contracting with multi-year installation horizons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parcel sorting is transitioning from mechanical throughput architectures toward software-defined routing flexibility, with autonomous mobile robot fleets displacing fixed conveyor spurs in mid-scale fulfillment centers.
For Market Incumbents: Hedge pneumatic diverter obsolescence through accelerated electric linear motor adoption in European retrofit pipelines. Anchor control software relationships against German and Japanese automation houses to defend routing algorithm access. Prioritize CE marking pre-certification to compress Machinery Directive conformity timelines. For New Entrants and Emerging Players: Capture white space in Indian modular hub installations where BIS certification pathways favor domestic-foreign joint ventures. Target Bangalore and Hyderabad logistics clusters with hybrid configurations addressing irregular parcel profiles. Lead with AMR sortation fleet management software to bypass capital-intensive conveyor manufacturing. For Investors and Strategic Acquirers: Distressed-cycle entries favor robotics-native specialists with Asian distribution center penetration. Long-term viability hinges on AI-vision classification convergence replacing barcode dependency. Watch Shein and Temu fulfillment network expansion rates as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| AMR Fleet Management Platform Launch | Enables hub operators to reconfigure flow paths within hours rather than weeks. |
| Backward Integration into Servo Motor Production | Reduces single-source exposure to Japanese and German automation component suppliers. |
| EU Green Deal Certification Pathway | Unlocks subsidy eligibility for regenerative motor architecture retrofits in Germany and France. |
| Strategic Partnership for SAMR Pre-Certification | Accelerates domestic installation timelines in Yangtze River Delta logistics clusters. |
| Acquisition of Vision Software Specialist | Fills AI-driven sortation capability gaps against robotics-native competitors in Asian markets. |
Research Methodology
Independent corroboration across hub operations directors, automation procurement leads, and aftermarket service heads underwrites the qualitative findings. Secondary validation draws from customs trade data for conveyor component imports, SEC filings of logistics infrastructure REITs, and SAMR certification disclosure databases. Bottom-up parcel volume modeling triangulates against top-down e-commerce fulfillment network capex disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include system automation level, end-user operational model, identification technology type, and installation configuration. CAGRs derive from hub throughput capacity expansion trajectories and retrofit cycle replacement rates. Forecast inputs incorporate steel and aluminum price index movements and CE marking timeline elasticity.
The model holds under stable commodity metal pricing and sustained e-commerce velocity mandates; deviation in F-Gas Regulation enforcement intensity or SAMR certification acceleration would shift replacement timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
CNC Controller Market
Automation
Global Zig-Bee Automation Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Terminal Automation Systems Market
Automation
Marketing Automation Solutions Market
Automation
Workload Scheduling and Automation Market
Automation
Distribution Automation Solutions Market
Automation
Elevator Control Market
Automation
Europe Data Center Automation Market
Automation
Data Center Automation Market
Automation
Laboratory Benchtop Automation Market
Automation
Europe Marketing Automation Software Market
Automation
Hyperautomation Market
Automation
Europe Laboratory Automation Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Intelligent Remote Terminal Unit Market