
 Middle East and Africa Workforce Management Market | 2026-2036
Middle East and Africa Workforce Management Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Workforce Management Market Insights
The shift from fragmented on-premise installations toward unified cloud-based platforms is realigning procurement patterns across the Middle East and Africa. SAP SE leverages its established enterprise resource planning footprint to bundle workforce modules with existing finance and supply chain deployments. Oracle Corporation anchors its regional position through data center investments in Riyadh and Dubai that address data residency requirements. NICE Ltd. specializes in workforce optimization for contact centers serving the Gulf's expanding banking and telecom sectors.
Workforce management encompasses software systems that automate time capture, shift scheduling, absence tracking, and labor compliance reporting across distributed employee populations. These platforms integrate biometric authentication, GPS-based clock-in verification, and real-time dashboard analytics to enforce labor regulations and optimize staffing costs. Cloud-based deployment represents the fastest-growing segment as Gulf enterprises migrate away from capital-intensive server infrastructure toward subscription models with automatic regulatory updates. The hospitality end-user category sustains strong demand in Dubai and Riyadh, where seasonal labor fluctuations and multi-property operations require sophisticated scheduling algorithms.
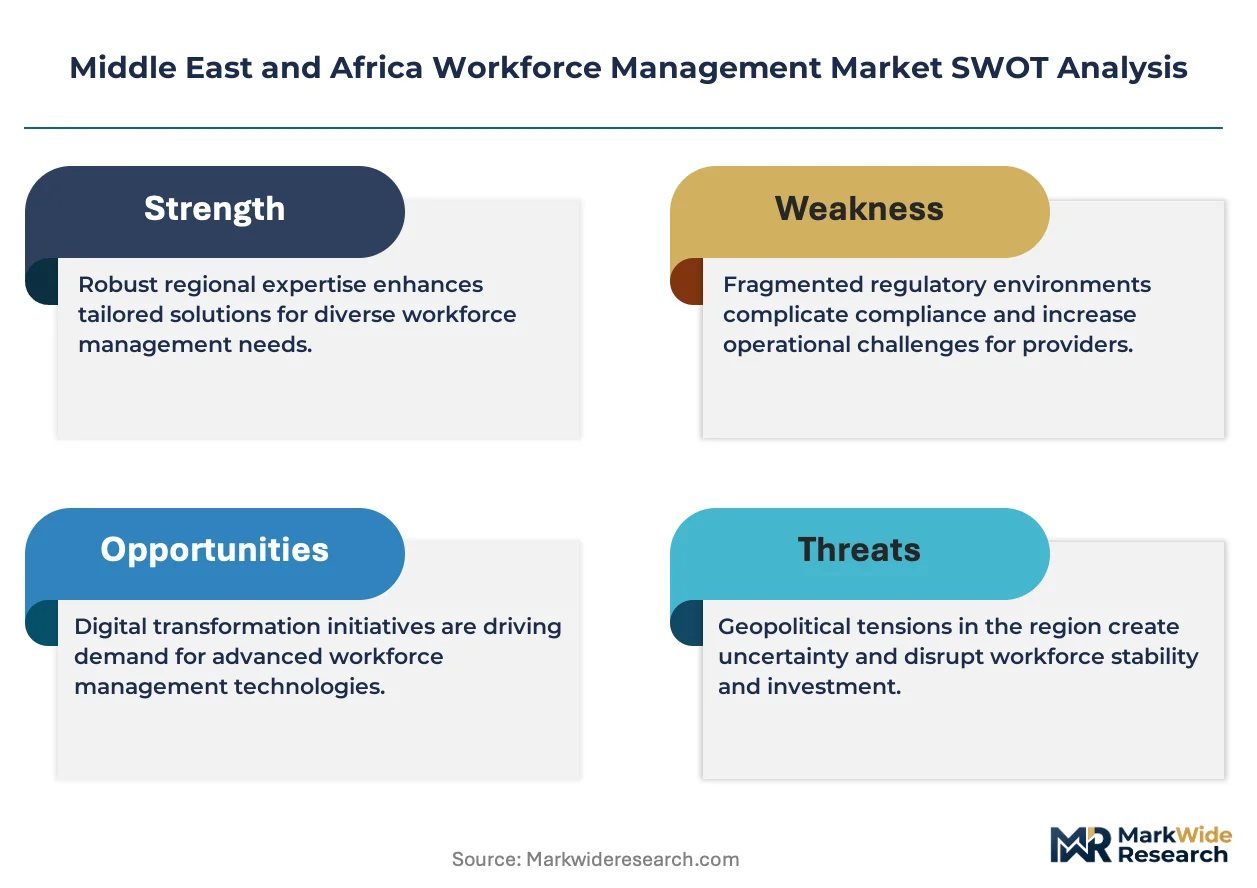
Saudi Arabia's Nitaqat quota system and the UAE's Emiratisation framework compel employers to deploy audit-ready workforce analytics that document citizen hiring ratios and wage compliance. South Africa's Protection of Personal Information Act restricts cross-border employee data flows, creating localization requirements for multinational platform providers. Organizations must evaluate whether vendor architectures accommodate Sharia-compliant payroll calculations and Gulf-specific holiday calendars before committing to long-term contracts.
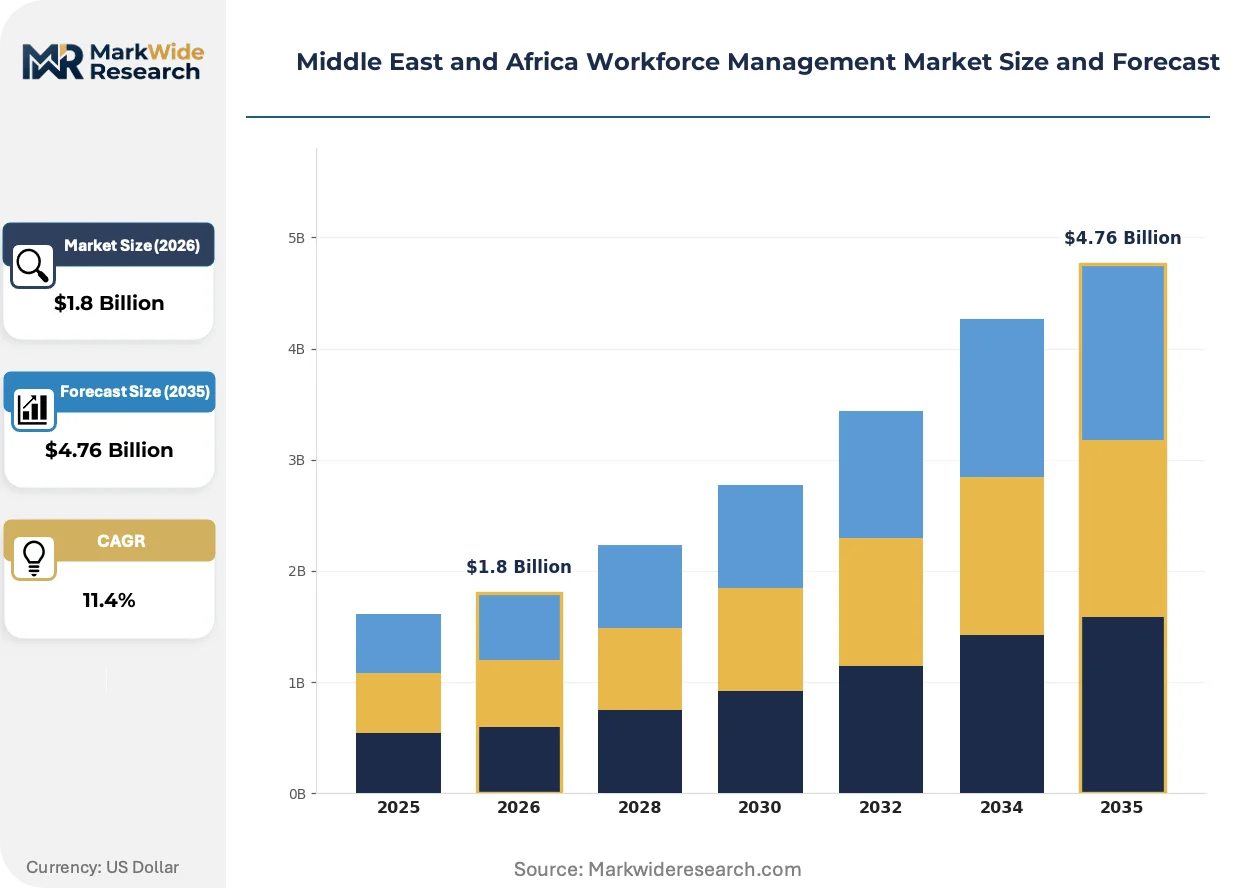
Market Dynamics
Cloud migration is compressing procurement cycles across the Middle East and Africa as Gulf enterprises abandon multi-year on-premise deployments for subscription-based platforms with embedded regulatory compliance modules.
Growth Catalysts
- Nitaqat Quota Enforcement:Saudi Arabia's citizen hiring mandates compel employers to deploy audit-ready workforce analytics that automate ratio tracking and penalty avoidance across enterprise payroll systems.
- Contact Center Expansion:Banking and telecom operators in Dubai and Riyadh are scaling workforce optimization platforms to manage seasonal volume spikes and multi-channel customer service staffing.
- Biometric Authentication:Facial recognition and fingerprint verification technologies are replacing paper-based attendance systems in Saudi public sector hospitals and UAE hospitality chains.
Market Restraints
- Data Localization Requirements:South Africa's Protection of Personal Information Act restricts cross-border employee data flows, forcing multinational vendors to establish regional data centers at substantial capital cost.
- Sharia Payroll Complexity:Gulf-specific zakat calculations and Islamic holiday calendars require platform customization that extends implementation timelines and inflates professional services fees.
- Legacy System Entrenchment:Established on-premise ERP installations in Nigerian banking and Kenyan manufacturing create switching friction that delays cloud migration decisions.
Strategic Opportunities
- Vision 2030 Public Sector Digitization:Saudi government workforce reforms are creating demand for integrated civil service management platforms spanning recruitment through retirement.
- Gig Economy Compliance:UAE and Qatar construction and logistics sectors need contractor classification tools that distinguish employees from independent workers for labor law adherence.
- AI-Enhanced Scheduling:Machine learning algorithms that predict absenteeism patterns and optimize shift coverage are penetrating under-served healthcare and retail segments in Egypt and Morocco.
Industry Challenges
- Localization Engineering Talent:Scarce Arabic-speaking software engineers capable of configuring region-specific payroll rules and regulatory reporting modules delay customer deployments.
- Interoperability with Government Portals:Integration complexity with Saudi Qiwa and UAE MOHAP employment systems requires custom API development that strains vendor delivery capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Workforce Management Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time & Attendance, Scheduling, Leave Management, Employee Self-Service Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Retail, Healthcare, Manufacturing, Hospitality Solution: Analytics, Employee Engagement, Compliance, Training |
| Companies Covered | UKG Inc., SAP SE, ADP, Inc., Oracle Corporation, Workday, Inc., Ceridian HCM, Inc., Infor, NICE Ltd., ATOSS Software AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Workforce Management Market Trends and Innovations
Workforce platforms across the Middle East and Africa are converging compliance automation with predictive analytics, transforming scheduling software from administrative tools into strategic labor optimization engines.
Unified cloud suites are consolidating time capture, absence management, and quota tracking into single-vendor architectures. Large Saudi healthcare networks and UAE hospitality groups are migrating from point solutions toward integrated platforms that eliminate data reconciliation between payroll and HR systems. This consolidation is compressing the addressable market for standalone scheduling vendors while expanding contract values for enterprise-suite providers.
Saudi Arabia's Nitaqat program and UAE Emiratisation frameworks are mandating real-time workforce ratio reporting that feeds directly into government audit portals. Employers must maintain granular visibility into citizen hiring percentages across all business units. Banking and construction sectors in Riyadh and Abu Dhabi are deploying specialized compliance dashboards that flag quota shortfalls before quarterly reporting deadlines trigger penalties.
Subscription pricing models are displacing perpetual licenses as the dominant procurement structure. Procurement teams in Dubai and Jeddah now prioritize vendors offering automatic regulatory updates and elastic user scaling over capital-intensive on-premise installations. This shift favors cloud-native providers with consumption-based pricing that aligns software costs with seasonal workforce fluctuations in hospitality and retail operations.
Middle East and Africa Workforce Management Market Segmentation
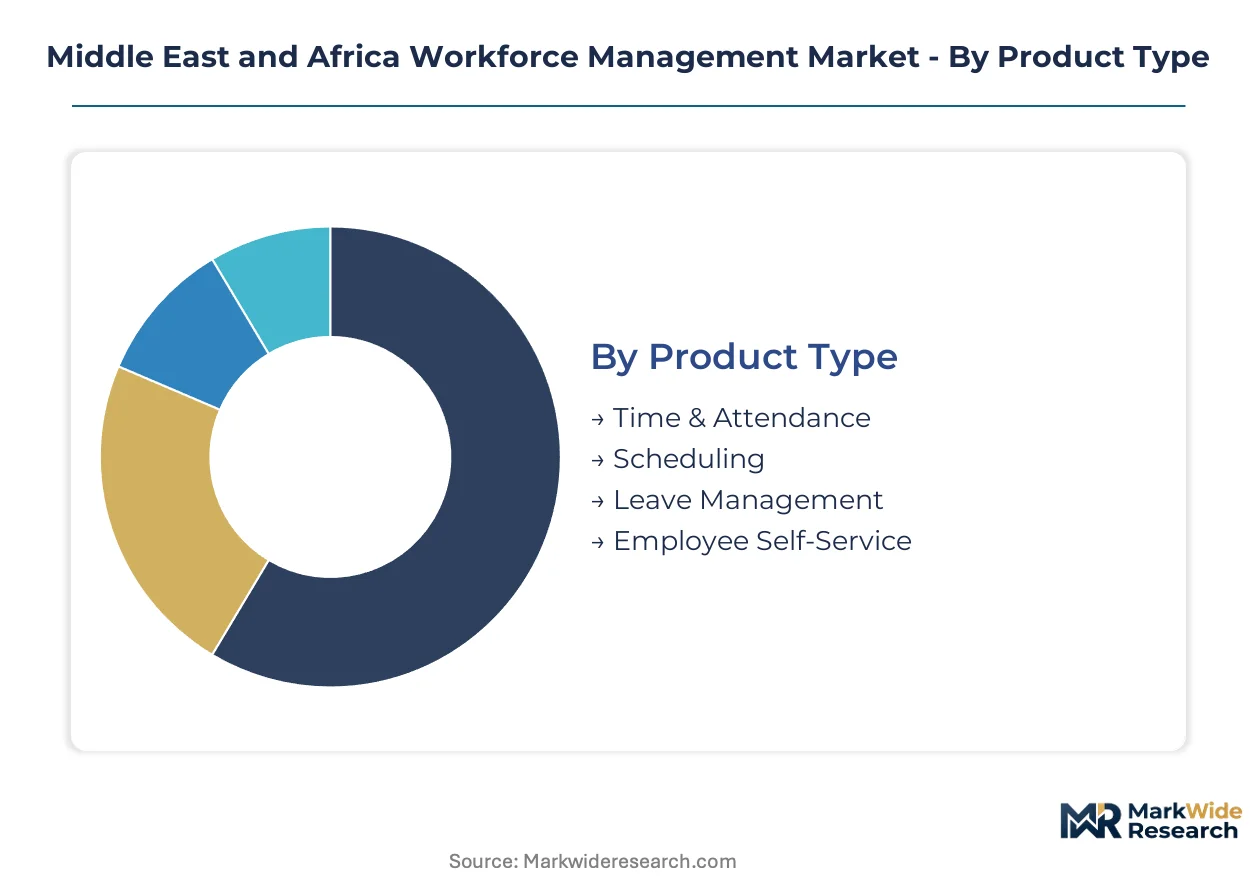
Workforce management platforms across the Middle East and Africa must navigate divergent regulatory and infrastructure requirements. Segmentation reveals which product architectures align with Saudi Nitaqat compliance mandates versus South African data localization rules.
Product Type:
Certification intensity varies sharply across product categories, with Nitaqat quota tracking and UAE Emiratisation reporting demanding government-audited validation that simpler time-capture modules do not require.
- Time & Attendance:Biometric verification systems integrate facial recognition and fingerprint authentication for Saudi public sector hospitals and UAE hospitality chains. Demand concentrates in Riyadh and Dubai, where labor law enforcement mandates tamper-proof attendance records for wage dispute resolution.
- Scheduling:AI-driven shift optimization algorithms predict absenteeism patterns across multi-property hospitality operations and seasonal retail surges. Egyptian healthcare networks and Moroccan retail chains are adopting these tools to reduce overtime costs and coverage gaps.
- Leave Management:Modules must accommodate Islamic holiday calendars and Hajj pilgrimage scheduling unique to Gulf operations.
- Employee Self-Service:Mobile-first portals enable construction and logistics workers across Qatar and UAE to access payslips and quota status without supervisor intervention.
Leading the category by volume: Time & Attendance. Growing fastest: Scheduling.
Deployment:
Cost tier stratification separates capital-intensive on-premise installations from subscription-based cloud alternatives with elastic scaling.
- Cloud-Based:Subscription models with automatic regulatory updates displace perpetual licenses across Dubai and Jeddah procurement teams. Saudi Vision 2030 public sector digitization and UAE banking compliance deadlines accelerate migration away from server infrastructure.
- On-Premise:Legacy ERP-integrated installations persist in Nigerian banking and Kenyan manufacturing where switching costs delay cloud transitions. These deployments require dedicated IT staff and hardware refresh cycles that strain mid-market budgets.
- Hybrid:Split architectures keep sensitive payroll data on local servers while pushing analytics to cloud dashboards.
- Mobile:GPS-enabled clock-in verification serves distributed construction sites and delivery fleets across the Gulf where fixed terminals are impractical.
Expanding most quickly: Cloud-Based. Retaining largest installed base: On-Premise.
End User:
Application-specific requirements drive divergent feature prioritization, from seasonal labor fluctuations in hospitality to 24/7 coverage mandates in healthcare.
- Hospitality:Multi-property operations in Dubai and Riyadh require sophisticated algorithms managing seasonal workforce surges and cross-location staffing pools. Chains integrate scheduling with guest occupancy forecasts to optimize labor costs against service standards.
- Healthcare:Saudi public sector hospitals deploy integrated platforms spanning recruitment through retirement, driven by Vision 2030 civil service reforms. Compliance with MOHAP workforce ratio requirements in UAE adds regulatory complexity.
- Retail:High-turnover environments across Cairo and Casablanca prioritize rapid onboarding and shift-swapping flexibility.
- Manufacturing:Shift-based production lines in Kenya and Nigeria need overtime tracking aligned with national labor codes and union agreements.
Capturing highest platform spend: Healthcare. Gaining share fastest: Hospitality.
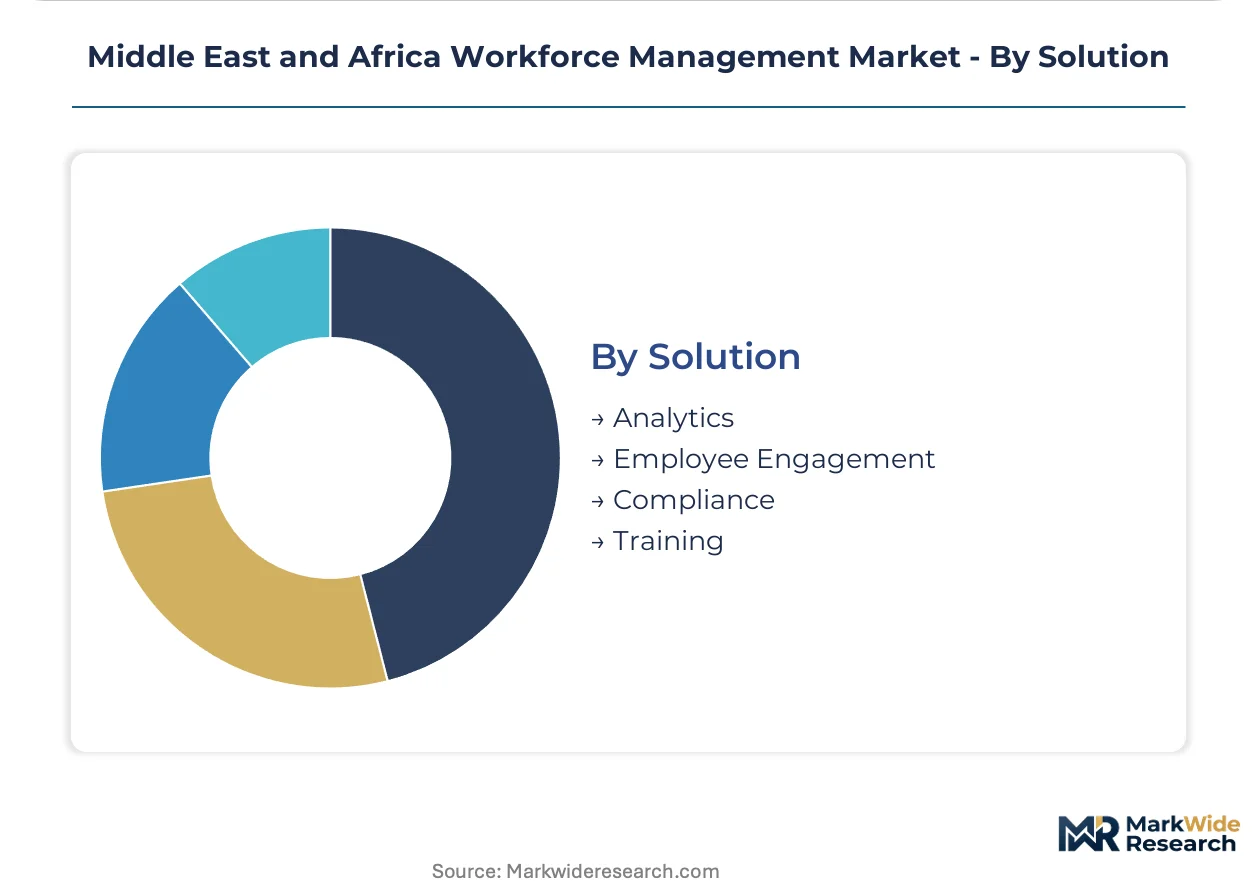
Solution:
Customer type differentiation separates enterprise buyers seeking unified suites from mid-market purchasers prioritizing point solutions with faster implementation.
- Compliance:Real-time quota dashboards automate Nitaqat ratio tracking and Emiratisation reporting for Saudi and UAE employers. Banking and construction sectors in Riyadh and Abu Dhabi deploy these tools to flag shortfalls before quarterly deadlines trigger penalties.
- Analytics:Predictive workforce planning tools forecast hiring needs and attrition risks across distributed operations. Large Saudi healthcare networks use these capabilities to align staffing with patient volume projections.
- Employee Engagement:Pulse surveys and recognition platforms address retention challenges in competitive Gulf labor markets.
- Training:Competency tracking modules support localization mandates by documenting citizen employee skill development for government audits.
Highest procurement priority: Compliance. Steepest expansion trajectory: Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oil and gas infrastructure concentration in the Eastern Province anchors Saudi Arabia's dominance in workforce platform procurement across the Middle East and Africa.
Saudi Arabia
Vision 2030 civil service reforms and Nitaqat quota enforcement drive integrated platform demand across Riyadh-based government agencies and Eastern Province petrochemical complexes. SFDA workforce regulations and Ministry of Human Resources audit requirements compel real-time citizen hiring ratio tracking. NEOM construction zones and Jeddah logistics hubs deploy biometric attendance systems for contractor compliance.
United Arab Emirates
Dubai's multi-property hospitality operations and Abu Dhabi banking contact centers sustain demand for AI-driven scheduling optimization. MOHAP Emiratisation targets and wage protection system mandates require automated quota reporting across Emirati-owned enterprises. Dubai International Financial Centre clusters and Abu Dhabi National Oil Company facilities anchor platform deployment at enterprise scale.
South Africa
Protection of Personal Information Act data localization rules and mining sector labor code complexity drive hybrid cloud-on-premise architectures. Johannesburg financial services and Cape Town manufacturing operations require POPIA-compliant workforce analytics that restrict cross-border employee data flows. Rustenburg platinum belt operations deploy overtime tracking aligned with union agreements.
Egypt
Cairo healthcare networks and Alexandria retail chains adopt predictive absenteeism algorithms to reduce coverage gaps in high-turnover environments. National labor law digitization initiatives and social insurance integration requirements reshape platform procurement priorities. Suez Canal logistics zones implement GPS-enabled workforce tracking for distributed operations.
Nigeria
Lagos banking sector legacy ERP entrenchment delays cloud migration despite rising demand for compliance automation. Central Bank of Nigeria workforce reporting standards and pension fund integration requirements complicate platform selection. Kano manufacturing clusters and Port Harcourt energy operations maintain on-premise installations due to infrastructure reliability concerns.
Middle East and Africa Workforce Management Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors align with local system integrators to navigate data residency requirements and government portal interoperability. The vendor base stratifies across three tiers: enterprise-suite providers with embedded workforce modules, specialized workforce optimization vendors, and regional system integrators offering localized implementation services. Portfolio diversification and geographic expansion through local data center investments represent the dominant competitive moves as multinational players address Saudi and South African localization mandates.
Within the enterprise-suite tier, SAP SE and Oracle Corporation exemplify platform consolidation strategies that bundle workforce modules with existing finance and supply chain deployments. UKG Inc. occupies a position among specialized workforce optimization providers serving contact center and hospitality verticals. NICE Ltd. anchors the workforce optimization segment for banking and telecom operators requiring multi-channel staffing management across Dubai and Riyadh operations.
| Leading Market Players |
|---|
| UKG Inc. |
| SAP SE |
| ADP, Inc. |
| Oracle Corporation |
| Workday, Inc. |
| Ceridian HCM, Inc. |
| Infor |
| NICE Ltd. |
| ATOSS Software AG |
| Others |
Pricing and Supply Chain Analysis
Enterprise-suite premium draws from bundled ERP integration and localized compliance engineering, while point-solution economy tiers compete on rapid deployment speed without customization depth. This bifurcation concentrates pricing power with SAP SE and Oracle Corporation in Riyadh and Dubai data center zones, while compressing margins for standalone scheduling vendors serving Egyptian retail and Moroccan healthcare mid-markets.
Pricing Analysis
Warranty and professional services bundling separates full-implementation packages from software-only subscriptions across Gulf procurement teams. Three-tier pricing structure across premium, standard, and economy levels aligns with deployment complexity: premium tiers embed Nitaqat compliance engineering and Arabic localization, standard tiers offer cloud-native scheduling without regulatory modules, and economy tiers deliver basic time-capture through mobile-first architectures. Pricing pressure stems from subscription commoditization in Egyptian and Nigerian mid-markets where cloud-native entrants undercut legacy ERP bundles. Public sector buyers in Saudi Arabia exhibit lowest price sensitivity due to Vision 2030 mandate urgency, while Kenyan manufacturing procurement teams prioritize capital preservation over feature depth.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center investments in Riyadh, Dubai, and Johannesburg zones. Software development draws from Indian engineering centers for core platform architecture and UAE-based Arabic localization specialists for regulatory module configuration. Distribution runs through regional system integrators—Saudi Technology Development and Investment Company (TAQNIA) partnerships, UAE-based Gulf Business Machines, and South African Dimension Data—rather than direct vendor sales. Single-source vulnerability concentrates in biometric hardware components sourced from Chinese and South Korean manufacturers for Saudi hospital deployments. Supply chain risk intensifies around POPIA-mandated data localization requiring Johannesburg server infrastructure that delays multinational cloud rollouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arabic-speaking compliance engineering talent scarcity props pricing for localized implementation services, constraining platform deployment velocity across Saudi and UAE public sector contracts.
For Market Incumbents: To counter cloud-native point-solution erosion in Egyptian and Moroccan mid-markets, SAP SE and Oracle Corporation should accelerate backward integration into UAE-based Arabic localization engineering capacity while embedding AI-driven scheduling modules that match standalone vendor functionality. Certification investment in Saudi SFDA and UAE MOHAP audit portal interoperability represents a critical defensive moat against modular competitors. For New Entrants and Emerging Players: Enter via under-served AI-enhanced scheduling penetration in Egyptian healthcare networks and Moroccan retail chains where incumbent ERP bundles lack predictive absenteeism algorithms. White-space concentration sits with contractor classification tools for UAE and Qatar construction logistics sectors navigating gig economy compliance mandates. Channel partnership with regional system integrators accelerates government portal integration without direct API development burden. For Investors and Strategic Acquirers: Re-rating potential sits with specialized workforce optimization vendors possessing UAE hospitality and Saudi healthcare reference architectures given accelerating cloud migration timelines. Long-term viability across the projection horizon favors platforms with embedded Nitaqat and Emiratisation compliance automation rather than generic scheduling functionality. Acquisition target archetype: mid-scale vendors with proven Saudi Qiwa portal integration and established Arabic engineering teams. Signal to watch: Saudi Ministry of Human Resources mandate expansion beyond current Nitaqat sectors into healthcare and education verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Data Center Expansion | Riyadh and Dubai hyperscaler zones address Saudi and UAE data residency mandates for workforce analytics. |
| Biometric Hardware Partnership | Chinese and South Korean facial recognition suppliers anchor tamper-proof attendance systems for Saudi hospital networks. |
| Government Portal API Integration | Saudi Qiwa and UAE MOHAP interoperability eliminates custom development delays for enterprise deployments. |
| AI-Driven Scheduling Module Launch | Predictive absenteeism algorithms penetrate Egyptian healthcare and Moroccan retail segments lacking optimization tools. |
| Regional System Integrator Alliance | TAQNIA and Gulf Business Machines channel partnerships accelerate localized implementation without direct sales overhead. |
Research Methodology
Multi-period observation of Nitaqat compliance deadline adherence, cloud migration procurement patterns, and biometric authentication deployment rates anchored the trend analysis, supplemented by interviews with Saudi Ministry of Human Resources digital transformation leads, UAE hospitality workforce operations directors, South African mining sector HR systems managers, Egyptian hospital network IT procurement officers, and Nigerian banking legacy platform engineers. Secondary validation drew from Saudi Vision 2030 progress disclosures, UAE MOHAP Emiratisation reporting statistics, South African POPIA compliance guidance documents, and hyperscaler Middle East data center capex announcements. Bottom-up platform deployment tracking across Riyadh, Dubai, Johannesburg, Cairo, and Lagos metro areas triangulated against top-down market sizing from vendor revenue disclosures and system integrator contract values.
Input-output matrices modeled deployment model transitions, end-user vertical concentration, and solution-type procurement priorities across the analysis window. Segmentation dimensions included product architecture (time-capture versus integrated suite), deployment infrastructure (cloud-native versus hybrid versus on-premise), organization scale (enterprise versus mid-market), vertical regulatory intensity (healthcare and banking versus retail and logistics), and geographic compliance framework (Saudi Nitaqat, UAE Emiratisation, South African POPIA, Egyptian labor digitization). CAGRs derived from deployment velocity curves weighted by government mandate enforcement timelines and cloud infrastructure availability. Industry-specific forecast inputs incorporated Saudi civil service reform staffing targets and UAE wage protection system expansion phases.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Saudi localization policy acceleration or South African data localization enforcement expansion. Assumptions reflect current regulatory trajectories without anticipating mandate scope extensions or bilateral data transfer agreement renegotiations. Trigger watch: Saudi Nitaqat sectoral expansion beyond private enterprise into healthcare and education, UAE Emiratisation penalty threshold adjustments, and South African POPIA cross-border enforcement precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Zig-Bee Automation Market
Automation
North America Home Automation Systems Market
Automation
Distribution Automation Solutions Market
Automation
Global Water Automation and Instrumentation Market
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
Global Automated Sample Storage Systems Market
Automation
Workload Automation Software Market
Automation
Global Door and Window Automation Market
Automation
Workload Scheduling and Automation Market
Automation
Global Form Automation Software Market
Automation
Cognitive Process Automation Market
Automation
Italy Process Orchestration Market
Automation
Process Automation Market
Automation
Data Center Automation Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Hyperautomation Market