
 Servicenow Tech Services Market | 2026-2036
Servicenow Tech Services Market Size, Share, and Industry Trends Forecast 2026-2036
Servicenow Tech Services Market Analytics
Platform implementation revenue is rewriting how IT service providers capture margin, shifting value from perpetual licenses toward ongoing configuration and optimization engagements. Deloitte leverages its enterprise consulting footprint to anchor large-scale ServiceNow deployments across regulated industries. Accenture competes through vertical specialization, embedding industry-specific workflows into platform rollouts. CloudStratex differentiates by concentrating on mid-market clients seeking rapid SaaS migration without full-scale systems integrator overhead.
ServiceNow tech services encompass the professional and managed activities required to deploy, configure, integrate, and maintain the ServiceNow enterprise cloud computing platform, which operates on a single data model architecture enabling workflow automation across IT, employee, and customer service domains. Implementation services dominate current revenue pools as organizations undertake initial platform standups, while integration services represent the fastest-expanding segment as enterprises connect ServiceNow instances with SAP, Salesforce, and legacy mainframe systems through API-led architectures. Consulting engagements around IT Departments and HR Teams command premium pricing due to complex organizational change management requirements, whereas Support services face margin compression from automated self-healing capabilities and vendor-direct customer success programs.
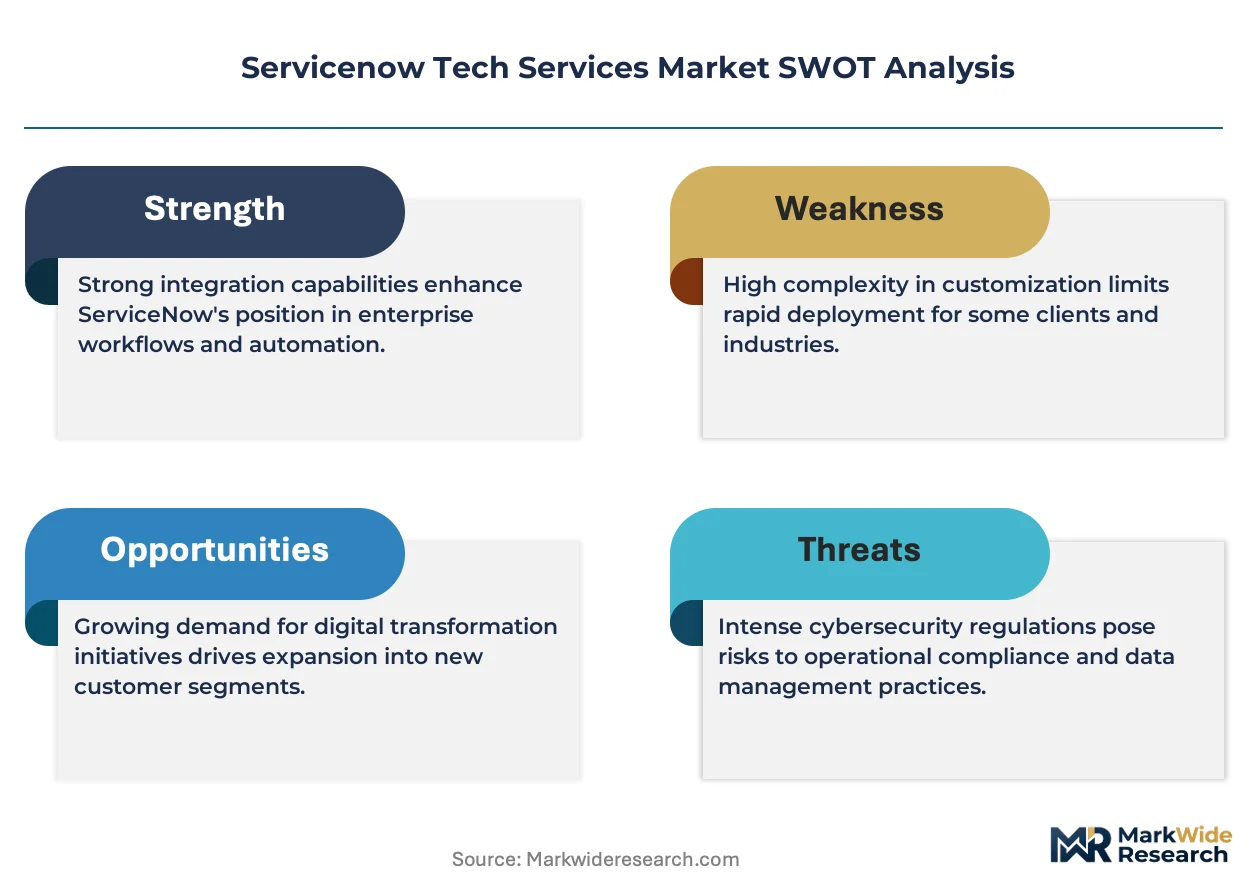
ISO 20000 IT service management standards shape platform configuration requirements across European deployments, while HIPAA security rule provisions govern how US healthcare organizations architect ServiceNow instances handling protected health information. The EU AI Act introduces new compliance layers for AI-driven predictive analytics modules within IT operations use cases, compelling service providers to build governance frameworks into implementation methodologies. Stakeholders must monitor how evolving data residency requirements across national jurisdictions affect multi-tenant cloud deployment architectures and associated professional service pricing models.
Market Dynamics
Platform revenue models are pivoting from perpetual licensing toward recurring configuration and optimization engagements as enterprises prioritize continuous workflow refinement over one-time deployments.
Growth Catalysts
- EU AI Act compliance mandates:Cloud migration requirements under the EU AI Act are forcing enterprises to modernize IT service management infrastructure, creating immediate demand for platform implementation services across regulated European industries.
- Healthcare workflow digitization:US hospitals and health systems are deploying ServiceNow instances to automate patient intake, bed management, and clinical asset tracking under HIPAA security rule governance.
- Industrial IoT integration:German automotive and machinery manufacturers require unified service orchestration across distributed production facilities, driving multi-instance platform rollouts with SAP connector architectures.
Market Restraints
- Certified architect scarcity:The limited pipeline of ServiceNow-certified technical architects constrains project velocity, extending implementation timelines and inflating day-rate premiums for qualified specialists.
- Vendor direct success programs:ServiceNow's expansion of vendor-direct customer success and automated self-healing capabilities is compressing margins for third-party support and maintenance providers.
- Legacy mainframe integration complexity:COBOL-based core banking and insurance systems resist API-led connectivity, requiring costly middleware layers that erode project ROI and delay platform value realization.
Strategic Opportunities
- Mid-market SaaS migration:Organizations with 500-5,000 employees represent an underserved segment seeking rapid cloud transition without Big Four consulting overhead, creating openings for specialized regional implementation partners.
- Predictive AIOps module expansion:IT operations teams are requesting AI-driven incident prediction and automated remediation workflows, requiring new governance frameworks that service providers can architect as premium offerings.
- Employee experience platform convergence:HR service delivery and workplace safety modules are merging with core ITSM deployments, enabling cross-functional workflow automation that commands higher engagement values.
Industry Challenges
- Organizational change management complexity:IT and HR transformation projects fail when workflow redesign neglects frontline user adoption, requiring dedicated change management specialists that most technical implementers lack.
- Multi-tenant data residency fragmentation:National data localization requirements across Germany, France, and Switzerland force architectural compromises that increase deployment complexity and compliance verification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Servicenow Tech Services Market |
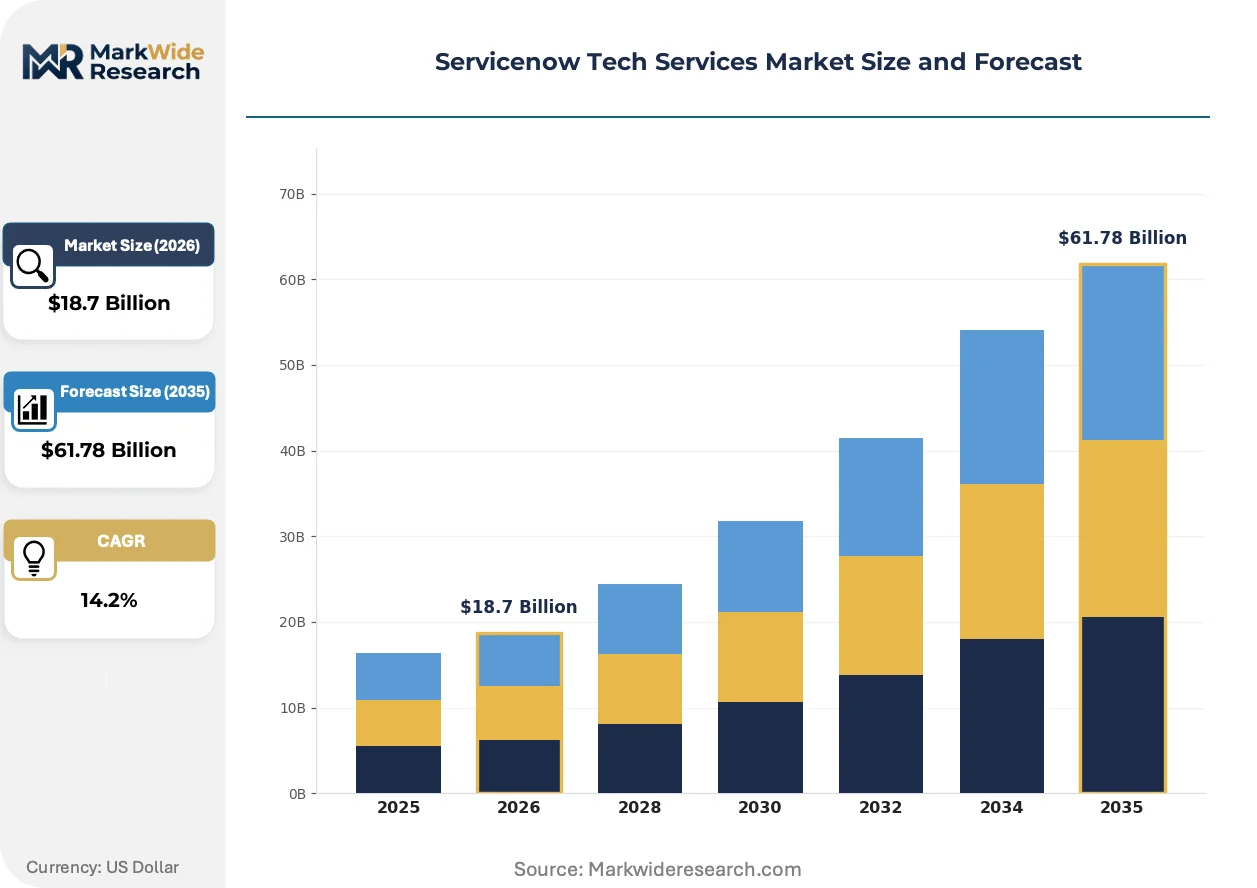
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Implementation, Integration, Consulting, Support Deployment: On-Premises, Cloud, Hybrid, SaaS End User: IT Departments, HR Teams, Finance Teams, Operations Product Type: Incident Management, Change Management, Service Catalog, Asset Management |
| Companies Covered | ServiceNow, Deloitte, CloudStratex, Tier44 Technologies, ReliaSource, CirrusPoint Solutions, Knowledge Accelerators, Plat4mation, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Servicenow Tech Services Market Evolving Landscape
Workflow automation architectures are converging with AI governance frameworks, reshaping how service providers design, deploy, and maintain enterprise platform instances across regulated industries.
Integration middleware is migrating from point-to-point connectors toward API-led composable architectures. Large manufacturers in Germany and the Netherlands are adopting MuleSoft and Boomi alongside ServiceNow to bridge SAP ERP and legacy warehouse systems. This shift is compressing traditional ETL project timelines while demanding new skill sets from implementation partners.
CSRD sustainability reporting requirements are mandating granular IT asset carbon footprint tracking across European deployments. The Corporate Sustainability Reporting Directive forces enterprises to document energy consumption by cloud instance and data center location. Financial services firms in Frankfurt and Paris are reconfiguring platform deployments to satisfy auditor traceability requirements.
Enterprise buyers are consolidating vendor relationships and demanding fixed-outcome contracts rather than time-and-materials engagements. Procurement teams at US healthcare systems and German industrial conglomerates now require milestone-based payments tied to workflow automation metrics. This compression is most visible in the US Midwest, where hospital networks have standardized on three-year platform optimization agreements with penalty clauses for missed efficiency targets.
Servicenow Tech Services Market Segmentation
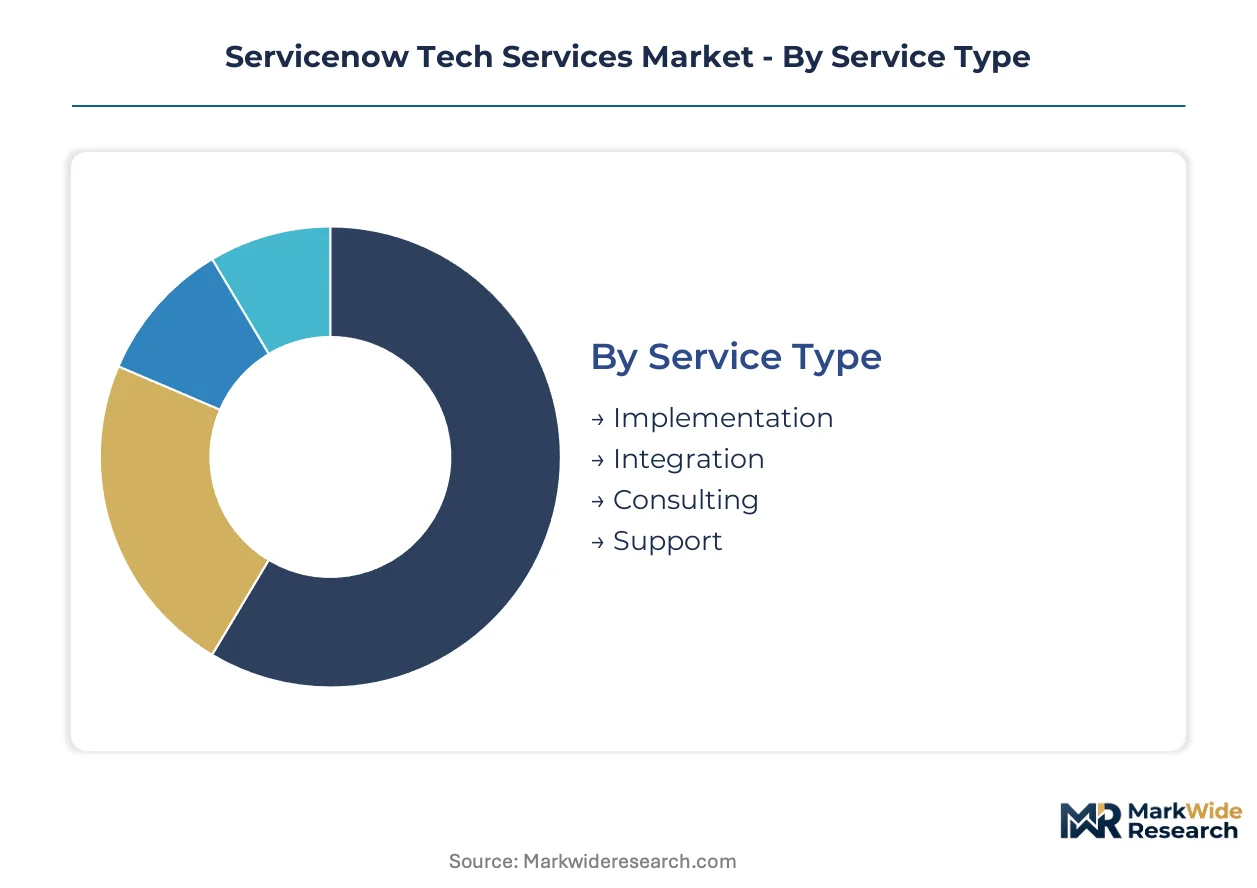
ServiceNow tech services fragment across four distinct dimensions that shape procurement patterns and margin capture. Each segmentation axis reveals how platform complexity, organizational maturity, and compliance requirements drive vendor selection and pricing structures.
Service Type:
The use-case spectrum spans initial platform standups through ongoing optimization, with each service tier commanding different pricing models and architect skill levels.
- Implementation:Initial platform configuration, instance provisioning, and workflow design for ITSM, HRSD, or CSM modules. German automotive manufacturers and US hospital networks currently concentrate demand here as they undertake foundational deployments under EU AI Act and HIPAA governance respectively.
- Integration:API-led connectivity between ServiceNow instances and SAP ERP, Salesforce CRM, or legacy mainframe systems through MuleSoft or Boomi middleware. This segment is expanding most quickly as enterprises pursue unified data architectures across distributed operations.
- Consulting:Organizational change management and process redesign engagements for IT Departments and HR Teams facing complex workflow transformation requirements.
- Support:Ongoing maintenance, patch management, and incident resolution, increasingly pressured by ServiceNow's vendor-direct customer success programs and automated self-healing capabilities.
The dominant share belongs to Implementation, while Integration is closing the gap fastest.
Deployment:
Architectural choices reflect data residency mandates, latency requirements, and existing infrastructure investments across regulated industries.
- Cloud:Multi-tenant SaaS deployments on ServiceNow data centers, preferred by mid-market organizations seeking rapid provisioning without capital expenditure. Frankfurt and Paris financial services firms are reconfiguring cloud instances to satisfy CSRD auditor traceability requirements.
- SaaS:Vendor-managed subscription instances with standardized update cycles, dominating new logo acquisition among 500-5,000 employee organizations.
- Hybrid:Split architectures retaining sensitive workloads on-premises while connecting to cloud orchestration layers, common among German industrial manufacturers with distributed production facilities.
- On-Premises:Self-managed instances in customer data centers, persisting in defense and intelligence sectors with strict air-gapping requirements.
Cloud deployments hold the largest installed base, though Hybrid configurations are gaining share fastest among European regulated industries.
End User:
Functional buyer groups determine workflow complexity, integration touchpoints, and change management intensity.
- IT Departments:Core ITSM consumers automating incident, problem, and change workflows. US healthcare systems are deploying predictive AIOps modules here under HIPAA security rule governance.
- HR Teams:Employee experience platform adopters merging service delivery with workplace safety modules, commanding premium engagement values due to cross-functional scope.
- Finance Teams:Emerging consumers of procurement and vendor management workflows, typically secondary expansion targets within existing platform estates.
- Operations:Manufacturing and supply chain users requiring integration with industrial IoT sensor networks and ERP production modules.
IT Departments anchor current revenue, yet HR Teams are expanding their platform footprint most aggressively.
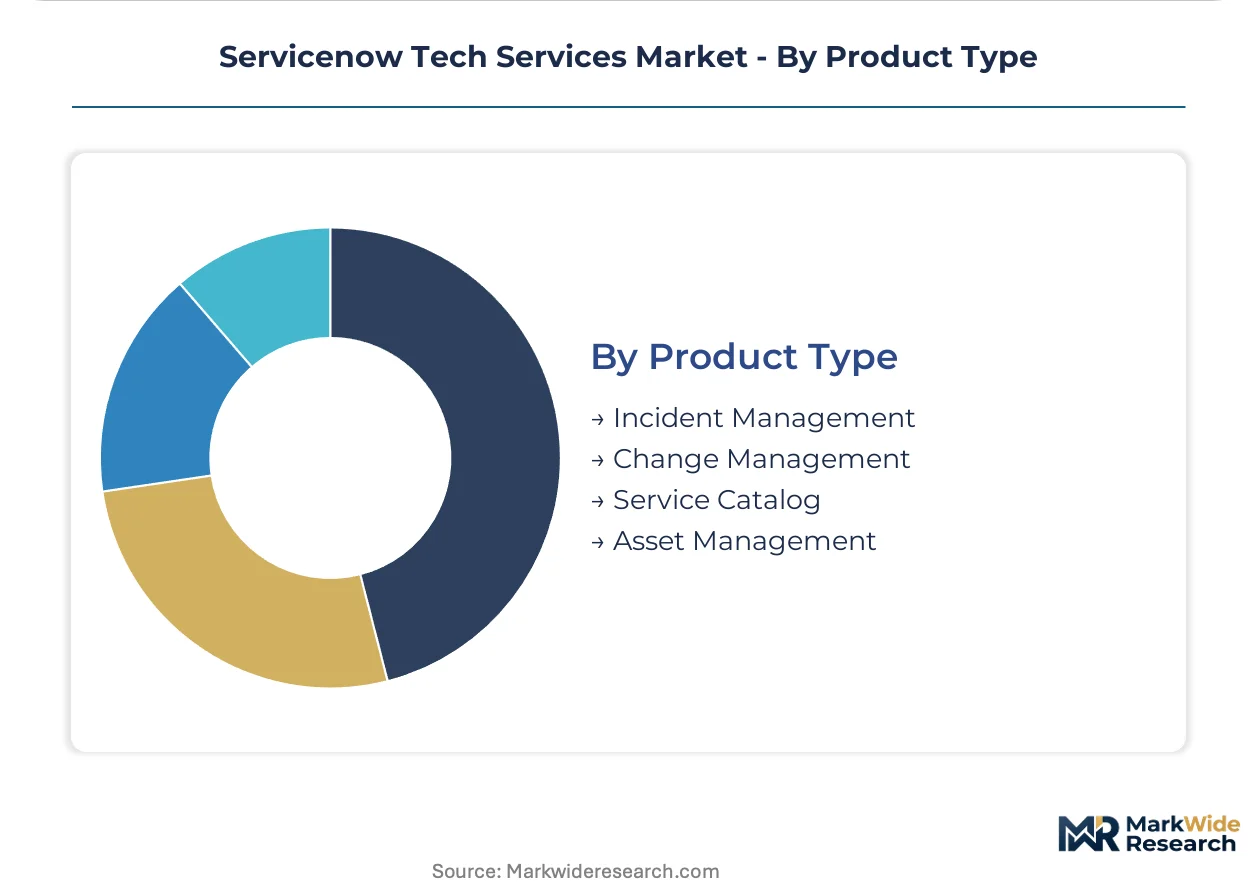
Product Type:
Module selection reveals organizational maturity and automation priorities across service delivery domains.
- Incident Management:Foundational ITSM module for ticket routing, escalation, and resolution tracking. German machinery manufacturers are layering AI-driven prediction capabilities here under EU AI Act compliance frameworks.
- Change Management:Workflow governance for IT infrastructure modifications, with demand concentrating in financial services firms facing stringent change advisory board requirements.
- Service Catalog:Self-service portals for IT and business service requests, standardizing procurement across decentralized enterprise units.
- Asset Management:Hardware and software lifecycle tracking, now extended to carbon footprint documentation for CSRD sustainability reporting mandates.
Incident Management retains the deepest penetration, while Asset Management is climbing the fastest on sustainability compliance tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare buyers in the United States exhibit the lowest price elasticity, accepting premium rates for HIPAA-compliant implementations, while mid-market manufacturers in India and Southeast Asia drive hard bargains on SaaS migration contracts.
United States
Hospital networks and health systems dominate demand as they automate patient intake and clinical asset tracking. HIPAA security rule provisions govern every architectural decision for PHI-handling instances. The Midwest hospital corridor from Chicago to Cleveland has standardized on three-year optimization agreements with penalty clauses for missed efficiency targets.
Germany
Automotive and machinery manufacturers require unified service orchestration across distributed production facilities. EU AI Act compliance mandates are forcing immediate platform modernization across regulated industries. The Stuttgart-Munich industrial belt leads multi-instance rollouts with SAP connector architectures.
United Kingdom
Financial services firms in London are reconfiguring cloud deployments to satisfy CSRD auditor traceability requirements for IT asset carbon footprint documentation. GDPR data residency rules complicate multi-tenant architectures. The City of London cluster demands fixed-outcome contracts tied to workflow automation metrics.
India
Mid-market IT services exporters with 500-5,000 employees seek rapid SaaS migration without Big Four consulting overhead. The country's national IT regulator influences data localization requirements for cloud instances. Bangalore and Hyderabad host the densest concentration of regional implementation partners competing on speed-to-deploy.
Netherlands
Logistics and maritime conglomerates pursue integration services to connect ServiceNow with warehouse management and port operations systems. CSRD sustainability reporting mandates are reshaping procurement criteria. The Rotterdam-Amsterdam corridor anchors demand for API-led composable architectures bridging legacy ERP investments.
Servicenow Tech Services Market Competitive Landscape
Global systems integrators and specialized platform boutiques split the market into distinct service tiers. The vendor base concentrates around three strategic archetypes: enterprise consultancies anchoring regulated-industry deployments, mid-market specialists competing on implementation velocity, and vendor-captive practices leveraging direct platform relationships. Dominant competitive moves include vertical workflow specialization and outcome-based contracting structures that displace time-and-materials engagements.
Within the enterprise consultancy tier, Deloitte and Accenture exemplify divergent positioning strategies—Deloitte leveraging its cross-industry footprint for large-scale regulated deployments, Accenture embedding vertical-specific workflows into platform rollouts. CloudStratex occupies a position within the mid-market specialist archetype, targeting organizations seeking rapid SaaS migration without full-scale systems integrator overhead. These three anchors illustrate how competitive differentiation is concentrating around service delivery models rather than technical capabilities alone.
| Leading Market Players |
|---|
| ServiceNow |
| Deloitte |
| CloudStratex |
| Tier44 Technologies |
| ReliaSource |
| CirrusPoint Solutions |
| Knowledge Accelerators |
| Plat4mation |
| Accenture |
| Others |
Value Network & Pricing Analysis
Bangalore's dense concentration of ServiceNow-certified technical architects feeds directly into global pricing power for implementation services, with regional labor arbitrage compressing day rates while EU AI Act compliance mandates inflate premium tiers for regulated European deployments.
Pricing Analysis
Post-implementation optimization contracts now drive lifetime value capture, with three-tier pricing structure across premium, standard, and economy levels differentiating by architect certification tier and HIPAA compliance scope. Price differentiation hinges on EU AI Act governance framework inclusion and vertical workflow customization depth. Pricing pressure stems from ServiceNow's vendor-direct customer success programs eroding third-party support margins. US hospital networks exhibit lowest price sensitivity, while Indian mid-market IT exporters negotiate aggressively on SaaS migration velocity.
Supply Chain Analysis
Tariff exposure between the United States and India dominates supply chain risk calculus for professional services delivery. Talent supply concentrates in India, Germany, and the United States, with certified architect pipelines drawing from technical universities and vendor accreditation programs. Raw material dependencies center on cloud infrastructure provisioning, proprietary training curricula, and API middleware licenses. Single-source vulnerability persists in ServiceNow's platform update cadence controlling downstream service timing. Distribution runs through direct enterprise sales, systems integrator partnerships, and regional implementation boutiques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ServiceNow tech services represent a platform-economics inflection where workflow automation interoperability with SAP ERP and Salesforce CRM ecosystems redefines competitive moats.
For Market Incumbents: Harden defensible positioning through captive certification academies in Stuttgart and Bangalore that lock architect supply chains, while embedding EU AI Act compliance frameworks as mandatory implementation modules to neutralize emerging regional competitors. Vertical integration into proprietary AIOps governance tooling creates switching costs against vendor-direct success program encroachment. For New Entrants and Emerging Players: Southeast Asian manufacturing hubs with 500-5,000 employee scale represent the most penetrable white space, where rapid SaaS migration demand outruns Big Four consulting capacity. Target predictive AIOps module rollouts as the entry wedge, positioning fixed-outcome contracts against time-and-materials incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because platform configuration engagements exhibit SaaS-like retention once embedded in client operational workflows. Acquisition targets should display mid-market velocity specialization with certified architect density. The signal to watch is CSRD sustainability reporting mandate expansion forcing asset management module upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-led connectivity with SAP ERP and Salesforce CRM commands premium implementation pricing. |
| Certification Academy Buildout | Captive architect pipelines in Bangalore and Stuttgart secure project velocity against talent scarcity. |
| Regulatory Compliance Module | EU AI Act governance frameworks embedded as standard offerings differentiate regulated-industry bids. |
| Geographic Expansion | Southeast Asian mid-market penetration captures underserved SaaS migration demand. |
| Strategic Partnership | MuleSoft and Boomi middleware alliances compress integration timelines for German manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ServiceNow platform engineers, IT procurement officers at US hospital networks, German automotive manufacturing CIOs, and regional implementation partners in Bangalore and Hyderabad. Secondary validation drew from SEC filings of systems integrators, hyperscaler capex disclosures, EU AI Act regulatory texts, and HIPAA security rule documentation. Bottom-up project pipeline analysis triangulated against top-down market sizing from vendor revenue disclosures.
Calibration across the analysis window employed segmented modeling by service type, deployment architecture, end-user function, and geographic regulatory cluster. CAGRs derived from historical implementation velocity trends, certified architect supply growth rates, and compliance mandate enforcement timelines. Integration complexity tiers and multi-tenant data residency requirements shaped regional adoption pattern inputs.
Practitioners should monitor EU AI Act enforcement granularity and ServiceNow vendor-direct program expansion for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Quality Management Software Market
Software & Services
Movie Editing Software Market
Software & Services
Data Conversion Services Market
Software & Services
Programmable Automation Controller (PAC) Programming Software Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Combat Management Systems Software Market
Software & Services
Search and Discovery Software Market
Software & Services
Applicant Tracking System (ATS) Market
Software & Services
Automotive Dealership Software Market
Software & Services
Customer Self-Service Software Market
Software & Services
Cemetery Management Software Market
Software & Services
BFSI Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
Business Activity Monitoring Software (BAM) Market
Software & Services
Europe CMMS Software Market
Software & Services
PAC Programming Software Market