
 Workload Scheduling and Automation Market | 2026-2036
Workload Scheduling and Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Workload Scheduling and Automation Market Intelligence
Mid-market enterprises with cloud-native infrastructure is unwinding the historical dominance of large financial institutions in workload automation procurement. BMC Software Inc. anchors its position through deep mainframe integration and legacy system compatibility. Stonebranch Inc. differentiates via agentless architecture and real-time data pipeline orchestration. IBM sustains relevance by leveraging its Watson AI layer for predictive failure detection in enterprise scheduling environments.
Workload scheduling and automation encompasses software platforms that orchestrate computational jobs across distributed, mainframe, and cloud resources using dependency mapping, time-based triggers, and resource-aware dispatch algorithms to ensure SLA compliance and infrastructure efficiency. Cloud-based deployment now leads technology adoption as enterprises retire on-premises job schedulers, while hybrid configurations capture the fastest expansion by bridging mainframe batch systems with Kubernetes-native workloads. Within applications, job scheduling remains the mature revenue core, whereas capacity planning functions are attracting disproportionate R&D investment as energy costs and carbon accounting tighten resource optimization requirements.
The EU AI Act, GDPR, and ISO 27001 collectively mandate explainable automation logic, data residency controls, and audit trails that reshape vendor product roadmaps and procurement criteria across European enterprises. In the United States, HIPAA and SEC cybersecurity disclosure rules extend similar compliance burdens to healthcare and financial automation deployments. Stakeholders must weigh vendor concentration risk against the interoperability demands of multi-cloud strategies as regulatory fragmentation deepens.
Market Dynamics
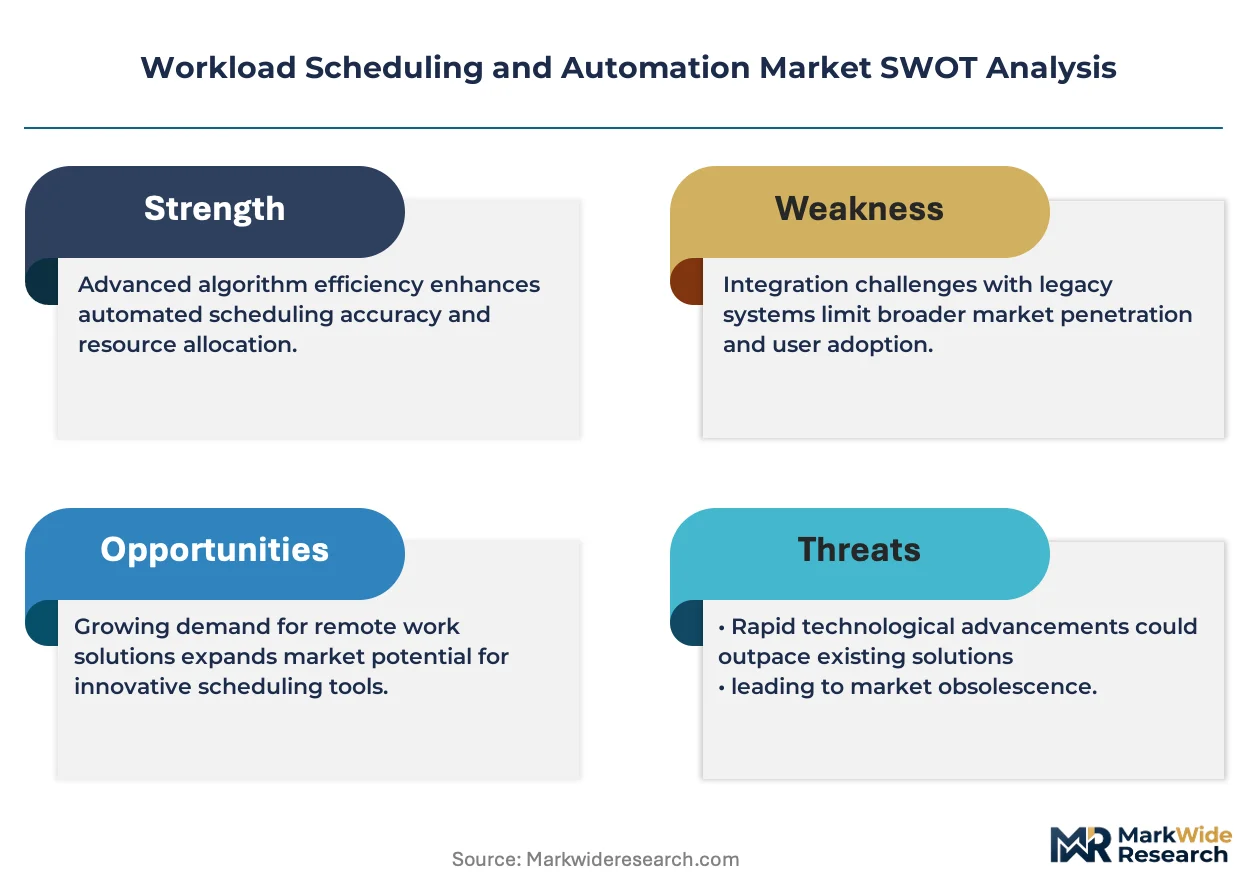
Hybrid infrastructure complexity is fragmenting procurement authority across CIO infrastructure teams and DevOps platform engineering groups, eroding the historical IT operations monopoly on workload automation purchasing decisions.
Growth Catalysts
- EU AI Act compliance mandates:Financial services and healthcare enterprises in Germany, France, and the Netherlands require auditable automation logic with explainable decision trails for algorithmic batch processing.
- Kubernetes-native workload proliferation:Container orchestration platforms now manage stateful batch jobs alongside microservices, forcing scheduler modernization across automotive and industrial manufacturing IT estates.
- Energy cost volatility:German industrial enterprises prioritize carbon-aware job scheduling to optimize compute workloads against real-time electricity pricing and grid carbon intensity signals.
Market Restraints
- Mainframe skill scarcity:COBOL and JCL expertise concentrates among retiring workforce cohorts in US and European financial institutions, constraining legacy scheduler migration velocity.
- Vendor lock-in dynamics:Deep integration with z/OS and IBMi ecosystems creates switching friction that protects incumbent positions but limits competitive pressure on pricing and innovation.
- Hybrid security perimeter expansion:Attack surface complexity across on-premises, private cloud, and multi-public-cloud deployments elevates cyber insurance premiums and compliance audit costs.
Strategic Opportunities
- Carbon accounting integration:CSRD reporting requirements position workload automation platforms as foundational infrastructure for Scope 3 emissions tracking and reduction verification.
- India manufacturing automation:PLI scheme beneficiaries in electronics and automotive assembly are greenfield-deploying cloud-native schedulers without mainframe technical debt.
- FinOps convergence:Real-time cloud cost optimization is merging with job scheduling functions, creating unified platforms that appeal to platform engineering budgets.
Industry Challenges
- Observability toolchain sprawl:Integration complexity between workload automation, APM, and SIEM platforms strains SRE team capacity and extends incident mean-time-to-resolution.
- Cross-functional alignment friction:DevOps teams prioritizing GitOps-native pipelines clash with enterprise architects mandating centralized policy governance and audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workload Scheduling and Automation Market |
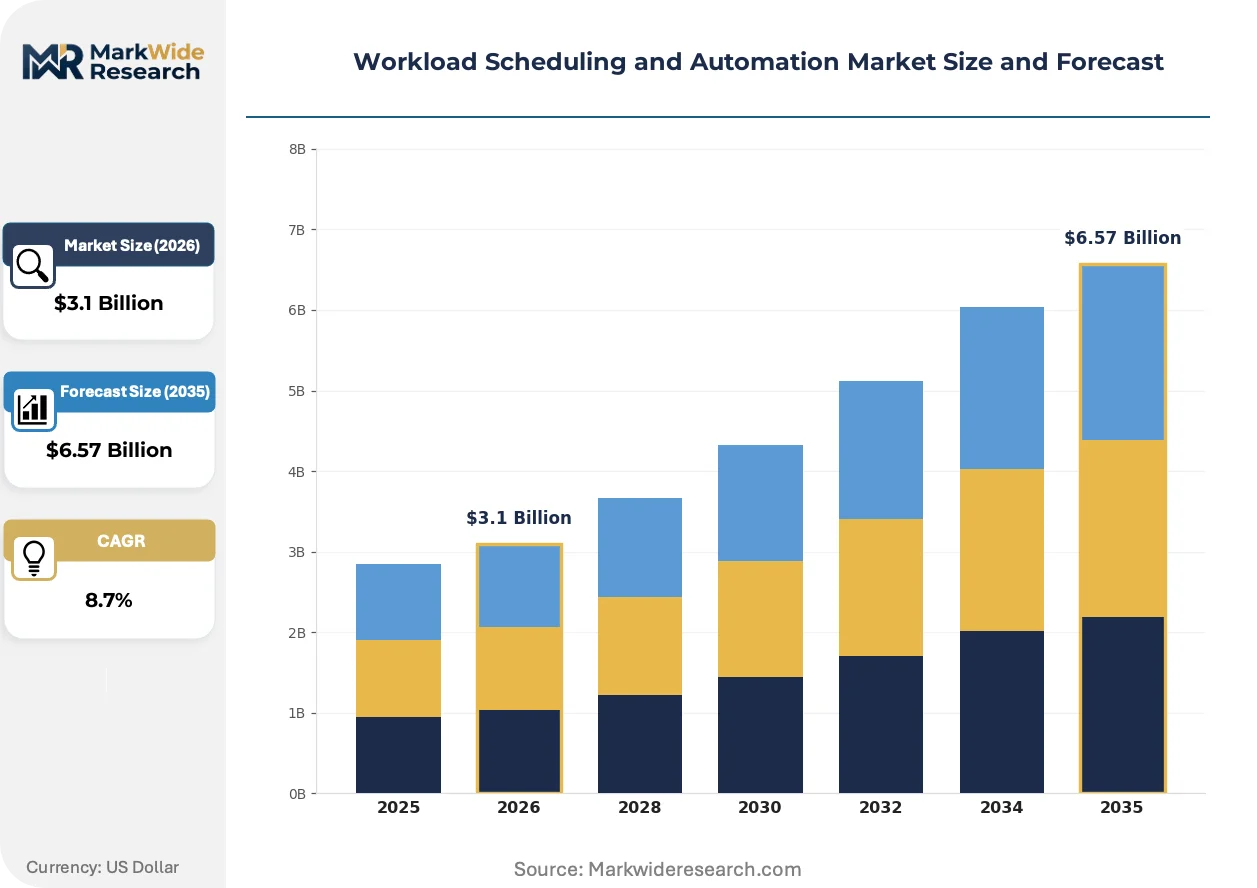
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, On-Premises, Hybrid, SaaS Deployment: Public Cloud, Private Cloud, Multi-Cloud, Edge Computing End User: IT Services, Telecommunications, BFSI, Healthcare Application: Job Scheduling, Resource Allocation, Load Balancing, Capacity Planning |
| Companies Covered | BMC Software Inc., Stonebranch Inc., IBM, Advanced Systems Concepts Inc., SAP SE, Microsoft Corporation, Redwood Software Inc., ServiceNow Inc., Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workload Scheduling and Automation Market Strategic Shifts & Innovations
Agentless architecture is compressing deployment timelines and security review cycles, while policy-as-code frameworks embed compliance directly into automation logic rather than bolting it on post-deployment.
Agentless workload orchestration is supplanting traditional agent-based deployment models across regulated industries. Banking and healthcare security teams in Switzerland and Germany now mandate agentless connectivity to eliminate endpoint attack surfaces. This architectural shift compresses procurement cycles from twelve-month security reviews to thirty-day pilot evaluations, reshaping competitive differentiation toward API-native integration depth.
The EU AI Act's algorithmic accountability requirements are forcing workload automation vendors to implement immutable audit logs and explainable dependency chains. Batch job definitions must now carry metadata tags tracing data lineage and decision logic for regulatory inspection. German automotive suppliers and French pharmaceutical manufacturers are prioritizing platforms with built-in policy enforcement engines over legacy schedulers requiring custom compliance overlays.
FinOps-driven procurement is collapsing the traditional separation between infrastructure cost management and operational scheduling. Platform engineering teams in US technology firms and UK financial services now evaluate workload automation through unit economics lenses, demanding per-job cost attribution and automated rightsizing recommendations. This behavioral shift elevates vendors with native cloud billing integration above those relying on third-party cost visibility tools.
Workload Scheduling and Automation Market Segmentation
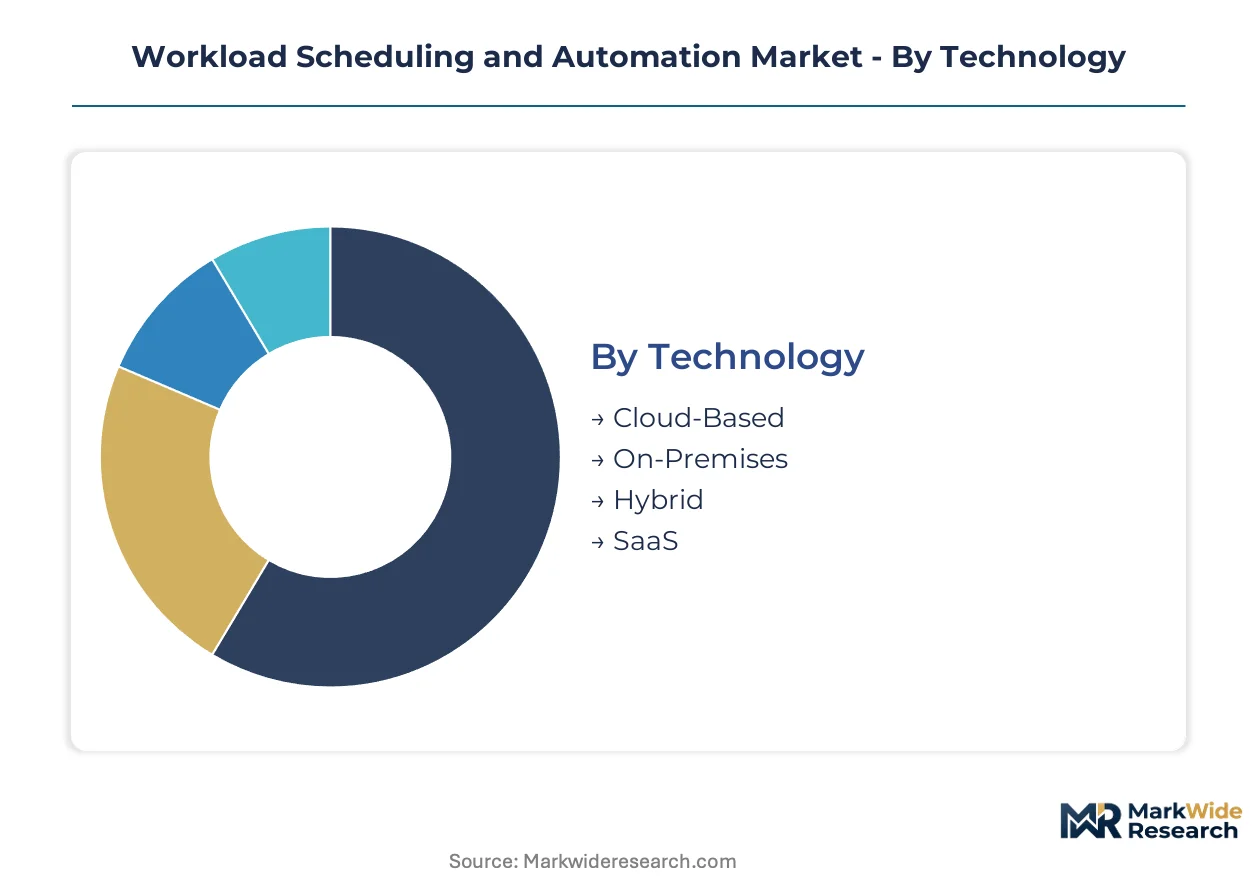
Workload automation procurement fragments across infrastructure maturity, compliance posture, and operational scale. Technology choices determine integration complexity with legacy estates. End-user concentration in regulated industries reshapes vendor feature roadmaps toward auditability and policy enforcement.
Technology:
Cloud-native architectures exert substitution pressure on mainframe-anchored deployments, though hybrid configurations preserve incumbent positions through interoperability requirements.
- Cloud-Based:Fully managed orchestration platforms eliminate infrastructure ownership overhead. German automotive suppliers and French pharmaceutical manufacturers prioritize cloud-based deployment to satisfy EU AI Act audit trail mandates without on-premises maintenance burdens.
- Hybrid:Bridges z/OS batch environments with Kubernetes-native workloads through unified control planes. Financial institutions in Switzerland and the Netherlands deploy hybrid technology to modernize scheduling without abandoning JCL-dependent core systems.
- On-Premises:Retains dominance in US healthcare and defense sectors where HIPAA and ITAR data residency requirements prohibit external compute placement.
- SaaS:Compresses procurement cycles through consumption-based pricing and zero-footprint deployment. Mid-market enterprises in India's PLI-backed manufacturing sector adopt SaaS to bypass mainframe technical debt entirely.
Hybrid technology anchors the volume base while SaaS gains share at the steepest rate.
Deployment:
Cost tier differentiation separates hyperscale-integrated deployments from sovereign-cloud configurations required by national data localization laws.
- Public Cloud:Leverages AWS, Azure, and GCP native scheduling services for elastic batch processing. US technology firms and UK financial services deploy public cloud deployment to align workload automation with FinOps unit economics frameworks.
- Multi-Cloud:Abstracts vendor-specific APIs through portable orchestration layers. Platform engineering teams at German industrial conglomerates mandate multi-cloud deployment to avoid single-provider concentration risk.
- Private Cloud:Delivers dedicated infrastructure within enterprise-controlled facilities. Swiss banking regulators require private cloud deployment for systemically important payment batch processing.
- Edge Computing:Dispatches jobs to distributed nodes for latency-sensitive manufacturing workflows. Automotive assembly plants in Germany deploy edge computing deployment for real-time quality control pipeline orchestration.
Public cloud deployment dominates current procurement volumes while multi-cloud configurations show the steepest expansion trajectory among enterprise renewals.
End User:
Application-specific requirements create divergent demand profiles across vertical compliance regimes and infrastructure legacy positions.
- BFSI:Demands immutable audit logs, SLA enforcement for payment clearing windows, and explainable dependency chains. German and French banks anchor BFSI demand through ECB and ACPR supervisory requirements for algorithmic batch accountability.
- Healthcare:Requires HIPAA-compliant data lineage tracking and patient information isolation. US hospital systems and German university medical centers drive healthcare segment investment in policy-as-code enforcement engines.
- IT Services:Prioritizes multi-tenant workload isolation and customer-specific SLA tiering. Managed service providers in India and Ireland scale IT services deployment through standardized automation templates.
- Telecommunications:Orchestrates network function virtualization and billing mediation batch jobs. European operators under BEREC guidelines deploy telecommunications-specific scheduling for 5G core network automation.
BFSI end users anchor the volume base while healthcare gains share at the steepest rate.
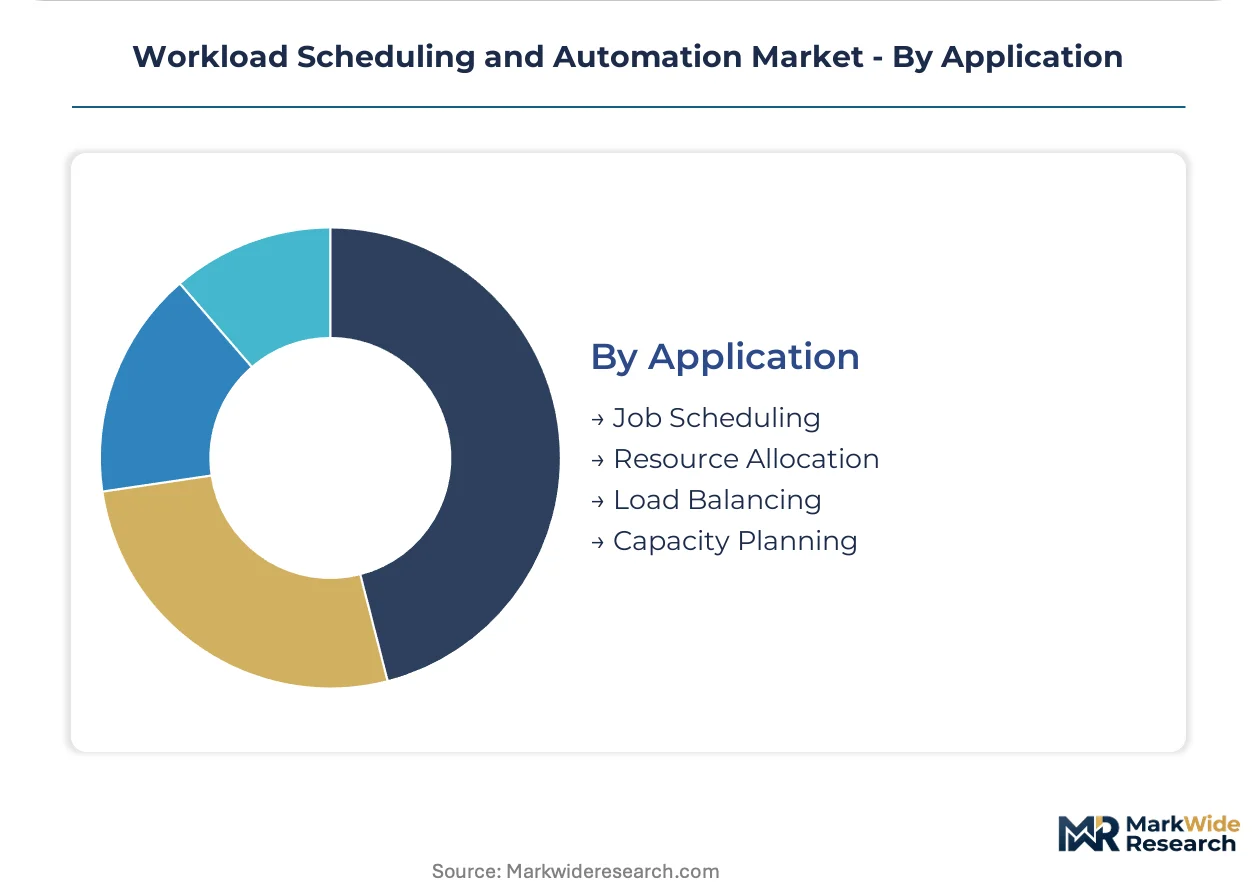
Application:
Maturity differentiation separates established job scheduling functions from emerging capacity planning capabilities attracting disproportionate R&D investment.
- Job Scheduling:Executes time-based and event-triggered batch processing across distributed resources. Financial services institutions in Germany and the Netherlands rely on job scheduling application for core banking end-of-day processing.
- Capacity Planning:Forecasts compute demand and optimizes resource allocation against carbon intensity signals. German industrial enterprises under CSRD reporting mandates prioritize capacity planning application for Scope 3 emissions verification.
- Resource Allocation:Dispatches workloads to optimal infrastructure based on cost, performance, and policy constraints. Cloud-native enterprises deploy resource allocation application for automated rightsizing recommendations.
- Load Balancing:Distributes computational tasks across redundant infrastructure to prevent single points of failure. Telecommunications operators utilize load balancing application for high-availability network service orchestration.
Job scheduling application anchors the volume base while capacity planning gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation vendors export workload orchestration platforms to automotive suppliers across Central Europe, while US cloud providers penetrate financial services markets in London and Singapore through compliance-certified SaaS offerings.
United States
Healthcare systems and defense contractors drive demand for HIPAA-compliant and ITAR-certified scheduling environments. The SEC cybersecurity disclosure rules mandate immutable audit trails for algorithmic batch processing in investment banks. Hospital networks in the Greater Boston corridor deploy on-premises orchestration to isolate patient data from external compute infrastructure.
Germany
Automotive suppliers and industrial conglomerates modernize mainframe-dependent scheduling estates under CSRD carbon accounting mandates. The EU AI Act requires explainable automation logic with decision lineage tracking for algorithmic batch jobs. Manufacturing clusters in Bavaria and Baden-Württemberg prioritize carbon-aware job scheduling against real-time electricity pricing signals.
United Kingdom
Financial services institutions in the City of London demand multi-cloud orchestration to avoid single-provider concentration risk. The Financial Conduct Authority's operational resilience requirements enforce SLA documentation for payment clearing batch windows. Fintech clusters in Manchester and Edinburgh adopt SaaS-native schedulers to bypass legacy technical debt.
India
PLI scheme beneficiaries in electronics and automotive assembly greenfield-deploy cloud-native schedulers without mainframe legacy constraints. The RBI's data localization guidelines push banking institutions toward private cloud orchestration with sovereign infrastructure controls. Manufacturing corridors in Maharashtra and Tamil Nadu integrate workload automation with shop-floor IoT pipelines for real-time quality control.
Switzerland
Private banking and pharmaceutical manufacturers mandate agentless architecture to eliminate endpoint attack surfaces in highly regulated environments. Swissmedic and FINMA audit requirements enforce immutable logs for batch processing in systemically important payment systems. Precision manufacturing clusters around Zurich and Basel deploy edge-computing schedulers for latency-sensitive production workflows.
Workload Scheduling and Automation Market Key Industry Players
Listed leaders compete with private specialists across compliance architecture and deployment flexibility, creating a tiered structure where scale advantages clash with niche regulatory expertise. The vendor base separates into three strategic archetypes: mainframe-anchored incumbents with deep z/OS integration, cloud-native challengers with Kubernetes-native orchestration, and agentless specialists targeting regulated European industries. Competitive moves concentrate on M&A for policy-as-code capabilities and strategic partnerships with hyperscale cloud providers to embed scheduling within native platform marketplaces.
Within the mainframe-anchored tier, BMC Software Inc. and IBM occupy positions defined by legacy system compatibility and deep enterprise entrenchment. Stonebranch Inc. exemplifies the agentless architecture vector that Swiss and German security teams increasingly mandate for regulated batch environments. SAP SE and Oracle Corporation represent the enterprise application extension archetype, embedding workload automation within broader ERP and database platform ecosystems to capture infrastructure budget consolidation.
| Leading Market Players |
|---|
| BMC Software Inc. |
| Stonebranch Inc. |
| IBM |
| Advanced Systems Concepts Inc. |
| SAP SE |
| Microsoft Corporation |
| Redwood Software Inc. |
| ServiceNow Inc. |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
Platform engineering scale economies in cloud-native workload automation compress marginal delivery costs for SaaS vendors while elevating price floors for hybrid deployments requiring mainframe integration expertise. German automotive suppliers and Swiss banking consortia absorb premium pricing for agentless architectures that eliminate twelve-month security review cycles, whereas Indian PLI manufacturers drive standard-tier SaaS pricing through volume procurement of greenfield orchestration platforms.
Pricing Analysis
Cloud-native generation pricing gaps separate Kubernetes-native SaaS tiers from legacy mainframe-anchored perpetual licenses and emerging edge-computing deployment premiums. Three-tier pricing structure across enterprise-grade policy enforcement, standard multi-cloud orchestration, and economy SaaS entry levels dominates procurement frameworks, with ISO 27001 and EU AI Act compliance tiers commanding substantial premiums over baseline configurations. Pricing pressure stems from FinOps-driven unit economics scrutiny among US technology firms and UK financial services, which now mandate per-job cost attribution. Mid-market enterprises exhibit highest price sensitivity, while German industrial conglomerates under CSRD mandates demonstrate lowest elasticity for carbon-aware scheduling capabilities.
Supply Chain Analysis
Just-in-time deployment preferences dominate cloud-native workload automation delivery, though strategic stockpiling of mainframe integration expertise persists among US and European financial institutions facing COBOL skill scarcity. Software development concentrates in Germany, the United States, and India, with intellectual property creation anchored in enterprise software hubs around Munich, Boston, and Bangalore. Component dependencies span Kubernetes orchestration engines, API gateway infrastructure, and immutable audit logging frameworks. Single-source vulnerability concentrates in IBM z/OS ecosystem dependencies for hybrid deployments. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales channels serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The workload scheduling and automation market constitutes a high-growth disruption as EU AI Act algorithmic accountability mandates force wholesale replacement of legacy schedulers lacking explainable decision trails. Kubernetes-native orchestration and agentless architecture adoption curves indicate technology inflection favoring architectural insurgents over mainframe-anchored incumbents.
For Market Incumbents: Compound defensive positioning through accelerated policy-as-code R&D investment and strategic capacity expansion in carbon-aware scheduling capabilities for German industrial clients. Deepen mainframe integration moats against cloud-native substitution threats by embedding Watson AI layers and immutable audit engines directly into z/OS scheduling environments. Prioritize certification fast-tracks for EU AI Act compliance to neutralize agentless architecture challengers in Swiss and Dutch banking sectors.
For New Entrants and Emerging Players: Certification fast-tracks for ISO 27001 and EU AI Act compliance create expedited market entry pathways for SaaS-native vendors targeting mid-market enterprises. White-space opportunities concentrate in Indian PLI manufacturing corridors and UK fintech clusters seeking to bypass legacy technical debt entirely. Carbon accounting integration for CSRD reporting represents the most penetrable application segment. Go-to-market execution should anchor on FinOps unit economics messaging to platform engineering budgets.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors agentless architecture specialists with demonstrated policy-as-code enforcement engines over mainframe-anchored incumbents facing structural decline in net-new procurement. Long-term viability across the projection horizon hinges on carbon-aware scheduling capabilities and multi-cloud abstraction layers. Acquisition target archetypes include Kubernetes-native orchestration platforms with embedded compliance frameworks. Watch for inflection when ECB operational resilience guidelines extend algorithmic accountability requirements to payment clearing batch windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Policy-as-Code Platform Integration | Embeds EU AI Act compliance directly into automation logic for German automotive suppliers. |
| Agentless Architecture Expansion | Eliminates endpoint attack surfaces that Swissmedic and FINMA auditors flag in banking deployments. |
| Carbon-Aware Scheduling Development | Positions platforms as foundational infrastructure for CSRD Scope 3 emissions verification. |
| FinOps Convergence Investment | Merges real-time cloud cost optimization with job scheduling for UK financial services procurement. |
| Multi-Cloud Abstraction Layer | Insulates German industrial conglomerates from single-provider concentration risk in orchestration. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with platform engineering directors, IT procurement officers at financial institutions, DevOps team leads, compliance auditors, and mainframe operations specialists. Secondary validation drew from SEC filings of publicly traded automation vendors, hyperscaler capex disclosures, EU regulatory implementation guidance, and GPO contracts for healthcare scheduling deployments. Bottom-up deployment modeling across technology tiers triangulated with top-down market sizing from vendor revenue disclosures.
Across the analysis window, forecasts incorporate deployment model segmentation by cloud-native, hybrid, and on-premises configurations; end-user vertical differentiation across BFSI, healthcare, and industrial manufacturing; and application-type splits between job scheduling and capacity planning. CAGRs derive from regression analysis of historical procurement velocity against regulatory implementation timelines and infrastructure modernization cycles. Kubernetes adoption curves and mainframe skill scarcity indices serve as primary forecast inputs.
Underlying assumptions cover steady EU AI Act enforcement progression, sustained cloud migration momentum, and stable energy cost volatility, with deviation risk concentrated in mainframe talent pipeline collapse and regulatory fragmentation between national implementations. Revision becomes warranted when ECB operational resilience guidelines or SEC cybersecurity disclosure rules cross enforcement thresholds that accelerate legacy scheduler replacement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Cognitive Process Automation Market
Automation
Parcel Sorting System Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Postal Automation System Market
Automation
Global Remote Monitoring and Control Market
Automation
Playout Automation Market
Automation
Data Center Automation Market
Automation
Laboratory Benchtop Automation Market
Automation
Universal Process Control Market
Automation
AR Automation Market
Automation
Automation Light Grids Market
Automation
CNC Controller Market
Automation
IoT Home Automation Market
Automation
Global Automated Liquid Handling System Market
Automation
Service Delivery Automation (SDA) Market
Automation
Micro Fulfillment Market