
 Escalator Control Systems Market | 2026-2036
Escalator Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Escalator Control Systems Market Analytics
EN 115-1 compliance tiers are redrawing supplier positioning in the escalator control systems market. Otis Elevator Company leverages its captive semiconductor sourcing to dominate premium digital control installations. Schindler Group anchors its European installed base through predictive maintenance software bundled with hardware retrofits. KONE Corporation differentiates via permanent magnet motor controls that cut energy draw in high-traffic transit environments.
Escalator control systems comprise motor drives, brake controllers, safety sensor arrays, and programmable logic units that govern speed, direction, and emergency stopping. These assemblies typically operate at 0.5 to 0.75 meters per second with fault-tolerant architectures to prevent uncontrolled descent or reverse operation. Microprocessor-based architectures now lead product type segmentation due to diagnostic granularity and remote monitoring compatibility. Digital control platforms represent the fastest-expanding technology category as building operators phase out relay-based units that lack IoT connectivity. Energy-efficient systems command margin premiums in airport and shopping mall applications where continuous duty cycles dominate operating profiles.
The US Department of Transportation enforces ADA accessibility standards that dictate escalator handrail speed synchronization and platform gap limits. China's SAMR implements GB 16899 escalator safety codes requiring dual-channel brake verification and step-chain monitoring. The EU Machinery Directive and EN 115 series together shape product certification requirements for any system sold across member states. Stakeholders must weigh upgrade cycles against full replacement economics as legacy analog controls face obsolescence in safety-critical certifications.
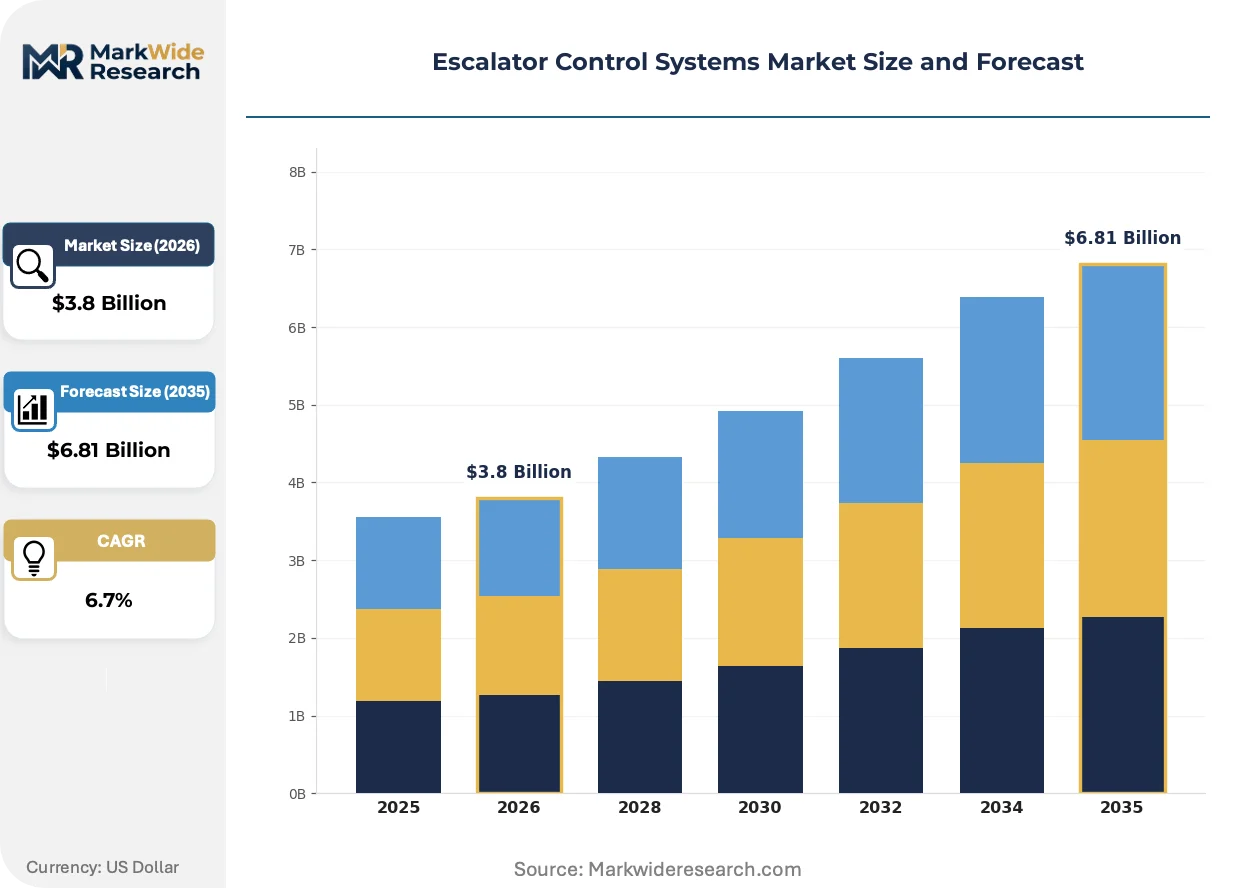
Market Dynamics
The transition from relay-based to microprocessor-based architectures is compressing replacement cycles as building operators face certification obsolescence in safety-critical installations. This technology displacement is redrawing supplier margins and service revenue pools across transit, retail, and commercial verticals.
Growth Catalysts
- Transit Infrastructure Buildouts:Metro rail authorities in India and China are specifying smart escalator systems with integrated condition monitoring for new underground corridors. These procurements bundle control hardware with multi-year service agreements.
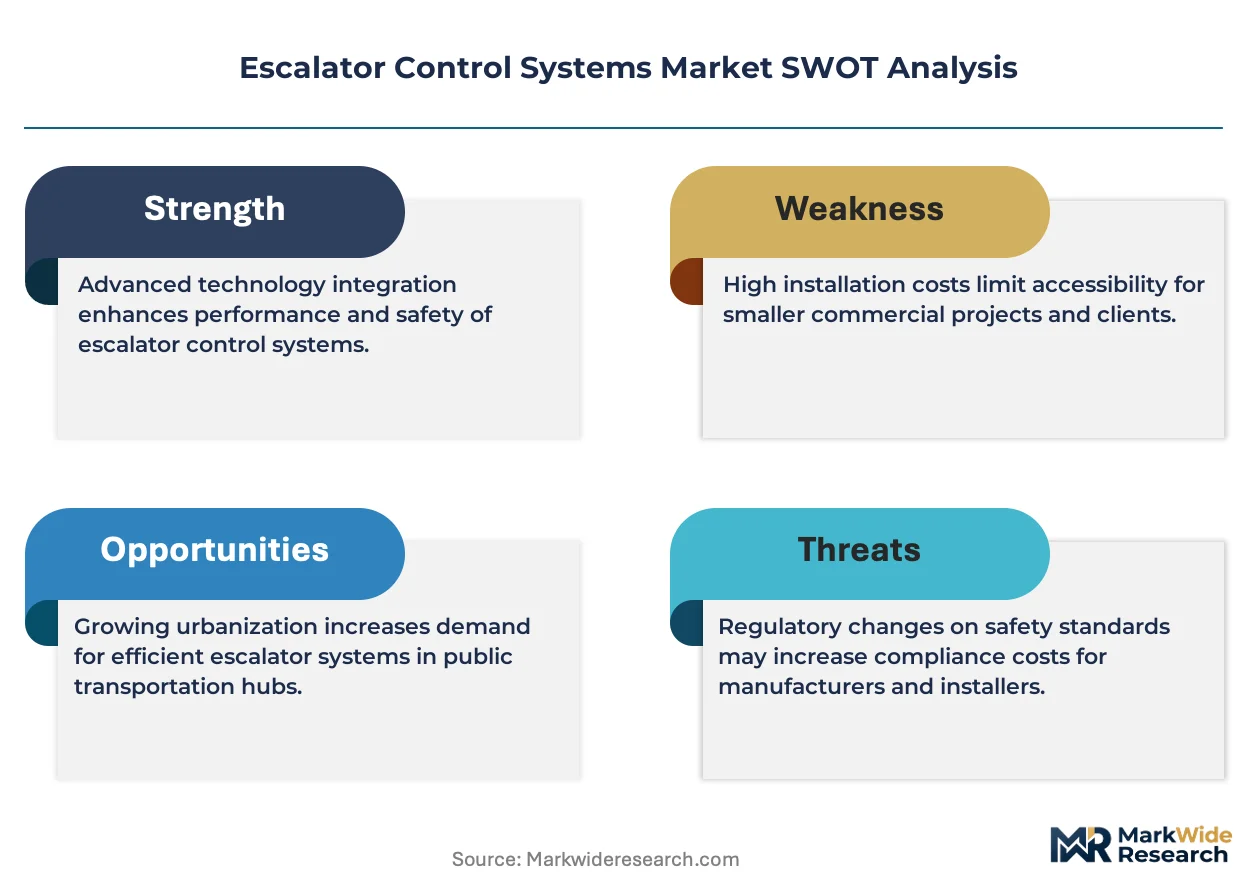
- EN 115-1 Safety Mandates:European standards now require redundant brake verification and sensor arrays, forcing hardware refresh cycles in aging installations across Germany, France, and the United Kingdom.
- Permanent Magnet Motor Adoption:Energy-efficient motor controls are displacing induction drives in airports and shopping malls where continuous duty cycles dominate operating economics.
Market Restraints
- Semiconductor Supply Concentration:Microprocessor and power electronics sourcing remains concentrated among East Asian foundries, exposing lead time volatility for control system manufacturers.
- Legacy Analog Obsolescence:Relay-based control platforms face decertification risks under evolving safety codes, stranding installed base upgrade economics for building operators.
- Electromechanical Integration Complexity:Brake controller and step-chain sensor alignment demands specialized field expertise that contractor networks struggle to scale.
Strategic Opportunities
- Predictive Maintenance Software:Control system vendors can unbundle diagnostic platforms from hardware sales, creating recurring revenue streams through remote monitoring subscriptions.
- GB 16899 Compliance Services:China's safety code implementation creates aftermarket demand for dual-channel brake verification retrofits in tier-two and tier-three cities.
- AI-Assisted Fault Detection:Machine learning convergence with edge computing enables real-time anomaly detection in high-traffic transit environments before safety threshold breaches.
Industry Challenges
- Embedded Systems Engineering Talent:Firmware development for fault-tolerant architectures requires scarce expertise in safety-critical programming standards.
- Multi-Jurisdiction Certification Timelines:Parallel approvals under EN 115, GB 16899, and ADA accessibility standards extend product launch windows by 12-18 months.
- Installed Base Integration Friction:Digital control retrofits must interface with legacy mechanical subsystems that lack standardized communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Escalator Control Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessor-Based, Relay-Based, Analog Control, Digital Control Application: Commercial Buildings, Airports, Shopping Malls, Transit Stations End User: Building Owners, Facility Managers, Architects, Contractors Technology: Smart Escalators, Conventional Escalators, Energy-Efficient Systems, Safety Sensors |
| Companies Covered | Otis Elevator Company, Schindler Group, KONE Corporation, TK Elevator, Mitsubishi Electric Corporation, Hitachi Ltd., Hyundai Elevator Co. Ltd., Fujitec Co. Ltd., Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Escalator Control Systems Market Evolving Landscape
Digitalization of escalator control architectures is collapsing the boundary between hardware and software value capture. Vendors now compete on diagnostic granularity and remote service attach rates rather than unit shipment volumes alone.
Silicon carbide power semiconductors are miniaturizing motor drive footprints while improving thermal efficiency in compact machine room installations. Airport operators in Singapore and Dubai are specifying these subsystems for high-duty-cycle applications where space constraints dominate. The technology is miniaturizing drive cabinet dimensions by 40 percent compared to conventional IGBT platforms, enabling retrofit installations previously deemed infeasible.
The EU Machinery Directive's 2023 amendment tightens conformity assessment procedures for safety-related control systems sold across member states. Manufacturers must now document fault mode analysis for every programmable logic unit variant, extending engineering validation cycles. Transit authorities in France and Germany are responding by consolidating procurement specifications to reduce vendor qualification overhead.
Building operators are unbundling escalator maintenance from original equipment contracts, creating openings for independent service providers with proprietary diagnostic tools. This disintermediation pressures incumbent vendors to open control system data interfaces or risk recurring revenue erosion. The shift is most visible in North American commercial real estate portfolios where facility management outsourcing has concentrated buyer negotiating leverage.
Escalator Control Systems Market Segmentation
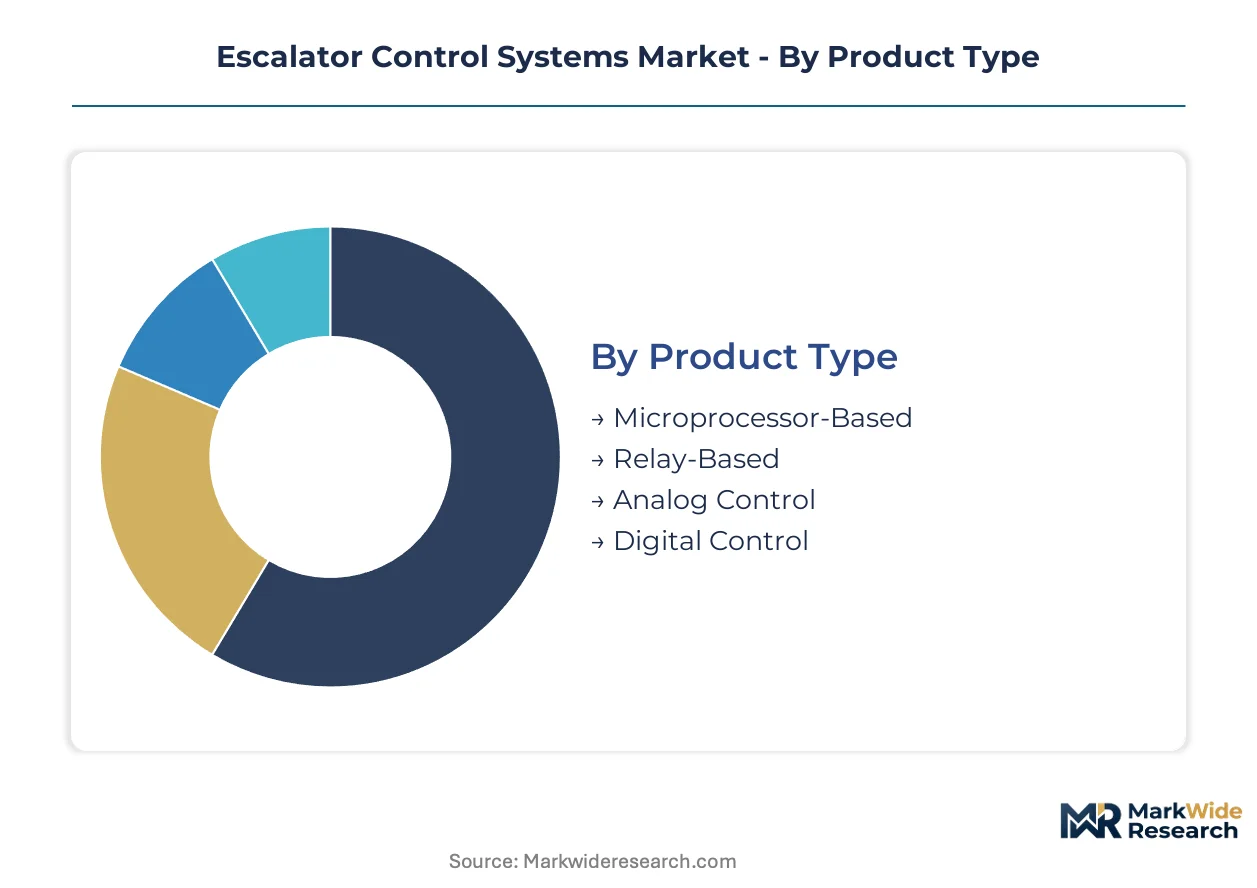
Escalator control systems fragment across four intersecting dimensions that shape procurement patterns and vendor positioning. Product architecture determines upgrade economics while application context dictates performance specifications and certification requirements.
Product Type:
Domestic production concentrates on relay-based and analog platforms for cost-sensitive retrofits, whereas microprocessor and digital systems flow through specialized import channels serving premium transit and commercial installations.
- Microprocessor-Based:These architectures embed fault-tolerant programmable logic units with diagnostic granularity down to individual sensor channels. Demand clusters in India's metro rail procurement and China's tier-one subway expansions where remote monitoring compatibility is mandatory. EN 115-1 compliance deadlines are accelerating replacement of legacy platforms in European transit authorities.
- Digital Control:Full-digital platforms integrate IoT connectivity, edge computing capability, and API-accessible telemetry streams. Airport operators in Singapore and Dubai specify these systems for high-duty-cycle environments where predictive maintenance contracts attach to hardware sales. The technology commands margin premiums through software recurring revenue models.
- Relay-Based:Electromechanical switching architectures dominate aging installed bases in secondary commercial buildings where upgrade budgets remain constrained.
- Analog Control:Voltage-regulated speed governors persist in legacy installations facing decertification risk under evolving safety codes.
Microprocessor-Based commands the established base. The steepest expansion runs through Digital Control.
Application:
Volume concentration tilts toward commercial buildings where replacement cycles follow property renovation timelines, while value capture concentrates in transit infrastructure with bundled service agreements.
- Transit Stations:Underground rail corridors specify redundant brake verification, dual-channel sensor arrays, and permanent magnet motor drives for continuous duty operation. Procurement bundles in India and China incorporate multi-year condition monitoring contracts. The EU Machinery Directive's tightened conformity assessments extend vendor qualification cycles for these safety-critical deployments.
- Airports:High-traffic terminals demand compact machine room footprints and silicon carbide power electronics for thermal efficiency. Singapore Changi and Dubai International anchor specification standards that cascade to secondary hubs. Duty-free retail integration drives handrail speed synchronization requirements under ADA accessibility standards.
- Commercial Buildings:Office and hospitality installations prioritize energy draw reduction through variable frequency drives.
- Shopping Malls:Extended operating hours favor permanent magnet motor retrofits over induction drive replacements.
Commercial Buildings anchor volume shipments. Airports generate the highest margin capture per installation.
End User:
Procurement authority fragmentation creates divergent buying criteria across the value chain, with facility managers prioritizing total cost of ownership while architects emphasize specification compliance.
- Facility Managers:Operating expenditure control drives predictive maintenance software adoption and unbundled service contracts. North American commercial real estate portfolios concentrate negotiating leverage through facility management outsourcing arrangements. These buyers demand open data interfaces to prevent vendor lock-in.
- Building Owners:Capital allocation discipline shapes replacement-versus-upgrade decisions as legacy analog controls face safety certification obsolescence. Ownership structures in German and French commercial property markets favor long-dated service agreements over upfront hardware premiums.
- Architects:Specification authority concentrates in greenfield developments where EN 115 and GB 16899 compliance documentation shapes short-list decisions.
- Contractors:Installation complexity around brake controller alignment favors vendors with scaled field service networks.
Facility Managers are gaining procurement influence fastest. Building Owners retain capital authority on replacement cycles.
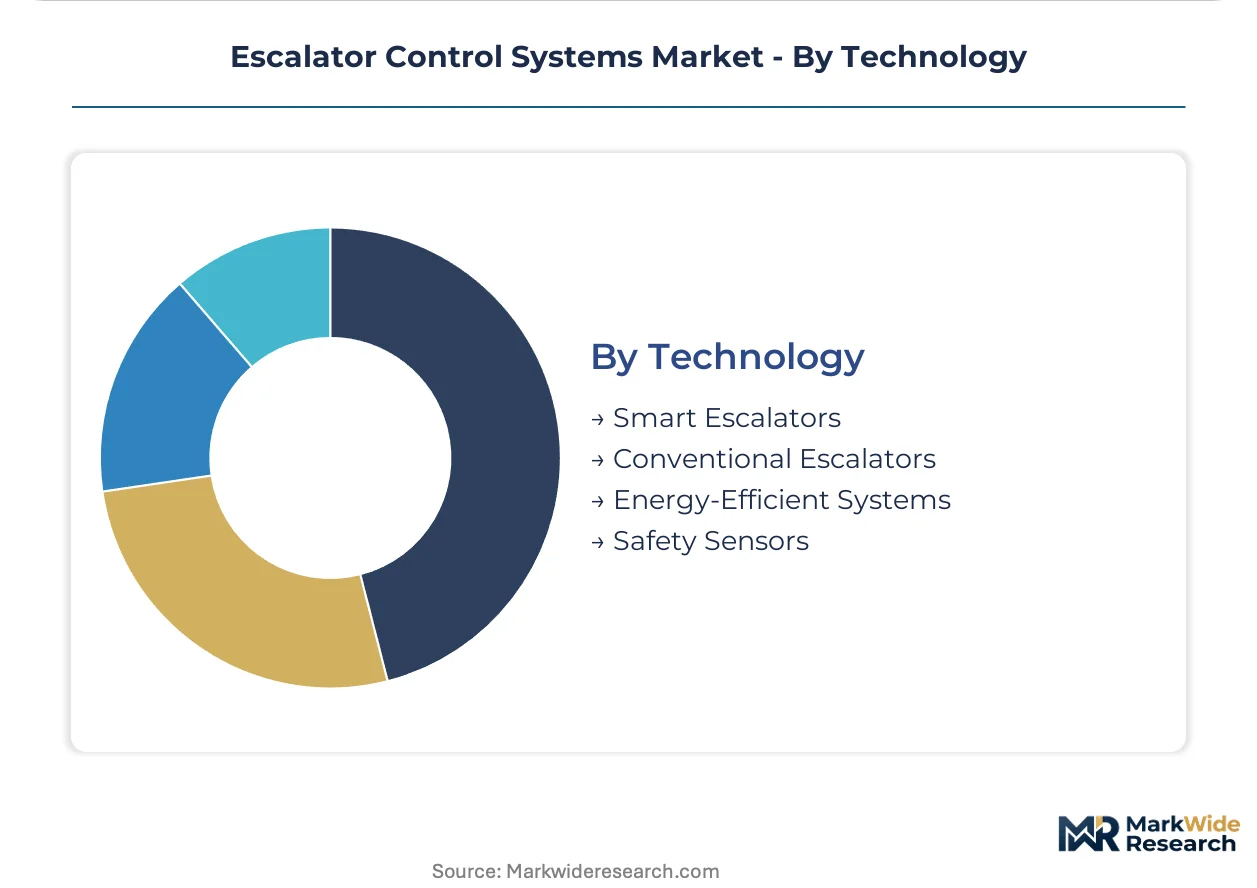
Technology:
Supply-side capability stratification separates integrated platform vendors from component specialists, with full-system providers capturing service attach rates that component suppliers cannot replicate.
- Smart Escalators:Integrated platforms combine motor drives, safety sensors, and cloud-connected diagnostics in unified architectures. China's SAMR GB 16899 implementation mandates dual-channel brake verification that these systems deliver natively. Edge computing convergence enables real-time anomaly detection before safety threshold breaches.
- Energy-Efficient Systems:Permanent magnet synchronous motor controls reduce energy draw in continuous duty applications. Airports and shopping malls specify these subsystems where operating economics dominate procurement criteria. Silicon carbide semiconductors miniaturize drive footprints by 40 percent versus conventional IGBT platforms.
- Safety Sensors:Step-chain monitoring and handrail speed verification arrays face redundant architecture mandates under European standards.
- Conventional Escalators:Basic induction drive systems persist in cost-sensitive replacement markets.
Conventional Escalators retain the largest installed base. Smart Escalators are expanding most quickly through transit infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Escalator control systems trade flows tilt toward import dependence in emerging transit markets while established manufacturing clusters in Germany, Japan, and China anchor supply capacity. Component sourcing concentrates among East Asian semiconductor foundries, creating cross-border lead time exposures for system integrators.
China
Subway expansion in Shanghai, Beijing, and Shenzhen drives replacement cycles for legacy relay-based controls under SAMR's GB 16899 safety mandates. Tier-one cities specify smart escalator platforms with dual-channel brake verification and cloud-connected diagnostics for new underground corridors. The Yangtze River Delta hosts domestic control system assembly clusters serving both local metro authorities and export markets.
India
Metro rail buildouts in Delhi, Mumbai, and Bengaluru accelerate procurement of microprocessor-based architectures with bundled service agreements. The Ministry of Housing and Urban Affairs prioritizes ADA-equivalent accessibility standards in station modernization programs. Control system imports from European and East Asian suppliers dominate as domestic manufacturing capacity remains concentrated in low-voltage electrical components.
Germany
EN 115-1 compliance deadlines force hardware refresh cycles in aging Frankfurt, Munich, and Berlin transit installations. The EU Machinery Directive's tightened conformity assessment procedures extend vendor qualification timelines for safety-critical deployments. Baden-Württemberg and Bavaria host precision drive manufacturing clusters supplying motor control subsystems across European retrofit markets.
United States
ADA accessibility standards enforced by the Department of Transportation dictate handrail speed synchronization requirements in airport and transit terminal modernizations. Facility management outsourcing in commercial real estate concentrates buyer negotiating leverage for predictive maintenance software attach rates. The Southeast and Texas metro corridors see accelerated replacement demand as 1980s-era analog controls face obsolescence.
Japan
Permanent magnet motor control adoption advances through METI energy efficiency directives targeting continuous-duty escalator installations in Tokyo and Osaka rail hubs. JIS standards alignment with EN 115 series enables dual-certification product platforms for export markets. Chubu region manufacturers supply compact drive subsystems optimized for constrained machine room footprints in dense urban transit environments.
Escalator Control Systems Market Competitive Landscape
Concentration sits with integrated platform vendors capable of bundling hardware with multi-year service contracts. The supplier base stratifies across three tiers: full-system providers with captive semiconductor sourcing, regional specialists focused on retrofit compatibility, and component subcontractors supplying motor drives and sensor arrays. Competitive dynamics center on predictive maintenance software unbundling and silicon carbide power electronics integration.
Among the integrated tier, Otis Elevator Company and Schindler Group exemplify archetypes pursuing recurring revenue through diagnostic platform attach rates. KONE Corporation occupies a position emphasizing energy-efficient motor control differentiation. These three anchors represent contrasting strategic vectors: captive supply chain depth, European installed base leverage, and permanent magnet drive specialization respectively. TK Elevator sits within the scale-driven segment, reflecting consolidation-era capacity positioning.
| Leading Market Players |
|---|
| Otis Elevator Company |
| Schindler Group |
| KONE Corporation |
| TK Elevator |
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Hyundai Elevator Co. Ltd. |
| Fujitec Co. Ltd. |
| Toshiba Corporation |
| Others |
Value Network & Pricing Analysis
EN 115-1 compliance deadlines gate both supplier qualification tiers and price differentiation across European procurement channels. Transit authorities in Germany and France now require redundant brake verification architectures that only microprocessor-based platforms deliver, compressing the addressable supply base while widening the premium that certified systems command over relay-based alternatives in retrofit markets.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade under EN 115 and GB 16899 standards, plus after-sales service bundling that attaches predictive maintenance subscriptions to hardware sales. Cost compression in relay-based tiers is intensifying because semiconductor supply concentration extends lead times for control system manufacturers. Facility managers in North American commercial real estate portfolios exhibit the highest price sensitivity, while airport operators in Singapore and Dubai accept premium positioning for silicon carbide power electronics and compact drive footprints.
Supply Chain Analysis
Inventory buffers for microprocessor units and power electronics have thinned to eight-week coverage as East Asian foundry allocation tightens. Control system assembly draws from semiconductor fabrication clusters in Taiwan and South Korea, with final integration concentrated in Germany, Japan, and China's Yangtze River Delta. Single-source vulnerability sits with silicon carbide substrate supply for next-generation motor drives. Distribution runs through authorized service networks that bundle installation with multi-year condition monitoring contracts, particularly in India's metro rail procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The escalator control systems market operates as a defensive-moat industry where regulatory certification entrenchment creates switching costs that lock building operators into incumbent service ecosystems.
For Market Incumbents: Fortify captive semiconductor sourcing arrangements to insulate margin structures from East Asian foundry allocation volatility. Deepen backward integration into permanent magnet motor manufacturing to capture energy-efficiency upgrade cycles in airport and shopping mall verticals. The threat of independent service providers with proprietary diagnostic tools demands accelerated API standardization to prevent recurring revenue erosion.
For New Entrants and Emerging Players: Predictive maintenance software unbundling represents the most penetrable service layer where Otis, Schindler, and KONE maintain closed data architectures. Target China's tier-two and tier-three cities for GB 16899 compliance retrofit services, where domestic control system assemblers lack field service scale. A go-to-market angle through cloud-connected diagnostic platforms with open API specifications can disintermediate hardware-centric incumbents in facility management outsourcing channels.
For Investors and Strategic Acquirers: SAMR's GB 16899 implementation reshapes the acquisition landscape by mandating dual-channel brake verification that stranded legacy installed bases cannot satisfy. The five-to-ten-year viability window favors targets with predictive maintenance software recurring revenue and EN 115-1 pre-certified hardware platforms. Watch for consolidation signals when transit authorities in India and China consolidate procurement specifications to reduce vendor qualification overhead.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Integration | Miniaturizes drive footprints by 40 percent for constrained machine room retrofits in Dubai and Singapore airports. |
| Predictive Maintenance Platform Unbundling | Creates recurring SaaS revenue streams detached from hardware shipment cycles in North American commercial portfolios. |
| GB 16899 Compliance Service Expansion | Captures aftermarket demand in China's tier-two cities where legacy relay-based controls face decertification. |
| Captive Semiconductor Sourcing | Insulates margin structures from Taiwan and South Korea foundry allocation volatility affecting lead times. |
| Permanent Magnet Motor Control Specialization | Addresses METI energy efficiency directives targeting continuous-duty installations in Tokyo and Osaka rail hubs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade databases, and industry association disclosures. The research program combined structured interviews with escalator maintenance directors, OEM procurement teams, transit authority engineering leads, and aftermarket service heads with validation against EN 115 implementation timelines, SAMR GB 16899 technical interpretations, and ADA accessibility standard enforcement patterns. Bottom-up unit economics from control system component costs and top-down market sizing from transit infrastructure budget allocations were cross-referenced to anchor volume estimates.
Segmentation dimensions modeled include product architecture tiers, application verticals across transit and commercial installations, end-user procurement authority types, and technology categories spanning smart escalators to conventional induction drives. CAGRs were derived from replacement cycle compression analysis, safety mandate implementation schedules, and energy efficiency retrofit penetration curves. Forecast inputs incorporated semiconductor lead time volatility indices and metro rail capital expenditure commitments from Delhi, Mumbai, Shanghai, and Shenzhen authorities.
Underlying assumptions cover sustained transit infrastructure buildout pacing, regulatory enforcement continuity, and semiconductor supply normalization, with deviation risk concentrated in multi-jurisdiction certification timeline extensions and electromechanical integration contractor capacity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Home Automation Market
Automation
Europe Data Center Automation Market
Automation
Smart Home Automation Market
Automation
Process Control Systems for Steel Market
Automation
North America Data Center Automation Market
Automation
Modular Laboratory Automation Market
Automation
Elevator Control Market
Automation
Italy Marketing Automation Software Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Intelligent Remote Terminal Unit Market
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
Automation-As-A-Service Market
Automation
Data Center Automation Market
Automation
RFID Kanban Systems Market
Automation
Global Cloud Automation Market
Automation
Micro Fulfillment Market