
 Global Healthcare Automation Market | 2026-2036
Global Healthcare Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Automation Market Foresight
The gap between legacy electronic health record architectures and cloud-native automation platforms is narrowing as health systems demand real-time interoperability. UiPath leverages robotic process automation to streamline claims processing for large hospital networks. Medtronic anchors its automation strategy around surgical workflow integration and connected device ecosystems. Qventus specializes in AI-driven patient flow optimization, competing on operational throughput rather than clinical diagnostics.
Healthcare automation encompasses the use of software robotics, sensor networks, and algorithmic decision systems to execute administrative, diagnostic, and therapeutic tasks with minimal human intervention, typically operating through HL7 FHIR interfaces and ISO 27001-certified cloud infrastructure to ensure patient data integrity. Its primary purpose is to reduce clinical error rates, accelerate revenue cycles, and extend specialist capacity across constrained provider networks. Robotic Process Automation commands the largest installed base among product types, though Patient Monitoring Systems capture higher per-unit margins through continuous data monetization. Cloud-based Solutions dominate new deployments, while Hybrid Models retain favor among academic medical centers with fragmented legacy estates.
FDA digital health pre-certification, the EU AI Act risk-classification framework, and HIPAA security rule enforcement collectively determine market access velocity and product development roadmaps for automation vendors. The EU AI Act specifically mandates conformity assessments for high-risk clinical decision support systems, creating compliance moats for established players. Stakeholders must weigh algorithmic transparency investments against speed-to-market advantages as regulatory divergence between Washington and Brussels widens.
Market Dynamics
Labor shortages across specialist clinical roles are forcing health systems to automate diagnostic workflows and revenue-cycle operations at unprecedented velocity. The FDA digital health pre-certification pathway and EU AI Act risk-classification framework are compressing vendor development timelines while raising compliance barriers.
Growth Catalysts
- FDA Digital Health Pre-Certification:The FDA's streamlined validation pathway accelerates algorithmic tool deployment for patient-facing diagnostics, reducing time-to-market for clinical decision support systems.
- Germany Hospital Network Consolidation:Integrated hospital systems in Germany deploy robotic process automation across revenue-cycle operations to offset administrative labor gaps.
- HL7 FHIR Interoperability Mandates:Real-time data exchange standards enable cloud-native automation platforms to integrate with legacy electronic health record architectures.
Market Restraints
- EU AI Act Conformity Costs:High-risk clinical decision support systems face mandatory third-party conformity assessments, creating capital intensity for algorithmic transparency investments.
- ISO 27001 Certification Bottlenecks:Cloud infrastructure providers face extended audit timelines for healthcare-specific security certifications, constraining deployment velocity.
- Legacy EHR Fragmentation:Academic medical centers with fragmented on-premise estates resist full cloud migration, limiting addressable market for pure SaaS automation vendors.
Strategic Opportunities
- India Diagnostic Laboratory Automation:Underpenetrated pathology lab networks present white space for automated specimen processing and AI-augmented histopathology.
- Japan Surgical Workflow Integration:METI incentives for smart hospital infrastructure create regulatory tailwinds for connected device ecosystems in perioperative care.
- Sensor-Cloud Convergence:Continuous patient monitoring data streams hybridize with edge computing architectures, enabling real-time predictive analytics for sepsis detection.
Industry Challenges
- Clinical Informaticist Talent Scarcity:Health systems lack personnel capable of configuring robotic process automation bots for HIPAA-compliant clinical workflows.
- Algorithmic Validation Timelines:FDA software-as-medical-device determinations extend development cycles for machine learning-based diagnostic tools.
- Multi-Cloud Integration Complexity:Hybrid deployments across AWS, Azure, and private data centers create interoperability friction for real-time patient data synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Automation Market |
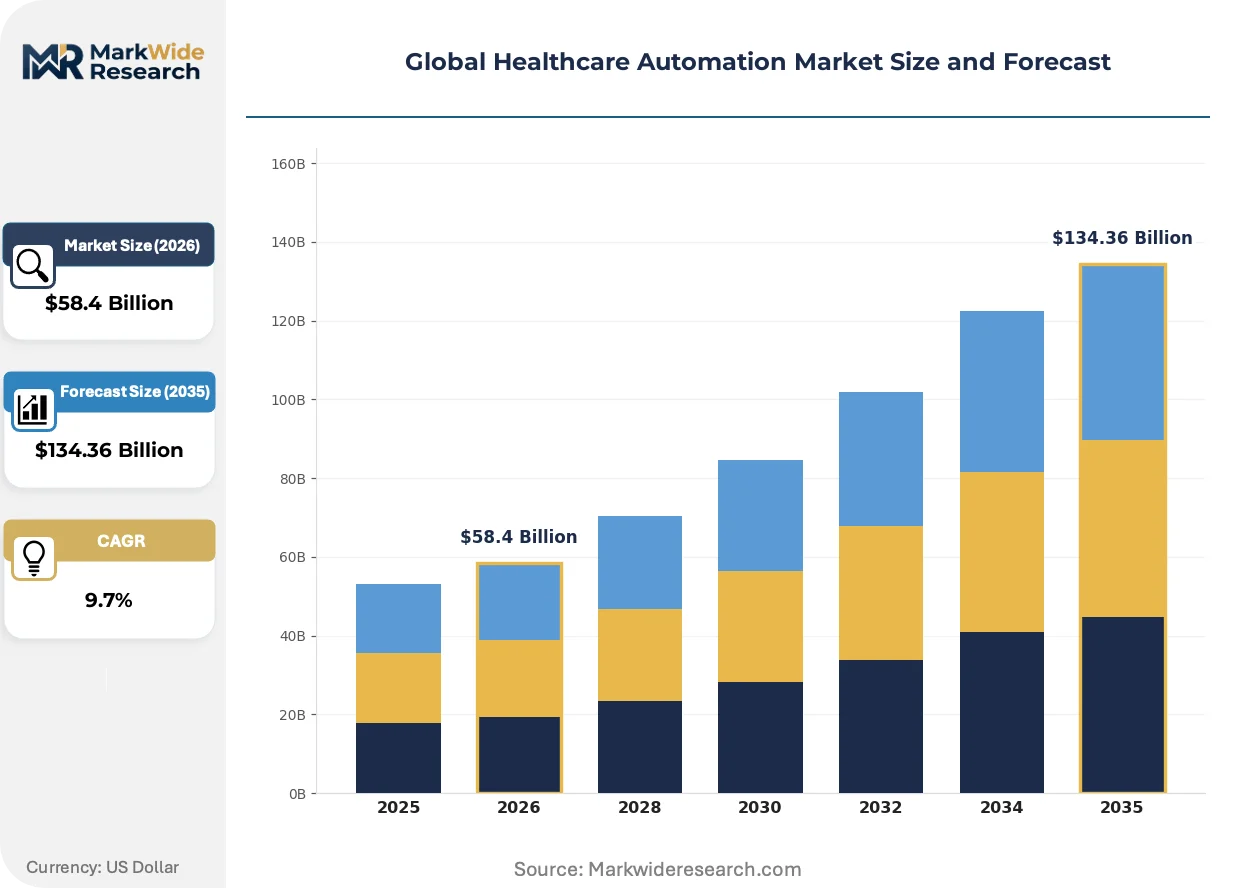
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $134.36 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Process Automation, Laboratory Information Management Systems, Electronic Health Records, Patient Monitoring Systems, Automated Dispensing Systems Application: Clinical Workflow Automation, Claims Processing, Patient Scheduling, Inventory Management, Compliance Tracking End User: Hospitals, Diagnostic Laboratories, Ambulatory Care Centers, Telemedicine Providers, Rehabilitation Facilities Deployment: Cloud-based Solutions, On-Premise Systems, Hybrid Models, Software as a Service, Platform as a Service |
| Companies Covered | UiPath, Merative, Medtronic, Biofourmis, Notable, Teladoc Health, Qventus, Enlitic, Tempus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Automation Market Shifts & Advancements
Automation architectures are bifurcating between cloud-native platforms and edge-deployed inference engines, with regulatory divergence between Washington and Brussels forcing vendors to maintain parallel compliance stacks.
Generative AI is hybridizing clinical documentation workflows, automating ambient listening for provider-patient encounters and auto-populating structured electronic health record fields. Large hospital networks in the United States pilot these tools to reduce physician administrative burden. The technology is compressing documentation time from fifteen minutes per encounter to under two minutes, reallocating clinician capacity to direct patient care.
The EU AI Act's risk-classification framework imposes mandatory post-market surveillance for high-risk clinical decision support systems, requiring algorithmic performance monitoring across diverse patient populations. Medical device manufacturers must maintain technical documentation and quality management systems exceeding MDR requirements. German hospital procurement departments now prioritize vendors with established conformity assessment credentials.
Subscription-based automation licensing is displacing perpetual software purchases across North American health systems, unbundling implementation and training costs from core platform fees. Integrated delivery networks negotiate enterprise-wide robotic process automation contracts with usage-based pricing tiers. This shift concentrates purchasing power among systems with sufficient scale to justify dedicated automation centers of excellence.
Global Healthcare Automation Market Segmentation
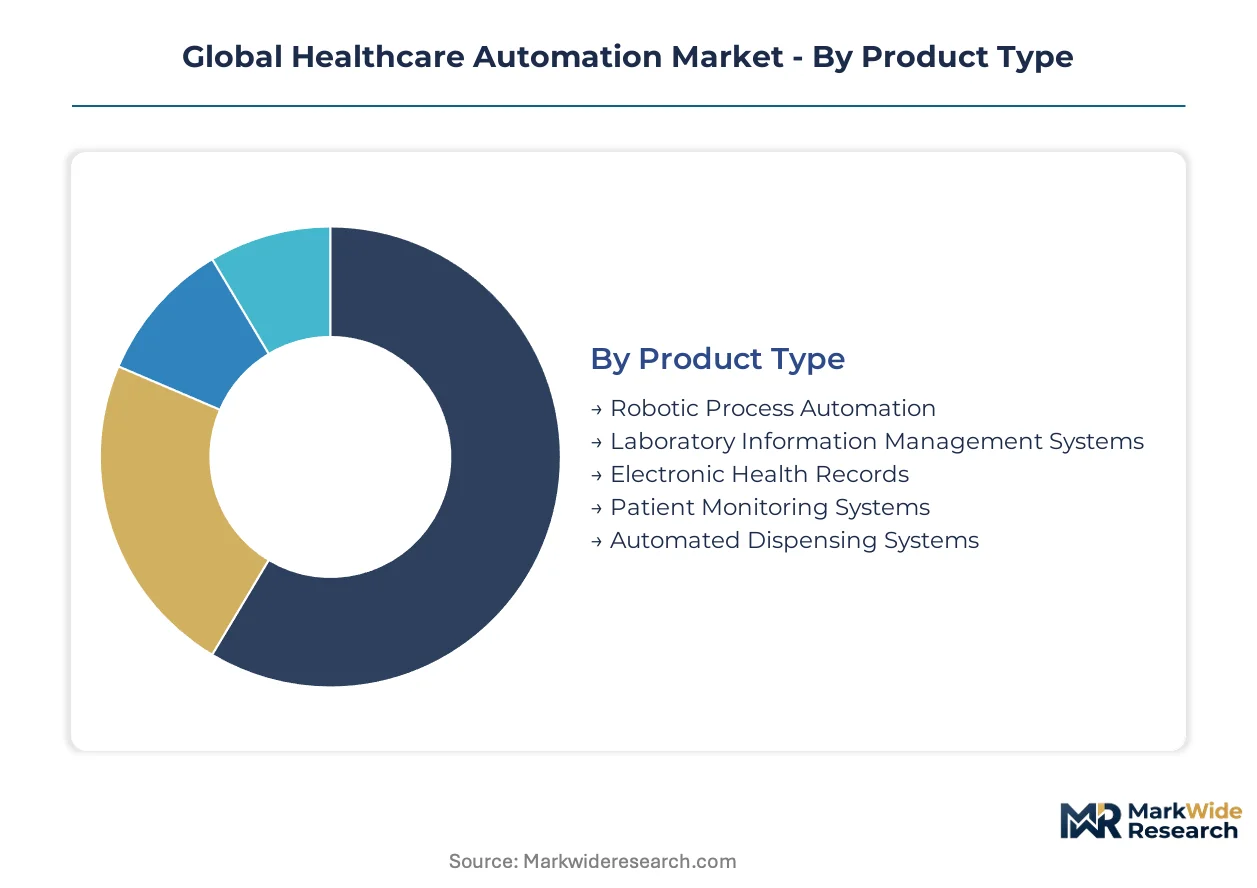
Automation architectures in healthcare diverge sharply across product types and deployment modes, with regulatory compliance requirements and interoperability standards fragmenting vendor roadmaps. Procurement decisions increasingly hinge on whether health systems prioritize real-time cloud scalability or legacy EHR integration.
Product Type:
Cost tier determines adoption velocity, with high-capital equipment facing longer procurement cycles than software-centric alternatives.
- Robotic Process Automation:Software bots execute repetitive administrative tasks including claims adjudication and prior authorization processing. Large hospital networks in the United States deploy UiPath and Automation Anywhere platforms to offset revenue-cycle staffing gaps.
- Patient Monitoring Systems:Continuous physiological sensors feed predictive analytics engines for early warning scoring. German hospital procurement departments prioritize vendors with EU AI Act conformity assessments for high-risk clinical decision support.
- Laboratory Information Management Systems:Specimen tracking and workflow orchestration platforms streamline pathology operations.
- Electronic Health Records:Core clinical data repositories with embedded automation modules for order entry and documentation.
- Automated Dispensing Systems:Robotic medication storage and retrieval units with barcode verification.
Robotic Process Automation holds installed capacity. Patient Monitoring Systems is rotating up the share rankings.
Application:
Application focus separates clinical-facing deployments from back-office efficiency plays, with divergent compliance obligations.
- Clinical Workflow Automation:Algorithmic task routing and decision support embedded within provider-facing interfaces. Academic medical centers in Japan leverage METI smart hospital incentives to fund perioperative workflow integration.
- Claims Processing:Automated eligibility verification, coding validation, and denial management for revenue-cycle operations. Indian diagnostic laboratory networks deploy RPA to accelerate third-party payer reimbursements.
- Patient Scheduling:Intelligent appointment optimization with predictive no-show modeling.
- Inventory Management:Automated supply chain tracking for pharmaceuticals and medical devices.
- Compliance Tracking:Audit trail generation and regulatory reporting automation.
Claims Processing dominates transaction volume. Clinical Workflow Automation is gaining share fastest.
End User:
Customer type dictates contract structure, with integrated delivery networks negotiating enterprise terms versus point solutions for standalone facilities.
- Hospitals:Inpatient and emergency department automation spanning clinical and administrative domains. German hospital network consolidation drives centralized procurement of robotic process automation across revenue-cycle operations.
- Telemedicine Providers:Cloud-native platforms for virtual consultation scheduling and remote patient monitoring. United States-based asynchronous care platforms automate intake triage and documentation to extend specialist reach.
- Diagnostic Laboratories:High-throughput specimen processing and AI-augmented histopathology.
- Ambulatory Care Centers:Point-of-care workflow optimization for outpatient procedures.
- Rehabilitation Facilities:Therapy scheduling and outcomes tracking automation.
Hospitals anchor procurement spend. Telemedicine Providers are climbing the fastest.
Deployment:
Maturity of cloud infrastructure separates early adopters from health systems with fragmented legacy estates resisting full migration.
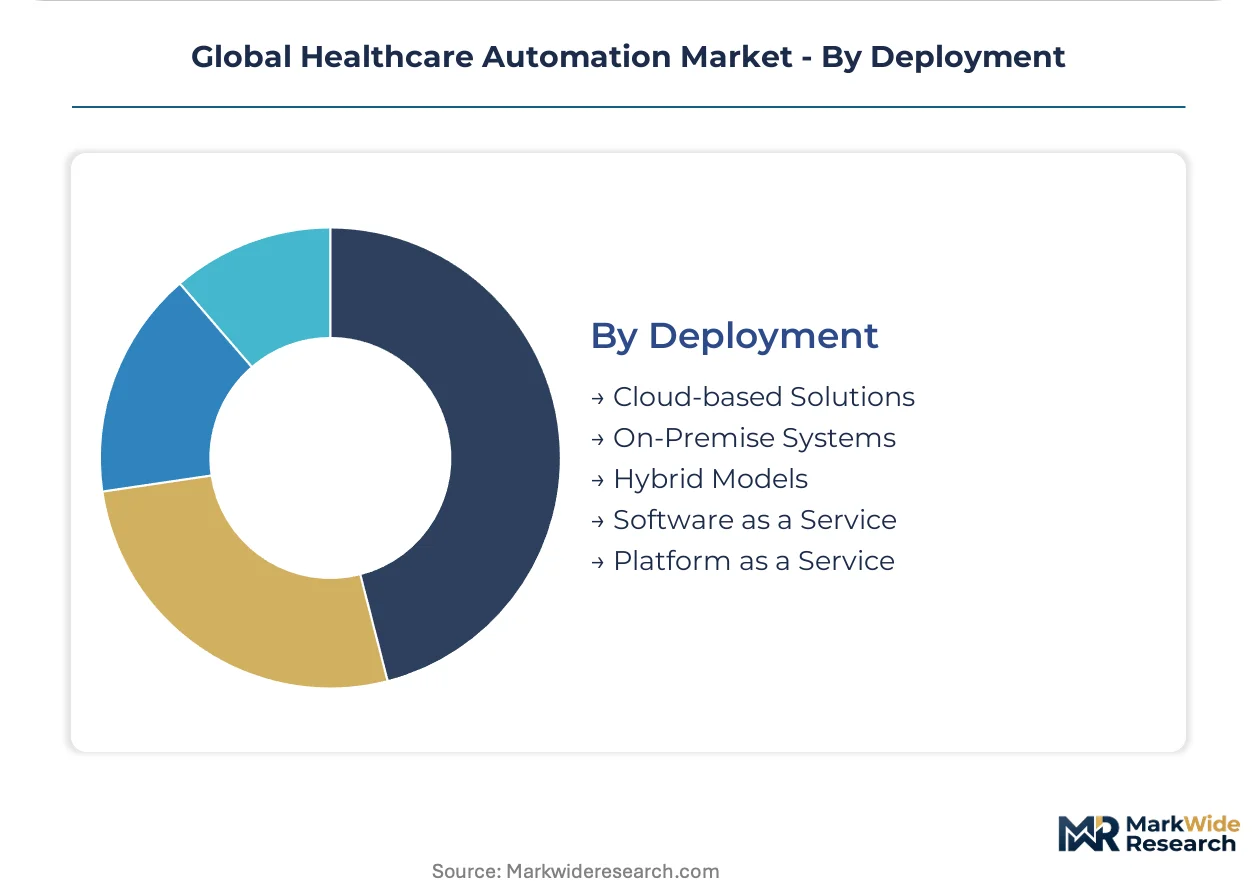
- Cloud-based Solutions:Fully managed SaaS platforms with ISO 27001-certified infrastructure and automatic updates. North American health systems favor these for rapid deployment without capital expenditure.
- Hybrid Models:Split architectures preserving sensitive data on-premise while leveraging cloud analytics. Academic medical centers with decades-old EHR fragmentation retain this approach to manage interoperability risk.
- On-Premise Systems:Self-hosted automation platforms requiring dedicated IT infrastructure.
- Software as a Service:Subscription licensing with usage-based pricing tiers.
- Platform as a Service:Developer environments for custom automation workflow construction.
Cloud-based Solutions command new deployment share. Hybrid Models retain defensive positioning in academic settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automation vendors export robotic process automation platforms to United States hospital networks seeking revenue-cycle efficiency. This transatlantic trade corridor shapes procurement patterns across both markets.
United States
Hospital networks in Texas and Florida deploy cloud-native automation to offset nursing shortages and accelerate claims adjudication. FDA digital health pre-certification streamlines algorithmic tool deployment for clinical decision support systems. The Greater Boston cluster concentrates AI-driven diagnostic startups targeting FDA breakthrough device designation.
Germany
Integrated hospital systems automate revenue-cycle operations to address administrative labor gaps across North Rhine-Westphalia and Bavaria. EU AI Act conformity assessments create compliance moats for established vendors serving high-risk clinical decision support markets. Berlin-Brandenburg anchors health technology procurement for centralized hospital network consolidation.
Japan
Smart hospital infrastructure incentives from METI accelerate surgical workflow integration in perioperative care facilities. PMDA software-as-medical-device determinations govern machine learning-based diagnostic tool deployment timelines. The Kansai region around Osaka concentrates connected device ecosystem development for aging population care.
India
Diagnostic laboratory networks in Maharashtra and Karnataka automate specimen processing to accelerate third-party payer reimbursements. CDSCO medical device regulations shape algorithmic validation requirements for AI-augmented histopathology tools. The Delhi-NCR corridor concentrates health technology implementation for underpenetrated pathology networks.
United Kingdom
NHS integrated care systems pilot robotic process automation for patient scheduling and clinical documentation workflows. MHRA software medical device guidance aligns with EU AI Act risk-classification frameworks post-Brexit. The London-Southeast cluster concentrates telemedicine platform development for virtual consultation automation.
Global Healthcare Automation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented automation architectures. Large hospital networks consolidate purchasing power through enterprise-wide contracts, while academic medical centers retain hybrid deployment preferences. Three archetypes dominate: cloud-native platform vendors, connected device ecosystem integrators, and AI-driven workflow optimization specialists. Competitive moves concentrate on strategic partnerships bridging legacy EHR interoperability gaps and M&A targeting algorithmic transparency capabilities.
Among United States-based automation vendors, UiPath and Qventus occupy distinct positioning within the competitive structure. UiPath exemplifies the robotic process automation archetype serving administrative workflow efficiency. Qventus represents AI-driven operational throughput optimization for patient flow management. Medtronic anchors the connected medical device ecosystem segment with surgical workflow integration capabilities. These three entities illustrate the tripartite competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| UiPath |
| Merative |
| Medtronic |
| Biofourmis |
| Notable |
| Teladoc Health |
| Qventus |
| Enlitic |
| Tempus |
| Others |
Supply & Pricing Matrix
Undercapacity in ISO 27001-certified cloud infrastructure across North American health systems is compressing deployment timelines and elevating vendor pricing power for compliant automation platforms. This utilization squeeze simultaneously tightens margins for legacy on-premise integrators and rewards cloud-native suppliers with certified security stacks.
Pricing Analysis
Next-generation AI-augmented clinical documentation tools command substantial premiums over prior-generation robotic process automation bots, while current-generation hybrid deployment models occupy a contracting middle tier. Three-tier pricing structure across premium, standard, and economy levels separates FDA pre-certified algorithmic platforms from CE-marked European alternatives and uncertified point solutions. Cost compression in the economy tier is intensifying because Indian diagnostic laboratories and Southeast Asian hospital networks prioritize lowest-unit-cost procurement over compliance depth. Telemedicine providers exhibit the highest price sensitivity due to thin reimbursement margins, while German integrated hospital networks demonstrate lowest sensitivity given EU AI Act conformity requirements.
Supply Chain Analysis
Export controls on GPU accelerators and advanced semiconductor components under United States Commerce Department restrictions are constraining supply flows for machine learning inference engines deployed in patient-facing diagnostic tools. Manufacturing concentrates in Taiwan for specialized medical-grade sensors, the United States for cloud infrastructure hardware, and Germany for precision robotic dispensing systems. Component sourcing draws from South Korean memory modules, Japanese optical sensors, and Chinese rare-earth magnets for motor assemblies. Single-source vulnerability in Taiwan semiconductor foundries poses structural risk for real-time patient monitoring device production. Distribution runs through GPO contracts for United States hospital networks and direct enterprise sales for European integrated delivery systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vendors with entrenched regulatory certifications that create switching costs exceeding implementation expenses for hospital procurement committees. Network effects concentrate among platforms achieving critical mass in HL7 FHIR interoperability, locking in data exchange advantages.
For Market Incumbents: Entrench FDA pre-certification pathways and EU AI Act conformity credentials as defensive barriers against cloud-native challengers. Acquire algorithmic transparency capabilities through targeted capability purchases rather than organic development to compress compliance timelines. Vertical integration into edge-computing hardware for perioperative settings secures supply continuity against semiconductor export restrictions. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated diagnostic laboratory automation segment where CDSCO regulatory requirements remain less stringent than FDA or EMA pathways. Target pathology specimen processing workflows in Maharashtra and Karnataka where incumbent RPA penetration lags revenue-cycle automation by several years. Pursue white-label partnerships with existing GPO contract holders to bypass direct hospital sales cycle friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cloud-native automation platforms as ISO 27001 certification and EU AI Act conformity assessment costs compound. Acquisition targets should demonstrate established conformity credentials in high-risk clinical decision support classifications rather than administrative workflow tools. Monitor FDA software-as-medical-device determination velocity as the critical inflection signal for machine learning diagnostic tool valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Accelerates algorithmic deployment for United States hospital network contracts against non-certified competitors. |
| EU AI Act Conformity Assessment | Creates procurement preference in German integrated hospital systems consolidating revenue-cycle operations. |
| Hospital System Partnership | Locks in multi-year enterprise RPA contracts with usage-based pricing tiers for integrated delivery networks. |
| Software Companion Development | Extends connected device ecosystems into perioperative workflow integration for METI incentive capture in Japan. |
| HL7 FHIR Interoperability Investment | Enables real-time data exchange with legacy EHR architectures resisting full cloud migration. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, clinical informaticists, biomedical engineers, GPO contracts managers, and regulatory affairs leads at automation vendors and refined through secondary validation. Primary research incorporated structured interviews and procurement database analysis. Secondary sources encompassed FDA 510(k) filings, EU MDR technical documentation, CMS Medicare claims data, hospital GPO contract repositories, and CDSCO medical device registration records. Bottom-up segmentation modeling triangulated against top-down market sizing across deployment modes and end-user categories.
Demand-supply balance modeling anchored forecast outputs, with installed base growth rates for robotic process automation cross-referenced against cloud infrastructure capacity expansion across the analysis window. Segmentation dimensions encompassed product type, application focus, end-user category, and deployment architecture. CAGRs derived from logistic diffusion curves for technology adoption, adjusted for regulatory approval timeline variability. Forecast inputs incorporated FDA pre-certification pathway throughput assumptions and EU AI Act conformity assessment queue projections.
Stress conditions across FDA software-as-medical-device determination delays, EU AI Act third-party auditor capacity constraints, and Taiwan semiconductor foundry utilization rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding interoperability standard adoption velocity and cloud security certification timeline normalization. Material shifts in United States export control scope for GPU accelerators or EU AI Act high-risk classification expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
UV Curing System Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Monitor Arm Market
Industrial Automation
Industrial Fieldbus Solution Market