
 Global App Builder Software Market | 2026-2036
Global App Builder Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global App Builder Software Market Foresight
Mid-market enterprise buyer concentration is pivoting as fragmented departmental procurement consolidates into centralized IT governance. SAP Build Apps leverages its ERP integration depth to anchor large manufacturing accounts. Bubble competes on visual programming flexibility for startups and agencies. FlutterFlow specializes in mobile-native output and controls the cross-platform build layer for design-led teams.
App builder software encompasses visual development environments that translate drag-and-drop interface composition into deployable application code, typically emitting React, Flutter, or native iOS/Android binaries through automated build pipelines. The primary commercial purpose is collapsing the time between business requirement definition and production software delivery, compressing cycles that previously required dedicated engineering squads. Cloud-Based deployment leads solution type adoption because subscription elasticity aligns with variable project pipelines. No-Code Platform growth outpaces Low-Code alternatives among line-of-business users lacking formal programming training. Enterprise Workflow Automation captures the deepest margin pools as these implementations require custom integration services and ongoing governance tooling.
FDA scrutiny of clinical trial data integrity shapes validation requirements for healthcare apps built on these platforms, while EU GDPR and the EU AI Act impose algorithmic transparency and data residency obligations that vendors must architect around. The FCC's evolving broadband infrastructure standards indirectly expand the addressable market by improving last-mile connectivity for field-deployed applications. Stakeholders must monitor how national data sovereignty laws fragment cloud hosting strategies and force multi-region compliance engineering.
Market Dynamics
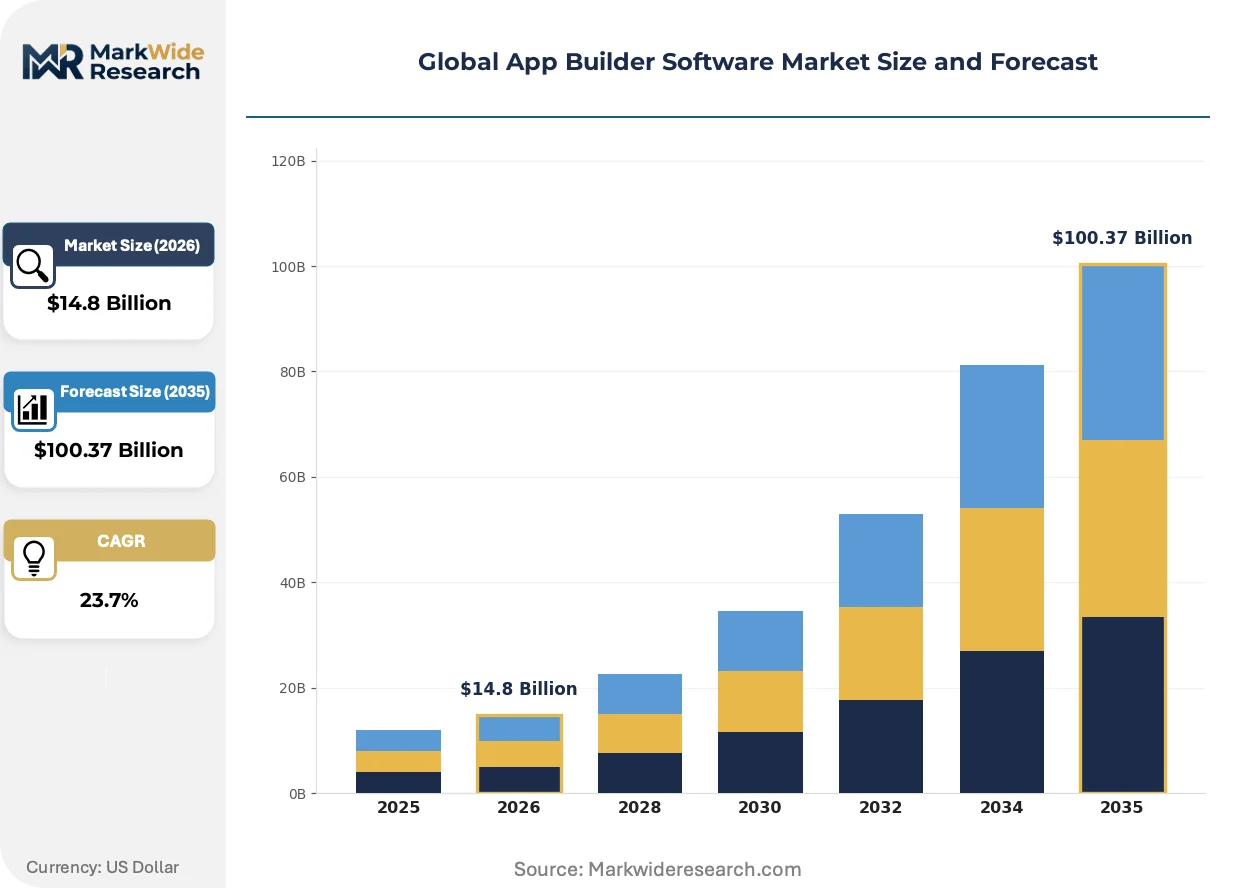
Enterprise workflow automation consolidation is compressing procurement cycles as mid-market manufacturers centralize departmental app spending under IT governance mandates. This structural shift rewards platforms with deep ERP integration and multi-tenant compliance architectures.
Growth Catalysts
- EU AI Act Algorithmic Transparency:European buyers now require auditable low-code platforms for automated decision systems, accelerating procurement of governance-ready tools in Germany and France.
- Citizen-Developer Workforce Expansion:India, Germany, and the United States are scaling internal app-building programs that bypass traditional engineering queues.
- Clinical Trial Data Integrity:FDA validation requirements for healthcare apps are pushing pharmaceutical sponsors toward pre-validated build environments that accelerate submission timelines.
Market Restraints
- Multi-Region Hosting Fragmentation:National data sovereignty laws in China, Russia, and Indonesia force vendors to engineer separate compliance stacks, raising operational overhead.
- Legacy System Integration Debt:SAP and Oracle ERP instances require custom connector development that extends implementation timelines and inflates professional services costs.
- Flutter/React Native Skill Scarcity:Visual platform output still demands native debugging expertise that mid-market IT departments struggle to retain.
Strategic Opportunities
- India Manufacturing Automation:PLI scheme incentives for domestic electronics and automotive producers are creating first-mover advantages for workflow automation vendors.
- CSRD Sustainability Reporting:EU Corporate Sustainability Reporting Directive mandates are driving demand for carbon-tracking applications built on auditable low-code foundations.
- Edge-Cloud Convergence:5G field deployment apps combining local processing with centralized governance are opening new use cases in utilities and logistics.
Industry Challenges
- Governance Tooling Talent Gap:Organizations lack personnel to administer role-based access controls and audit trails across proliferating citizen-built applications.
- Cross-Platform Certification Burden:Healthcare and financial services apps require simultaneous ISO 27001, SOC 2, and sector-specific validations that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global App Builder Software Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $100.37 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Solution Type: Low-Code Platform, No-Code Platform, Rapid Application Development, Integrated Development Environment Use Case: Enterprise Workflow Automation, Customer Engagement, Field Service Management, Internal Collaboration Tools End User Industry: Financial Services, Education Services, Government Agencies, Manufacturing Sector |
| Companies Covered | Softr, SAP Build Apps, Bubble, AppGyver, Bildr, WeWeb, Adalo, Draftbit, FlutterFlow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global App Builder Software Market Shifts & Advancements
Generative AI code synthesis is absorbing traditional visual programming workflows, compressing the boundary between natural language specification and deployable application binaries. This convergence is redrawing competitive moats around inference infrastructure and prompt governance tooling.
Large language model copilots embedded within visual builders are absorbing routine logic construction tasks previously requiring manual component configuration. Manufacturing and logistics teams in Germany and the United States are adopting these interfaces fastest, cutting initial prototype cycles from weeks to hours. The structural consequence is that platform differentiation is absorbing toward data integration depth rather than front-end composition speed.
GDPR Article 22 automated decision safeguards and EU AI Act high-risk system obligations are forcing vendors to embed explainability dashboards and human-in-the-loop checkpoints. Healthcare and financial services deployments face the steepest compliance engineering requirements. German automotive suppliers and French insurers are currently the most advanced in mandating these architectural features during procurement.
Line-of-business buyers are consolidating fragmented departmental subscriptions into enterprise-wide platform contracts with centralized governance. The channel being disrupted is direct self-serve procurement through individual credit cards. This pattern is most visible in United States mid-market manufacturers where CFO mandates now require IT approval for any workflow automation spend above departmental thresholds.
Global App Builder Software Market Segmentation
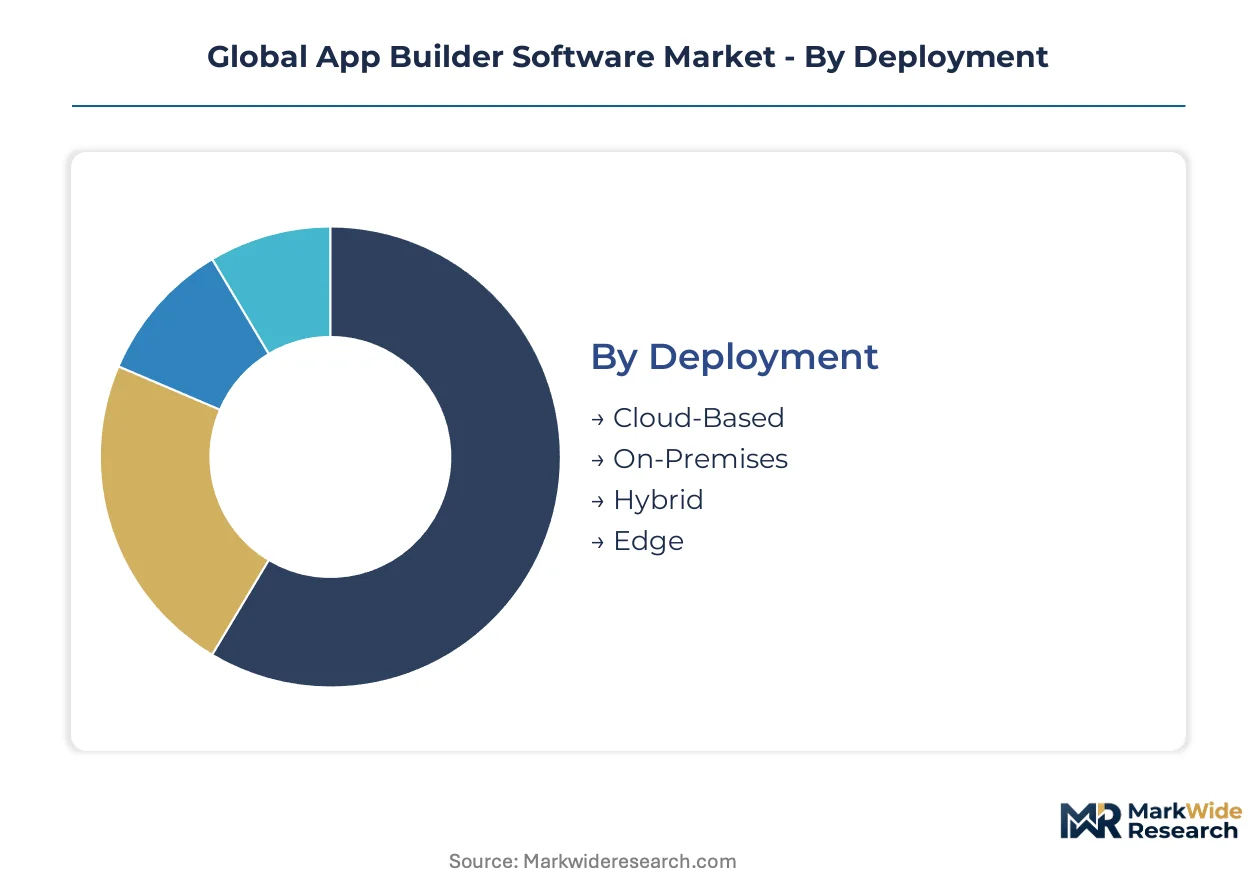
Deployment architecture determines compliance posture and margin structure for app builder vendors. Solution type alignment shapes buyer procurement authority and implementation timelines. Use case concentration reveals where workflow automation delivers measurable ROI versus experimental adoption.
Deployment:
Supply concentration in hyperscale infrastructure is compressing vendor hosting economics and forcing multi-region compliance engineering.
- Cloud-Based:Subscription elasticity aligns with variable project pipelines at mid-market manufacturers. Demand concentrates in Germany and the United States where IT governance mandates now require centralized procurement of cloud-native platforms over departmental credit-card subscriptions.
- On-Premises:Air-gapped environments serve financial services and government agencies with data residency requirements. German automotive suppliers and French insurers mandate these deployments for EU AI Act high-risk system compliance, extending sales cycles but deepening annual contract values.
- Hybrid:Combines centralized governance with edge processing for field service applications.
- Edge:Local execution for utilities and logistics with intermittent connectivity.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution Type:
Cost tier stratification separates enterprise governance investments from line-of-business self-serve experiments.
- No-Code Platform:Visual builders with zero coding requirements target citizen-developers in India and the United States. Manufacturing teams in these countries deploy internal collaboration tools fastest, bypassing traditional engineering queues entirely.
- Low-Code Platform:Extensible frameworks allowing custom scripting for IT governance mandates. German and French buyers require auditable foundations for automated decision systems under GDPR Article 22 and EU AI Act obligations.
- Rapid Application Development:Compressed prototyping cycles for agencies and startup validation.
- Integrated Development Environment:Full-code control for specialized compliance engineering.
Today's leader: Low-Code Platform. Tomorrow's challenger: No-Code Platform.
Use Case:
Application maturity correlates with measurable ROI documentation and procurement centralization speed.
- Enterprise Workflow Automation:Deep ERP integration captures the steepest margin pools through custom connector development and ongoing governance tooling. Mid-market manufacturers in Germany and the United States consolidate departmental spending here under CFO mandates.
- Customer Engagement:Mobile-native output for design-led teams requiring cross-platform build layers.
- Field Service Management:5G deployment apps combining local processing with centralized oversight.
- Internal Collaboration Tools:Citizen-built productivity applications proliferating fastest in India.
Today's leader: Enterprise Workflow Automation. Tomorrow's challenger: Field Service Management.
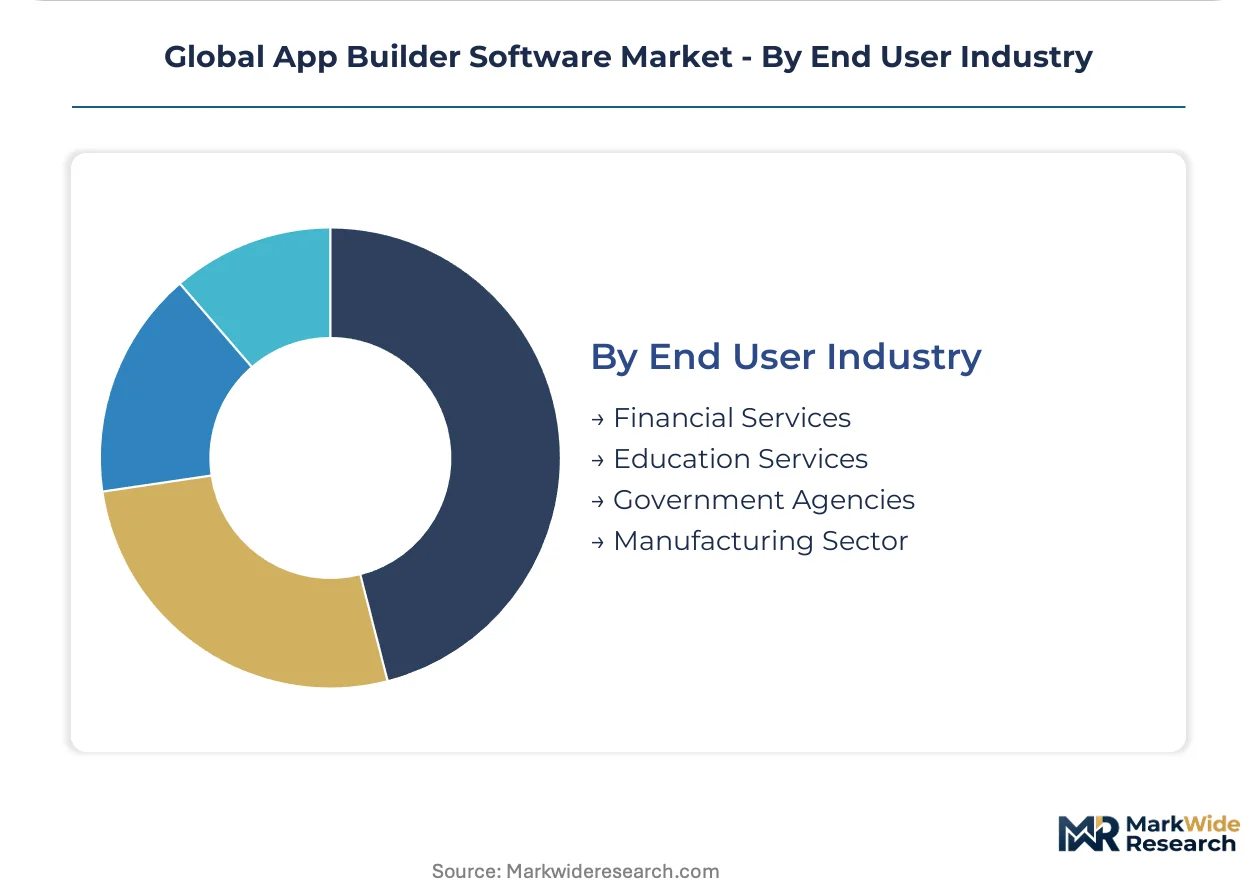
End User Industry:
Regulatory burden intensity shapes platform selection criteria and validation timeline expectations.
- Financial Services:ISO 27001, SOC 2, and sector-specific certifications delay revenue recognition. French insurers and German banks mandate explainability dashboards and human-in-the-loop checkpoints for automated decision systems.
- Manufacturing Sector:PLI scheme incentives in India create first-mover advantages for domestic electronics and automotive producers deploying workflow automation.
- Government Agencies:Data sovereignty requirements favor on-premises or hybrid deployments with multi-tenant compliance architectures.
- Education Services:Budget-constrained adoption concentrating on no-code self-serve models.
Today's leader: Financial Services. Tomorrow's challenger: Manufacturing Sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's manufacturing automation push contrasts with India's citizen-developer workforce expansion, yet both markets concentrate procurement under centralized IT governance mandates. Regulatory divergence between EU algorithmic transparency requirements and US clinical validation standards fragments vendor compliance engineering.
United States
Mid-market manufacturers consolidate departmental app spending under CFO-mandated IT approval thresholds. FDA validation requirements for healthcare apps push pharmaceutical sponsors toward pre-validated build environments. Boston and San Francisco clusters anchor demand for rapid prototyping tools among biotech startups.
Germany
Automotive suppliers mandate explainability dashboards and human-in-the-loop checkpoints for automated decision systems. EU AI Act high-risk system obligations and GDPR Article 22 safeguards extend sales cycles but deepen contract values. Bavaria's industrial belt leads adoption of ERP-integrated workflow automation.
India
PLI scheme incentives for domestic electronics and automotive producers create first-mover advantages for manufacturing automation vendors. BIS standards and RBI data localization requirements shape platform selection criteria. Karnataka and Maharashtra host the largest citizen-developer training programs bypassing traditional engineering queues.
France
French insurers and banks require auditable low-code foundations for automated underwriting and risk scoring systems. CNIL enforcement of GDPR automated decision safeguards accelerates procurement of governance-ready platforms. Paris and Lyon financial services clusters drive premium-tier platform adoption.
United Kingdom
Post-Brexit regulatory divergence complicates EU AI Act alignment for UK-headquartered enterprises with continental operations. FCA guidelines on algorithmic trading transparency extend to internal workflow automation tools. London's fintech density sustains demand for rapid application development environments.
Global App Builder Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architectures and compliance postures. SAP Build Apps leverages ERP integration depth to anchor large manufacturing accounts, while visual programming specialists capture design-led agency workflows. Three archetypes dominate: enterprise governance platforms, citizen-developer tools, and mobile-native builders. Consolidation pressure intensifies through strategic partnerships and geographic licensing arrangements rather than outright acquisition.
Among pure-play specialists, Bubble and FlutterFlow occupy distinct positioning vectors. Bubble exemplifies the visual programming flexibility archetype for startup and agency segments. FlutterFlow anchors the mobile-native output tier controlling cross-platform build layers. Softr represents the no-code self-serve model proliferating among line-of-business users lacking formal programming training. Each sits within a defensible niche as procurement centralization favors governance depth over composition speed.
| Leading Market Players |
|---|
| Softr |
| SAP Build Apps |
| Bubble |
| AppGyver |
| Bildr |
| WeWeb |
| Adalo |
| Draftbit |
| FlutterFlow |
| Others |
Supply & Pricing Matrix
Hyperscale cloud compute pricing indices cascading through infrastructure-as-a-service tiers compress vendor hosting economics and force three-tier pricing stratification across premium governance, standard self-serve, and economy citizen-developer levels.
Pricing Analysis
Capacity additions in India and Germany are reshaping price floors for citizen-developer tooling, compressing entry-level subscription tiers. SaaS-tiered pricing dominates, with differentiation anchored in ISO 27001 certification grade and ERP connector depth. Pricing pressure stems from open-source visual builder alternatives eroding mid-market accounts. Departmental buyers in United States manufacturing show highest price sensitivity; German automotive suppliers accept premium tiers for EU AI Act compliance.
Supply Chain Analysis
GPU inference capacity rests on Taiwan Semiconductor Manufacturing, NVIDIA silicon supply, and United States hyperscaler datacenter buildouts. Critical dependencies include cloud orchestration software, pre-trained model weights, and low-latency edge node hardware. Single-source vulnerability concentrates in NVIDIA AI accelerator supply. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in app builder software hinges on governance tooling premiumization as compliance engineering costs shift from buyer professional services to vendor recurring revenue.
For Market Incumbents: Deploy ERP connector ecosystems as defensive moats against SAP Build Apps integration depth. Consolidate fragmented departmental subscriptions under centralized IT governance contracts to counter Bubble and FlutterFlow self-serve growth. Deepen vertical integration into pre-validated healthcare build environments to capture FDA-driven pharmaceutical sponsor demand. For New Entrants and Emerging Players: Launch via India PLI scheme manufacturing automation channels to bypass entrenched United States and German incumbent relationships. Target field service management edge-cloud convergence use cases in utilities and logistics where governance requirements remain undefined. Pursue CNIL-aligned explainability dashboard partnerships with French insurers as regulatory wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with no-code platforms possessing native EU AI Act audit trail architecture. Five-to-ten year viability favors vendors combining citizen-developer accessibility with IT governance depth. Watch BIS standards enforcement in India as inflection indicator for manufacturing automation procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep SAP and Oracle ERP connectors anchor large manufacturing accounts in Germany and the United States. |
| Geographic Expansion | India PLI scheme incentives create first-mover manufacturing automation advantages in Karnataka and Maharashtra. |
| Acquisition of Specialist Firm | Governance tooling startups address talent gaps in role-based access control administration. |
| Product Launch | Explainability dashboards satisfy French CNIL and German KBA automated decision system mandates. |
| Strategic Partnership | Hyperscaler marketplace listings compress customer acquisition costs for mid-market manufacturers. |
Research Methodology
Bottom-up enterprise workflow automation modeling reconciled against top-down hyperscaler capex tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combined with secondary validation against SEC filings, App Annie mobile adoption data, hyperscaler infrastructure disclosures, and EU regulatory filings. Triangulation between demand-side deployment timelines and supply-side capacity buildouts calibrates market sizing.
Historical trendline analysis of cloud-native platform adoption patterns anchors projection methodology across deployment model, organization size, vertical integration complexity, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth rate reconciliation against aggregate market boundary conditions. Model inputs incorporate citizen-developer workforce expansion trajectories in India, Germany, and the United States alongside EU AI Act implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA validation requirement enforcement or China data sovereignty law fragmentation. Assumptions reflect current procurement centralization momentum and compliance engineering cost trajectories. A small set of named triggers—BIS standards adoption velocity, CNIL algorithmic transparency enforcement intensity, and PLI scheme disbursement timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Fiber Simulation Software Market
Software & Services
Enterprise Content Management Software Market
Software & Services
Global Custom Software Development Services Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Consignment Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Global AB Testing Software Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Global Retail Management Systems Software Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Cloud-Based ERP Software Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Global Performance Appraisal Software Market
Software & Services
Applicant Tracking System (ATS) Market