
 Home Automation System Market | 2026-2036
Home Automation System Market Size, Share, and Industry Trends Forecast 2026-2036
Home Automation System Market Intelligence
The R&D-to-manufacturing capability gap is reorganizing competitive tiers across the home automation system industry. Johnson Controls leverages its building-automation heritage to dominate commercial-grade climate integration. Amazon sustains consumer-facing voice control through Echo-device ubiquity and Alexa skill breadth. Samsung Electronics anchors whole-home ecosystems via SmartThings platform interoperability with its appliance portfolio.
A home automation system comprises networked controllers, sensors, actuators, and software platforms that manage lighting, climate, security, and entertainment functions through centralized or distributed command architectures. These systems typically operate across 2.4 GHz and 5 GHz wireless bands with latency thresholds below 100 milliseconds for real-time responsiveness, serving residential and commercial properties seeking operational efficiency and occupant convenience. Security systems command premium margins due to recurring monitoring revenue and insurance-mandated installation requirements. Wireless connectivity is displacing wired infrastructure in retrofit applications across aging residential stock. DIY installation is capturing share among tech-savvy millennials purchasing starter kits through e-commerce channels.
The FCC governs radio-frequency emissions for wireless smart-home devices in the United States, while the EU AI Act imposes algorithmic transparency requirements on automated decision-making systems in European deployments. China's MIIT enforces GB standards for IoT device cybersecurity, creating compliance costs for foreign entrants. Stakeholders must monitor evolving interoperability mandates and energy-efficiency labeling rules that will determine platform-level market access and product certification requirements.
Market Dynamics
The Matter protocol standardization is dissolving interoperability barriers across ecosystems, forcing platform providers to compete on service depth rather than lock-in while enabling multi-vendor installations that were previously technically impractical.
Growth Catalysts
- Insurance-mandated security installations:Property insurers in the United States and Germany now require certified smart security systems for premium discounts, creating compulsory demand in high-value residential segments.
- GB standards compliance:China's MIIT cybersecurity mandates for IoT devices are accelerating domestic manufacturing upgrades that export-capable suppliers leverage for competitive positioning.
- Retrofit wireless infrastructure:Mesh networking protocols operating across 2.4 GHz and 5 GHz bands eliminate rewiring costs in aging residential stock, unlocking renovation-driven replacement cycles.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for wireless chipsets concentrates in Taiwan and South Korea, exposing automation vendors to geopolitical disruption and allocation constraints.
- Copper and rare earth volatility:Sensor housings and actuator motors depend on input materials with price swings that compress hardware margins and complicate project bidding.
- EU AI Act algorithmic transparency:Automated decision-making systems in European deployments face documentation burdens that extend certification timelines and raise compliance costs.
Strategic Opportunities
- India smart city integration:Municipal infrastructure projects in Bengaluru and Hyderabad seek building-to-grid automation that residential platform providers can adapt for commercial deployment.
- Aging-in-place healthcare convergence:Fall-detection sensors and medication-adherence hubs merge home automation with remote patient monitoring, opening reimbursement pathways through Medicare Advantage plans.
- DIY channel expansion:E-commerce starter kits targeting tech-savvy millennials bypass professional installer networks, capturing margin that previously flowed to systems integrators.
Industry Challenges
- Embedded systems firmware expertise:The shortage of engineers fluent in real-time operating systems and sub-100-millisecond latency optimization constrains product development velocity.
- Legacy HVAC integration complexity:Proprietary control buses from established climate equipment manufacturers resist standardized API adoption, forcing costly gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Automation System Market |
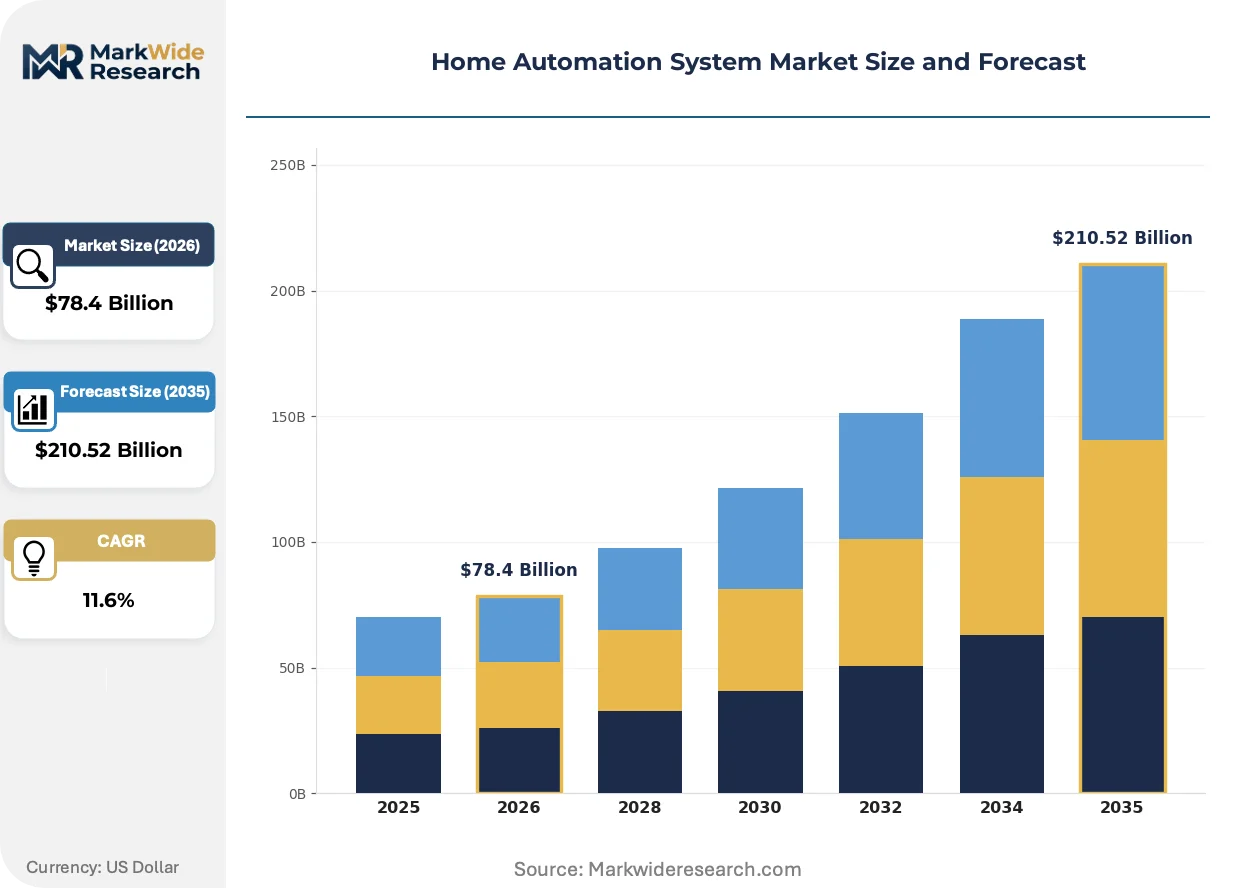
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $210.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control, Security Systems, HVAC Control, Entertainment Systems Technology: Wireless, Wired, Bluetooth, Z-Wave End User: Residential, Commercial, Industrial, Retail Installation Type: DIY, Professional, Integrated, Standalone |
| Companies Covered | Johnson Controls, Schneider Electric, Siemens, Honeywell International, Amazon, Alphabet, Samsung Electronics, Apple, ADT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Automation System Market Strategic Shifts & Innovations
Protocol convergence and edge computing architectures are redistributing intelligence between cloud platforms and local controllers, altering where value capture occurs in the technology stack.
Thread networking is fragmenting the connectivity landscape by enabling IP-native device communication without Wi-Fi power consumption. Luxury housing developers in Dubai and Miami are specifying Thread-certified lighting and climate nodes for new construction. This topology is fragmenting hub-centric architectures into distributed mesh configurations that reduce single points of failure.
The EU AI Act imposes algorithmic transparency requirements on automated decision-making systems in European deployments. Home automation vendors must now document training data provenance and decision logic for occupancy-prediction algorithms. Germany and France are experiencing the steepest compliance cost increases as national regulators issue implementing guidance ahead of enforcement deadlines.
Millennial buyers are consolidating purchasing authority for starter-home automation through direct-to-consumer channels. Big-box retailers and specialty e-commerce platforms are displacing traditional security dealer networks for entry-tier sensor and camera sales. This channel rotation is most pronounced in the United States, where Amazon and Best Buy capture growing share of first-time smart home acquisitions.
Home Automation System Market Segmentation
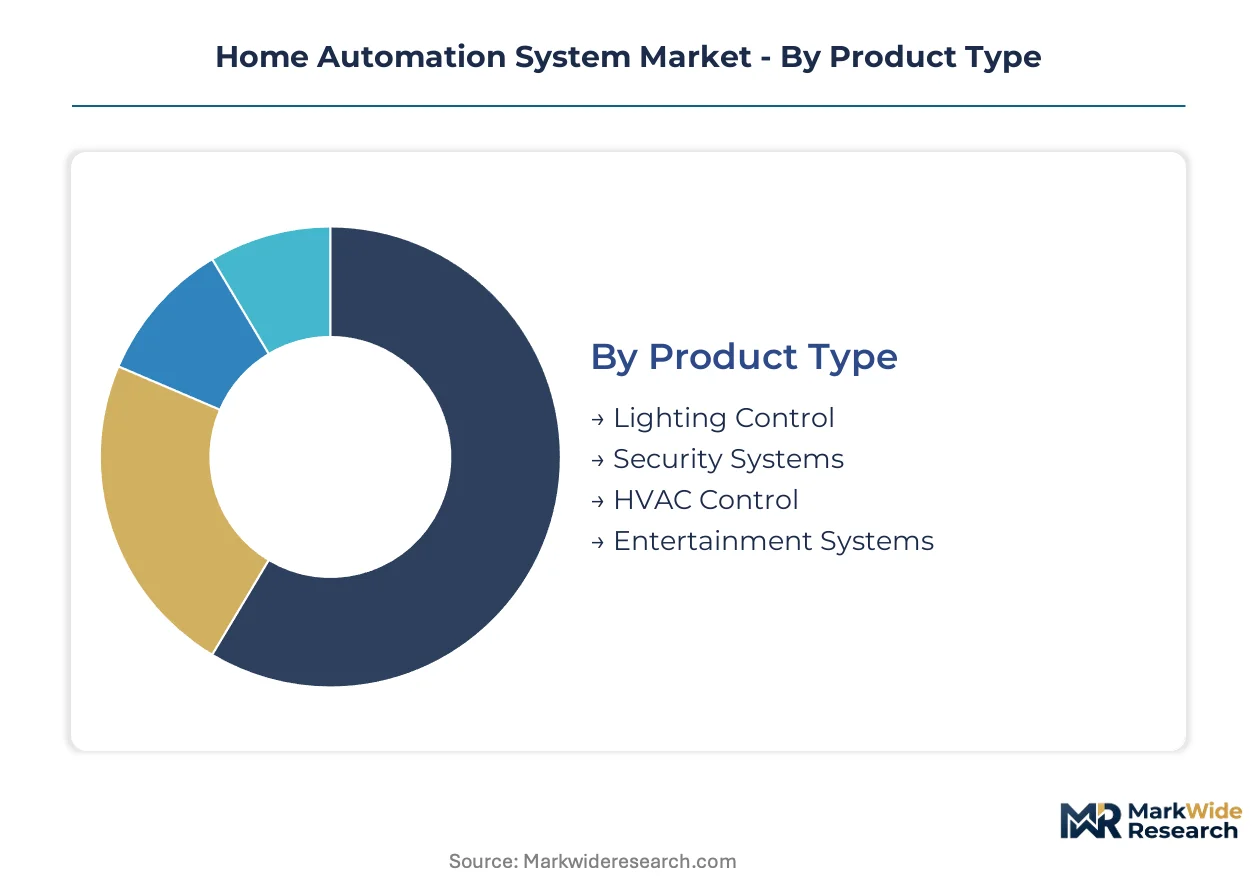
Home automation system vendors must navigate divergent certification requirements and latency thresholds across product categories. Segmentation reveals where regulatory compliance costs concentrate and which installation modes unlock retrofit opportunities in aging housing stock.
Product Type:
FCC Part 15 governs radio-frequency emissions for wireless lighting and security nodes in the United States, while the EU AI Act imposes algorithmic transparency mandates on automated HVAC decision systems in European deployments.
- Lighting Control:Dimmable LED drivers and circadian-tuning algorithms operate across 2.4 GHz mesh networks with sub-50-millisecond response times. Demand clusters in Dubai and Miami luxury developments where Thread-certified nodes are specified for new construction.
- Security Systems:Integrated sensor arrays combining motion detection, glass-break acoustics, and video analytics command recurring monitoring revenue streams. German and US property insurers now mandate certified installations for premium discounts, creating compulsory demand in high-value residential segments.
- HVAC Control:Smart thermostats and zone-damper actuators interface with proprietary control buses from established climate equipment manufacturers.
- Entertainment Systems:Multi-room audio distribution and unified remote platforms consolidate fragmented media hardware.
Established volume favors Lighting Control; emerging adoption favors Security Systems.
Technology:
Cost tier differentiation separates enterprise-grade wired infrastructure from consumer wireless deployments, with hybrid architectures emerging in mid-market commercial retrofits.
- Wireless:Wi-Fi and proprietary mesh protocols operating across 2.4 GHz and 5 GHz bands eliminate rewiring costs in aging residential stock. China's MIIT enforces GB standards for IoT cybersecurity that accelerate domestic manufacturing upgrades among export-capable suppliers.
- Wired:Ethernet and powerline carrier systems deliver deterministic latency below 10 milliseconds for commercial building automation. Germany's KBA-equivalent building codes and France's CNIL-equivalent data handling rules impose stricter electromagnetic compatibility testing than US FCC requirements.
- Bluetooth:Low-energy beacon networks enable proximity-based scene triggering with minimal power draw.
- Z-Wave:Sub-GHz mesh topology penetrates walls more effectively than 2.4 GHz alternatives in dense urban construction.
Retrofit applications favor Wireless; new construction specifications favor Wired.
End User:
Customer type determines whether procurement flows through systems integrators or direct-to-consumer channels, with corresponding margin capture shifts.
- Residential:Single-family and multifamily dwellings drive starter-kit volumes through Amazon and Best Buy e-commerce channels. Millennial buyers consolidating purchasing authority bypass traditional security dealer networks for entry-tier sensor sales.
- Commercial:Office buildings and hospitality properties require BACnet integration and centralized facility management dashboards. Johnson Controls leverages building-automation heritage to dominate climate integration in this segment.
- Industrial:Manufacturing facilities and warehouses demand ruggedized actuators with IP65+ ingress protection.
- Retail:Point-of-sale integration and customer traffic analytics merge automation with loss prevention.
Volume concentration favors Residential; margin expansion favors Commercial.
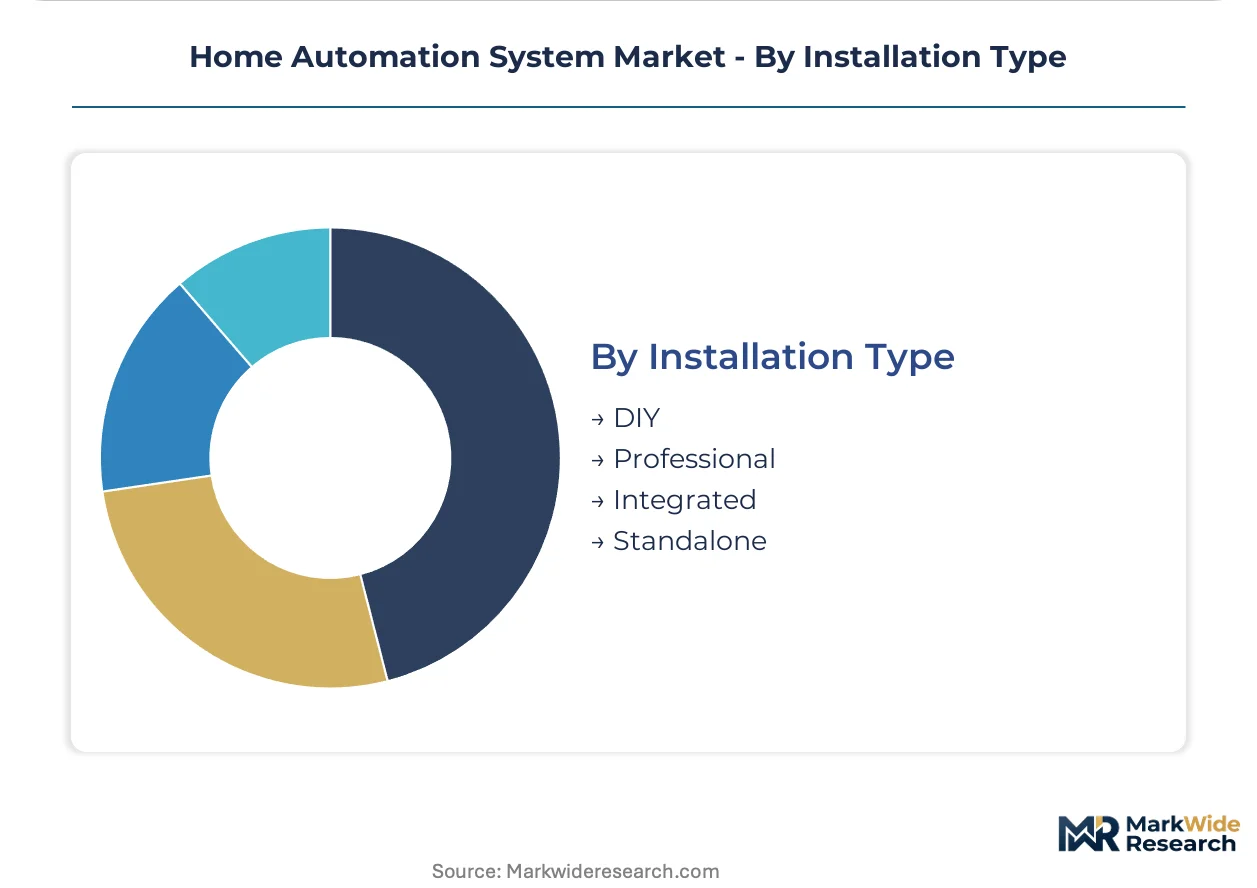
Installation Type:
Supply concentration in semiconductor fabrication shapes which installation modes can scale, with DIY kits most exposed to Taiwan and South Korea chip allocation constraints.
- DIY:Pre-configured starter kits with smartphone-guided setup capture margin previously flowing to systems integrators. Best Buy and Amazon displace professional installer networks for first-time smart home acquisitions in the United States.
- Professional:Certified technician deployment ensures code compliance and warranty validity for insurance-mandated security installations. Germany's regulatory complexity and France's CNIL-equivalent data documentation burdens extend certification timelines for automated decision systems.
- Integrated:Whole-home ecosystems anchor customer lifetime value through platform interoperability.
- Standalone:Single-function devices operate without hub dependencies for rental and temporary applications.
Channel rotation favors DIY; compliance complexity favors Professional.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. The United States prioritizes insurance-linked security installations and voice-controlled entertainment hubs. China emphasizes MIIT-certified cybersecurity compliance and whole-apartment smart building specifications. Germany demands EU AI Act transparency documentation for automated climate systems.
United States
Property insurers in high-value coastal markets mandate certified smart security installations for premium discounts, creating compulsory demand that bypasses discretionary purchase cycles. The FCC governs radio-frequency emissions for wireless devices under Part 15 rules, with particular scrutiny on 2.4 GHz and 5 GHz band congestion. Miami and Los Angeles luxury developments specify Thread-certified lighting nodes for new construction, displacing legacy hub-centric architectures.
China
MIIT's GB standards for IoT device cybersecurity accelerate domestic manufacturing upgrades among export-capable suppliers in the Pearl River Delta. Whole-apartment automation specifications dominate new residential construction in tier-one cities, with developers bundling climate and security systems as standard amenities. Shenzhen hardware clusters concentrate sensor and actuator production, leveraging integrated circuit design capabilities from neighboring Hong Kong and Taiwan supply relationships.
Germany
The EU AI Act imposes algorithmic transparency requirements on automated HVAC decision systems, extending certification timelines for occupancy-prediction algorithms. KBA-equivalent building codes enforce stricter electromagnetic compatibility testing than US FCC requirements, favoring wired infrastructure in commercial retrofits. Munich and Frankfurt commercial property managers prioritize BACnet-integrated climate systems that interface with legacy equipment from established European manufacturers.
India
Municipal smart city projects in Bengaluru and Hyderabad seek building-to-grid automation that residential platform providers adapt for commercial deployment. BIS certification requirements for electronic imports create compliance friction for foreign entrants, though PLI scheme incentives accelerate domestic assembly capacity. DIY starter kit demand concentrates in Delhi-NCR and Mumbai metropolitan markets, where tech-savvy millennials bypass professional installer networks through Amazon and Flipkart e-commerce channels.
United Arab Emirates
Luxury housing developers in Dubai specify Matter-protocol lighting and climate nodes for new construction, leveraging the standard's interoperability to reduce vendor lock-in risk. MOHAP-equivalent building safety regulations mandate integrated fire and security system connectivity in high-rise residential towers. Abu Dhabi sovereign wealth-backed infrastructure projects test whole-district automation architectures that merge residential, commercial, and municipal control layers.
Home Automation System Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with platform providers competing on service depth rather than ecosystem lock-in. Johnson Controls leverages building-automation heritage to dominate commercial-grade climate integration, while Amazon sustains consumer-facing voice control through Echo-device ubiquity. Samsung Electronics anchors whole-home ecosystems via SmartThings platform interoperability. Strategic moves concentrate on Matter protocol certification acceleration and insurance partnership formations for security-mandated installations.
Within the integrated platform tier, Johnson Controls and Schneider Electric exemplify building-automation specialists extending from commercial infrastructure into premium residential deployments. Samsung Electronics occupies a position bridging consumer electronics and whole-home ecosystem orchestration. Among voice-centric entrants, Amazon represents the direct-to-consumer channel strategy that captures millennial starter-kit demand through e-commerce dominance. The competitive terrain rewards backward integration into sensor hardware and upstream control over wireless chipset allocation.
| Leading Market Players |
|---|
| Johnson Controls |
| Schneider Electric |
| Siemens |
| Honeywell International |
| Amazon |
| Alphabet |
| Samsung Electronics |
| Apple |
| ADT |
| Others |
Cost & Logistics Intelligence
Ninety-day chipset lead times from Taiwan foundries compress margin buffers for DIY kit manufacturers while amplifying pricing power for vertically integrated platform providers with captive allocation agreements. This inventory-to-pricing dynamic forces tier-two vendors toward spot-market premiums or specification downgrades.
Pricing Analysis
Long-term offtake contracts dominate commercial building-automation procurement, while consumer-facing hardware operates on transactional per-unit models with quarterly price reviews. Pricing stratifies across Matter-certified premium tiers, UL-listed security hardware, and uncertified economy sensors. Cost compression in entry-tier wireless nodes intensifies as Amazon and Best Buy consolidate purchasing leverage. Residential DIY buyers exhibit highest price sensitivity; luxury developers specifying Thread-certified infrastructure show lowest elasticity.
Supply Chain Analysis
Taiwan and South Korea anchor wireless chipset fabrication, while China's Pearl River Delta clusters sensor and actuator assembly. Copper sensor housings, neodymium actuator motors, and lithium battery cells draw from geographically dispersed mining operations. Single-source vulnerability concentrates in Taiwan semiconductor foundries exposed to geopolitical disruption. Distribution runs through Amazon and Best Buy e-commerce channels for consumer tiers, with systems integrators controlling commercial project flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
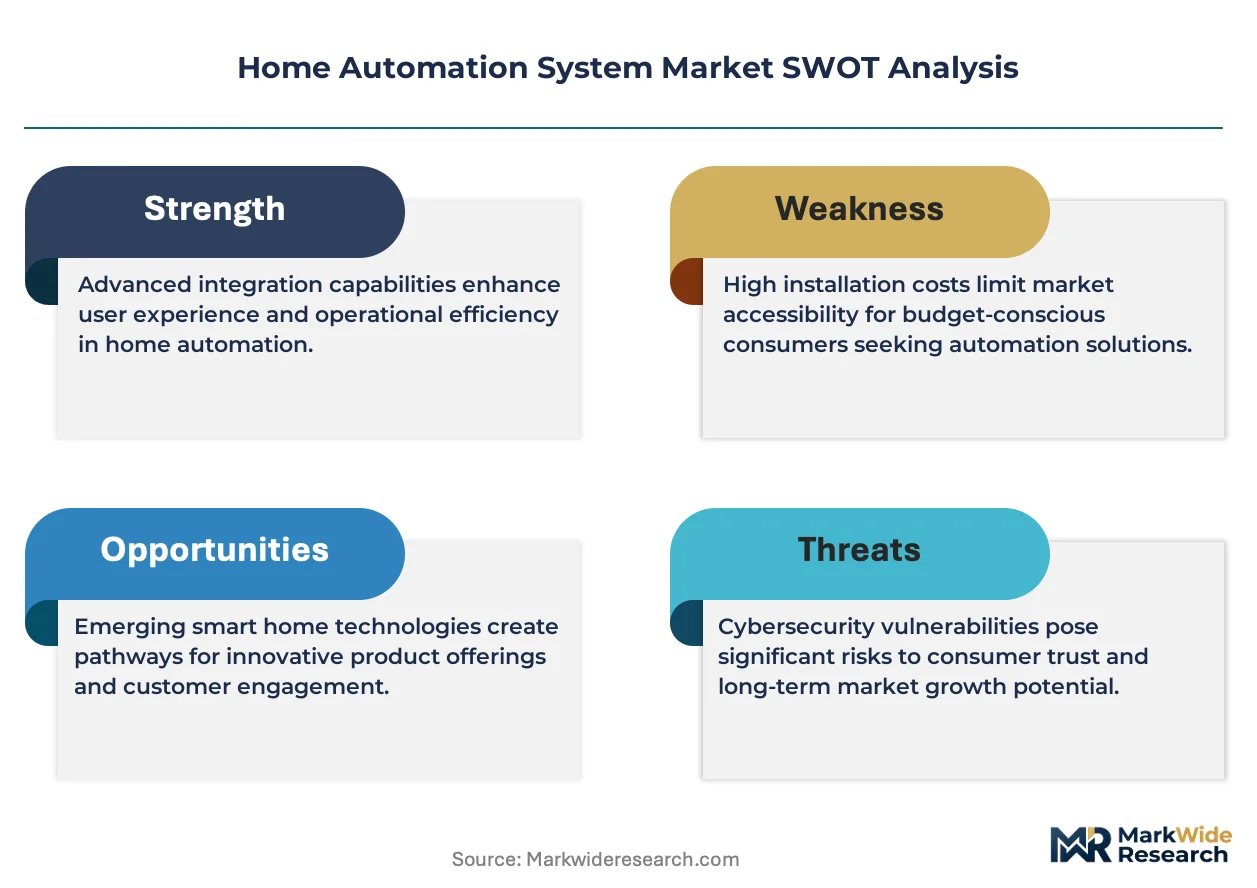
Protocol fragmentation and insurance-mandated security requirements create specialized niches for focused competitors. The Matter standardization dissolves ecosystem lock-in, opening white-space for service-depth differentiation.
For Market Incumbents: Consolidate firmware engineering capabilities through acquisition of real-time operating system specialists. Secure captive wireless chipset allocation via direct foundry partnerships to defend against Taiwan supply disruption. Accelerate GB standards pre-certification for China market access ahead of domestic competitor scaling.
For New Entrants and Emerging Players: Matter certification fast-track enables interoperability positioning without proprietary ecosystem investment. Target India's smart city building-to-grid automation segment where municipal procurement favors adaptable residential platform architectures. Pursue direct-to-consumer channel bypass of established installer networks through Flipkart and Amazon India partnerships.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because service-depth competition favors integrated providers over point-solution vendors. Acquisition focus should center on Thread-certified hardware specialists with insurance partnership pipelines. Monitor EU AI Act enforcement timelines in Germany and France as inflection indicators for compliance-cost barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Enables multi-vendor installations previously blocked by ecosystem lock-in. |
| Insurance Partnership Formation | Captures compulsory demand from US and German property insurer mandates. |
| Foundry Allocation Agreement | Secures semiconductor supply against Taiwan geopolitical disruption risk. |
| GB Standards Pre-Certification | Accelerates China MIIT compliance for export-capable manufacturing positioning. |
| Edge Computing Architecture Shift | Redistributes intelligence from cloud to local controllers, altering value capture. |
Research Approach
A standing panel of smart home platform engineers, systems integrators, property insurance risk officers, and FCC regulatory consultants provided ongoing calibration across primary fieldwork and secondary validation. Primary inputs combined interviews with Johnson Controls and Schneider Electric building-automation directors, Amazon Alexa hardware procurement leads, and Shenzhen sensor manufacturer operations heads. Secondary sources encompassed FCC Part 15 filings, MIIT GB standard drafts, EU AI Act implementing guidance, and hyperscaler smart home capex disclosures. Bottom-up segment sizing triangulated against top-down market aggregation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation across product type, technology architecture, end-user category, and installation mode. CAGRs derived from fitted growth curves applied to baseline penetration rates. Industry-specific forecast inputs included Matter protocol adoption velocity, insurance mandate expansion timelines, and wireless chipset allocation constraints.
Decision-makers should treat outputs as directional under base assumptions of sustained Matter standardization and stable Taiwan semiconductor supply; material deviation would warrant model refresh. Specific risk factors include EU AI Act enforcement intensity, China MIIT cybersecurity rule evolution, and geopolitical disruption to East Asian foundry operations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Automated Sample Storage Systems Market
Automation
Pneumatic Tube System Market
Automation
Workload Scheduling and Automation Market
Automation
Laboratory Benchtop Automation Market
Automation
Global Database Automation Systems Market
Automation
Asia-Pacific Data Center Automation Market
Automation
Automated Cell Block Systems Market
Automation
Indonesia Automation and Control System Market
Automation
Automation-As-A-Service Market
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
CNC Controller Market
Automation
Global Zig-Bee Automation Market
Automation
Process Automation Market
Automation
Distribution Automation Solutions Market
Automation
Global Automated Liquid Handlers Market
Automation
IoT Home Automation Market