
 Lab Automation Market | 2026-2036
Lab Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Automation Market Intelligence
The demand emphasis from academic labs toward high-throughput contract research organizations is shifting the market's center of gravity. This change favors scalable, modular platforms over standalone instruments. Thermo Fisher Scientific, Inc. leverages its comprehensive portfolio to serve this diverse customer base. Meanwhile, Hamilton Company specializes in precision liquid handling robotics for complex workflows, particularly in genomics.
Lab automation involves using robotic and software-driven equipment to execute laboratory tasks with minimal human intervention. These systems achieve sub-microliter precision in liquid handling, a critical parameter for sensitive assays. Their primary purpose is enhancing throughput and ensuring data consistency in research and diagnostics. Liquid handling systems form a foundational product segment, while the application of robotic arms is expanding beyond simple plate moving.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) enforce strict validation protocols for automated systems used in GxP environments. ISO standards, such as ISO 15189 for medical laboratories, also influence equipment design and software traceability requirements. A key decision for labs is balancing the capital cost of fully integrated platforms against the flexibility of modular automation.
Market Dynamics
The central force shaping the lab automation market is the industrialization of life science research, driven by contract research organizations. This shift prioritizes throughput, scalability, and reproducibility, favoring integrated platforms over disconnected, single-task instruments and redefining vendor-customer relationships.
Growth Catalysts
- Artificial Intelligence Integration:The application of AI and machine learning for predictive analytics in genomic and proteomic data analysis accelerates drug discovery timelines and improves diagnostic accuracy.
- CRO Demand Expansion:Contract research organizations require high-throughput screening and automated sample preparation to manage large-scale projects, creating consistent demand for scalable automation solutions.
- Biotechnology Cluster Concentration:Concentrated research and development investment within biotechnology hubs, particularly in the United States and Germany, fosters rapid adoption of advanced automation technologies to maintain a competitive edge.
Market Restraints
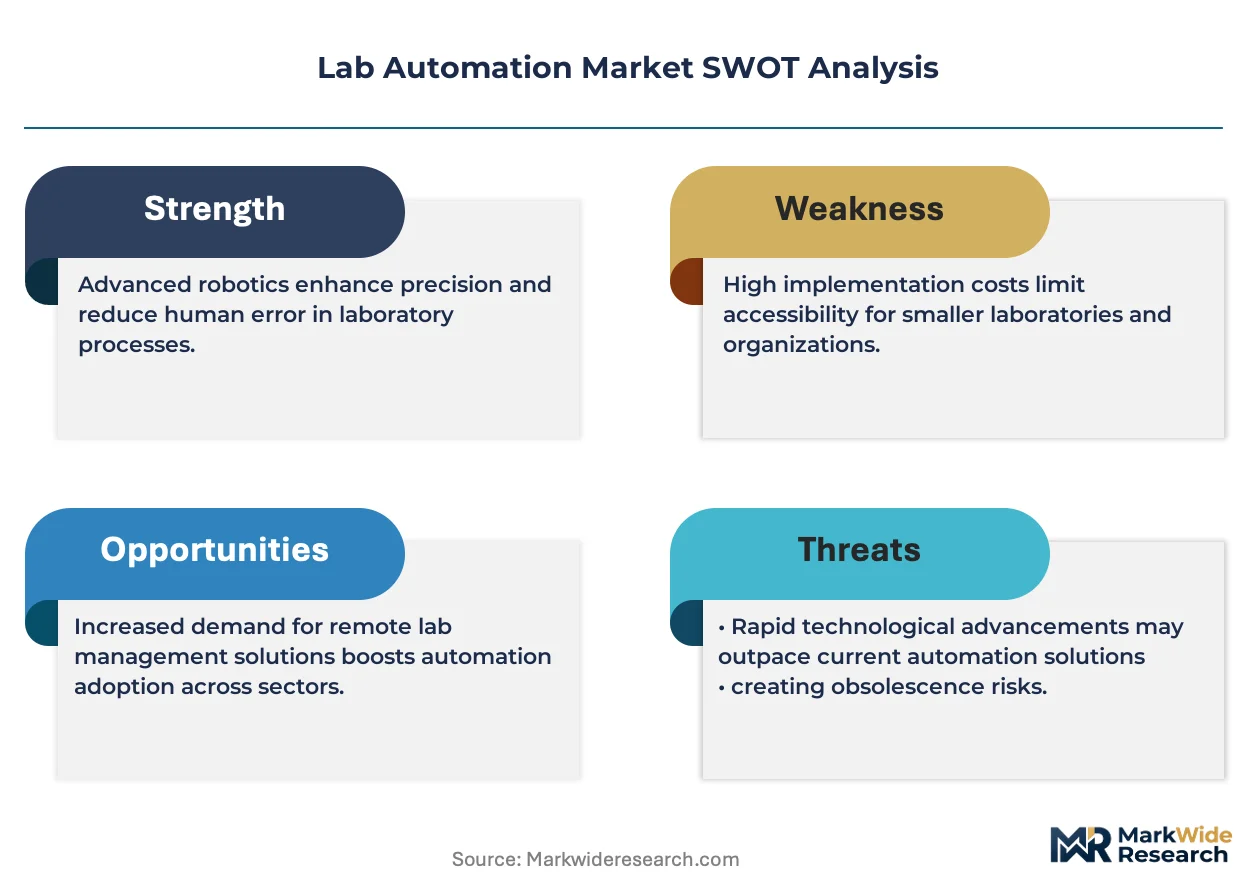
- High Capital Costs:The significant upfront investment required for fully integrated, high-throughput automation systems presents a substantial barrier for smaller academic labs, startups, and facilities with limited budgets.
- Interoperability Standards Gap:A lack of universal communication protocols between instruments from different manufacturers creates integration challenges, leading to data silos and workflow inefficiencies that require custom software development.
- Stringent Regulatory Validation:The rigorous and time-consuming validation processes mandated by the FDA and EMA for automated systems in GxP-compliant environments can delay the implementation of new technologies.
Strategic Opportunities
- Cell and Gene Therapy Manufacturing:Automation offers solutions for the complex, highly precise, and sterile workflows required in cell and gene therapy production, representing a significant new application area.
- Expansion in Emerging Markets:Biopharmaceutical sectors in Southeast Asian countries are expanding, creating an opportunity for vendors to introduce modular and mid-range automation solutions tailored to nascent lab infrastructures.
- Microfluidics Convergence:Integrating microfluidics with robotic liquid handlers enables "lab-on-a-chip" platforms, miniaturizing assays, reducing reagent consumption, and increasing analytical speed for point-of-care diagnostics.
Industry Challenges
- Specialized Talent Shortage:A persistent gap exists for professionals with hybrid expertise in laboratory sciences, robotics, and software engineering, which complicates system operation, maintenance, and troubleshooting.
- Legacy System Integration:Connecting modern automated platforms with older, existing Laboratory Information Management Systems (LIMS) is often complex and costly, hindering seamless data flow and enterprise-wide connectivity.
- Data Format Standardization:The absence of a universal data format standard across vendors complicates the aggregation and comparative analysis of results from different automated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Automation Market |
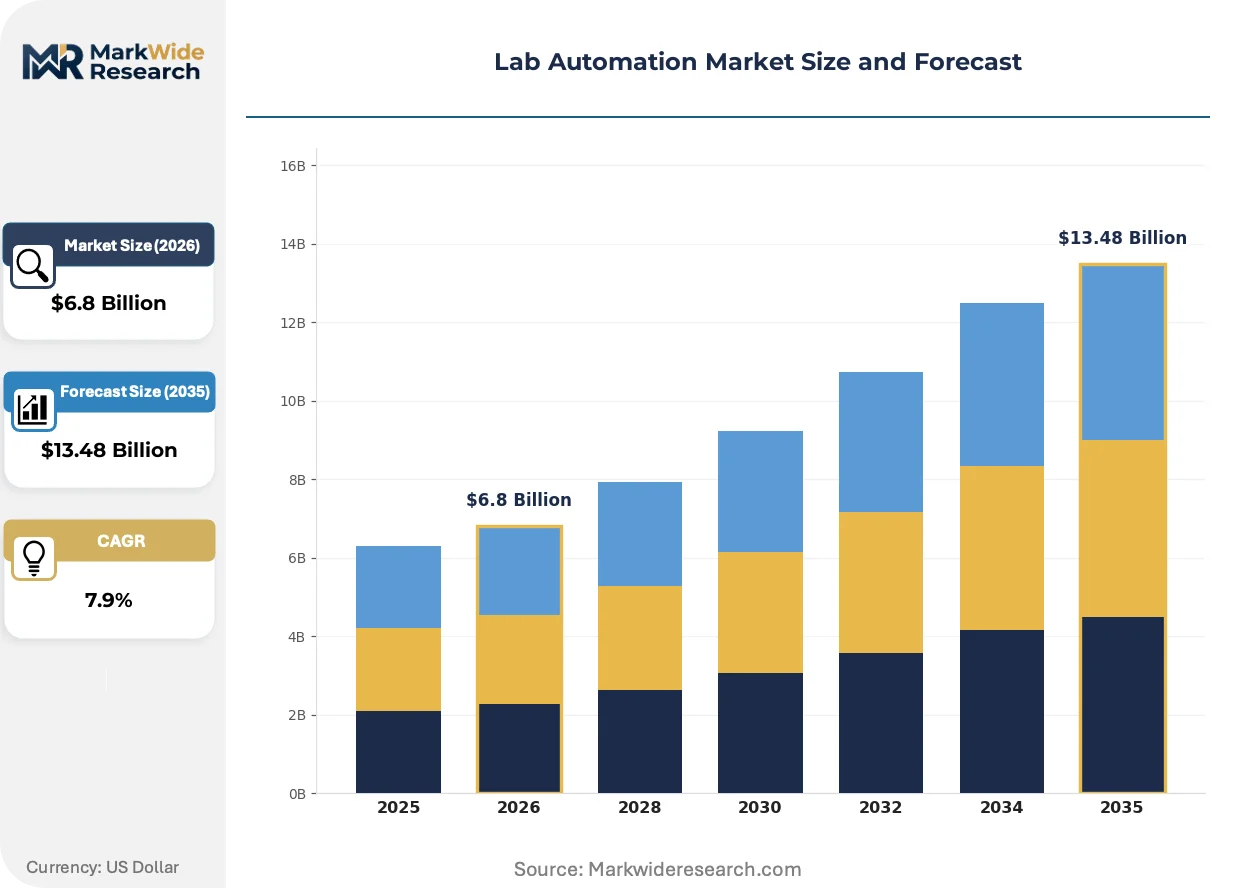
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Handling Systems, Robotic Arms, Automation Software, Plate Handlers, Microplate Readers, Barcode Scanners Technology: Artificial Intelligence, Optical Recognition, Machine Learning, Sensor Integration, Data Analytics, Robotic Process Automation Application: Pharmaceutical Research, Genomic Analysis, Chemical Testing, Environmental Monitoring, Food Safety Assessment, Forensic Science End User: Biotechnology Firms, Academic Labs, Clinical Diagnostics, Contract Research Organizations, Quality Control Units, Food Testing Facilities |
| Companies Covered | Thermo Fisher Scientific, Inc., Danaher Corporation, Agilent Technologies, Inc., PerkinElmer Inc., Tecan Group Ltd., Hamilton Company, Siemens Healthineers, F. Hoffmann-La Roche Ltd., QIAGEN N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Automation Market Strategic Shifts & Innovations
The defining trend is the shift from automating discrete tasks to orchestrating entire workflows through connected, data-centric ecosystems. This evolution prioritizes software and connectivity, transforming how laboratories manage resources, execute experiments, and generate insights from increasingly complex datasets.
Cloud-native software provides a centralized platform for designing, scheduling, and monitoring automated laboratory workflows. Research organizations, particularly multi-site CROs and global pharmaceutical firms, are adopting these solutions to manage instrument fleets and data streams remotely. This software-centric model is overtaking siloed, on-premise instrument control software, enabling greater operational flexibility and collaborative research across geographic boundaries.
Regulatory frameworks governing data sovereignty are directly impacting system architecture. For example, China's Personal Information Protection Law (PIPL) imposes strict rules on cross-border transfers of genomic and clinical data. This forces life science organizations to either build costly in-country data centers or adopt federated analytics models, particularly impacting the global clinical trials segment.
A notable shift in acquisition models is the move from one-time capital equipment purchases to subscription-based "automation-as-a-service" offerings. This disrupts the traditional sales channel by bundling hardware, software updates, consumables, and technical support into a recurring operational expense. The model is gaining traction among capital-constrained biotechnology startups in the United States and specialized diagnostic labs seeking financial flexibility.
Lab Automation Market Segmentation
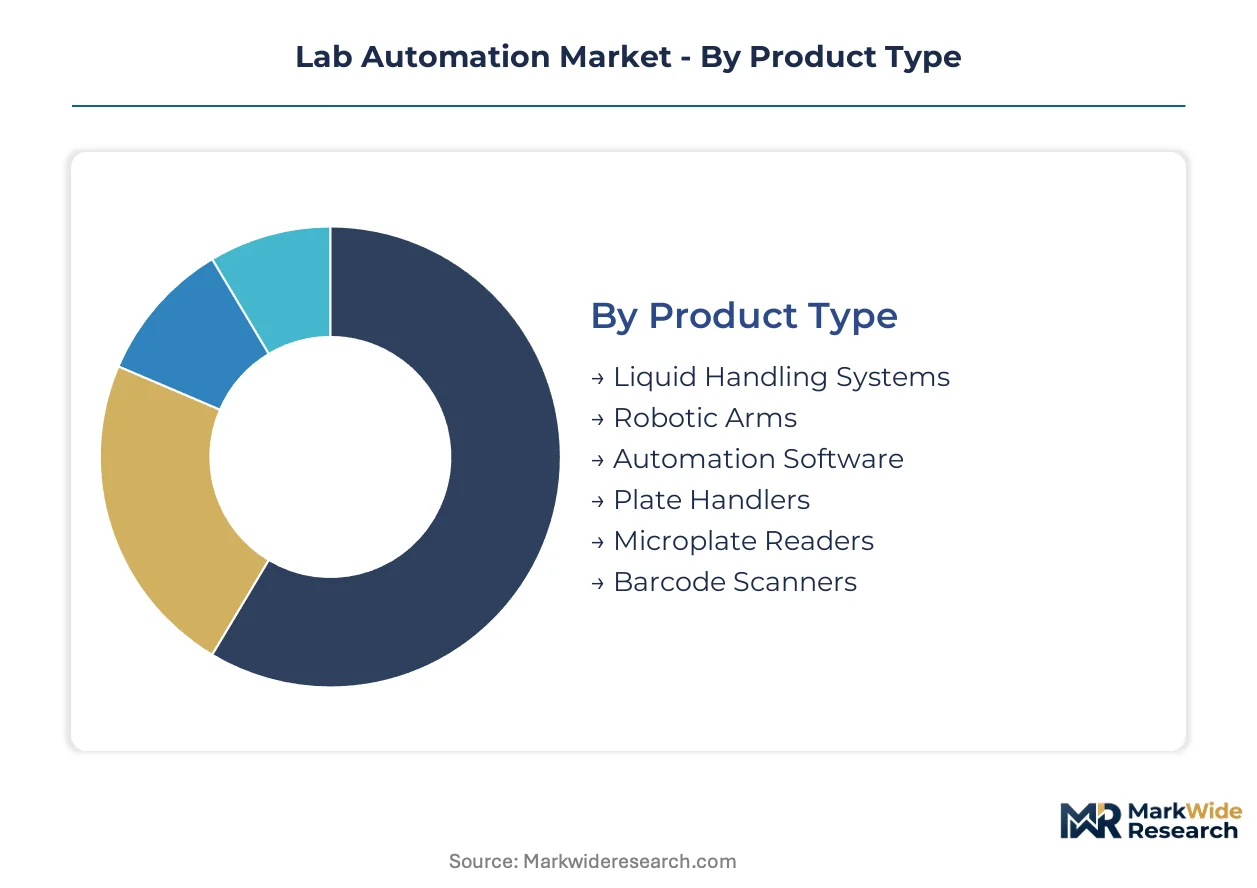
Lab automation market segmentation provides a granular view of the diverse product offerings, underlying technologies, varied applications, and distinct end-user requirements. Understanding these segments clarifies the market's evolving landscape and highlights areas of concentrated demand and innovation within the life sciences sector.
Product Type:
Product types define the operational capabilities and precision levels achievable within lab automation workflows, ranging from physical manipulation to data capture.
- Liquid Handling Systems:These automated platforms precisely aspirate and dispense sub-microliter volumes, essential for assay miniaturization and reproducibility. Demand concentrates in pharmaceutical research for high-throughput drug screening, driven by the need for consistent results.
- Robotic Arms:These articulated mechanical systems manipulate labware, move plates, and integrate various instruments into a cohesive workflow. Their demand is accelerating in contract research organizations managing complex multi-step protocols across different platforms.
- Automation Software:This provides the control layer for instrument orchestration, data acquisition, and workflow management across automated systems.
- Plate Handlers:These devices automate the movement and stacking of microplates, increasing efficiency in high-volume screening applications.
- Microplate Readers:These instruments detect and quantify biological, chemical, or physical reactions in microplates, crucial for diagnostic and research assays.
- Barcode Scanners:These devices ensure positive sample identification and tracking throughout automated laboratory processes, enhancing data integrity and compliance.
Mature deployment sits with Liquid Handling Systems. Newer deployment is concentrated in Automation Software.
Technology:
Technological advancements fundamentally enhance the intelligence, autonomy, and data processing capabilities of automated lab systems, driving efficiency gains.
- Artificial Intelligence:AI algorithms enable predictive analytics and decision-making in complex genomic and proteomic data analysis. Its demand is strongest in biotechnology firms seeking accelerated drug discovery timelines and improved diagnostic accuracy.
- Machine Learning:ML models optimize experimental parameters, identify patterns in large datasets, and improve system performance over time. Academic labs increasingly adopt ML for novel biomarker identification, driven by data complexity.
- Optical Recognition:This technology uses cameras and image processing to identify samples, track components, and verify liquid levels, improving process reliability.
- Sensor Integration:Embedded sensors monitor environmental conditions and instrument status, providing real-time feedback for critical process control.
- Data Analytics:This involves processing and interpreting large volumes of experimental data, transforming raw results into actionable scientific insights.
- Robotic Process Automation:RPA automates repetitive, rule-based digital tasks within lab information systems, streamlining administrative and data entry efforts.
Artificial Intelligence represents the fastest-growing trajectory in technology adoption.
Application:
Lab automation applications span diverse scientific disciplines, each requiring specialized system configurations and analytical precision for specific research or diagnostic goals.
- Pharmaceutical Research:This application focuses on drug discovery, development, and high-throughput screening of compounds for efficacy and toxicity. Contract research organizations are a primary driver, needing to process vast compound libraries efficiently.
- Genomic Analysis:This involves automated DNA/RNA extraction, sequencing preparation, and PCR setup for genetic studies and diagnostics. Biotechnology clusters in the United States show strong demand, propelled by personalized medicine initiatives.
- Chemical Testing:This includes automated sample preparation and analysis for quality control, material science, and industrial chemistry processes.
- Environmental Monitoring:Automated systems analyze water, soil, and air samples for pollutants and contaminants, ensuring regulatory compliance.
- Food Safety Assessment:This application uses automation for pathogen detection, allergen testing, and nutritional analysis in food production.
- Forensic Science:Automated platforms assist in DNA profiling, toxicology screening, and evidence processing for criminal investigations.
Pharmaceutical Research drives significant volume, while Genomic Analysis demands high complexity from automated systems.
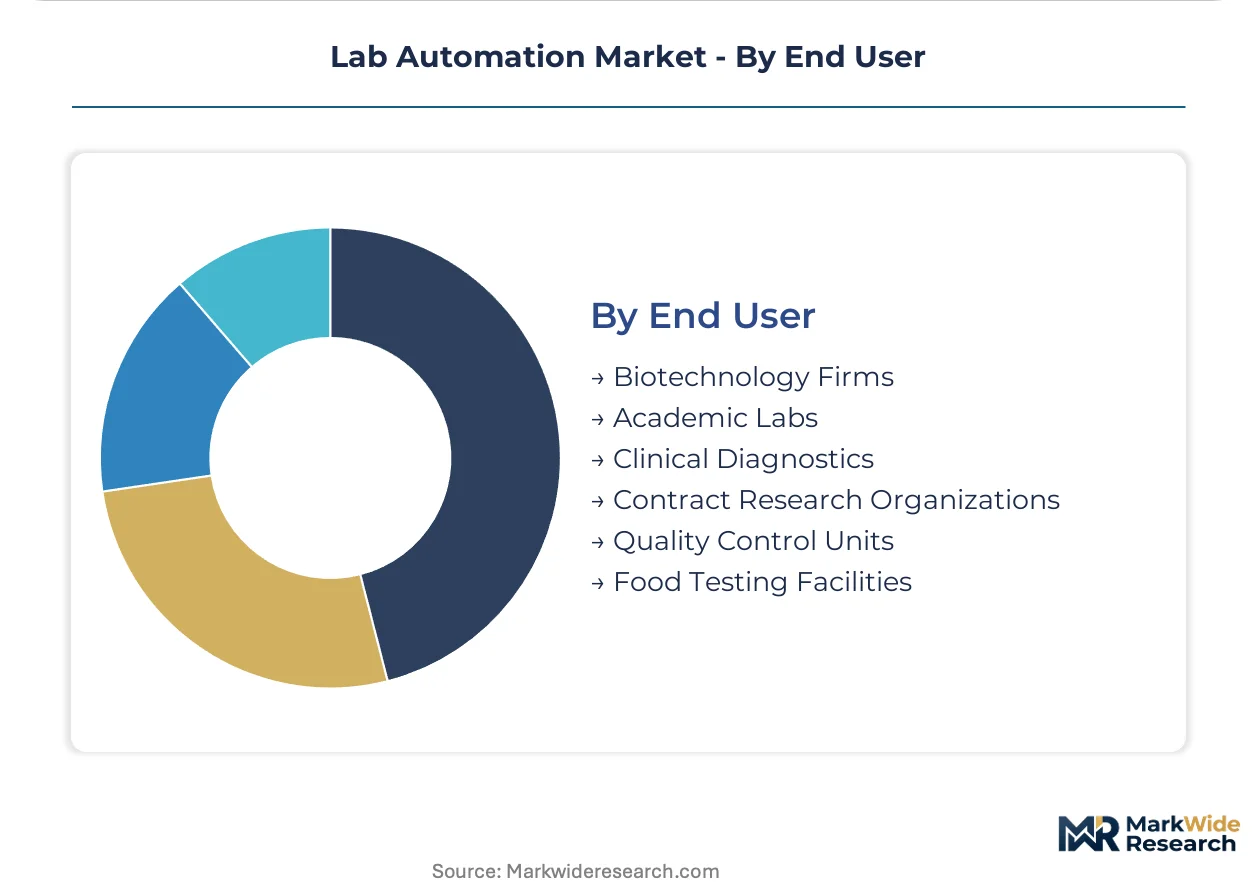
End User:
End-user segments reflect distinct operational scales, budgetary constraints, and regulatory environments influencing automation adoption and system integration choices.
- Contract Research Organizations:CROs leverage automation for high-throughput screening, sample management, and assay development on behalf of pharmaceutical clients. Their business model prioritizes scalability and rapid turnaround times.
- Biotechnology Firms:These companies utilize automation for drug discovery, cell line development, and bioprocess optimization. Concentrated in clusters like Germany, they seek to accelerate research and product development.
- Academic Labs:University-affiliated research facilities adopt automation for fundamental scientific discovery and educational purposes, often balancing cost with flexibility.
- Clinical Diagnostics:These labs employ automated systems for routine patient sample analysis, ensuring accuracy and efficiency in disease detection.
- Quality Control Units:Industrial and manufacturing settings use automation for product testing and compliance verification, maintaining consistent quality standards.
- Food Testing Facilities:These specialized labs use automated workflows for safety, quality, and nutritional analysis of food products before market release.
Contract Research Organizations lead in automation investment, while Academic Labs often prioritize modular and cost-effective solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotechnology clusters, often operating with specific research incentives, drive concentrated demand for advanced lab automation technologies. These specialized zones foster rapid innovation and adoption, particularly in regions with robust life science funding. The strategic deployment of automated systems within these hubs accelerates research outcomes and diagnostic capabilities.
United States
Demand for high-throughput screening and genomic analysis drives significant investment in lab automation across the United States. US FDA validation protocols mandate rigorous testing for automated systems in GxP environments, ensuring data integrity. The Boston-Cambridge biotech cluster rapidly adopts advanced automation, maintaining its competitive edge in drug discovery.
Germany
German biotechnology firms and pharmaceutical research centers require advanced automation for complex workflows and GxP compliance. The European Medicines Agency (EMA) enforces strict validation for automated systems, influencing equipment design and software traceability. Munich's life science ecosystem concentrates on integrating AI for predictive analytics, accelerating drug discovery timelines.
China
China's expanding biopharmaceutical sector and growing clinical trials segment generate significant demand for scalable lab automation solutions. The Personal Information Protection Law (PIPL) imposes strict rules on cross-border transfers of genomic data, impacting system architecture. The Yangtze River Delta region sees investment in automated platforms, particularly for in-country data processing.
Switzerland
Swiss pharmaceutical R&D and specialized diagnostics drive demand for highly precise liquid handling systems and integrated automation. Swissmedic oversight and adherence to ISO 15189 standards ensure robust validation for automated lab equipment. Basel's pharmaceutical hub focuses on advanced robotics for complex workflows, particularly in cell and gene therapy manufacturing.
India
Indian contract research organizations and biopharmaceutical manufacturers increasingly seek modular automation to enhance throughput and reproducibility. The Central Drugs Standard Control Organization (CDSCO) guidelines influence the adoption of validated systems in GxP settings. Bengaluru's biotech corridor is witnessing growth in mid-range automation, catering to nascent lab infrastructures.
Lab Automation Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the lab automation market's structure. The market exhibits a tiered competitive landscape, ranging from comprehensive solution providers to niche technology innovators. Strategic archetypes include integrated platform developers, precision instrument manufacturers, and software-centric orchestrators. Companies primarily engage in strategic partnerships for technology integration and targeted acquisitions to expand their portfolio capabilities.
Among integrated platform developers, Thermo Fisher Scientific, Inc. represents a comprehensive portfolio approach, serving a diverse customer base with broad automation solutions that span multiple product types and technologies. Hamilton Company, known for its precision engineering, exemplifies specialized expertise in liquid handling robotics, crucial for complex genomic workflows and high-precision assays. Tecan Group Ltd. also occupies a significant position within the automation landscape, providing advanced solutions that encompass liquid handling, microplate readers, and sophisticated software for various laboratory applications, anchoring its presence across research and diagnostic segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Danaher Corporation |
| Agilent Technologies, Inc. |
| PerkinElmer Inc. |
| Tecan Group Ltd. |
| Hamilton Company |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd. |
| QIAGEN N.V. |
| Others |
Cost & Logistics Intelligence
Contract research organizations' demand for scalable, high-throughput solutions significantly impacts lab automation vendors, driving a shift towards integrated platform pricing models. This demand pressure influences supply chain configurations to prioritize modularity and rapid deployment.
Pricing Analysis
Lead-time-driven pricing structures emerge for rapid deployment of specialized lab automation solutions, particularly for urgent research projects. Subscription-based "automation-as-a-service" models offer operational expense flexibility, complementing traditional capital equipment purchases. Price differentiation stems from customization for complex genomic workflows and the level of integrated software support. Pricing pressure stems from the significant upfront capital costs for fully integrated systems, making academic labs highly price-sensitive, while large CROs prioritize performance and reliability.
Supply Chain Analysis
Dual-sourcing requirements for critical components mitigate risks in the lab automation supply chain, especially for precision robotics. Geographic supply concentrates in the United States for advanced software, Germany for precision engineering, and China for expanding manufacturing capabilities. The supply chain relies on specialized robotic actuators, microfluidic components, and advanced sensor technologies. Single-source vulnerability for highly specialized liquid handling components poses a structural risk. Distribution runs through direct sales channels for integrated systems and specialized distributors for modular instruments and consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lab automation market exhibits supply constraints, primarily driven by a persistent shortage of specialized talent in robotics and software engineering. This scarcity props up pricing for advanced integration and maintenance services.
For Market Incumbents: Deploy strategic partnerships with AI/ML software developers to enhance predictive analytics capabilities across existing platforms. Market incumbents should acquire niche software firms to counter the threat from emerging software-centric orchestrators. Expand global service and support networks, particularly in nascent biotechnology markets like Southeast Asia, to capture new revenue streams. Invest in modular, open-architecture system designs to simplify integration with diverse laboratory information management systems.
For New Entrants and Emerging Players: Microfluidics integration with robotic liquid handlers offers a technology-first wedge into miniaturized assay development and point-of-care diagnostics. New entrants can target capital-constrained biotechnology startups in the United States and mid-range labs in emerging markets. Focus on "automation-as-a-service" models to lower upfront costs and accelerate adoption. Develop specialized software for complex cell and gene therapy manufacturing workflows, leveraging precision and sterility requirements.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term value in the industrialization of life science research. Investors should target software orchestrators and specialized precision robotics firms with strong intellectual property in genomics. Acquisition profiles should prioritize companies addressing interoperability gaps and offering cloud-native workflow management solutions. A signal to watch is the widespread adoption of universal communication protocols between laboratory instruments, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-driven Predictive Analytics | Enhances drug discovery timelines for pharmaceutical research. |
| Modular Platform Development | Addresses diverse needs of contract research organizations. |
| Automation-as-a-Service Offering | Lowers entry barriers for biotechnology startups in the United States. |
| Microfluidics R&D Investment | Miniaturizes assays for point-of-care diagnostics. |
| Global Talent Development Programs | Mitigates specialized talent shortages in Germany. |
Research Approach
Multi-period observation of lab automation market size, CAGR, and technology adoption rates anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with lab directors, automation engineers, procurement managers, and regulatory specialists across biotechnology and pharmaceutical sectors. Secondary data sources included FDA validation reports, EMA guidelines, ISO standards, and company financial filings. Bottom-up and top-down triangulation ensured data integrity and comprehensive market understanding.
An input-output matrix served as the analytical framework for projecting market dynamics over the forecast period. This model segmented the market by product type, technology, application, end-user, and geographic cluster concentration. Compound Annual Growth Rates were derived from historical trends and projected growth drivers, including AI integration and CRO demand. Key forecast inputs included global R&D spending in life sciences and evolving regulatory frameworks.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid shifts in global public health crises. The forecasts reflect assumptions about stable R&D funding and technological evolution. Deviation in major economic downturns or disruptive new automation technologies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Remote Monitoring and Control Market
Automation
US Workload Scheduling and Automation Market
Automation
Helpdesk Automation Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Self Bag Drop Machine Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
Postal Automation System Market
Automation
Database Automation Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
IoT Home Automation Market
Automation
Dropshipping Automation Software Market
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
Global Direct Mail Automation Software Market
Automation
Global Zig-Bee Automation Market
Automation
Escalator Control Systems Market
Automation
Industrial Vending Machines Market