
 Pneumatic Tube System Market | 2026-2036
Pneumatic Tube System Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Tube System Market Intelligence
Hospital-grade stainless steel certification is redrawing procurement criteria across the pneumatic tube system landscape. Swisslog Holding AG leverages its integrated building logistics portfolio to anchor large-scale hospital deployments across multiple continents. Aerocom GmbH competes through specialized engineering for complex multi-site healthcare networks with custom routing requirements. Pevco Systems International Inc. dominates the North American acute-care segment with extensive service infrastructure and regulatory compliance expertise.
A pneumatic tube system comprises a network of sealed tubes, carrier vessels, blower units, and automated routing controls that transport physical items using differential air pressure, typically operating at velocities between 5 and 25 meters per second depending on payload sensitivity. These systems eliminate manual courier dependency in time-critical environments where chain-of-custody and speed determine operational outcomes. Vacuum technology leads installed base volumes due to proven reliability in hospital pharmacy and laboratory applications, while hybrid configurations represent the fastest-expanding segment as facilities seek flexible pressure modes for diverse payload types. Modular product architecture captures expanding margin pools by reducing site-specific engineering costs and accelerating deployment timelines for retrofit installations.
FDA quality system regulations and EU MDR conformity requirements shape product validation, material traceability, and post-market surveillance obligations for medical-grade pneumatic transport equipment. ISO 14971 risk management standards further constrain design choices for systems handling biological specimens and pharmaceuticals in clinical settings. Stakeholders must monitor evolving cybersecurity frameworks for connected building infrastructure as networked tube systems integrate with hospital information platforms and automated warehouse management layers.
Market Dynamics
Hospital pharmacy automation mandates are compressing installation timelines for pneumatic tube networks as facilities race to eliminate medication delivery errors before accreditation audits.
Growth Catalysts
- EU MDR conformity deadlines:European hospitals are accelerating capital equipment upgrades to meet medical device traceability requirements, directly expanding procurement volumes for certified pneumatic transport infrastructure.
- Specimen chain-of-custody automation:Clinical laboratories in Germany and the United States are retrofitting legacy courier systems with vacuum-sealed tube networks to eliminate handling gaps in diagnostic workflows.
- Stainless steel certification premiums:Hospital-grade material specifications are creating pull-through demand for corrosion-resistant carrier vessels and antimicrobial tube linings in high-throughput pharmacy applications.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings for blower motor windings and pneumatic valve housings are compressing manufacturer margins and triggering price escalation clauses in multi-year service contracts.
- OEM service infrastructure concentration:North American acute-care facilities face vendor lock-in risks where proprietary routing software and carrier designs limit third-party maintenance options.
- Autonomous mobile robot substitution:Warehouse and logistics facilities are piloting floor-based autonomous vehicles for internal transport, diverting capital away from fixed pneumatic infrastructure in non-clinical settings.
Strategic Opportunities
- India hospital network expansion:Greenfield medical cities in Gujarat and Tamil Nadu are specifying integrated building logistics systems including pneumatic transport as standard infrastructure.
- Cybersecurity framework convergence:Connected tube systems integrating with hospital information platforms can capture premium positioning by certifying against IEC 62443 industrial control security standards.
- Hybrid pressure technology:Dual-mode vacuum-positive pressure configurations are opening retrofit opportunities in older facilities previously constrained by single-pressure architecture limitations.
Industry Challenges
- ISO 14971 risk documentation:Clinical engineering departments struggle to maintain living hazard analysis files for biological specimen transport systems under continuous design revision cycles.
- Building information modeling integration:Pneumatic routing design requires specialized MEP coordination expertise that sits outside standard HVAC contractor skill sets, extending project timelines.
- Multi-site standardization:Health systems acquiring regional hospital networks face carrier incompatibility and control protocol fragmentation across inherited equipment vintages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Tube System Market |
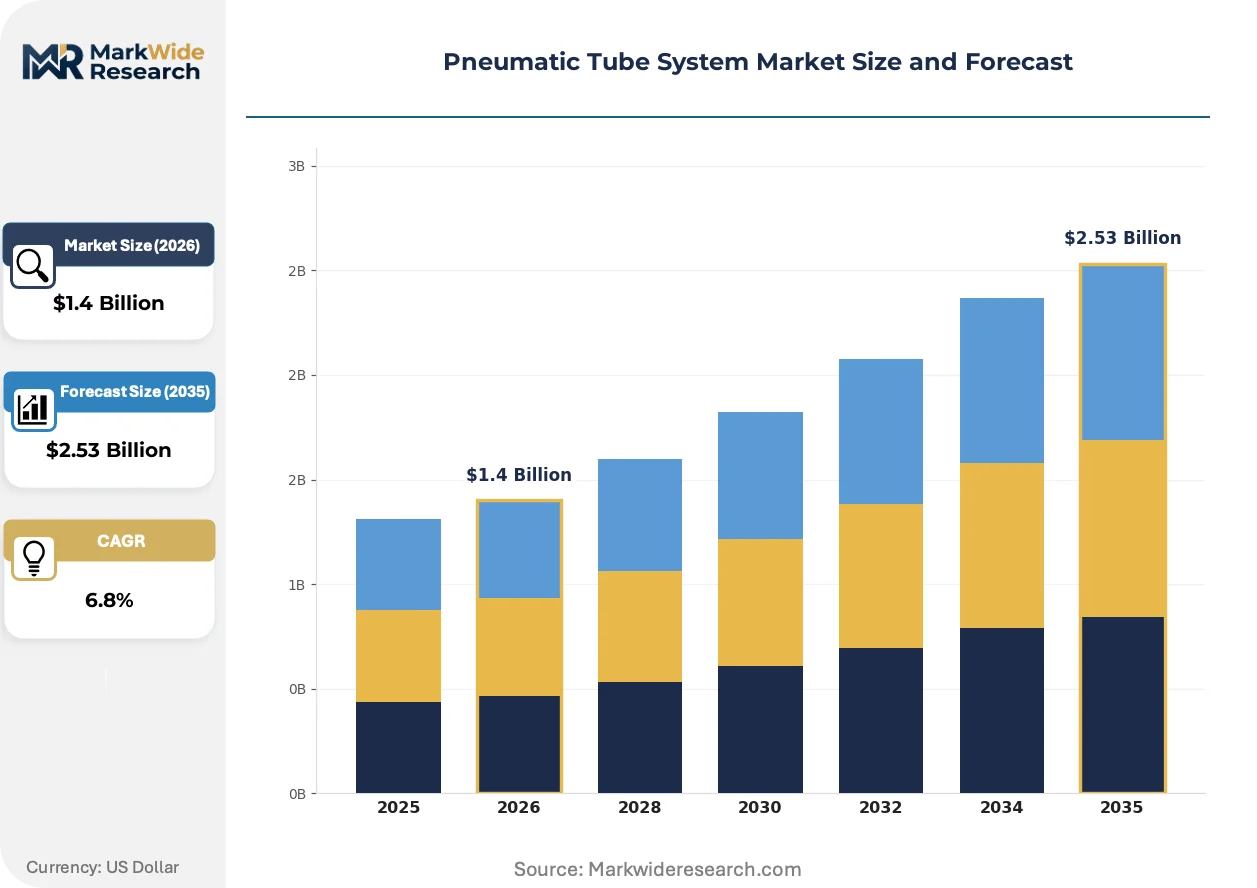
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary, Portable, Modular, Customized Technology: Vacuum, Positive Pressure, Hybrid, Pneumatic Ejector Application: Hospitals, Laboratories, Banks, Retail Outlets, Manufacturing Plants End User: Medical Facilities, Research Centers, Financial Institutions, Commercial Establishments |
| Companies Covered | Swisslog Holding AG, Aerocom GmbH, Pevco Systems International Inc., Eagle Pneumatic Inc., Air-Log International GmbH, Quirepace Limited, Sumetzberger GmbH, Kelly Systems, Hanter Ingenjörsteknik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Tube System Market Strategic Shifts & Innovations
Digital twin simulation is compressing deployment risk for complex multi-zone pneumatic networks while predictive maintenance algorithms are reshaping service contract economics.
Artificial intelligence-based routing optimization is fragmenting traditional fixed-path pneumatic architectures. Machine learning algorithms now calculate dynamic carrier dispatch sequences based on real-time priority flags and tube occupancy data. Major hospital systems in the United States and Germany are piloting adaptive routing in high-volume laboratory-to-pharmacy corridors. This capability is fragmenting the installed base between legacy deterministic controllers and software-defined infrastructure.
The FDA's enforcement of cybersecurity guidance for networked medical devices is tightening validation requirements for tube system interfaces with electronic health records. Manufacturers must now document threat modeling and penetration testing for blower control units with wireless connectivity. Acute-care facilities in North America are prioritizing vendors with pre-submitted 510(k) cybersecurity documentation.
Performance-based service agreements are displacing traditional time-and-materials maintenance contracts for pneumatic infrastructure. Hospital procurement departments in Switzerland and the Netherlands are unbundling equipment purchase from uptime guarantees, paying per successful carrier delivery rather than per technician visit. This shift concentrates risk with OEMs and rewards predictive maintenance capabilities over reactive break-fix responsiveness.
Pneumatic Tube System Market Segmentation
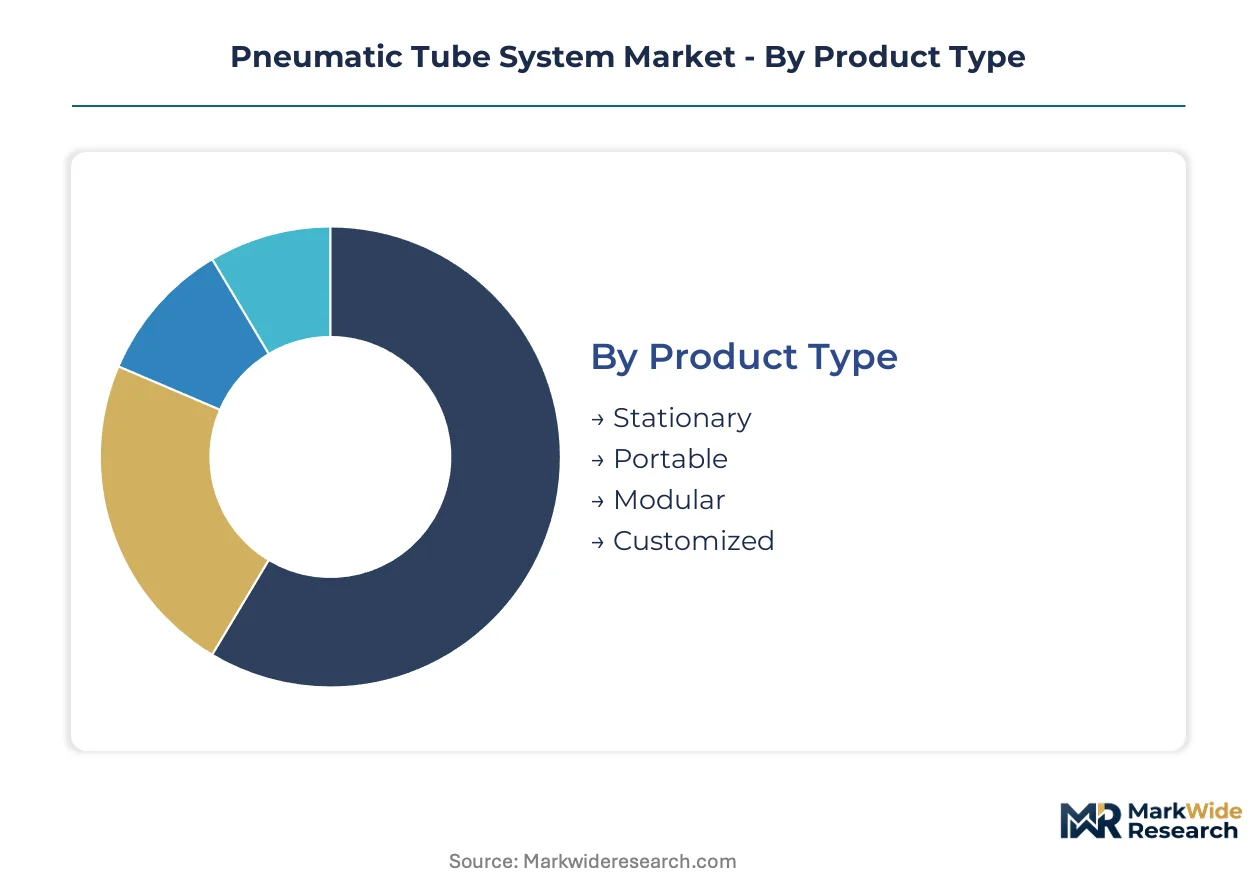
Pneumatic tube system segmentation reveals divergent engineering priorities across healthcare, financial, and industrial domains. Product architecture and pressure technology choices determine installation complexity, maintenance burden, and regulatory compliance pathways for end users.
Product Type:
Stationary systems dominate domestic hospital infrastructure deployments across Germany and the United States, while portable configurations serve export markets requiring rapid field installation capabilities.
- Stationary:Fixed tube networks with permanent blower stations and automated routing controls anchor large medical campus installations. Demand concentrates in German university hospitals where dense building footprints reward capital-intensive permanent infrastructure. FDA quality system documentation requirements favor established stationary platforms with extensive validation histories.
- Modular:Pre-engineered component kits reduce site-specific engineering costs and accelerate deployment timelines for retrofit installations. Swiss hospital networks are standardizing on modular architectures to enable phased expansion across acquired regional facilities. This segment gains share fastest where health systems prioritize operational flexibility over custom engineering.
- Portable:Self-contained units with temporary mounting systems serve construction sites, disaster response deployments, and temporary clinical facilities.
- Customized:Bespoke routing designs address unique building constraints, heritage structure limitations, or specialized payload requirements in complex multi-site networks.
Stationary systems hold the largest share; momentum sits with modular configurations.
Technology:
Pressure modality selection tracks application sensitivity requirements and payload diversity, with cost tiers separating proven vacuum installations from premium hybrid capabilities.
- Vacuum:Negative pressure transport using blower-induced suction operates at velocities between 5 and 15 meters per second for biological specimens and pharmaceuticals. Hospital pharmacy and laboratory applications across the United States favor vacuum technology for proven chain-of-custody reliability. Copper price volatility for motor windings constrains margin expansion in high-volume vacuum system manufacturing.
- Hybrid:Dual-mode vacuum-positive pressure configurations enable flexible velocity control for diverse payload types from delicate tissue samples to secure documents. German clinical engineering departments are retrofitting legacy single-pressure networks with hybrid capabilities to consolidate infrastructure. This segment climbs the fastest as facilities seek to unify previously separate transport systems.
- Positive Pressure:Compressed air propulsion achieves higher velocities for time-critical applications with robust payload containment.
- Pneumatic Ejector:Venturi-based acceleration systems reduce mechanical complexity in compact installations with moderate throughput requirements.
Vacuum technology anchors installed base volumes; hybrid configurations capture expanding margin pools.
Application:
Customer type and volume concentration separate high-throughput hospital installations from lower-intensity commercial deployments.
- Hospitals:Acute-care facilities deploy extensive tube networks connecting pharmacy, laboratory, blood bank, and nursing units to eliminate medication delivery errors. North American health systems are compressing installation timelines ahead of Joint Commission accreditation audits. EU MDR conformity deadlines are accelerating capital equipment upgrades in European hospital networks.
- Laboratories:Clinical and research facilities prioritize specimen integrity through sealed carrier transport with automated chain-of-custody documentation. German diagnostic laboratories are retrofitting legacy courier systems to close handling gaps in high-volume testing workflows. ISO 14971 risk management standards constrain design choices for biological specimen transport equipment.
- Banks:Financial institutions utilize secure document and cash transport between teller stations, vaults, and processing centers.
- Retail Outlets:Large-format stores deploy tube systems for cash management and inter-department communication in high-foot-traffic environments.
- Manufacturing Plants:Industrial facilities transport small components, quality control samples, and documentation across production floor distances.
Hospitals command the dominant revenue share; laboratories show the steepest expansion trajectory.
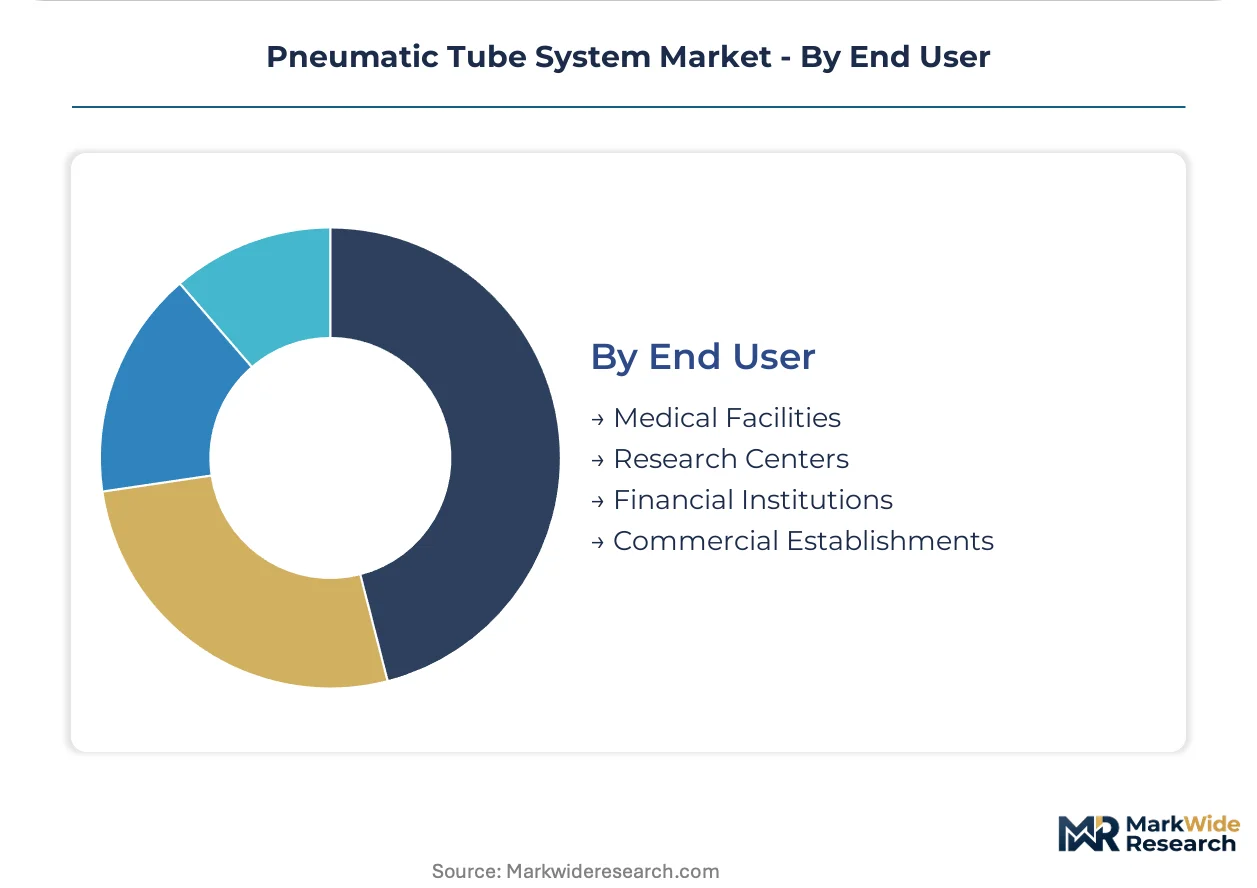
End User:
Maturity and standardization levels vary sharply across regulated medical environments versus less structured commercial settings.
- Medical Facilities:Hospitals, clinics, and integrated delivery networks represent the most specification-intensive customer segment with mandatory stainless steel certification and antimicrobial lining requirements. Procurement departments in Switzerland and the Netherlands are unbundling equipment purchase from performance-based uptime guarantees. Cybersecurity framework convergence for connected building infrastructure is reshaping vendor selection criteria.
- Research Centers:Academic and private research institutions demand flexible routing configurations for diverse specimen types with rigorous audit trail documentation. Specimen chain-of-custody automation is driving retrofit demand in United States and German research facilities. Predictive maintenance algorithms are reshaping service contract economics in this segment.
- Financial Institutions:Banks and credit unions prioritize physical security integration and transaction logging for cash and document transport systems.
- Commercial Establishments:Retail, hospitality, and corporate campus users favor standardized configurations with minimal customization and rapid deployment timelines.
Medical facilities dominate procurement volumes; research centers generate the fastest-growing specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for pneumatic tube systems clusters in Germany, Switzerland, and the United States, with each hub serving distinct regulatory environments and customer specification requirements. Distribution networks radiate from these centers to hospital systems and industrial facilities across their respective economic spheres.
Germany
Dense hospital networks in Bavaria and North Rhine-Westphalia drive demand for automated specimen transport infrastructure. The EU MDR conformity deadlines are accelerating capital equipment upgrades across German university hospitals. Siemens Healthineers and regional system integrators in Erlangen cluster are retrofitting legacy pharmacy logistics with certified stainless steel networks.
United States
Acute-care facilities in Texas, Florida, and the Northeast Corridor are compressing installation timelines ahead of Joint Commission accreditation audits. FDA enforcement of medical device quality system regulations is prompting manufacturers to enhance validation documentation. Hospital systems in Greater Boston are piloting AI-based routing optimization in high-volume laboratory corridors.
Switzerland
Swiss hospital procurement departments are unbundling equipment purchase from performance-based uptime guarantees, paying per successful carrier delivery. Swissmedic medical device traceability requirements shape vendor selection criteria for pneumatic transport infrastructure. Zurich and Geneva medical cities are specifying integrated building logistics systems as standard infrastructure.
India
Greenfield medical cities in Gujarat and Tamil Nadu are specifying pneumatic tube systems as core hospital infrastructure. The country's national pharmaceutical regulator is tightening quality system documentation for imported medical-grade transport equipment. Apollo Hospitals and Max Healthcare networks in Delhi-NCR and Hyderabad are deploying modular configurations for phased campus expansion.
United Kingdom
NHS Trusts in London and the Midlands are retrofitting legacy courier systems with vacuum-sealed tube networks to close handling gaps in diagnostic workflows. The Medicines and Healthcare products Regulatory Agency is aligning post-market surveillance requirements with EU MDR standards. Guy's and St Thomas' NHS Foundation Trust anchors demand for antimicrobial carrier vessels in high-throughput pharmacy applications.
Pneumatic Tube System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the pneumatic tube system landscape. Swiss and German engineering specialists dominate premium hospital-grade certifications with integrated building logistics portfolios, while North American service-intensive operators capture acute-care volume through regulatory compliance expertise. The market structure separates into three strategic archetypes: integrated logistics conglomerates, specialized pneumatic engineering firms, and regional service infrastructure operators. Consolidation pressure is intensifying through strategic partnerships between hardware manufacturers and predictive maintenance software providers, alongside geographic expansion into India's hospital network buildout.
Within the integrated logistics tier, Swisslog Holding AG exemplifies the capital-intensive conglomerate model with multi-continent hospital deployment capabilities. Among specialized German engineering firms, Aerocom GmbH and Air-Log International GmbH occupy positions anchored in complex multi-site healthcare network design. On the North American service-intensive vector, Pevco Systems International Inc. represents the regulatory compliance and acute-care service infrastructure archetype.
| Leading Market Players |
|---|
| Swisslog Holding AG |
| Aerocom GmbH |
| Pevco Systems International Inc. |
| Eagle Pneumatic Inc. |
| Air-Log International GmbH |
| Quirepace Limited |
| Sumetzberger GmbH |
| Kelly Systems |
| Hanter Ingenjörsteknik AB |
| Others |
Cost & Logistics Intelligence
Performance-based service contracts with per-delivery fee structures lock in multi-year supply access and price visibility for hospital procurement departments across Switzerland and the Netherlands. These arrangements concentrate risk with OEMs while rewarding predictive maintenance capabilities over reactive service responsiveness.
Pricing Analysis
EU MDR conformity deadlines dictate the pricing tier structure for pneumatic tube systems across European hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated stainless steel systems from modular retrofit configurations and portable field units. Cost compression in standard-tier equipment is intensifying because copper and aluminum price volatility for blower motor windings compresses manufacturer margins. Acute-care facilities in North America show the lowest price sensitivity due to Joint Commission accreditation audit pressures, while commercial establishments in retail and hospitality segments drive the hardest volume negotiations.
Supply Chain Analysis
Strategic stockpiling of corrosion-resistant carrier vessels and antimicrobial tube linings prevails among German and Swiss manufacturers facing EU MDR material traceability requirements. Manufacturing capacity clusters in Germany, Switzerland, and the United States, drawing from specialized MEP coordination expertise and precision blower engineering capabilities. Supply chain risk centers on single-source vulnerability for proprietary routing software and carrier designs that limit third-party maintenance options in North American acute-care facilities. Distribution runs through hospital GPO contracts in the United States and direct system integrator relationships in German university hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection arrives as AI-based routing optimization fragments legacy fixed-path architectures and demands interoperability between pneumatic networks and hospital information systems. This shift rewards vendors with pre-certified cybersecurity documentation and penalizes closed proprietary ecosystems.
For Market Incumbents: Shield installed base revenues by accelerating backward integration into predictive maintenance software capabilities before hardware-software unbundling accelerates. Consolidate service infrastructure density in Texas and Florida health systems where Joint Commission audit timelines compress replacement windows. Prioritize IEC 62443 industrial control security certification to capture premium positioning in connected building infrastructure tenders. For New Entrants and Emerging Players: Anchor in India's greenfield medical cities in Gujarat and Tamil Nadu where pneumatic tube systems are specified as standard infrastructure without legacy carrier incompatibility burdens. Target research center specimen chain-of-custody automation as the most penetrable segment, where ISO 14971 risk documentation gaps create entry opportunities. Pursue modular architecture partnerships with Apollo Hospitals and Max Healthcare networks to establish reference installations. For Investors and Strategic Acquirers: Predictive maintenance software specialists with hospital data platform integrations represent the highest-conviction acquisition archetype for this market's next phase. Long-term viability hinges on cybersecurity framework convergence for connected medical devices rather than hardware manufacturing scale. Revision becomes warranted when autonomous mobile robot substitution rates in non-clinical logistics facilities cross thresholds that divert capital from fixed pneumatic infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Pressure Technology Retrofit | Dual-mode configurations capture margin pools in German facilities constrained by single-pressure legacy architecture. |
| Cybersecurity Certification Pathway | IEC 62443 compliance unlocks premium positioning in Swiss and Dutch hospital procurement tenders. |
| Modular Architecture Standardization | Pre-engineered component kits reduce site-specific engineering costs for India's greenfield medical cities. |
| AI-Based Routing Optimization | Machine learning dispatch algorithms fragment deterministic controllers in Greater Boston laboratory corridors. |
| Performance-Based Service Agreement | Per-delivery uptime guarantees concentrate risk with OEMs and reshape contract economics in Netherlands hospitals. |
Research Approach
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract records preceded structured interviews with biomedical engineering directors, GPO contracts managers, clinical laboratory supervisors, and pneumatic system maintenance technicians. Primary fieldwork across German university hospitals and North American acute-care facilities combined with secondary validation against SEC filings of integrated logistics conglomerates and customs data for blower motor component trade flows. Bottom-up installation volume estimates triangulated against top-down healthcare capital expenditure projections.
Variance decomposition across product type, pressure technology, application, and end-user dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro healthcare infrastructure investment patterns. Forecast inputs incorporated EU MDR conformity deadline acceleration curves and copper price volatility indices for motor winding cost modeling.
Material uncertainties — regulatory enforcement intensity for cybersecurity guidance, autonomous mobile robot substitution rates in warehouse logistics, and raw material price swings for pneumatic valve housings — sit outside the modeled envelope. Forecasts reflect assumptions about hospital pharmacy automation mandate timelines and health system consolidation patterns. Revision becomes warranted when FDA medical device quality system regulation enforcement crosses thresholds that trigger accelerated validation documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Automatic Message Handling System Market
Automation
Europe Marketing Automation Software Market
Automation
Industrial Vending Machines Market
Automation
Smart Home Automation Market
Automation
Postal Automation System Market
Automation
Global Business Process Automation Software Market
Automation
Global Warehouse Execution System Market
Automation
Laboratory Automation Market
Automation
Home Automation System Market
Automation
Global Process Automation and Instrumentation Market
Automation
Playout Automation Market
Automation
Hyperautomation Market
Automation
US Workload Scheduling and Automation Market
Automation
Global Zig-Bee Automation Market
Automation
Recruiting Automation Software Market
Automation
Global Database Automation Systems Market