
 Wireless Video Surveillance Market | 2026-2036
Wireless Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Video Surveillance Market Intelligence
Subscription-based Video Surveillance as a Service (VSaaS) is decoupling hardware sales from recurring software and analytics revenue. This model shifts the value proposition toward ongoing service and data insights. Axis Communications leverages its open-platform strategy to integrate with a wide ecosystem of third-party software. In contrast, Verkada specializes in a closed, end-to-end cloud solution, bundling hardware, software, and support into a single subscription, which appeals to customers seeking simplicity and unified management.
Wireless video surveillance systems transmit video and audio data using radio frequencies, eliminating the need for physical network cabling. These systems typically operate on Wi-Fi protocols using the 2.4 GHz or 5 GHz bands, enabling flexible deployment in locations where hardwiring is difficult or cost-prohibitive. Their primary purpose is to provide scalable security monitoring for commercial, public, and residential spaces. IP Cameras constitute the largest product segment, valued for their high resolution and advanced networking features. The application of cellular technology is expanding for remote site monitoring, such as in construction and energy infrastructure projects.
Regulatory frameworks significantly influence product design and market access. In the United States, the Federal Communications Commission (FCC) regulates the radio frequency spectrum used by wireless devices. In Europe, the General Data Protection Regulation (GDPR) imposes strict rules on the collection, processing, and storage of personal data captured by surveillance systems. These standards compel manufacturers to incorporate privacy-by-design principles. Vendors must navigate a complex landscape of data privacy laws and cybersecurity standards to maintain market trust.
Market Dynamics
The central structural force shaping the market is the bifurcation between open-platform ecosystems and closed, vertically integrated cloud solutions. This creates distinct value propositions for customers, pitting customizable, multi-vendor systems against the simplicity of single-vendor, subscription-based services.
Growth Catalysts
- Smart Building Integration:The expansion of smart building projects is a primary catalyst, with surveillance systems becoming integral components for security, energy management, and occupancy analytics, particularly in new commercial construction.
- Public Safety Initiatives:Government investment in public safety and traffic monitoring infrastructure, especially in urban centers across India and Brazil, creates large-scale, concentrated demand for wireless surveillance networks.
- Edge-Based AI:The shift toward AI-powered analytics on edge devices allows for real-time data processing and reduced network bandwidth consumption, enabling more sophisticated applications like facial recognition and behavioral analysis.
Market Restraints
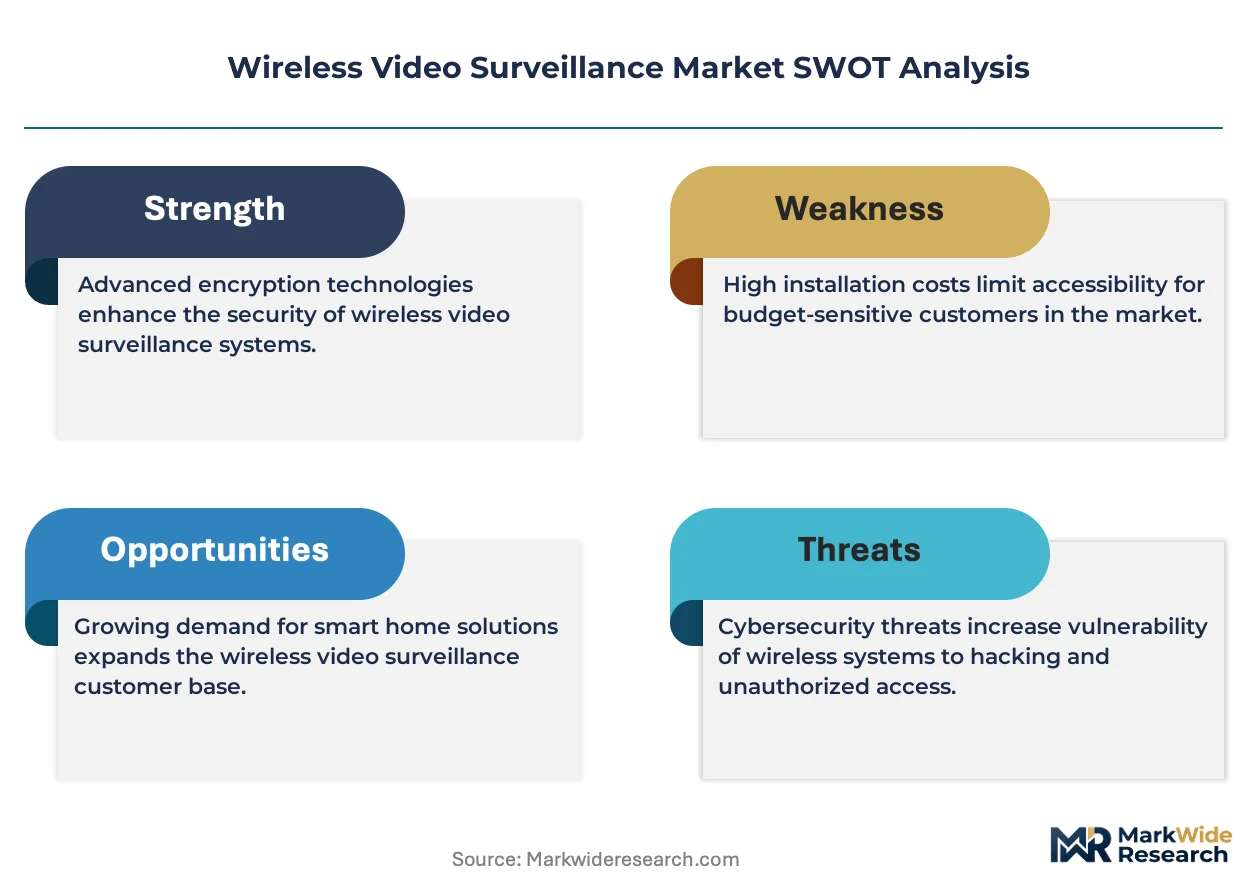
- Spectrum Congestion:Increased device density in urban areas leads to interference and performance degradation on the commonly used 2.4 GHz and 5 GHz Wi-Fi bands, posing a significant technical restraint on reliability.
- Data Privacy Regulation:Compliance with stringent data privacy frameworks, such as Europe's GDPR, introduces complexity and cost into product development, requiring features like privacy masking and auditable data access logs.
- Cybersecurity Vulnerabilities:Wireless systems are inherently exposed to network-based threats, and the risk of unauthorized access or data interception acts as a major barrier to adoption for security-sensitive end users.
Strategic Opportunities
- Cellular Connectivity:The application of 4G and 5G cellular technology opens opportunities for monitoring remote or temporary sites, such as construction projects and energy infrastructure, where traditional network cabling is impractical.
- VSaaS for SMEs:The subscription-based Video Surveillance as a Service (VSaaS) model presents a significant opportunity to penetrate the small and medium-sized enterprise market, which seeks lower upfront costs and simplified management.
- Analytics for Operations:There is a growing opportunity to repurpose video data for operational intelligence beyond security, including retail footfall analysis, manufacturing process optimization, and logistics monitoring.
Industry Challenges
- Legacy System Integration:A primary operational challenge is the difficulty of integrating new, high-resolution wireless IP cameras with customers' existing, often analog, legacy security systems and command centers.
- Data Management at Scale:Managing the vast volumes of high-definition video data generated by large-scale deployments creates significant challenges related to storage costs, data retention policies, and efficient retrieval.
- Cybersecurity Talent Gap:A shortage of skilled cybersecurity professionals capable of designing, implementing, and maintaining secure wireless surveillance networks presents a challenge for both vendors and end users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Video Surveillance Market |
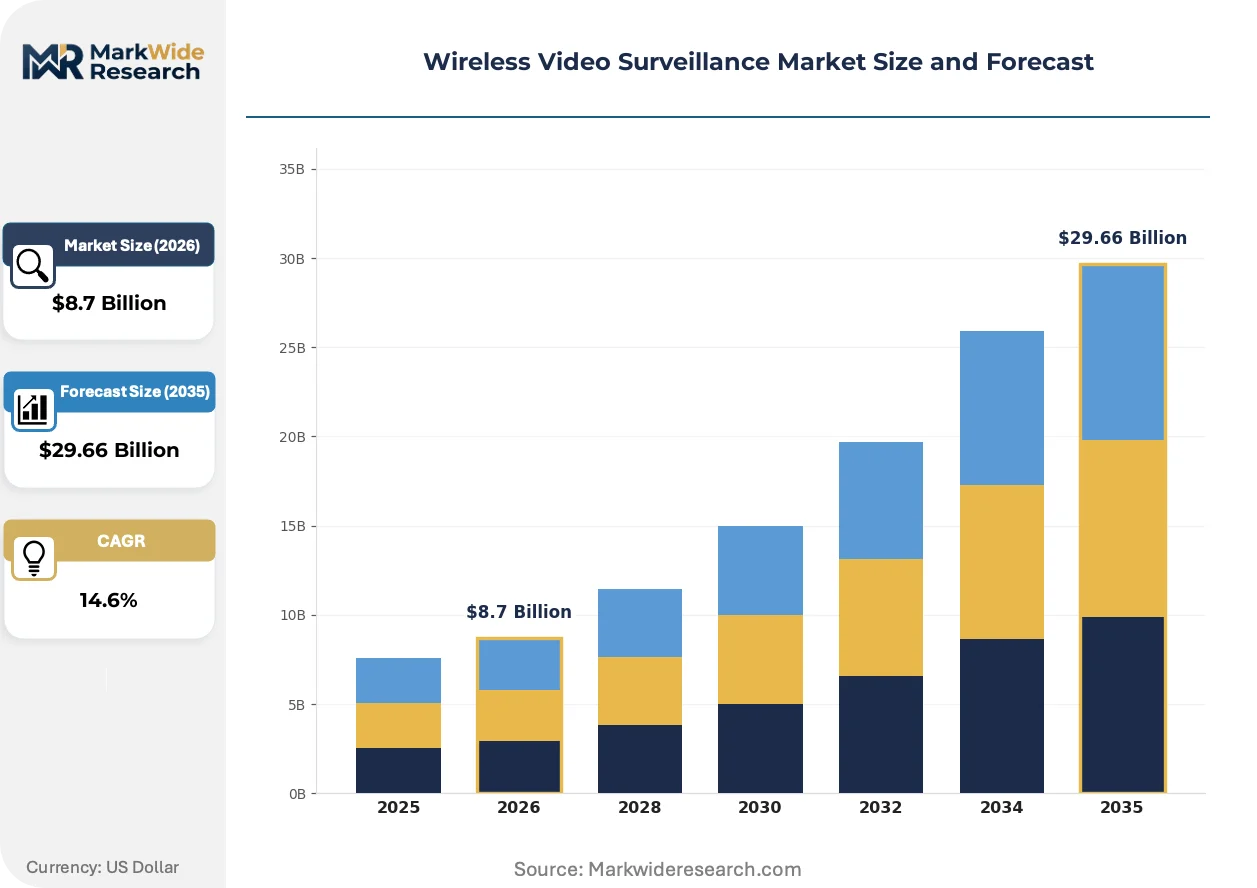
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IP Cameras, Analog Wireless Cameras, PTZ Cameras, Thermal Cameras, Network Video Recorders Technology: Wi-Fi, Zigbee, Cellular, Bluetooth, Ultra-Wideband Application: Perimeter Security, Traffic Monitoring, Public Safety, Retail Loss Prevention, Smart Building Surveillance End User: Government Facilities, Educational Institutions, Hospitality, Commercial Complexes, Residential Buildings |
| Companies Covered | Hangzhou Hikvision Digital Technology, Dahua Technology, Axis Communications, Bosch Security Systems, Cisco Systems, Honeywell, Hanwha Vision, Verkada, Eagle Eye Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Video Surveillance Market Strategic Shifts & Innovations
The evolution from hardware-centric security to data-driven services is the market's defining theme. This transition is powered by the convergence of cloud platforms, on-device artificial intelligence, and new recurring revenue models that prioritize ongoing analytical insights over one-time equipment sales.
Edge computing, which embeds AI analytics processors directly within cameras, reduces latency and conserves network bandwidth. Commercial and public safety sectors are rapidly adopting this for immediate threat detection and operational alerts without relying on cloud round-trips. This on-device intelligence is expanding into non-security applications, including retail analytics and industrial process monitoring, creating new value streams from video data.
Europe's General Data Protection Regulation (GDPR) imposes strict rules on the processing of personal data captured by surveillance systems. This forces manufacturers to build privacy-by-design principles directly into their hardware and software, such as automated video redaction. The data storage and access control product segments are most affected, responding with auditable user permissions and configurable data retention policies.
A fundamental shift in acquisition strategy sees customers favoring operational expenditure (OpEx) models over traditional capital expenditure (CapEx). The rise of Video Surveillance as a Service (VSaaS) disrupts the conventional channel by bundling hardware, software, and support into a single recurring payment. This all-in-one approach is most prominent in the small business sector, which prioritizes predictable costs and simplified vendor management.
Wireless Video Surveillance Market Segmentation
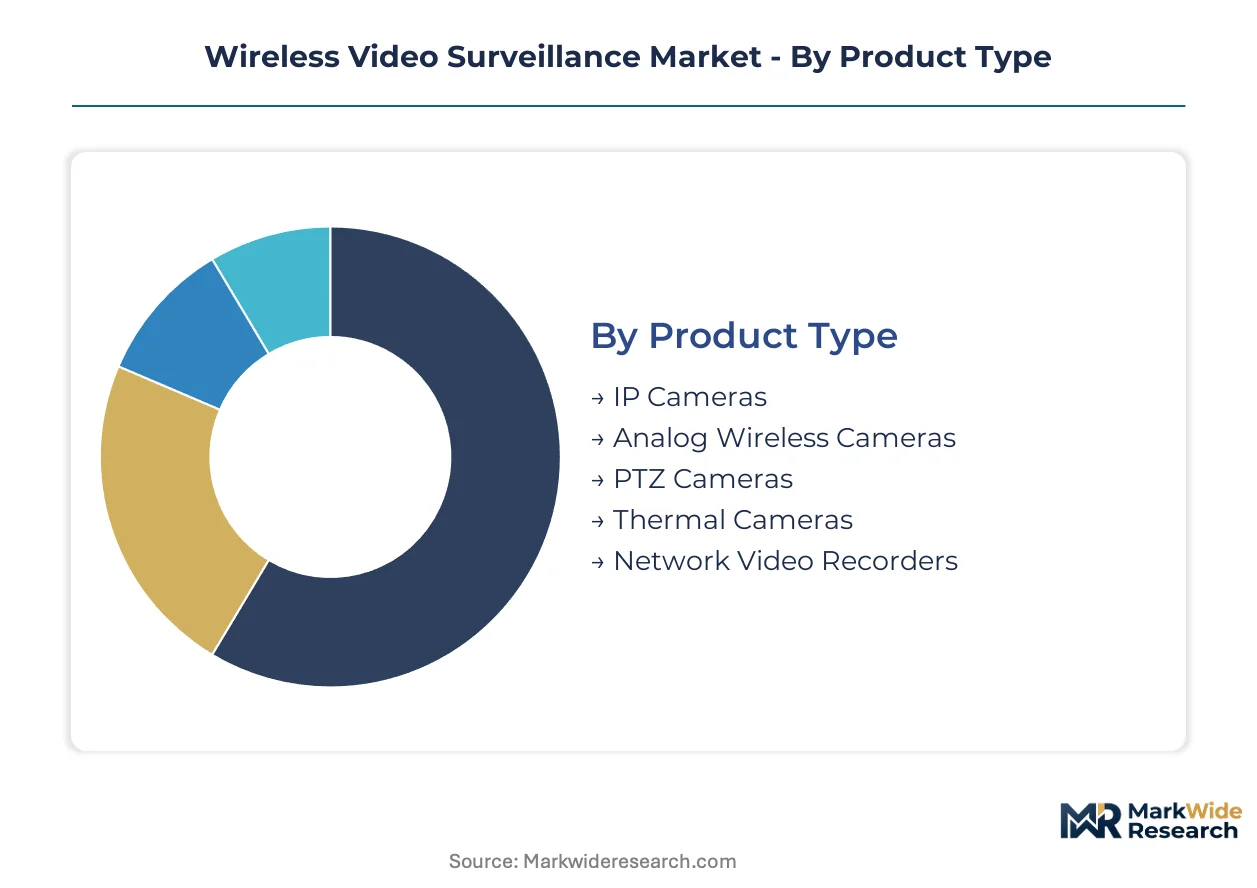
Market segmentation provides a critical framework for understanding the diverse needs and technological preferences within the wireless video surveillance industry. This analysis highlights how distinct product features, underlying technologies, specific applications, and varied end-user requirements shape demand and drive innovation across different market sub-sectors.
Product Type:
Achieving market access for wireless video surveillance products often involves navigating specific regulatory certifications, particularly for radio frequency emissions and data privacy standards like those from the FCC in the United States or GDPR in Europe.
- IP Cameras:These digital cameras transmit video data over an Internet Protocol network, offering high resolution, advanced analytics integration, and remote accessibility. Demand is concentrating in smart building surveillance projects due to their seamless integration with AI-powered edge devices.
- PTZ Cameras:Pan-Tilt-Zoom cameras offer remote control over camera orientation and magnification, providing flexible and wide-area coverage. Public safety initiatives in urban centers across India and Brazil significantly drive demand for these dynamic monitoring solutions.
- Analog Wireless Cameras:These systems transmit video via traditional radio frequencies, often serving as cost-effective solutions for basic surveillance needs.
- Thermal Cameras:Thermal cameras detect heat signatures rather than visible light, enabling effective surveillance in complete darkness, fog, or smoke.
- Network Video Recorders:NVRs are dedicated devices or software platforms used for recording, storing, and managing video streams from IP cameras.
IP Cameras sits at the top of the volume ranking, with PTZ Cameras climbing the fastest.
Technology:
Technology adoption in wireless video surveillance is largely dictated by the specific application's requirements for range, bandwidth, and power efficiency.
- Wi-Fi:This widely adopted technology uses 2.4 GHz or 5 GHz radio bands for short to medium-range data transmission, enabling flexible deployment. Commercial complexes widely adopt Wi-Fi for its cost-effectiveness and ease of integration into existing network infrastructure.
- Cellular:Leveraging 4G and 5G networks, cellular technology provides long-range, secure connectivity for remote or mobile surveillance applications. Demand for cellular technology is expanding in construction sites and energy infrastructure for monitoring temporary or isolated locations.
- Zigbee:A low-power, short-range wireless protocol, Zigbee is suitable for small-scale residential security systems and smart home integrations.
- Bluetooth:Primarily used for very short-range, peer-to-peer connections, Bluetooth often facilitates initial device setup or local data transfer for wireless cameras.
- Ultra-Wideband:UWB offers high-bandwidth, short-range communication with enhanced precision for location tracking and secure data transmission.
Technology choices reflect a trade-off between range, bandwidth, and power consumption.
Application:
The diverse applications of wireless video surveillance are driven by the specific security and operational intelligence needs of different customer types.
- Smart Building Surveillance:This application integrates wireless cameras with building management systems for security, energy optimization, and occupancy analytics. New commercial construction projects increasingly incorporate these systems for comprehensive oversight, particularly in dense urban environments.
- Public Safety:Wireless surveillance systems are deployed by government entities for law enforcement, emergency response, and urban monitoring to enhance citizen security. Government investments in India and Brazil are significantly expanding public safety networks, focusing on large-scale deployments.
- Perimeter Security:This application focuses on securing the external boundaries of properties, often utilizing motion-activated and long-range wireless cameras.
- Traffic Monitoring:Cameras are deployed to observe traffic flow, detect incidents, and manage urban transportation systems efficiently.
- Retail Loss Prevention:Wireless surveillance helps deter theft, monitor customer behavior, and manage inventory within retail environments.
Application diversity reflects the evolving role of video beyond traditional security functions.
End User:
The end-user segment for wireless video surveillance systems is characterized by varying operational requirements and margin profiles, influencing system complexity and feature prioritization.
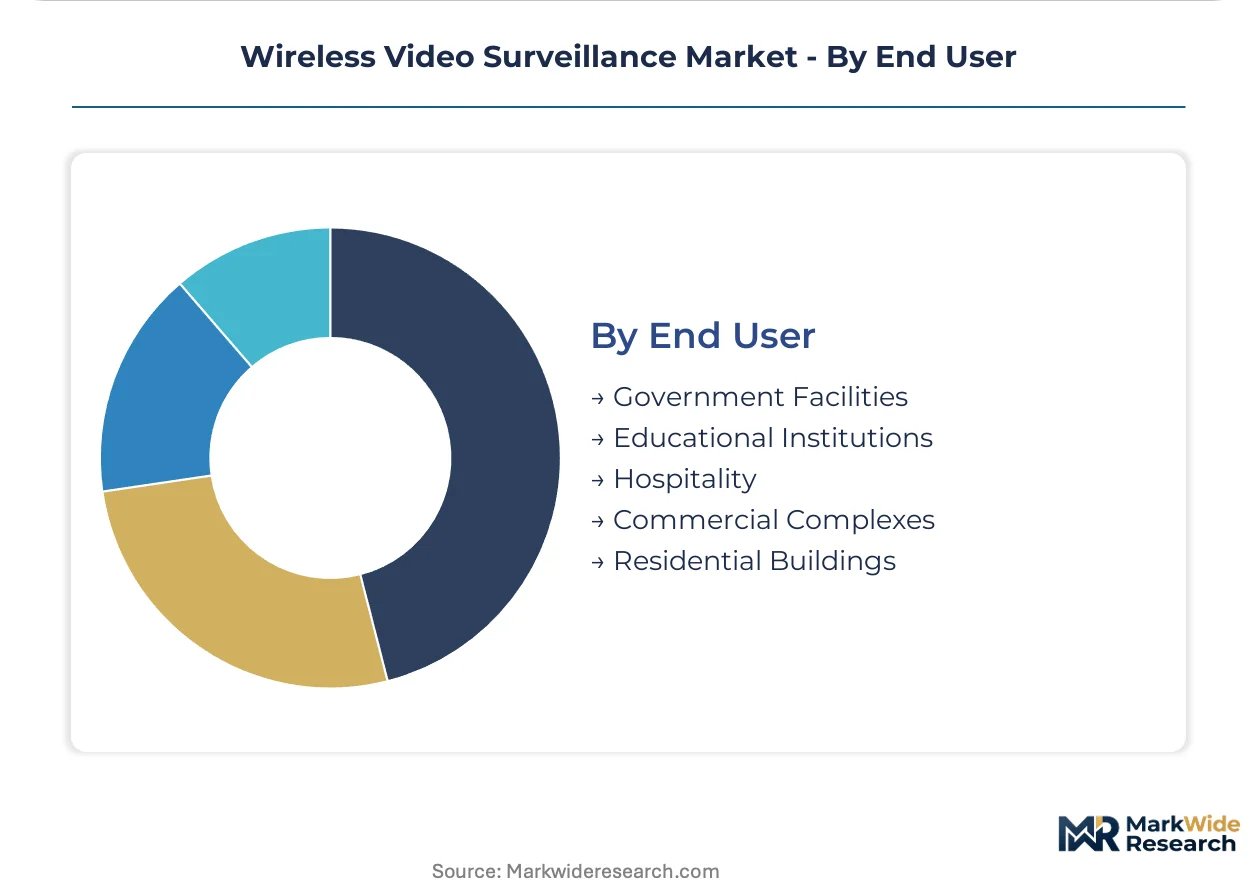
- Commercial Complexes:These users require extensive, integrated camera networks and advanced analytics for security, operational efficiency, and asset protection across large properties. These installations often demand high-resolution cameras and robust data management solutions.
- Government Facilities:Government entities demand robust, secure, and compliant systems for public safety, critical infrastructure monitoring, and asset protection. Regulatory compliance from bodies like the FCC or GDPR and data integrity are paramount for these high-security installations.
- Educational Institutions:Schools and universities implement wireless surveillance for campus safety, access control, and asset protection.
- Hospitality:Hotels and resorts utilize cameras to enhance guest safety, monitor common areas, and manage property security.
- Residential Buildings:Homeowners and residential property managers adopt wireless systems for home security, remote monitoring, and property management.
End-user requirements vary significantly, influencing system complexity and feature prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks significantly influence wireless video surveillance product design and market access. The cost of compliance with stringent data privacy and cybersecurity standards can create arbitrage opportunities, influencing manufacturing and deployment strategies. This dynamic shapes regional investment and technology adoption patterns across different geographies.
United States
Demand for smart building integration and commercial complex security drives wireless video surveillance adoption across various sectors. The Federal Communications Commission (FCC) stringently regulates the radio frequency spectrum used by these wireless devices. Tech hubs like Silicon Valley and Boston actively develop AI-powered edge devices for advanced analytics and real-time processing.
Germany
Strict adherence to the General Data Protection Regulation (GDPR) profoundly impacts surveillance system design and data handling practices. Smart city projects and industrial automation initiatives create demand for secure, privacy-by-design solutions. Cities such as Berlin and Munich are implementing advanced urban monitoring systems that prioritize data protection.
India
Government investment in public safety and traffic monitoring fuels significant market expansion for wireless networks. The Smart Cities Mission program actively accelerates large-scale wireless network deployments across urban areas. Urban centers including Mumbai and Delhi are significantly expanding their surveillance infrastructure to enhance citizen security.
Brazil
Public safety initiatives and infrastructure development generate concentrated demand for wireless surveillance systems in urban environments. Regulatory frameworks for data privacy and telecommunications influence deployment strategies and product features. Major cities like Rio de Janeiro and São Paulo are key areas for public security network expansion and traffic monitoring.
China
Extensive smart city projects and industrial monitoring drive significant demand for advanced wireless systems. National GB standards and the Cybersecurity Law impact product design, data management, and network security requirements. Shenzhen and Hangzhou serve as major hubs for surveillance technology manufacturing and large-scale urban deployment.
Wireless Video Surveillance Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the wireless video surveillance market. The industry exhibits a tiered structure, ranging from established hardware providers to agile software-centric innovators. Key strategic archetypes include integrated solution providers, open-platform enablers, and VSaaS specialists. Companies are primarily engaging in strategic partnerships for ecosystem expansion and continuous product portfolio diversification to capture new demand.
Specialists in integrated solutions, such as Hangzhou Hikvision Digital Technology Co., Ltd., represent a significant segment, offering comprehensive hardware and software packages. Axis Communications AB exemplifies the open-platform strategy, integrating with a wide ecosystem of third-party software and analytics providers. Verkada Inc. occupies a distinct position by providing a closed, end-to-end cloud solution, bundling hardware, software, and support into a single subscription service. These players illustrate the market's fundamental bifurcation between highly customizable multi-vendor systems and simplified, unified management platforms, each appealing to different customer priorities.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology |
| Dahua Technology |
| Axis Communications |
| Bosch Security Systems |
| Cisco Systems |
| Honeywell |
| Hanwha Vision |
| Verkada |
| Eagle Eye Networks |
| Others |
Cost & Logistics Intelligence
Small and medium-sized enterprises prioritizing operational expenditure models are reshaping procurement, forcing suppliers to bundle hardware and software, which impacts traditional transactional pricing structures.
Pricing Analysis
Distributor margins for traditional hardware sales are experiencing compression as customers favor subscription-based Video Surveillance as a Service (VSaaS) models. Pricing stratifies across premium, standard, and economy tiers, driven by hardware resolution, advanced analytics features, and bundled after-sales support. Pricing softness runs through the hardware segment due to the decoupling of recurring software revenue. Small and medium-sized businesses exhibit high price sensitivity, seeking lower upfront costs and predictable monthly payments for simplified management.
Supply Chain Analysis
Direct-to-customer subscription models are streamlining distribution for vertically integrated providers like Verkada, bypassing traditional channel partners. Supply concentrates in Asian manufacturing hubs, particularly China, for IP cameras and associated components. Key dependencies include AI chipsets for edge processing and radio frequency modules for wireless transmission. Geopolitical tensions affecting component availability from major manufacturing regions present a structural supply chain risk. Distribution for open-platform providers often runs through a network of system integrators and value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless video surveillance market is transitioning into a late-cycle quality story, driven by demand for AI-powered edge analytics and privacy-by-design solutions.
For Market Incumbents: Acquire specialized AI analytics firms to accelerate edge intelligence capabilities and maintain a competitive advantage. This strategy counters the threat from agile software-centric new entrants. Investment in privacy-by-design R&D helps navigate stringent regulatory frameworks like GDPR. Channel control through exclusive partnerships with large system integrators also strengthens market position.
For New Entrants and Emerging Players: Cellular connectivity innovations create a technology-first wedge into remote site monitoring applications, such as construction and energy infrastructure. Target small and medium-sized enterprises with simplified, subscription-based VSaaS offerings. A go-to-market angle focusing on unified cloud management and predictable OpEx models resonates strongly with this price-sensitive segment.
For Investors and Strategic Acquirers: Asymmetric upside sits with software-centric VSaaS providers demonstrating strong recurring revenue growth and a clear path to operational intelligence beyond security. Long-term viability depends on platforms capable of repurposing video data for diverse operational insights. A key signal to watch is the increasing share of recurring revenue relative to one-time hardware sales, indicating successful business model transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch | Expansion of AI-powered edge devices enhances real-time threat detection and operational efficiency. |
| Strategic Partnership | Integration with smart building platforms secures new commercial construction projects. |
| Acquisition of Specialist Firm | Ingesting cybersecurity expertise mitigates wireless network vulnerabilities and builds trust. |
| Platform Integration | Open-platform strategies facilitate broader ecosystem participation for Axis Communications. |
| Geographic Expansion | Deployment into urban centers in India and Brazil taps concentrated public safety demand. |
Research Approach
Direct dialogue with security directors, IT procurement officers, smart city planners, and system integrators informed this analysis. Primary insights were triangulated with secondary data from FCC and GDPR regulatory documents, company annual reports, and technology journals. This approach combined bottom-up market sizing with top-down validation.
Market sizing and growth projections were derived from a multi-factor analytical framework. The model incorporated segmentation dimensions including product type, technology, application, end user, and regional regulatory frameworks across the analysis window. Compound annual growth rates were established by analyzing historical trends and future market drivers, with inputs such as smart building construction rates and government infrastructure spending.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving data privacy regulations and technological disruptions. All forecasts reflect assumptions documented within the study. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
Germany Video Surveillance Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
India Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
Surveillance Camera Systems Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
North America Pedestrian Detection Systems Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market