
 Wearable and Body-Worn Cameras Market | 2026-2036
Wearable and Body-Worn Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable and Body-Worn Cameras Market Analytics
Aftermarket service revenue is reshaping competitive economics in wearable and body-worn cameras. Axon Enterprise leverages its cloud-based evidence management ecosystem to sustain recurring subscription income alongside hardware sales. Panasonic dominates professional-grade camera manufacturing for law enforcement, while Garmin anchors the outdoor enthusiast segment with ruggedized, GPS-integrated wearable recorders.
Wearable and body-worn cameras are compact, sensor-integrated recording devices typically weighing under 200 grams, designed for hands-free operation via head-mounted, chest-mounted, or clip-on form factors with resolution standards reaching 1080p or higher. These systems serve commercial and institutional purposes spanning real-time surveillance, post-incident evidence documentation, and remote field monitoring. Head-mounted configurations command premium positioning in tactical law enforcement applications, while smart glasses represent the fastest-growing product type as enterprises adopt augmented-reality workflows. Wi-Fi and 4G LTE connectivity segments capture disproportionate margin pools through recurring data-service contracts.
The FCC governs radio-frequency emissions for wireless-enabled body cameras in the United States, while GDPR compliance requirements in Europe constrain cross-border evidence storage and cloud architecture design. The EU AI Act introduces additional scrutiny for facial-recognition capabilities integrated into smart glasses and surveillance platforms. Stakeholders must monitor evolving data-retention mandates and interoperability standards that determine which vendors qualify for government procurement frameworks.
Market Dynamics
Cloud-based evidence management ecosystems are restructuring competitive economics, converting one-time hardware transactions into recurring subscription revenue streams that lock municipal police departments into long-term vendor relationships.
Growth Catalysts
- Federal grant programs:Municipal police departments in the United States access Justice Department funding streams that subsidize body-worn camera procurement and reduce budget friction for cash-constrained agencies.
- GDPR data-protection frameworks:European evidence-handling protocols mandate encrypted storage and audit-trail capabilities, forcing vendors to upgrade security architectures that subsequently qualify for premium government contracts.
- 4G LTE connectivity modules:Real-time streaming capabilities enable remote command-center oversight of tactical operations, expanding addressable use cases beyond post-incident review into live situational awareness.
Market Restraints
- Image sensor supply concentration:Advanced CMOS sensors for low-light recording concentrate among East Asian semiconductor foundries, exposing procurement timelines to geopolitical friction and export control volatility.
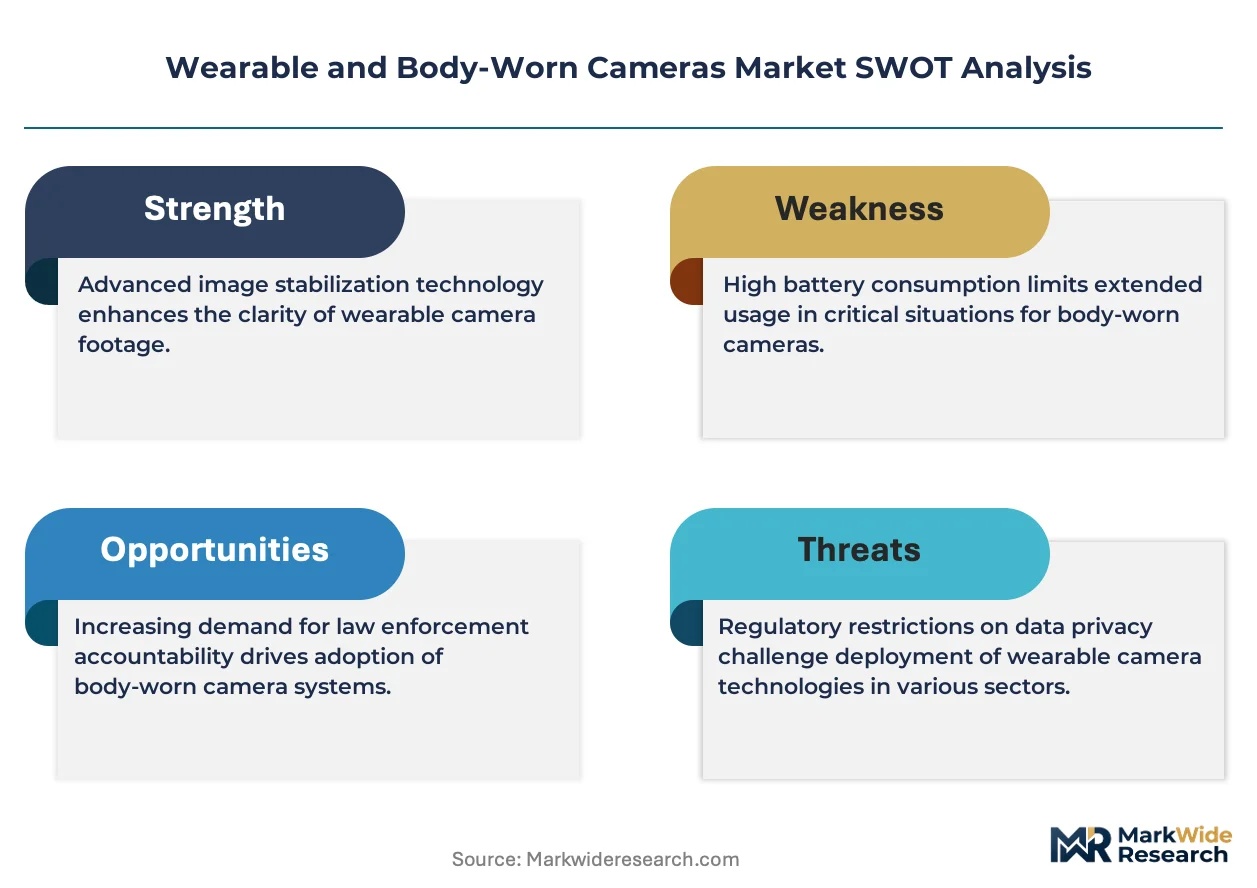
- EU AI Act facial-recognition restrictions:Prohibitions on real-time biometric identification in public spaces constrain feature roadmaps for smart glasses and limit premium pricing for AI-enabled wearable platforms.
- Lithium-polymer battery cost structures:Extended shift-length recording requirements demand high-density power cells that inflate bill-of-materials costs and compress hardware margins at volume price points.
Strategic Opportunities
- India industrial safety mandates:Factory inspectorate regulations in Maharashtra and Gujarat are beginning to require visual documentation of hazardous operations, opening a new enforcement-driven demand vertical.
- Augmented-reality workflow convergence:Integration of heads-up displays with hands-free recording creates enterprise utility for field-service technicians in energy and telecommunications infrastructure maintenance.
- Subscription-based evidence platforms:Cloud storage and chain-of-custody automation transform municipal procurement from capital expenditure cycles into operational budget line items with higher lifetime value capture.
Industry Challenges
- Cybersecurity certification timelines:FedRAMP authorization for federal agency cloud deployment extends vendor sales cycles by 18-24 months and requires dedicated compliance engineering teams.
- Legacy digital evidence system integration:Proprietary data formats from incumbent platforms create migration friction when police departments attempt to consolidate multi-vendor camera fleets under unified management systems.
- Forensic video analyst talent scarcity:Specialized skills in metadata extraction and tamper detection command premium compensation, constraining service expansion for evidence-management providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable and Body-Worn Cameras Market |
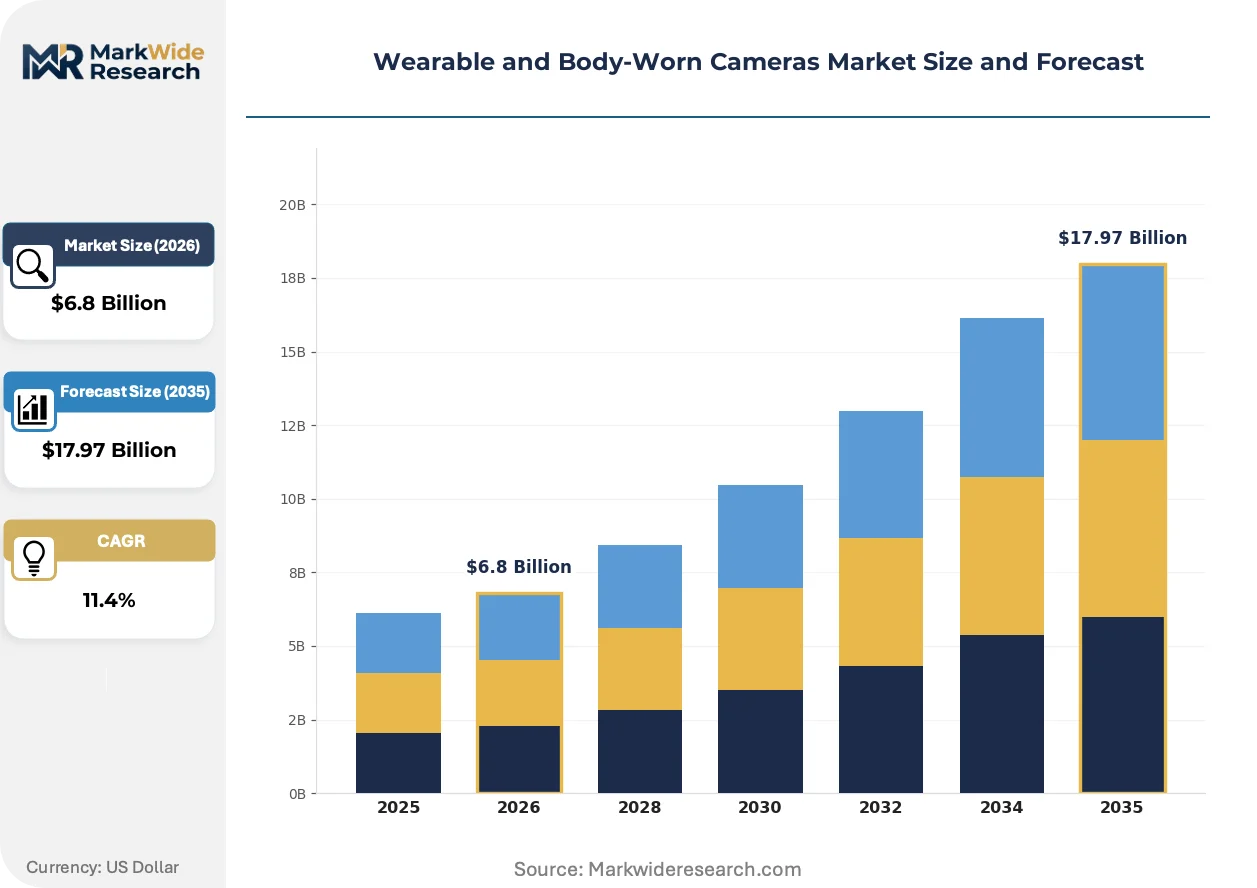
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-mounted, Chest-mounted, Clip-on, Smart Glasses Technology: Wi-Fi, Bluetooth, 4G LTE, GPS End User: Law Enforcement, Security Personnel, Healthcare Professionals, Outdoor Enthusiasts Application: Surveillance, Field Monitoring, Training, Documentation |
| Companies Covered | Panasonic Corporation, NICE Systems Ltd., Axon Enterprise Inc., Hytera Communications Corporation Limited, GoPro Inc., Motorola Solutions Inc., Garmin Ltd., WatchGuard Technologies Inc., Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable and Body-Worn Cameras Market Evolving Landscape
Edge-computing architectures are redistributing processing loads from centralized servers to camera hardware itself, enabling real-time analytics that were previously impossible under bandwidth-constrained field conditions.
On-device AI inference engines are digitizing evidence triage workflows. Patrol officers in Chicago and London Metropolitan units now receive automated flagging of critical incidents without manual video review. This compression of review cycles is digitizing how departments allocate investigative resources and prioritize case preparation.
GDPR's cross-border data-transfer restrictions are fragmenting cloud architecture strategies. European police forces must maintain sovereign data residency, compelling vendors to establish regional hosting infrastructure. French and German procurement frameworks now disqualify providers lacking certified EU-based server capacity.
Evidence unbundling from hardware bundles is altering municipal buying patterns. Texas and Florida departments increasingly separate camera acquisition from storage contracts, pitting specialized cloud providers against integrated vendors. This disaggregation is most visible in mid-sized agencies with sufficient procurement sophistication to manage multi-vendor relationships.
Wearable and Body-Worn Cameras Market Segmentation
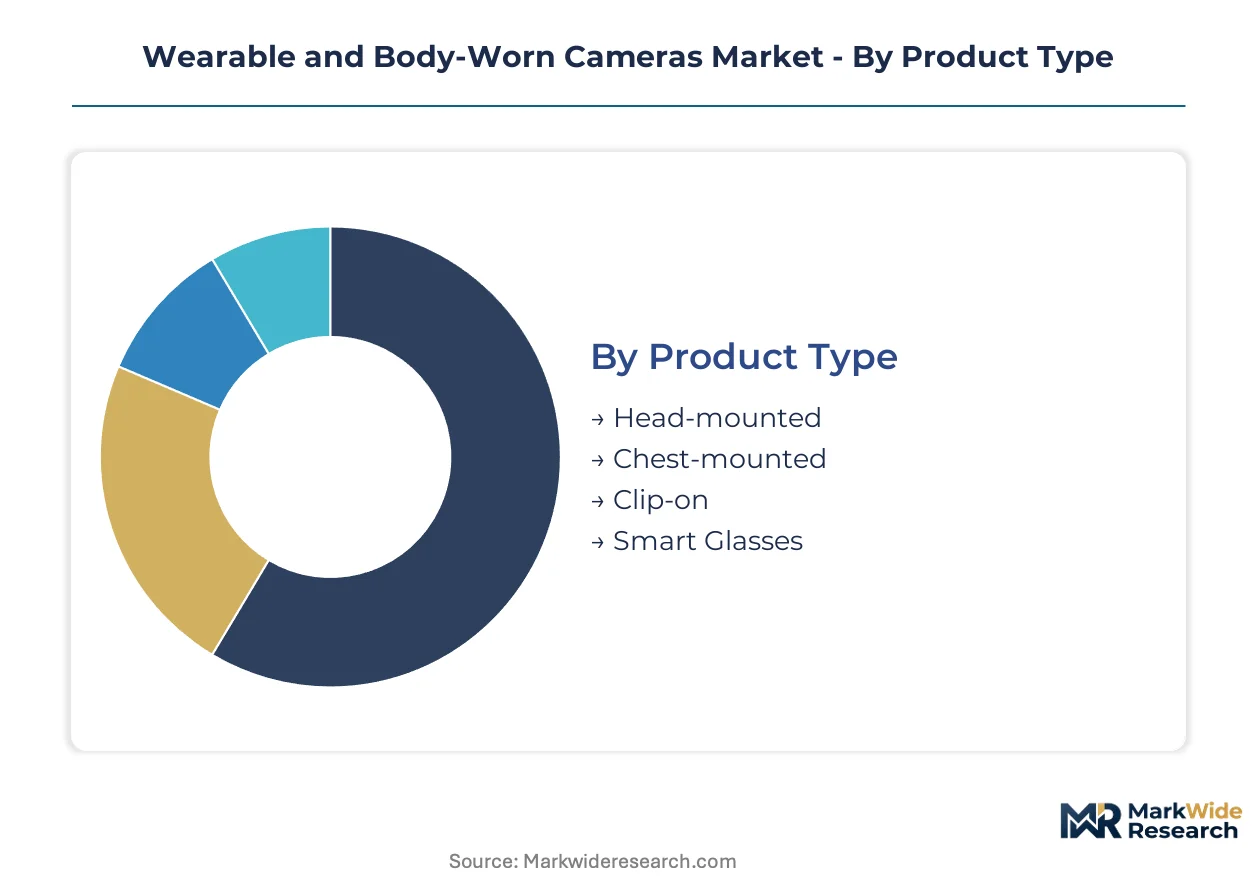
Wearable and body-worn camera markets fragment across four structural dimensions that determine pricing power, procurement channels, and compliance burdens. Product form factors dictate hardware margins while connectivity technologies unlock recurring revenue streams. End-user verticals and application contexts shape feature roadmaps and certification requirements.
Product Type:
Mature tactical configurations coexist with emerging augmented-reality platforms, creating a bifurcated hardware landscape.
- Head-mounted:Helmet and tactical headset integrations deliver stabilized recording for SWAT and military operators. Demand concentrates in United States federal law enforcement grants, constrained by extended battery life requirements for 12-hour shifts.
- Smart Glasses:Augmented-reality overlays with hands-free documentation are gaining enterprise adoption among field-service technicians. German industrial safety inspectors and French utility maintenance crews pilot these for remote expert guidance workflows.
- Chest-mounted:Standardized uniform attachments dominate municipal police procurement due to established evidence-chain protocols and judicial acceptance.
- Clip-on:Compact lapel devices serve private security and healthcare visitor documentation where discretion outweighs field-of-view requirements.
Chest-mounted units retain volume leadership; smart glasses hold the steepest expansion curve.
Technology:
Connectivity tiers separate capital-hardware sales from subscription-driven revenue models.
- 4G LTE:Cellular modules enable real-time streaming to command centers during active incidents. United Kingdom Metropolitan Police and Chicago Police Department deployments prioritize this capability for tactical oversight, though monthly data contracts inflate total cost of ownership.
- Wi-Fi:Local network offload dominates evidence upload workflows in station-house environments. GDPR-compliant European forces require segmented architectures where Wi-Fi never touches public internet during transfer.
- GPS:Location metadata embedding supports chain-of-custody verification and incident reconstruction for traffic enforcement units.
- Bluetooth:Low-energy pairing with smartphones extends battery life for outdoor enthusiast and healthcare documentation use cases.
Wi-Fi retains volume leadership; 4G LTE commands the premium pricing tier.
End User:
Procurement sophistication varies dramatically across institutional buyers versus consumer segments.
- Law Enforcement:Municipal and federal agencies drive standardization through Justice Department grant frameworks. Compliance with FBI Criminal Justice Information Services security policies filters vendor qualification.
- Security Personnel:Private firms in Texas and Florida increasingly unbundle hardware from cloud storage, managing multi-vendor fleets.
- Healthcare Professionals:HIPAA-compliant documentation of patient encounters creates demand for encrypted, audit-trailed recording in United States hospital systems.
- Outdoor Enthusiasts:Ruggedized, GPS-integrated devices serve adventure sports documentation with consumer-grade durability expectations.
Law enforcement retains volume leadership; healthcare professionals represent the fastest-growing trajectory.
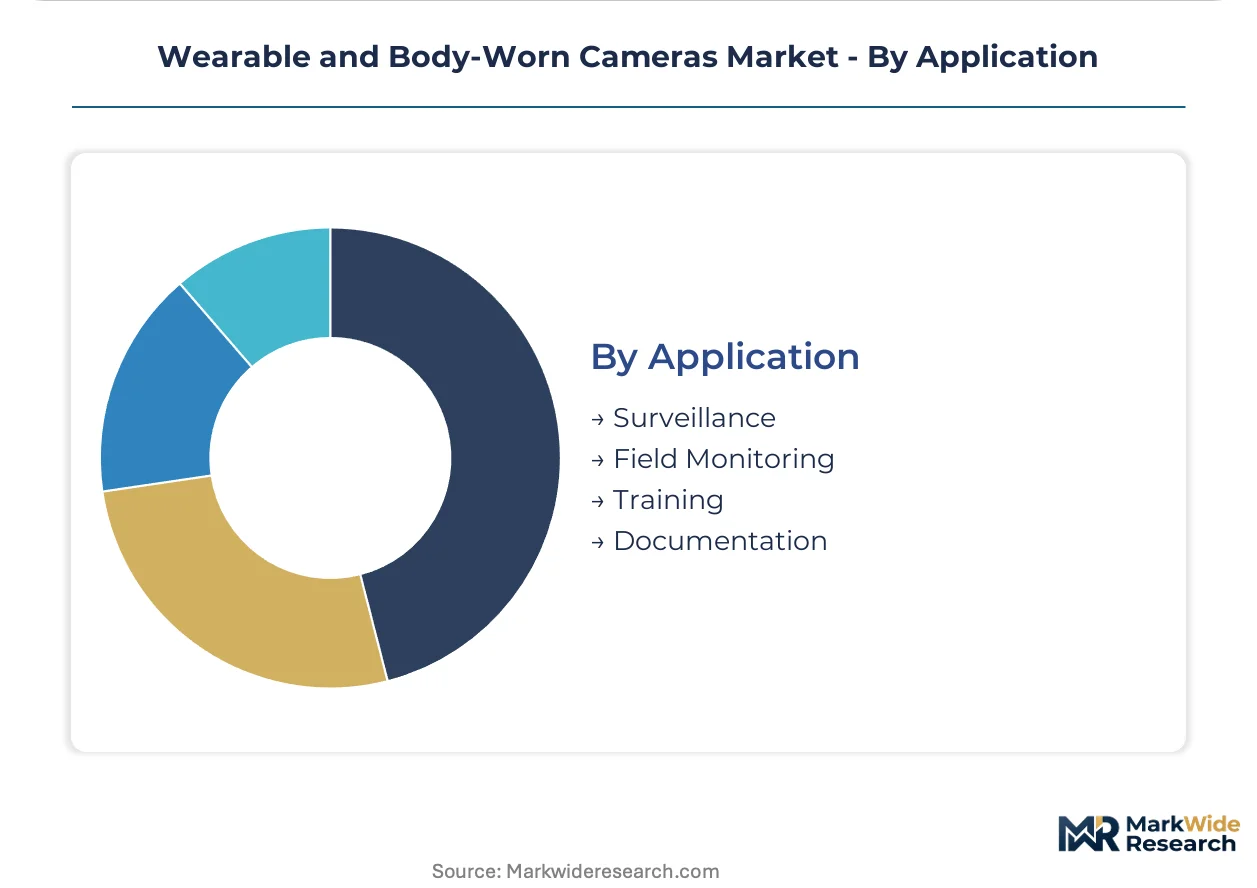
Application:
Use-case specificity determines sensor specifications, storage architectures, and software integration depth.
- Surveillance:Continuous recording with pre-event buffer capabilities dominates tactical law enforcement specifications. Low-light CMOS performance and image stabilization differentiate procurement winners.
- Documentation:Healthcare and insurance claims workflows prioritize tamper-evident metadata and automated redaction tools for privacy compliance.
- Field Monitoring:Remote infrastructure inspection in energy and telecommunications sectors drives demand for hands-free operation with heads-up display integration.
- Training:De-escalation simulation and after-action review applications require synchronized multi-angle capture and annotation tools.
Surveillance retains volume leadership; field monitoring climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States municipal buyers exhibit the lowest price elasticity, absorbing premium hardware-plus-subscription bundles through federal grant pipelines, while Indian industrial safety adopters face acute budget constraints that favor unbundled procurement of lower-cost hardware.
United States
Justice Department grant programs covering up to 50% of acquisition costs drive municipal police department procurement volumes. FCC Part 15 radio-frequency emission standards mandate certification for all wireless-enabled devices entering federal agency supply chains. Chicago and Dallas-Fort Worth metropolitan agencies are consolidating multi-vendor fleets under unified cloud evidence management architectures.
Germany
Federal police modernization initiatives and state-level interior ministry budgets fund body-worn camera deployments across all 16 Länder. GDPR cross-border data transfer restrictions compel vendors to maintain sovereign EU server infrastructure. Bavarian manufacturing clusters around Munich and Nuremberg are piloting smart glasses for industrial safety inspectorate documentation workflows.
United Kingdom
Metropolitan Police Service procurement frameworks establish technical specifications adopted by regional constabularies. Home Office funding streams subsidize rollout to frontline officers in England and Wales. Greater Manchester and West Midlands forces are testing 4G LTE real-time streaming capabilities for tactical command oversight.
India
Maharashtra and Gujarat factory inspectorate mandates for hazardous operation visual documentation create enforcement-driven demand from manufacturing SMEs. Bureau of Indian Standards certification requirements filter import eligibility for professional-grade recording equipment. Bangalore and Hyderabad technology corridors are emerging as domestic assembly locations for cost-optimized wearable devices.
Australia
State police force procurement through Victoria Police and New South Wales Police standardization programs drives volume concentration. Therapeutic Goods Administration oversight applies to healthcare documentation devices entering hospital systems. Perth mining operations and Queensland energy infrastructure projects are adopting ruggedized field monitoring recorders for remote inspection workflows.
Wearable and Body-Worn Cameras Market Competitive Landscape
Integrated platform vendors and specialized hardware fabricators split the market into distinct competitive spheres with divergent margin structures. The vendor base concentrates around three strategic archetypes: cloud-native evidence ecosystem providers, professional-grade camera manufacturers with law enforcement heritage, and ruggedized outdoor electronics specialists. Dominant competitive moves include strategic partnerships between hardware OEMs and cloud software vendors, plus geographic expansion through localized certification and regional hosting infrastructure.
Within the integrated platform tier, Axon Enterprise exemplifies the subscription-revenue archetype through its cloud-based evidence management positioning. Panasonic Corporation occupies a position representing professional-grade manufacturing heritage with established law enforcement supply relationships. Garmin Ltd. anchors the ruggedized outdoor specialist segment, exemplifying GPS-integrated wearable recorder positioning for adventure sports and field applications.
| Leading Market Players |
|---|
| Panasonic Corporation |
| NICE Systems Ltd. |
| Axon Enterprise Inc. |
| Hytera Communications Corporation Limited |
| GoPro Inc. |
| Motorola Solutions Inc. |
| Garmin Ltd. |
| WatchGuard Technologies Inc. |
| Sony Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in Taiwanese CMOS sensor foundries is compressing component pricing while simultaneously enabling tier-one vendors to negotiate volume discounts that tier-two assemblers cannot match. This utilization asymmetry stratifies procurement power across the vendor base, with integrated platform providers capturing margin that hardware-only competitors surrender.
Pricing Analysis
Aftermarket service revenue, particularly cloud storage subscriptions and evidence-management contracts, now drives lifetime value capture exceeding hardware margins by multiples. Subscription-based pricing stratifies across premium, standard, and economy tiers anchored to retention periods and chain-of-custody automation depth. Pricing pressure stems from municipal procurement offices unbundling camera acquisition from storage contracts in Texas and Florida, forcing pure-play hardware vendors toward commodity positioning. Federal grant-subsidized buyers in the United States exhibit lowest price sensitivity, while Indian industrial safety adopters face acute budget constraints favoring unbundled, lower-cost hardware procurement.
Supply Chain Analysis
Contract-manufacturing concentration rests with Foxconn and Flex facilities in Shenzhen and Penang, supplemented by specialized EMS providers in Vietnam for final assembly. Image sensor supply concentrates in Taiwan and South Korea, while lithium-polymer battery cells source predominantly from Chinese and Japanese chemical producers. Single-source vulnerability in advanced CMOS sensors for low-light recording exposes procurement timelines to export control volatility and geopolitical friction. Distribution runs through direct municipal procurement channels for law enforcement verticals, with enterprise and consumer segments served via specialized electronics distributors and direct-to-platform digital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Law enforcement technology procurement cycles are recovering from pandemic-delayed municipal budgets, with Justice Department grant program renewals providing cyclical lift to vendor order books.
For Market Incumbents: Build switching-cost moats through deeper integration of on-device AI inference engines that automate evidence triage workflows. Incumbents should consolidate multi-vendor fleet management capabilities to capture municipal agencies consolidating disparate camera deployments, while investing in FedRAMP authorization engineering teams to shorten federal sales cycles threatened by cybersecurity certification delays. For New Entrants and Emerging Players: Build out white-space positions in healthcare documentation and Indian industrial safety inspectorate mandates, where HIPAA compliance expertise and BIS certification capabilities filter competition. The most penetrable entry point lies in Maharashtra and Gujarat factory compliance workflows, where enforcement-driven demand from manufacturing SMEs meets acute budget constraints favoring cost-optimized hardware with modular cloud connectivity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native evidence ecosystem providers with municipal police department subscription lock-in. Long-term viability favors vendors with demonstrated cross-border data-residency compliance for GDPR-constrained European procurement. The signal to watch is unbundling momentum in mid-sized United States agencies, where separation of hardware and storage contracts indicates procurement sophistication enabling multi-vendor competition.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Evidence Platform Integration | Locks municipal agencies into recurring subscription revenue streams with high switching costs. |
| Regional Data Residency Infrastructure | Qualifies vendors for French and German procurement frameworks requiring GDPR-compliant EU hosting. |
| On-Device AI Inference Development | Automates incident flagging for Chicago and London Metropolitan units, compressing review cycles. |
| Healthcare HIPAA Compliance Certification | Opens hospital system documentation workflows with encrypted, audit-trailed recording requirements. |
| Indian BIS Certification and Local Assembly | Enables cost-optimized participation in Maharashtra and Gujarat industrial safety mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal police procurement officers, cloud evidence platform product managers, CMOS sensor procurement leads at camera OEMs, and industrial safety compliance officers in Indian manufacturing states. Secondary validation drew from FCC Part 15 equipment authorization databases, EU public procurement notices under GDPR frameworks, Bureau of Indian Standards certification registries, and municipal budget disclosure filings. Bottom-up unit shipment estimates were triangulated against top-down addressable market sizing across connectivity tiers and end-user verticals.
Calibration against historical adoption curves in United States federal grant cycles and European police modernization waves anchored growth assumptions across the analysis window. Segmentation modeling incorporated product form factor, connectivity technology, end-user institutional type, and application context dimensions. CAGRs were derived from regression analysis of procurement volume trends against funding program allocations and regulatory mandate implementation timelines, with cross-validation against component supply constraints in image sensor and battery cell markets.
Stress conditions across federal grant program suspension, EU AI Act facial-recognition prohibition expansion, and lithium-polymer supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procurement cycle normalization and cloud subscription attach rates. Quarterly review of municipal budget adoption timelines and export control classification adjustments for CMOS sensors is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Wireless Video Surveillance Market