
 India Surveillance Analog Camera Market | 2026-2036
India Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
India Surveillance Analog Camera Market Insights
Skilled CCTV installation technician shortages across Uttar Pradesh and Bihar is redrawing how vendors deploy service networks in northern India. CP Plus leverages its extensive distributor footprint to sustain rural market coverage where trained labor remains scarce. Hikvision India Pvt. Ltd. anchors premium project bids through localized technical support centers. Prama India Private Limited competes on price-performance positioning for mid-tier commercial installations.
Analog surveillance cameras transmit continuous video signals over coaxial cable without digital encoding, typically operating at resolutions up to 960H or D1 with PAL/NTSC signal formats and requiring dedicated DVR units for recording storage. Bullet cameras dominate outdoor perimeter deployments across manufacturing facilities and warehousing complexes due to weather-resistant housings and infrared night-vision range. PTZ cameras command higher margin pools in traffic monitoring and large public venue applications where motorized pan-tilt-zoom functionality eliminates multiple fixed-camera requirements. Indoor dome configurations lead volume in retail surveillance and banking lobby installations where discrete positioning reduces vandalism risk.
BIS certification mandates under the Compulsory Registration Scheme govern electronic security product imports and domestic manufacturing quality benchmarks. The Ministry of Home Affairs Safe City project guidelines and state-level police modernization programs shape procurement specifications for public safety camera networks. Stakeholders must weigh analog infrastructure replacement cycles against hybrid DVR migration paths as IP-based systems gain policy preference in central government tenders.
Market Dynamics
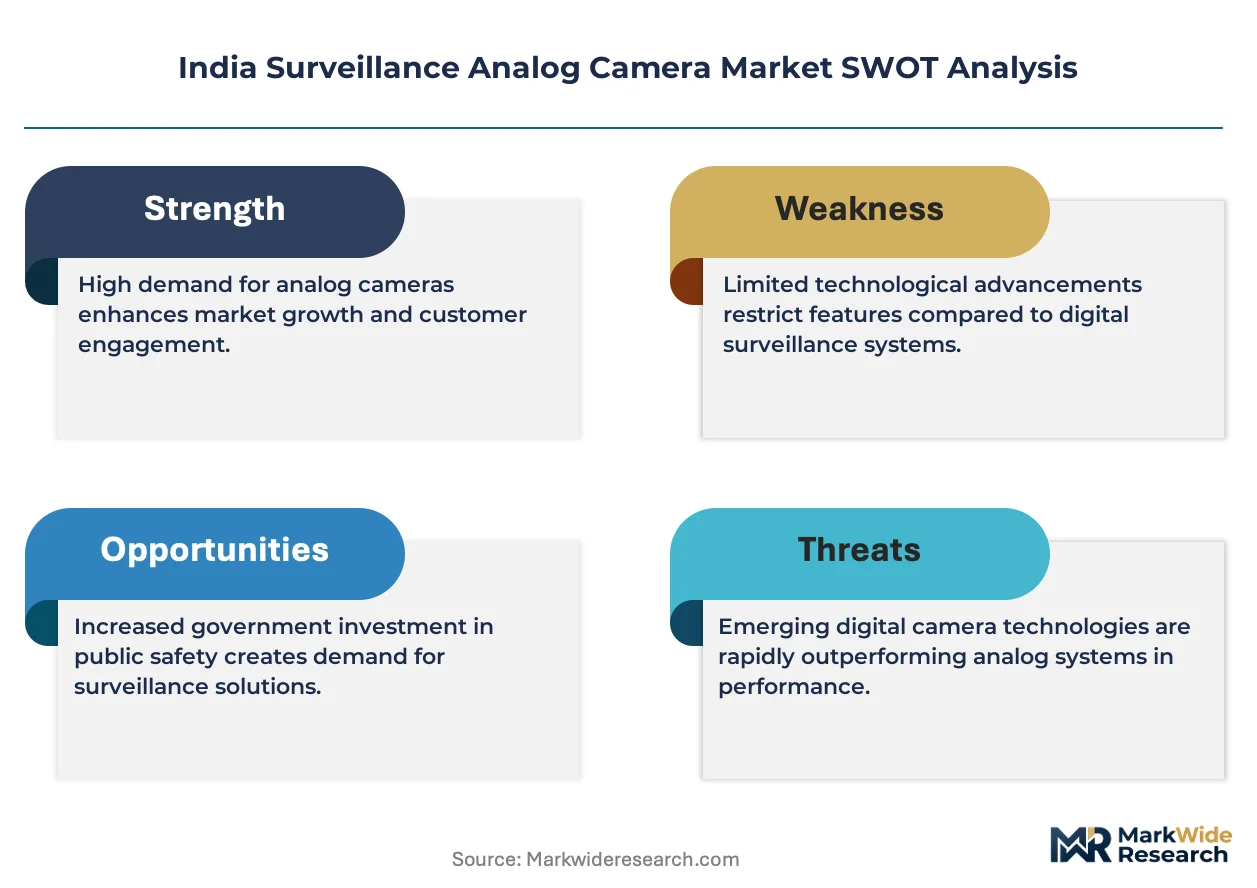
The India Surveillance Analog Camera Market pivots on BIS certification mandates that filter import flows and elevate domestic manufacturing compliance costs, compressing vendor margins while steering procurement toward certified suppliers.
Growth Catalysts
- Smart City Infrastructure:Maharashtra and Gujarat municipal projects expand camera network procurement for traffic management and public safety monitoring.
- PLI Scheme Incentives:Production-linked incentives for electronics manufacturing attract component localization investments that reduce import dependency.
- Tier-Two Banking Expansion:South Indian states accelerate branch security upgrades where analog systems still dominate cost-sensitive installations.
Market Restraints
- Copper Cable Cost Volatility:Coaxial infrastructure material costs fluctuate with global copper pricing, squeezing project budgets for large-scale analog deployments.
- IP Camera Substitution:Network-based surveillance systems capture premium project bids in government tenders where policy preference tilts toward digital encoding.
- BIS Compliance Friction:Compulsory Registration Scheme testing timelines delay product launches by three to six months for unregistered imports.
Strategic Opportunities
- Hybrid DVR Migration:Bridge technology enables analog camera reuse while supporting IP integration, extending equipment lifecycle in budget-constrained facilities.
- Uttar Pradesh Service Networks:Technician training partnerships with industrial training institutes address installation labor scarcity in northern hinterlands.
- Safe City Program Tailwinds:Ministry of Home Affairs guidelines for police modernization fund camera deployments in state capitals and district headquarters.
Industry Challenges
- Certification Bottlenecks:BIS laboratory capacity constraints create testing queues that stall product registration for new market entrants.
- Legacy Integration Complexity:Existing coaxial infrastructure in aging commercial buildings complicates partial upgrade paths to hybrid or full-IP architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Surveillance Analog Camera Market |
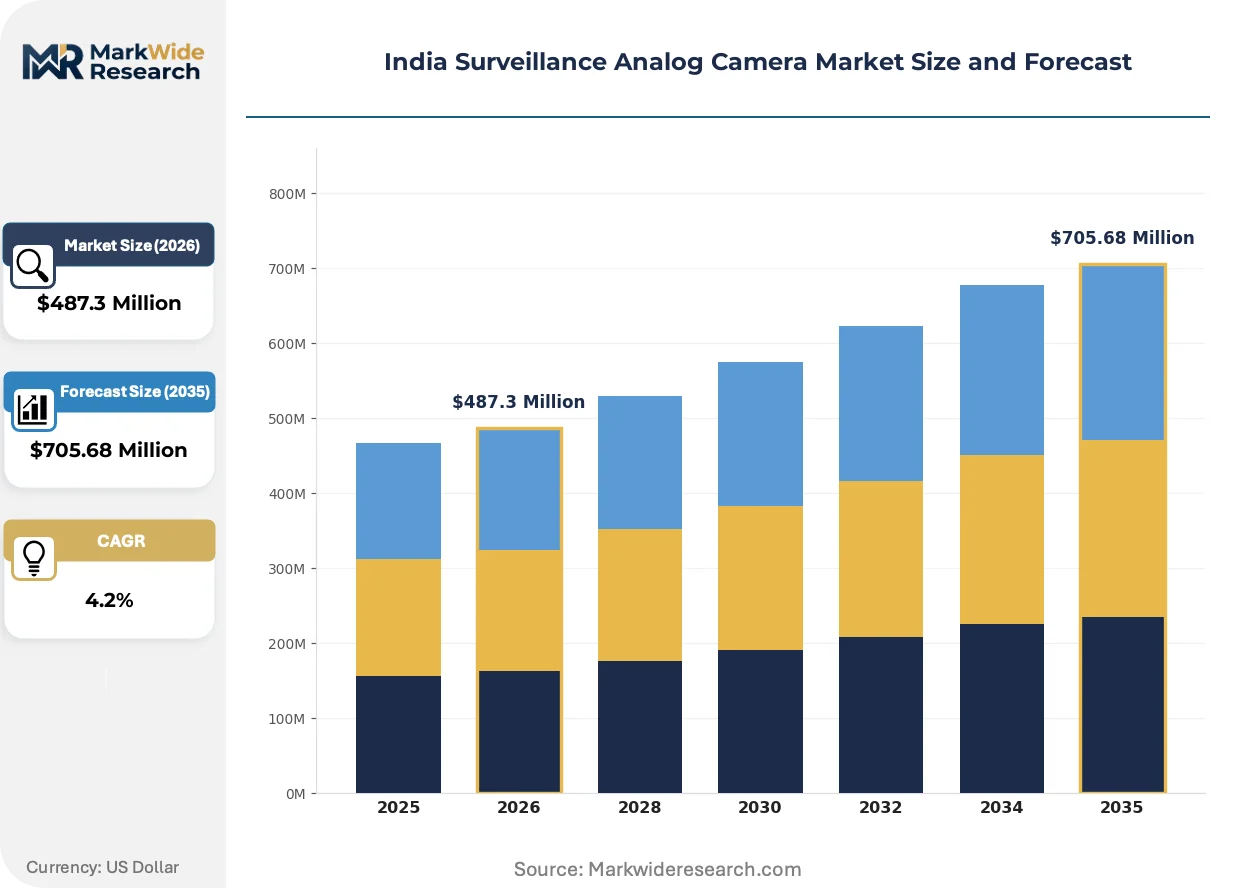
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $705.68 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: Dome Cameras, Bullet Cameras, PTZ Cameras, Box Cameras Installation Type: Indoor, Outdoor, Ceiling Mounted, Wall Mounted Connectivity: Wired, Wireless, Hybrid, Ethernet Usage Scenario: Public Safety, Retail Surveillance, Home Security, Industrial Monitoring |
| Companies Covered | CP Plus, Prama India Private Limited, Hikvision India Pvt. Ltd., Zhejiang Dahua Technology Co., Ltd., Honeywell International Inc., Bosch Security Systems, Axis Communications, Godrej Security Solutions, Matrix Comsec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Surveillance Analog Camera Market Trends and Innovations
Product evolution in the India Surveillance Analog Camera Market centers on extending analog relevance through signal processing advances and hybrid compatibility layers that bridge coaxial infrastructure toward network-era functionality.
960H and WD1 resolution formats are displacing standard D1 specifications in new installations across manufacturing and warehousing sectors. Facility security managers in Gujarat industrial corridors adopt these higher-density analog signals to maximize existing coaxial cable investments. The shift is displacing entry-level DVR configurations as buyers demand recording units capable of handling expanded horizontal pixel counts without full infrastructure replacement.
BIS Compulsory Registration Scheme enforcement tightens quality benchmarks for electronic security products entering Indian commerce. The regulation forces importers to submit samples for electromagnetic compatibility and safety testing before market release. Domestic manufacturers with existing laboratory relationships accelerate certification cycles, capturing shelf space ahead of delayed import arrivals.
Banking and retail security managers now unbundle installation from equipment procurement, contracting specialized technicians separately from hardware vendors. This purchasing pattern disrupts traditional distributor-led turnkey models in South Indian tier-two cities. The fragmentation concentrates service revenue with regional installation specialists while compressing hardware margins for camera suppliers competing on price-performance positioning.
India Surveillance Analog Camera Market Segmentation
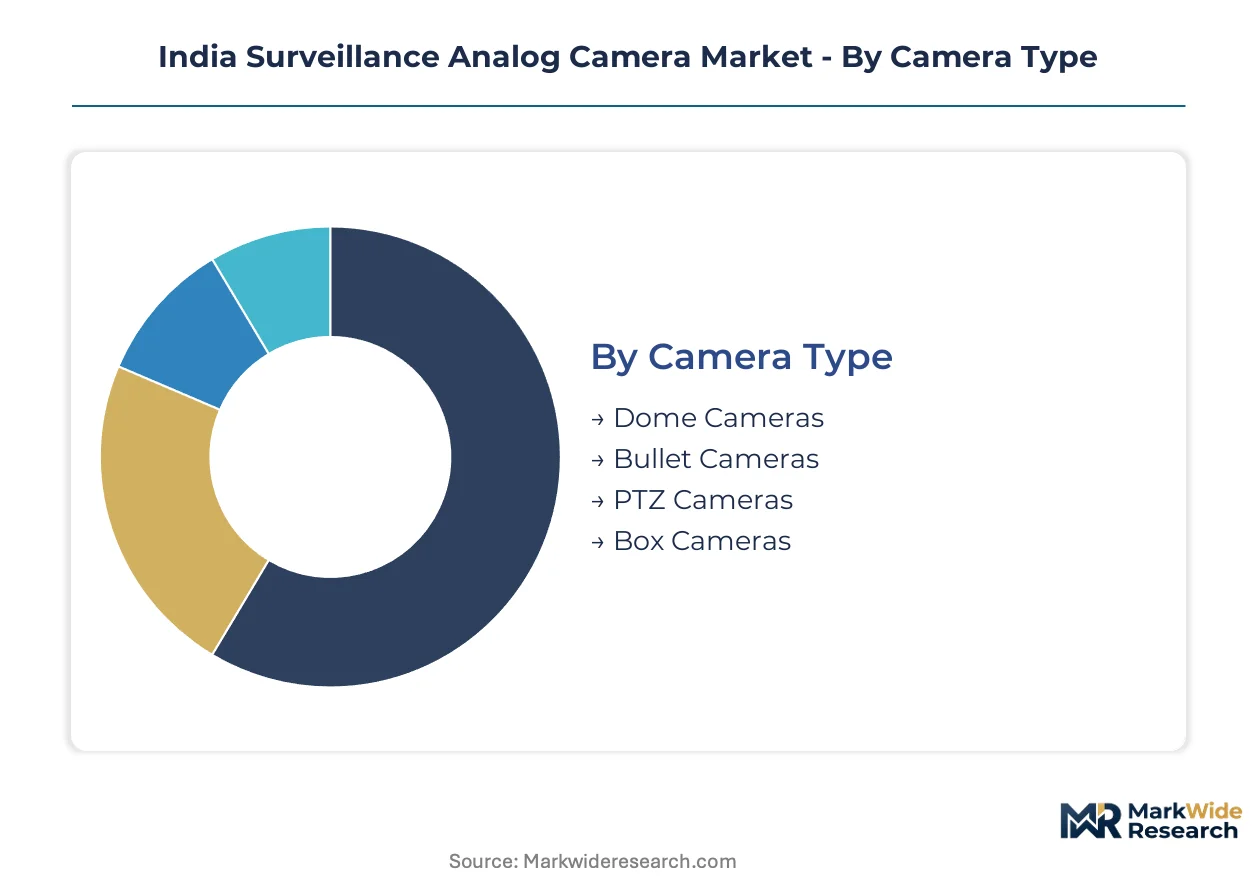
Segmentation reveals how procurement patterns diverge across India's surveillance landscape. BIS certification requirements and coaxial infrastructure legacy create distinct buyer clusters with incompatible upgrade paths.
Camera Type:
Margin pools concentrate in motorized configurations where mechanical complexity commands premium pricing over fixed-position alternatives.
- Bullet Cameras:Weather-resistant housings enclose fixed-lens optics with infrared arrays for perimeter monitoring. Manufacturing facilities across Gujarat industrial corridors deploy these for boundary surveillance where dust and monsoon exposure demand IP66-rated enclosures. Demand concentrates in warehousing and factory perimeter applications where installation simplicity outweighs coverage flexibility needs.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms enable remote directional control through coaxial telemetry signals. Traffic management authorities in Maharashtra municipal projects specify these for intersection monitoring where single-unit coverage reduces infrastructure density. Higher component costs and mechanical wear susceptibility create service revenue attachment opportunities distinct from fixed-camera deployments.
- Dome Cameras:Vandal-resistant hemispherical housings suit discrete indoor positioning in banking lobbies and retail floors.
- Box Cameras:Modular lens-interchangeable bodies serve specialized applications requiring varifocal adjustments or low-light optimization.
The dominant share belongs to Bullet Cameras, while PTZ Cameras is closing the gap fastest.
Installation Type:
Volume distribution tracks building stock age, with newer commercial construction favoring ceiling integration while legacy retrofits default to wall mounting.
- Outdoor:IP-rated housings withstand environmental exposure across temperature extremes and precipitation. Municipal smart city deployments in Gujarat and Maharashtra specify these for street-level public safety networks where enclosure durability determines replacement cycles. Procurement specifications increasingly mandate BIS-certified weatherproofing validation.
- Ceiling Mounted:Recessed or surface-mount brackets position optics downward for lobby and corridor coverage. Banking infrastructure expansion across South Indian tier-two cities drives demand where discrete positioning reduces tampering risk. Installation labor scarcity in Uttar Pradesh and Bihar complicates deployment timelines for overhead mounting configurations.
- Indoor:Unsealed housings serve climate-controlled environments with lower ingress protection requirements.
- Wall Mounted:Bracket-based positioning dominates retrofit installations where ceiling access proves structurally difficult.
Outdoor captures the largest volume position, though Ceiling Mounted is expanding most quickly in new commercial construction.
Connectivity:
Technology transition tension shapes procurement decisions as buyers weigh coaxial replacement against hybrid migration paths.
- Wired:Coaxial cable transmission remains the installed base standard for analog signal integrity over distance. Existing infrastructure in aging commercial buildings across northern India locks buyers into continuity-dependent upgrade paths. Copper price volatility directly impacts project economics for large-scale deployments.
- Hybrid:Bridge architectures accept analog camera inputs while supporting IP encoder integration for phased migration. Budget-constrained facility managers in South Indian banking and retail sectors favor this path to preserve coaxial investments while enabling future network expansion.
- Wireless:Radio-frequency transmission serves temporary or cable-inaccessible deployments with power-over-coax alternatives.
- Ethernet:Native IP connectivity sits outside pure analog definitions but appears in transitional procurement specifications.
Wired retains the dominant share, while Hybrid is gaining share fastest as facilities defer full infrastructure replacement.
Usage Scenario:
Application-specific performance requirements create divergent specification tiers across end-use verticals.
- Public Safety:Municipal and state government networks prioritize wide-area coverage with centralized monitoring integration. Ministry of Home Affairs Safe City program guidelines shape procurement specifications for police modernization in state capitals and district headquarters. Funding flows through state-level police modernization programs with BIS compliance mandatory for tender eligibility.
- Retail Surveillance:Discrete positioning and loss prevention analytics compatibility drive specification priorities. Tier-two city expansion across South India concentrates demand where analog systems still dominate cost-sensitive branch security upgrades. Unbundled installation contracting disrupts traditional turnkey procurement patterns.
- Industrial Monitoring:Process surveillance and perimeter security in manufacturing environments.
- Home Security:Residential deployments with simplified installation and basic recording requirements.
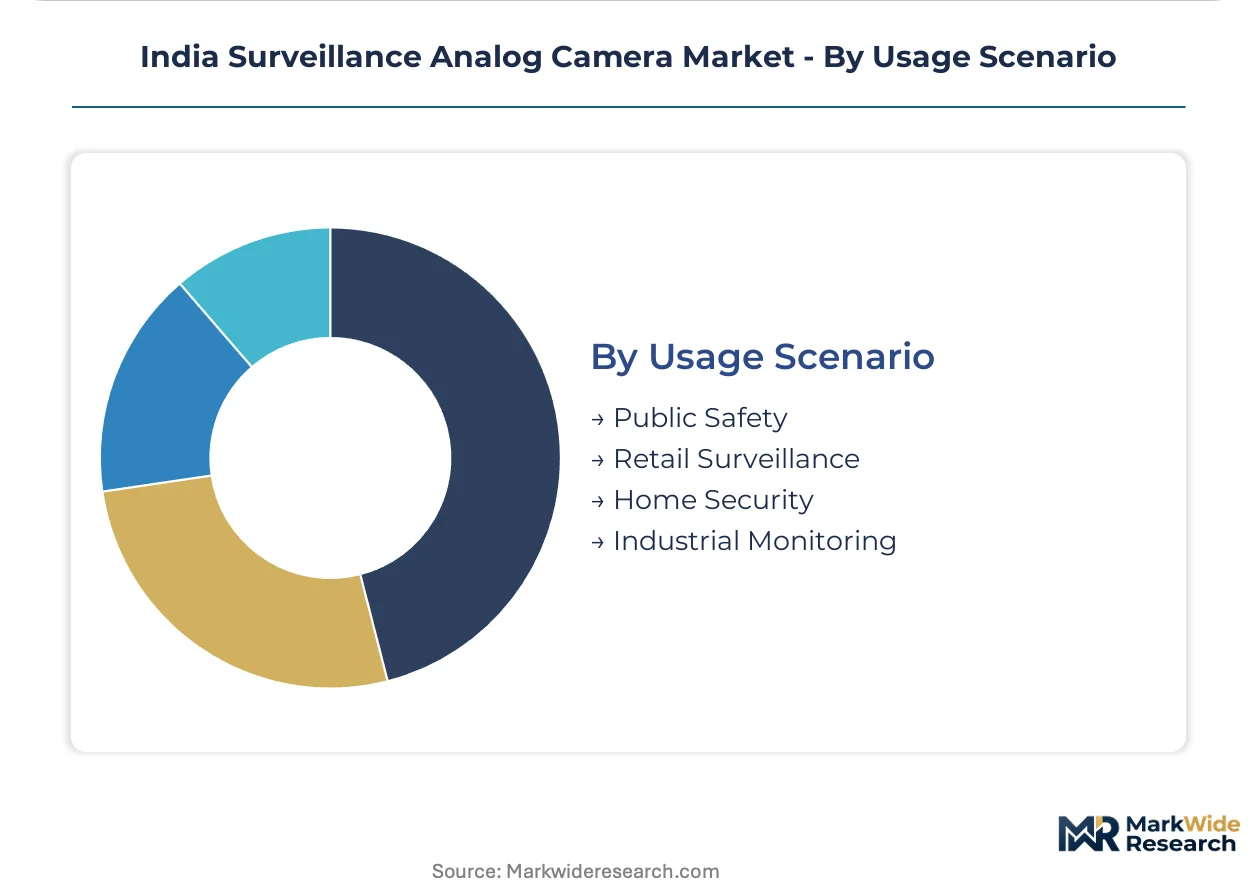
Public Safety commands the dominant share, while Retail Surveillance is climbing the fastest on banking infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat dominate municipal procurement through smart city infrastructure, while South Indian banking corridors drive commercial demand and northern states grapple with technician shortages that reshape service deployment models.
Maharashtra
Municipal corporations in Mumbai, Pune and Nagpur expand traffic monitoring networks under state police modernization programs. BIS certification requirements filter tender eligibility for public safety camera deployments. Manufacturing clusters in Nashik and Aurangabad industrial zones adopt bullet camera configurations for perimeter surveillance where dust exposure demands IP66-rated housings.
Gujarat
Smart city projects in Ahmedabad, Surat and Vadodara prioritize centralized command center integration for street-level surveillance networks. Ministry of Home Affairs Safe City guidelines shape procurement specifications with mandatory domestic manufacturing compliance. Chemical and pharmaceutical manufacturing corridors in Ankleshwar and Vapi deploy weather-resistant outdoor configurations for boundary monitoring.
Karnataka
Banking infrastructure expansion across Bangalore, Mysore and Mangalore drives dome camera installations in branch lobbies and ATM vestibules. Unbundled installation contracting disrupts traditional turnkey procurement as regional technicians capture service revenue. The state electronics manufacturing policy attracts component localization investments that reduce import dependency for security hardware.
Tamil Nadu
Retail surveillance upgrades in Chennai, Coimbatore and Madurai concentrate demand for discrete ceiling-mounted configurations. Coimbatore textile and engineering clusters adopt hybrid DVR migration paths to preserve coaxial infrastructure while enabling future IP integration. State-level industrial corridor development funds partial security system modernization in aging commercial facilities.
Uttar Pradesh
Installation technician scarcity across Lucknow, Kanpur and Varanasi redistributes service network deployment strategies toward training partnerships with industrial training institutes. Banking branch expansion in tier-two cities proceeds with wall-mounted retrofit configurations where ceiling access proves structurally difficult. BIS laboratory capacity constraints delay product registration cycles for new market entrants targeting northern hinterlands.
India Surveillance Analog Camera Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic distributors competing against multinational technology providers on certification speed and service reach. The vendor landscape organizes around three archetypes: extensive rural distribution networks, localized technical support centers, and price-performance positioning for mid-tier commercial installations. Capacity expansion through PLI scheme incentives and technician training partnerships represent the dominant competitive moves as vendors address labor scarcity in northern states.
Among domestic specialists, CP Plus anchors the extensive distribution archetype with rural market coverage capabilities, while Prama India Private Limited occupies the price-performance tier for mid-tier commercial installations. Hikvision India Pvt. Ltd. represents the multinational localization model through technical support center investments. These three patterns illustrate how certification compliance and service network geography determine competitive positioning in procurement decisions.
| Leading Market Players |
|---|
| CP Plus |
| Prama India Private Limited |
| Hikvision India Pvt. Ltd. |
| Zhejiang Dahua Technology Co., Ltd. |
| Honeywell International Inc. |
| Bosch Security Systems |
| Axis Communications |
| Godrej Security Solutions |
| Matrix Comsec |
| Others |
Pricing and Supply Chain Analysis
Long-term municipal offtake contracts for Maharashtra and Gujarat smart city deployments lock in supply access for certified domestic manufacturers while anchoring price visibility against copper cable volatility. BIS Compulsory Registration Scheme compliance costs flow through to procurement premiums, compressing margins for unregistered imports and elevating certified suppliers into preferred vendor status.
Pricing Analysis
Project-based pricing dominates municipal tenders and banking infrastructure contracts, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and after-sales service bundling. Price differentiation rests on BIS compliance status and localized technical support reach, with premium tiers capturing PTZ motorized configurations for traffic management. Cost compression in economy tiers intensifies as IP camera substitution pressures legacy analog bids in government procurement. Tier-two banking branches in South India exhibit highest price sensitivity, while Maharashtra municipal projects prioritize certification reliability over unit cost.
Supply Chain Analysis
BIS laboratory capacity in Delhi and Mumbai functions as a chokepoint that throttles import registration timelines and steers procurement toward pre-certified domestic inventory. Component sourcing draws from China, Taiwan, and South Korea for image sensors and infrared arrays, with copper cable supply tethered to global commodity exchanges. Single-source vulnerability concentrates in specialized coaxial connector manufacturing. Distribution runs through CP Plus rural footprint, Hikvision technical support centers, and regional installation specialists across Uttar Pradesh and Bihar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India surveillance analog camera market sits in early-cycle expansion as hybrid DVR migration extends equipment lifecycles and Safe City program funding accelerates municipal procurement velocity.
For Market Incumbents: Fortify certification pipeline investments to compress BIS registration cycles and defend shelf space against delayed import arrivals. Deepen technician training partnerships with industrial training institutes in Uttar Pradesh and Bihar to capture service revenue from unbundled installation contracting. Prioritize backward integration into copper cable assembly to hedge commodity volatility and project margin erosion. For New Entrants and Emerging Players: BIS fast-track through domestic manufacturing partnerships offers the most penetrable path around laboratory capacity bottlenecks that stall unregistered competitors. Target ceiling-mounted dome configurations in Karnataka banking expansion where discrete positioning demand outpaces established vendor coverage. Lead with hybrid DVR bundling to anchor coaxial infrastructure reuse while enabling future IP migration. For Investors and Strategic Acquirers: Capital is best deployed toward regional installation specialists with industrial training institute relationships that capture unbundled service revenue across northern hinterlands. Long-term viability hinges on hybrid technology transition timing as IP substitution pressures analog relevance. Monitor Safe City program funding disbursement velocity as the critical inflection signal for municipal procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Fast-Track Investment | Accelerates product registration timelines ahead of laboratory-constrained competitors. |
| Hybrid DVR Platform Development | Preserves coaxial infrastructure investments while enabling phased IP migration for banks. |
| Technician Training Institute Partnership | Addresses installation labor scarcity in Uttar Pradesh and Bihar corridor expansion. |
| Copper Cable Backward Integration | Hedges commodity price volatility exposure in large-scale municipal deployments. |
| Safe City Program Tender Positioning | Captures Ministry of Home Affairs funding flows for state capital surveillance networks. |
Research Methodology
Initial hypotheses were tested against primary input from municipal procurement officers, banking security managers, CCTV installation technicians, and electronics distributors and refined through secondary validation. Fieldwork encompassed Maharashtra and Gujarat smart city project documentation, BIS registration databases, and PLI scheme disclosure filings. Customs trade data, state police modernization budget allocations, and industrial corridor development reports supplied quantitative anchors. Bottom-up channel checks across tier-two South Indian cities triangulated against top-down Ministry of Home Affairs funding flow analysis.
Variance decomposition across camera type, installation configuration, connectivity architecture, and end-use vertical shaped the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles, hybrid migration adoption curves, and municipal tender award velocity. Copper price elasticity coefficients and BIS laboratory queue duration estimates fed industry-specific forecast sensitivity testing.
Underlying assumptions cover BIS enforcement continuity, PLI scheme extension, and Safe City funding disbursement schedules, with deviation risk concentrated in IP camera policy preference shifts and copper commodity spikes. Practitioners should keep alternative scenarios live as Ministry of Home Affairs tender specifications and state-level police modernization priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Europe Surveillance IP Camera Market
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
Cellular Interception Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Storage Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
India Surveillance Storage Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market