
 Surveillance Camera Systems Market | 2026-2036
Surveillance Camera Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Surveillance Camera Systems Market Analysis
Video-analytics-as-a-service is pivoting how surveillance vendors monetize hardware deployments, shifting revenue from one-time equipment sales toward recurring software subscriptions. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its vertically integrated manufacturing to dominate price-sensitive municipal tenders across Asia. Axis Communications AB differentiates through open-platform architecture that integrates third-party analytics without vendor lock-in.
Surveillance camera systems encompass image-capture devices with sensors ranging from 2MP to 8K resolution, paired with video management software for real-time monitoring and forensic review. Their primary purpose spans crime prevention, traffic management, and critical infrastructure protection across public and private domains. Dome cameras and bullet cameras anchor most commercial installations, while IP technology displaces analog infrastructure as enterprises prioritize remote accessibility and edge-based analytics. The transportation end-user segment generates outsized demand for PTZ cameras capable of tracking moving targets across wide perimeters.
The EU AI Act restricts biometric identification in public spaces, compelling vendors to re-engineer product roadmaps for European compliance. China's GB standards and NMPA cybersecurity rules mandate local data residency, shaping how foreign suppliers architect cloud-connected systems. India's BIS certification requirements for electronic safety equipment create a formal barrier to uncertified imports. Stakeholders must weigh regulatory fragmentation against the cost of maintaining region-specific firmware and cloud instances.
Market Dynamics
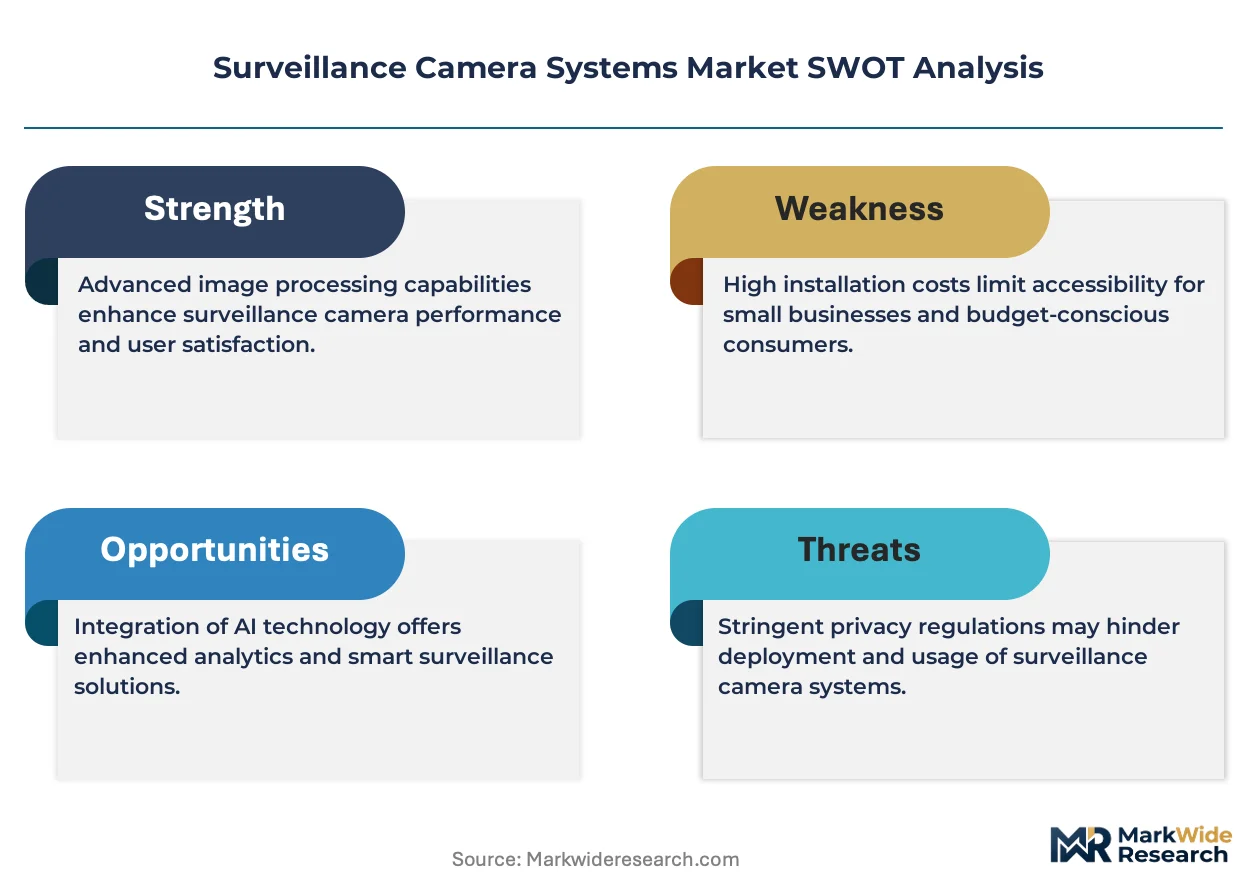
The surveillance camera systems sector is reconfiguring around edge-based artificial intelligence, where on-device inference reduces bandwidth costs and latency while triggering new compliance obligations under biometric governance frameworks.
Growth Catalysts
- Smart city infrastructure mandates:India's Ministry of Housing and Urban Affairs accelerates Safe City deployments across metropolitan clusters, generating concentrated demand for integrated video management platforms with command-center interoperability.
- EU AI Act compliance engineering:European procurement specifications now embed privacy-by-design requirements, compelling vendors to develop anonymization-first architectures that qualify for public-sector tenders.
- Edge computing silicon maturation:Dedicated neural processing units in camera chipsets enable real-time object classification without cloud dependency, reducing operational expenditure for bandwidth-constrained deployments.
Market Restraints
- Image sensor supply concentration:Advanced CMOS fabrication capacity clusters in Taiwan and South Korea, exposing camera manufacturers to geopolitical disruption risk and allocation constraints during demand surges.
- GDPR-derived liability exposure:Data protection authorities in Germany and France impose substantial fines for unauthorized biometric processing, elevating insurance costs and legal review overhead for system operators.
- Cloud storage substitution pressure:Hybrid architectures combining local network video recorders with selective cloud tiering displace fully managed SaaS models in cost-sensitive municipal accounts.
Strategic Opportunities
- Perimeter defense in critical infrastructure:Thermal-visible fusion cameras address detection requirements at airports, ports, and power substations where conventional visible-spectrum equipment fails in adverse conditions.
- India's BIS certification pathway:Domestic manufacturing incentives under the PLI scheme for electronics create favorable conditions for establishing certified production facilities serving South Asian demand.
- 5G private network convergence:Ultra-reliable low-latency connectivity enables wireless PTZ deployments in mining and construction sites previously unreachable through cabled infrastructure.
Industry Challenges
- Embedded systems security engineering:Firmware vulnerability management demands specialized talent scarce in traditional security integrator channels, slowing patch cycles and certification timelines.
- Interoperability certification complexity:ONVIF Profile compliance testing for multi-vendor environments extends pre-deployment validation periods and strains project delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surveillance Camera Systems Market |
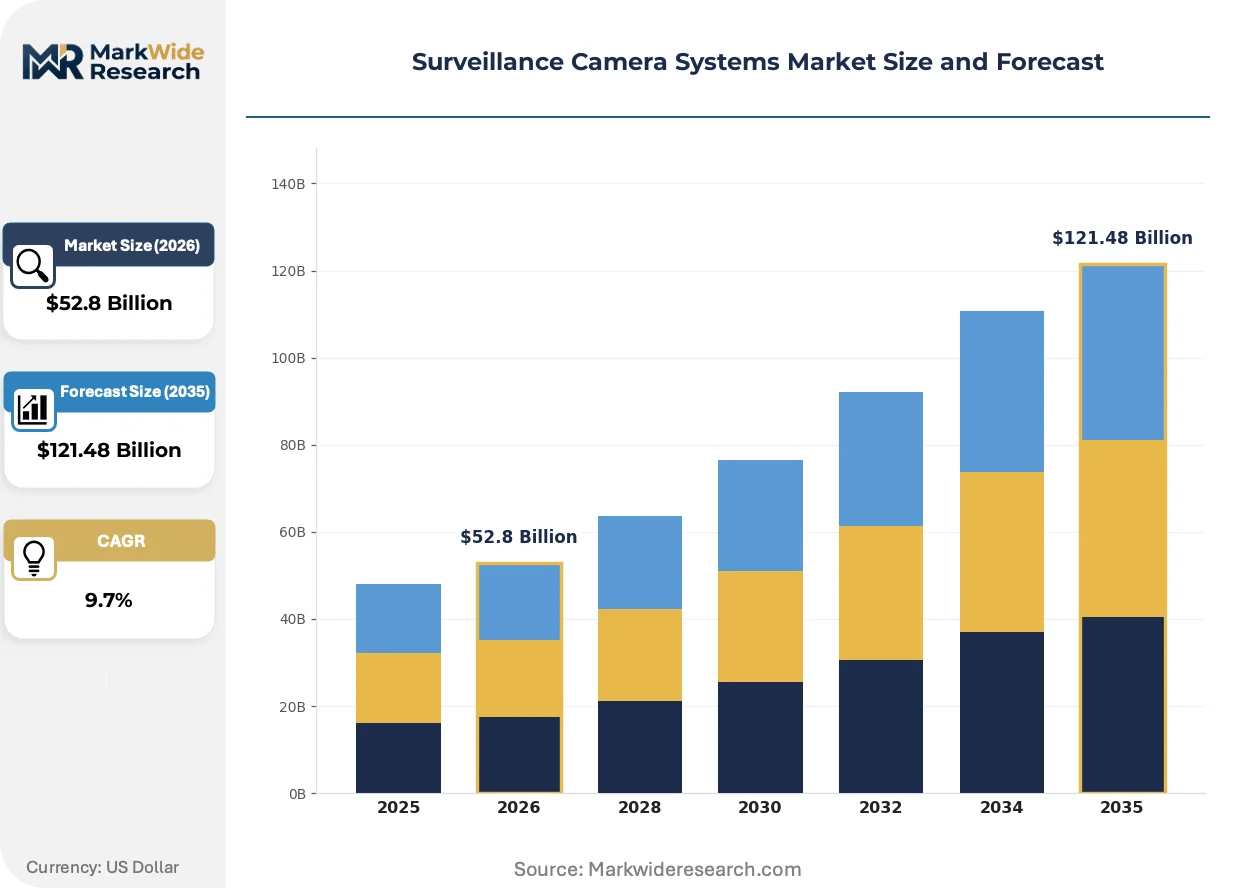
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $121.48 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, Box Cameras Technology: Analog, IP, HD-TVI, Wireless End User: Retail, Transportation, Banking, Government Installation Type: Indoor, Outdoor, Covert, Hybrid |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Zhejiang Dahua Technology Co., Ltd., Axis Communications AB, Bosch Security Systems GmbH, Honeywell International Inc., Hanwha Vision Co., Ltd., Teledyne FLIR LLC, Motorola Solutions, Inc., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surveillance Camera Systems Market Emerging Trajectories
Computational imaging and connectivity protocols are dissolving traditional hardware-software boundaries, enabling surveillance infrastructure to function as programmable sensor networks rather than passive recording devices.
Multi-spectral imaging fusion is electrifying perimeter security applications by combining visible, thermal, and near-infrared channels into unified threat-detection streams. Airport authorities in Singapore and oil terminal operators in the UAE deploy these systems for continuous coverage through fog, smoke, and darkness. The technology is compressing sensor count requirements while elevating detection confidence thresholds beyond what single-modality equipment achieves.
China's GB/T 28181 national standard for video networking interoperability is mandating protocol uniformity across provincial public security deployments. Foreign suppliers must engineer dedicated firmware branches to satisfy these specifications, fragmenting product development resources. European and North American vendors with limited China presence are ceding municipal tender participation to domestically certified competitors rather than absorbing compliance overhead.
Subscription-based video analytics unbundling is restructuring how enterprise buyers acquire intelligence capabilities. Large retail chains in the United States and logistics operators in Germany now procure people-counting and dwell-time analysis as metered services rather than perpetual licenses. This consumption-pattern shift concentrates vendor relationships with cloud-native platform providers capable of elastic scaling across distributed camera estates.
Surveillance Camera Systems Market Segmentation
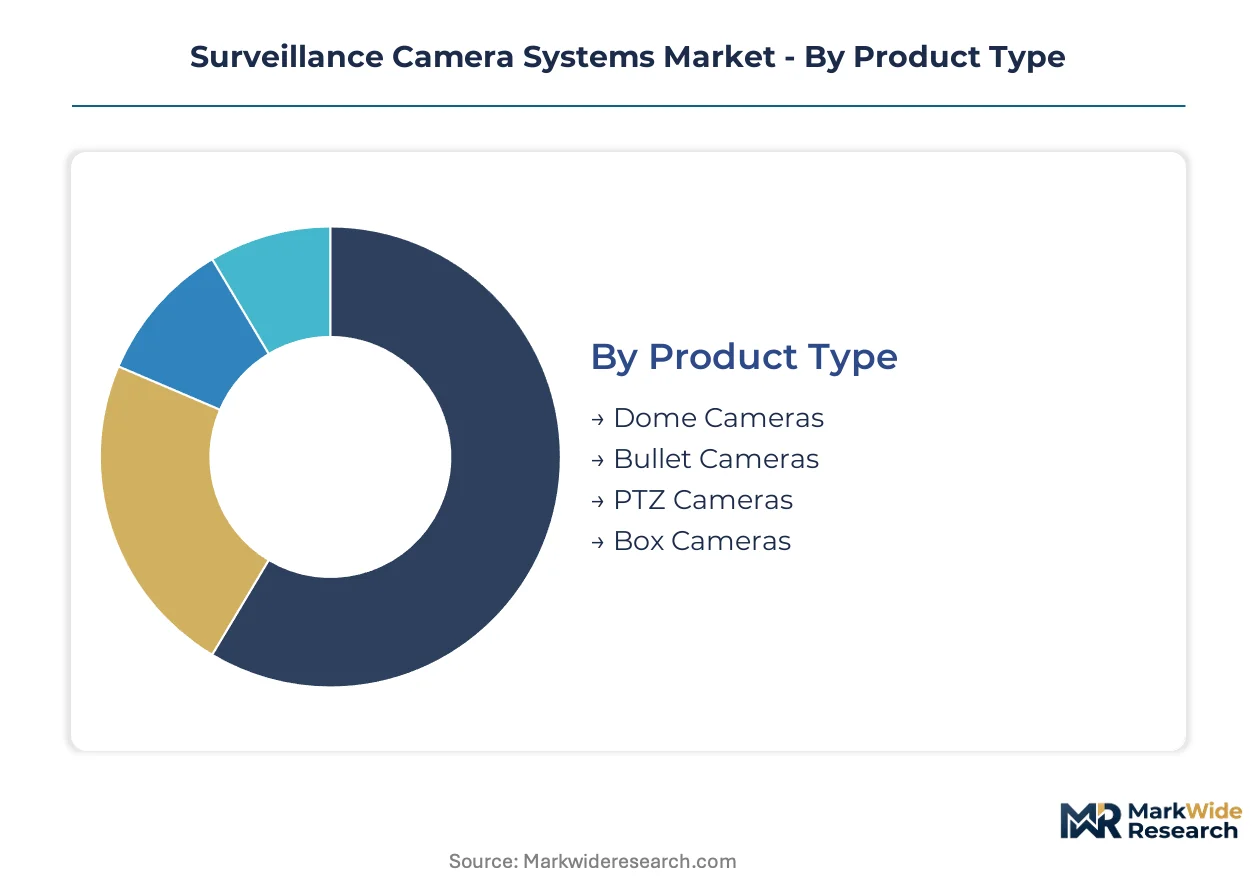
Surveillance camera systems fragment across four critical dimensions that shape procurement workflows, integration complexity, and lifecycle economics. Buyers prioritize different specifications depending on whether the deployment serves forensic investigation, real-time response, or deterrence objectives.
Product Type:
Physical form factor determines mounting flexibility, environmental resilience, and optical range that buyers must match to site constraints.
- Dome Cameras:Hemispherical housings with vandal-resistant polycarbonate enclosures protect internal PTZ mechanisms in high-traffic public corridors. Retail chains in Germany and hospitality operators across the UAE specify these for discrete ceiling-mounted coverage where tampering resistance outweighs range requirements.
- PTZ Cameras:Pan-tilt-zoom actuators with 30x optical zoom and preset tour programming track moving targets across expansive perimeters. Transportation authorities in India deploy these at rail yards and port terminals where continuous operator attention is impractical and automated tracking reduces staffing overhead.
- Bullet Cameras:Weather-sealed cylindrical housings with integrated IR illuminators deliver fixed-angle coverage for exterior building perimeters.
- Box Cameras:Modular lens-interchangeable bodies allow custom focal length selection for specialized forensic applications.
Dome cameras lead on scale across commercial indoor deployments; PTZ cameras lead on momentum in critical infrastructure and transportation verticals.
Technology:
Signal transmission architecture governs cabling infrastructure, cybersecurity exposure, and analytics deployment flexibility.
- IP:Network-addressable devices streaming H.265-compressed video over Ethernet enable edge analytics and centralized VMS integration. Enterprises in the United States and facility operators in Singapore prioritize these for remote accessibility and API-driven automation that analog infrastructure cannot support.
- Wireless:Wi-Fi 6 and private 5G connectivity eliminate trenching and conduit costs in heritage buildings and temporary construction sites. Mining operations in Australia and event venues in Brazil adopt these where cabled infrastructure is physically impractical or cost-prohibitive.
- Analog:Coaxial-based CVBS transmission persists in cost-constrained retrofit scenarios where existing cabling must be preserved.
- HD-TVI:High-definition transport video interface bridges analog infrastructure with megapixel resolution over legacy coax.
IP dominates new-build specifications; wireless is gaining share fastest in mobile and temporary deployment scenarios.
End User:
Regulatory exposure and incident response protocols drive divergent feature priorities across vertical markets.
- Government:Municipal public safety deployments demand command-center interoperability, evidence-grade chain-of-custody logging, and compliance with national encryption standards. India's Safe City program and EU AI Act procurement specifications concentrate demand for privacy-by-design architectures with automated redaction capabilities.
- Transportation:Airports, seaports, and rail networks require wide-dynamic-range imaging and thermal fusion for 24-hour perimeter integrity. Operators in Singapore and the UAE specify these for fog-penetrating detection where conventional visible-spectrum equipment fails.
- Retail:Loss prevention and occupancy analytics prioritize compact form factors with embedded people-counting algorithms.
- Banking:Facial recognition and transaction-timestamp synchronization dominate branch and ATM deployment specifications.
Government accounts anchor procurement volume through multi-year framework agreements; transportation verticals show steepest expansion trajectory driven by infrastructure modernization programs.
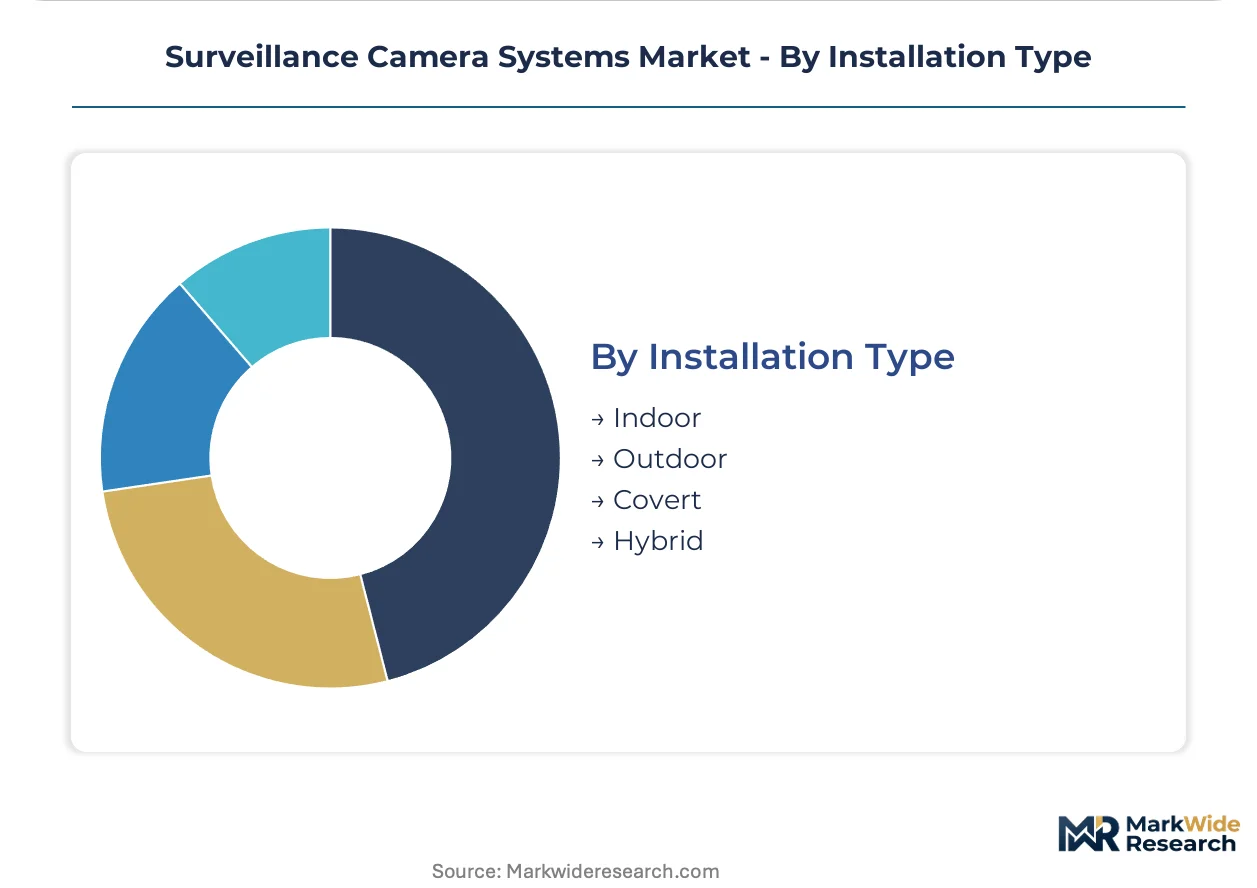
Installation Type:
Environmental exposure and concealment requirements determine housing specifications and deployment methodology.
- Outdoor:IP67-rated enclosures with integrated heaters and wipers sustain operation across temperature extremes from -40°C to 60°C. Critical infrastructure operators in Canada and Saudi Arabia specify these for substation and pipeline monitoring where equipment failure carries safety consequences.
- Indoor:Compact form factors with PoE power delivery minimize aesthetic intrusion in corporate offices, healthcare facilities, and educational institutions.
- Covert:Disguised housings embedded in environmental fixtures serve investigative and dignitary protection applications.
- Hybrid:Dual indoor-outdoor certified units reduce SKU complexity for integrators serving mixed-environment deployments.
Outdoor installations command premium pricing through environmental hardening; indoor volumes dominate unit shipments across commercial building stock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where surveillance hardware is manufactured and certified. Compliance costs for the EU AI Act and India's BIS standards diverge sharply, pushing vendors to regionalize firmware development and cloud infrastructure rather than maintaining unified global platforms.
China
Provincial public security procurement concentrates demand in the Yangtze River Delta and Pearl River Delta manufacturing clusters. GB/T 28181 national standards for video networking interoperability mandate protocol uniformity that foreign suppliers struggle to satisfy. Hangzhou and Shenzhen anchor domestic production capacity serving municipal Safe City deployments across eastern provinces.
India
Metropolitan Safe City programs in Delhi, Mumbai, and Bangalore generate concentrated demand for command-center-integrated video management platforms. BIS certification requirements for electronic safety equipment create formal barriers to uncertified imports. The PLI scheme for electronics manufacturing is drawing assembly investment toward Gujarat and Tamil Nadu industrial corridors.
Germany
Data protection authorities in Berlin and Munich impose substantial fines for unauthorized biometric processing, elevating insurance costs for system operators. GDPR-derived liability exposure compels vendors to engineer anonymization-first architectures. The Rhine-Ruhr industrial belt anchors demand from critical infrastructure operators requiring thermal-visible fusion for perimeter defense.
United States
Large retail chains and logistics operators in Texas and California are procuring video analytics as metered cloud services rather than perpetual licenses. FCC spectrum regulations shape private 5G network deployments for wireless PTZ cameras in mining and construction sites. The Southwest and Pacific Northwest concentrate edge computing silicon development enabling on-device inference.
Singapore
Changi Airport and port terminal operators specify multi-spectral imaging systems for fog-penetrating detection where conventional visible-spectrum equipment fails. The city-state's Smart Nation infrastructure mandates command-center interoperability standards that filter vendor participation. Government technology procurement frameworks prioritize privacy-by-design certifications from EU AI Act-aligned suppliers.
Surveillance Camera Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base organizes into three tiers: vertically integrated hardware conglomerates dominating municipal tenders, open-platform specialists capturing enterprise accounts seeking interoperability, and regional assemblers serving price-sensitive retrofit markets. Consolidation pressure concentrates in the middle tier as cloud-native analytics providers unbundle software from hardware. Strategic moves center on compliance engineering for fragmented regulatory environments and backward integration into edge computing silicon.
Within the integrated hardware tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Zhejiang Dahua Technology Co., Ltd. represent archetypes of vertically structured players with captive manufacturing ecosystems. Axis Communications AB occupies a position exemplifying open-platform architecture strategies that minimize vendor lock-in. Among diversified technology conglomerates, Bosch Security Systems GmbH and Honeywell International Inc. anchor multi-product security portfolios where surveillance cameras represent one node in broader building automation offerings.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Zhejiang Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Bosch Security Systems GmbH |
| Honeywell International Inc. |
| Hanwha Vision Co., Ltd. |
| Teledyne FLIR LLC |
| Motorola Solutions, Inc. |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Captive manufacturing ecosystems in China's Yangtze River Delta and Pearl River Delta anchor both component supply security and pricing power for vertically integrated vendors serving municipal tenders. Hangzhou Hikvision Digital Technology Co., Ltd. and Zhejiang Dahua Technology Co., Ltd. leverage in-house sensor packaging and firmware development to compress bill-of-materials costs while maintaining margin buffers against price-sensitive procurement in India and Southeast Asia.
Pricing Analysis
Distributor margins spanning 15-25 percent for security integrators shape final procurement costs for mid-market enterprise buyers. Three-tier pricing structure across premium, standard, and economy levels separates Axis Communications AB's open-platform subscriptions from Hikvision's hardware-centric tenders and regional assemblers' unbranded retrofit equipment. Price differentiation hinges on certification grade—BIS, GB/T 28181, and EU AI Act compliance tiers—and bundled video-analytics-as-a-service subscriptions. Cost compression in the economy tier is intensifying because India's PLI scheme for electronics manufacturing draws domestic assembly investment toward Gujarat and Tamil Nadu corridors. Municipal accounts in India's Safe City program exhibit highest price sensitivity; airport operators in Singapore and the UAE show lowest sensitivity due to thermal-visible fusion requirements and 24-hour perimeter integrity mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from China's provincial public security bureaus, while security integrators and value-added distributors serve fragmented commercial accounts across Europe and North America. CMOS image sensor fabrication concentrates in Taiwan and South Korea, with advanced node capacity feeding neural processing unit integration for edge-based AI inference. Optical lens assemblies draw from Japanese precision manufacturers; power management ICs source from South Korean and Chinese foundries. Single-source vulnerability in Taiwan's semiconductor fabrication exposes camera manufacturers to geopolitical disruption risk and allocation constraints during demand surges. Distribution runs through authorized distributors for enterprise accounts and direct municipal tender participation for government framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software subscription attach rates and premium-tier thermal fusion deployments, driven by edge computing silicon maturation reducing downstream bandwidth costs. Cost-down trajectories in neural processing unit integration enable vendors to maintain pricing while embedding advanced analytics.
For Market Incumbents: Deploy firmware branch engineering as the primary lever to defend municipal tender participation against emerging cloud-native analytics providers. Axis Communications AB should deepen open-platform certification investments for EU AI Act compliance to capture privacy-by-design procurement specifications in Germany and France. Hangzhou Hikvision Digital Technology Co., Ltd. must accelerate GB/T 28181 protocol uniformity across provincial deployments to maintain domestic market dominance against regulatory fragmentation threats. For New Entrants and Emerging Players: The 40-60 percent price-point gap between Hikvision's economy tenders and Axis's premium subscriptions creates entry space for mid-tier vendors offering BIS-certified hardware with metered analytics in India's Safe City corridor. Target wireless PTZ deployments in mining and construction sites across Australia and Brazil where private 5G network convergence eliminates incumbent cabling advantages. Pursue channel partnerships with regional security integrators lacking in-house analytics development capability rather than direct OEM competition. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native video analytics platforms because enterprise procurement is shifting from perpetual licenses toward metered services that concentrate vendor relationships. Acquire targets with established ONVIF Profile compliance and API-driven automation capabilities serving retail and logistics verticals in the United States and Germany. Watch edge computing silicon development announcements from Southwest and Pacific Northwest semiconductor clusters as the signal indicating which hardware vendors can unbundle analytics without cloud dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Integration | Neural processing unit embedding in camera chipsets enables real-time object classification without cloud dependency for bandwidth-constrained deployments. |
| Regulatory Compliance Engineering | EU AI Act anonymization-first architectures qualify vendors for German and French public-sector tenders while elevating insurance costs for non-compliant operators. |
| Video-Analytics-as-a-Service Unbundling | Metered subscription models restructure enterprise procurement toward elastic scaling across distributed camera estates in U.S. retail and German logistics. |
| Multi-Spectral Imaging Fusion | Thermal-visible-near-infrared channel combination addresses fog-penetrating detection requirements at Singapore Changi Airport and UAE oil terminals. |
| Private 5G Network Convergence | Ultra-reliable low-latency connectivity enables wireless PTZ deployments in Australian mining and Brazilian event venues previously unreachable through cabled infrastructure. |
Methodological Framework
Direct dialogue with video management software architects, municipal procurement officers in India's Safe City program, security integrators serving European critical infrastructure, and edge computing silicon product managers grounded qualitative assessment. Secondary validation drew from SEC filings of listed surveillance vendors, EU AI Act implementation guidance documents, India's BIS certification registries for electronic safety equipment, and China's GB/T 28181 protocol specifications. Bottom-up camera shipment estimates by form factor and technology tier triangulated against top-down video analytics subscription revenue disclosures.
Segment-level value outputs across the projection horizon reflect modeled interactions between product type, technology architecture, end-user vertical, and installation environment. The analytical framework incorporated dome, PTZ, bullet, and box camera form factors; IP, wireless, analog, and HD-TVI transmission technologies; government, transportation, retail, and banking end-user segments; plus outdoor, indoor, covert, and hybrid installation types. CAGRs derived from regression analysis of historical procurement patterns against smart city infrastructure spend, regulatory compliance cost trajectories, and edge computing adoption curves. Forecast inputs included neural processing unit penetration rates and 5G private network deployment timelines for wireless surveillance applications.
Caveats apply where geopolitical disruption in Taiwan semiconductor fabrication, accelerated EU AI Act enforcement actions by German and French data protection authorities, or India's PLI scheme manufacturing incentive revisions could materially shift the outlook. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Wireless Security Camera Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
United Kingdom Video Surveillance Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Wireless Home Security Camera Market