
 France Video Surveillance Market | 2026-2036
France Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
France Video Surveillance Market Insights
The capability gap between cloud-native software developers and legacy hardware manufacturers is rotating competitive capital allocation across the France video surveillance landscape. Axis Communications AB leverages its open-platform camera architecture to sustain developer ecosystem loyalty in large municipal deployments. Bosch Security Systems anchors its position through in-house sensor manufacturing and stringent German-origin quality protocols that French government buyers favor. Schneider Electric SE competes by integrating video feeds into broader building-management dashboards, extending its electrical infrastructure relationships into security procurement cycles.
Video surveillance encompasses the networked capture, transmission, storage, and analysis of visual data through fixed or pan-tilt-zoom cameras operating at resolutions from 1080p to 4K, typically compressed via H.265 codecs for bandwidth efficiency. The primary purpose spans crime prevention, operational safety monitoring, and post-incident forensic investigation across commercial and public infrastructure. IP technology leads installed value as French enterprises retire coaxial analog systems, though hybrid configurations persist where legacy cable plant cannot be economically replaced. Cameras generate the dominant hardware margin pool, while accessories such as edge-computing gateways and specialized lenses capture expanding attach rates as analytics processing migrates toward the network periphery.
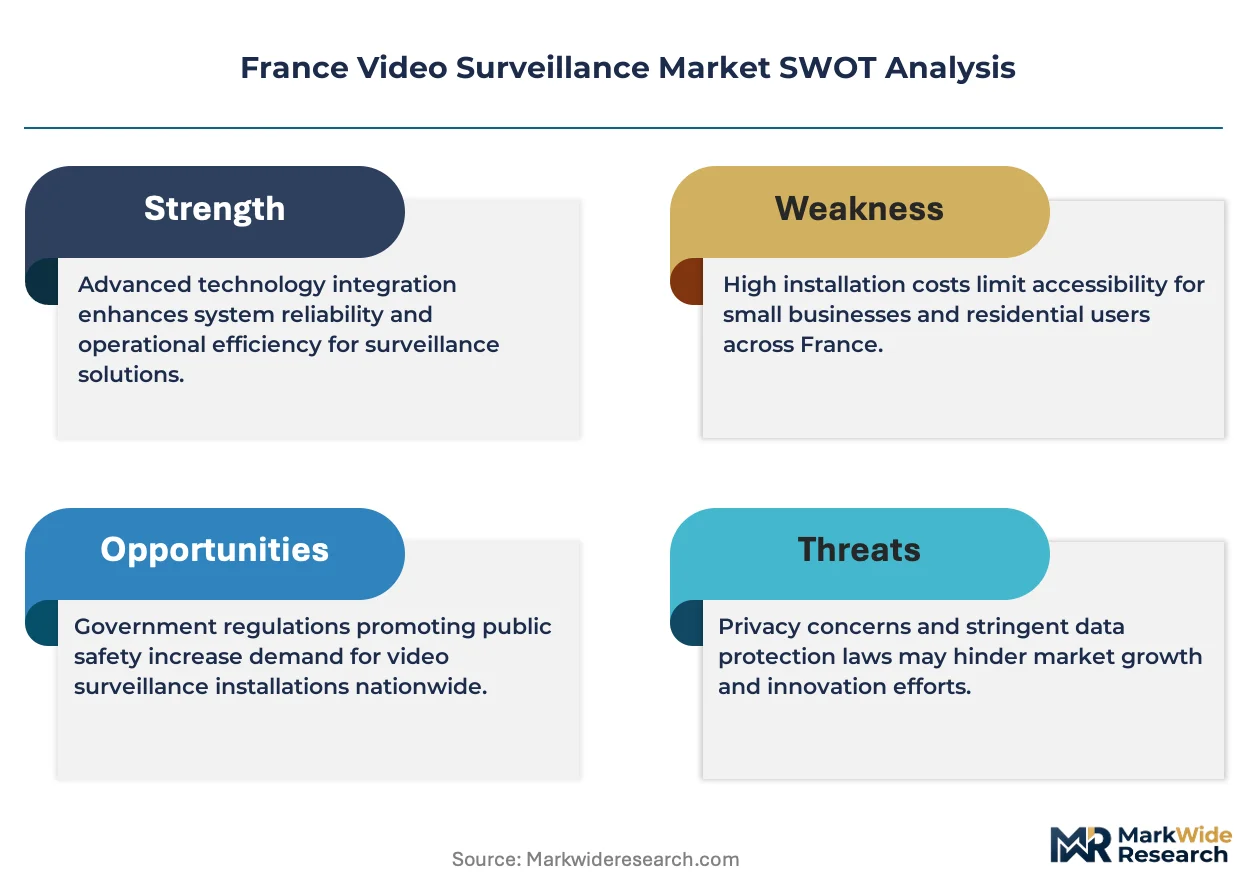
CNIL data-protection rulings constrain facial recognition deployment scope in French public spaces, compelling vendors to engineer privacy-by-design features such as automatic blurring and retention limits. The EU AI Act's risk-classification framework subjects certain biometric video analytics to conformity assessment obligations before market placement. ANSSI cybersecurity certification requirements for critical infrastructure operators are reshaping procurement specifications toward encrypted video streams and supply-chain provenance documentation. Stakeholders must monitor whether forthcoming French implementing decrees will tighten operator liability for algorithmic bias in automated surveillance alerts.
Market Dynamics
Cloud-native AI analytics are decomposing the traditional stack of on-premise storage and dedicated NVR hardware, forcing French integrators to rebuild margin models around software subscriptions rather than box shipments.
Growth Catalysts
- LOPPSI 2 Security Framework:French law enforcement agencies accelerate video analytics procurement mandates, creating guaranteed demand pipelines for facial recognition and behavioral detection systems in transport nodes.
- Edge Computing Migration:Processing-intensive analytics relocate to camera-adjacent gateways, reducing bandwidth costs for municipal operators managing thousands of feeds across distributed infrastructure.
- Critical Infrastructure Protection:ANSSI cybersecurity certification requirements compel encrypted video streams and supply-chain provenance documentation, expanding attach rates for hardened hardware configurations.
Market Restraints
- CNIL Privacy Enforcement:Data-protection rulings constrain facial recognition deployment scope in public spaces, forcing engineering investment in automatic blurring and retention-limit features without revenue offset.
- Legacy Cable Plant:Hybrid analog-digital configurations persist where coaxial infrastructure replacement costs exceed municipal security budgets, fragmenting procurement into incompatible technology islands.
- Sensor Supply Concentration:Image sensor fabrication concentrates in East Asian foundries, exposing French system integrators to lead-time volatility and customs documentation complexity.
Strategic Opportunities
- Building Management Convergence:Video feeds integrate into electrical infrastructure dashboards, allowing Schneider Electric and similar firms to bundle security procurement with existing BMS relationships.
- Île-de-France Transport Density:Parisian operators at Gare du Nord and Châtelet-Les Halles deploy pilot facial recognition systems, creating reference architectures for secondary French cities.
- EU AI Act Conformity:Risk-classification frameworks for biometric analytics create first-mover advantages for vendors completing conformity assessments before implementing decrees tighten.
Industry Challenges
- Algorithmic Bias Liability:French implementing decrees may impose operator accountability for discriminatory automated alerts, requiring forensic audit capabilities most integrators lack.
- Multi-Vendor Integration Complexity:Open-platform camera architectures from Axis Communications demand specialized engineering talent to reconcile API variations across municipal deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Video Surveillance Market |
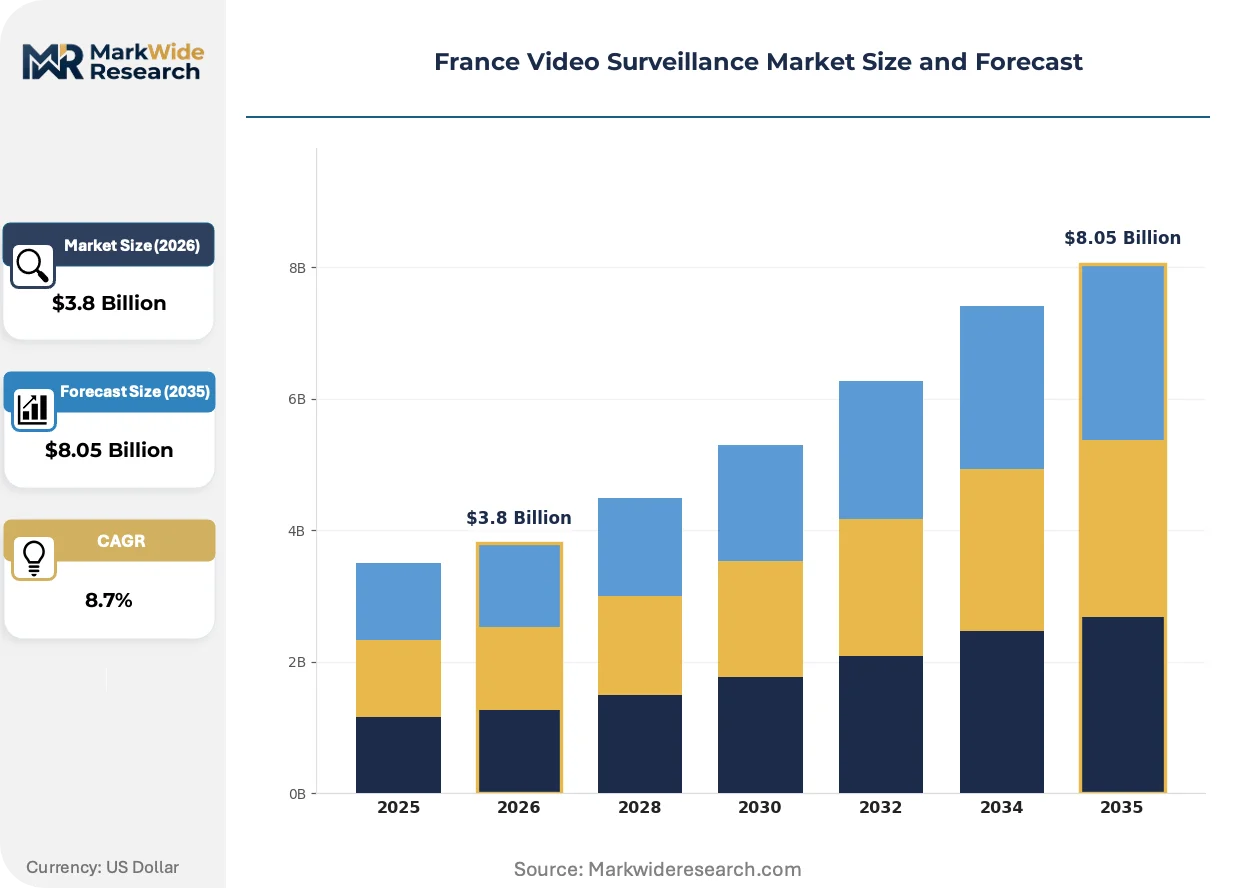
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Recorders, Monitors, Accessories Technology: IP, Analog, Wireless, Hybrid End User: Retail, Transportation, Residential, Government Installation Type: Indoor, Outdoor, Centralized, Decentralized |
| Companies Covered | Panasonic Corporation, Johnson Controls, Axis Communications AB, ANAVEO, Genetec, Bosch Security Systems, Schneider Electric SE, Veesion, Honeywell Security Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Video Surveillance Market Trends and Innovations
Three distinct vectors reshape competitive positioning: software-defined architectures erode hardware loyalty, regulatory compliance becomes a product feature, and procurement cycles compress as cloud subscriptions replace capital expenditure.
Edge-based AI inference is decomposing the centralized analytics model that dominated French municipal surveillance for two decades. Transport operators in Paris now deploy GPU-equipped gateways within 50 meters of camera clusters, processing facial recognition and abandoned-object detection locally. This shift compresses bandwidth requirements by 60-70 percent while enabling real-time alerting that cloud-dependent architectures cannot match.
The EU AI Act's risk-classification framework subjects biometric video analytics to conformity assessment obligations before market placement. French vendors must document training data provenance and algorithmic performance across demographic subgroups, adding 9-15 months to product launch timelines. Critical infrastructure operators now specify CE-marked AI components exclusively, filtering procurement pools to pre-certified suppliers.
Subscription pricing for video analytics software displaces perpetual licensing in municipal RFPs. French transport authorities at RATP and SNCF pilot monthly-per-camera models that bundle software updates, cloud storage, and cybersecurity patches. This shift transfers balance-sheet risk from capital-constrained operators to vendors, who must now price recurring revenue streams against traditional hardware margins.
France Video Surveillance Market Segmentation
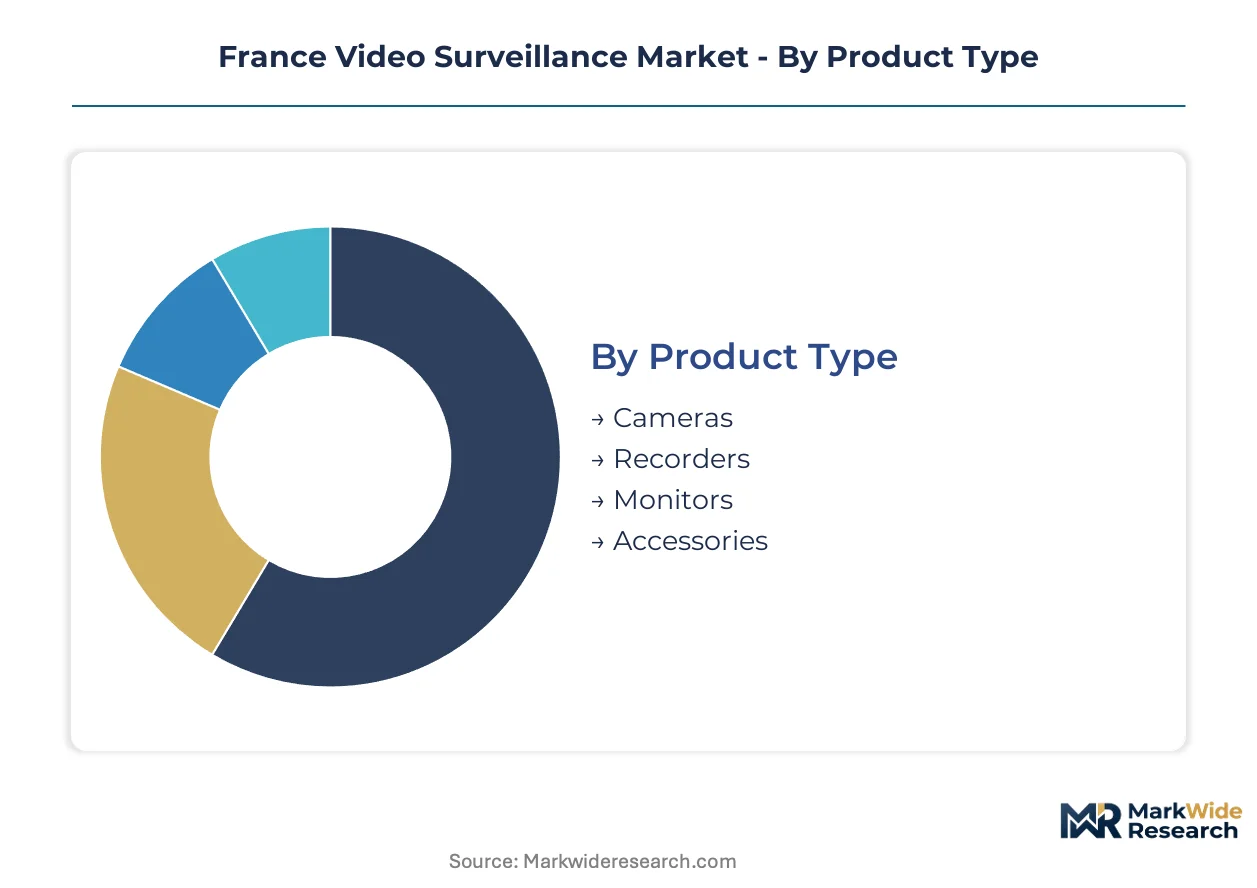
Segmentation in the France video surveillance market reveals how regulatory pressure and infrastructure legacy reshape procurement patterns. Buyers segment choices around CNIL compliance obligations, ANSSI certification tiers, and the physical constraints of existing cable plant across French municipalities.
Product Type:
CNIL data-protection rulings and ANSSI cybersecurity mandates differentiate hardware procurement by compliance burden and encryption capability.
- Cameras:Fixed and pan-tilt-zoom units operating at 1080p to 4K resolution, compressed via H.265 codecs for bandwidth efficiency. Demand concentrates in Île-de-France transport nodes where Parisian operators at Gare du Nord deploy facial recognition-capable units under LOPPSI 2 frameworks.
- Recorders:Network video recorders and digital video recorders managing storage architectures from on-premise servers to cloud-native platforms. Municipal buyers in secondary French cities favor hybrid configurations where legacy coaxial infrastructure persists.
- Monitors:Display units for real-time feed observation and forensic review in control room environments.
- Accessories:Edge-computing gateways, specialized lenses, and mounting hardware capturing expanding attach rates as analytics processing migrates toward network peripheries.
Established volume favors cameras; emerging adoption favors accessories.
Technology:
Migration cost and infrastructure replacement timelines stratify technology choices across French enterprise and municipal budgets.
- IP:Internet Protocol-based digital transmission dominating installed value as French enterprises retire coaxial analog systems. RATP and SNCF specify IP architectures for new Parisian transport deployments.
- Analog:Coaxial-based legacy systems persisting where cable plant replacement exceeds municipal security budgets. Hybrid analog-digital configurations fragment procurement in peripheral French regions.
- Wireless:Radio-frequency and cellular transmission for temporary deployments or heritage structures where cable installation is prohibited.
- Hybrid:Mixed IP-analog architectures bridging legacy infrastructure with modern analytics requirements.
IP technology claims the steepest expansion trajectory; hybrid configurations retain defensive positions in budget-constrained installations.
End User:
Application-specific risk profiles and regulatory exposure differentiate end-user procurement specifications and compliance investment.
- Transportation:Rail, metro, and airport operators deploying behavioral detection and facial recognition under LOPPSI 2 mandates. Châtelet-Les Halles serves as reference architecture for biometric video analytics pilots.
- Government:Law enforcement and municipal security agencies procuring under ANSSI cybersecurity certification requirements for encrypted video streams and supply-chain provenance documentation.
- Retail:Loss prevention and customer analytics applications constrained by CNIL rulings on public space biometric deployment.
- Residential:Private property monitoring with lower regulatory burden but growing subscription preference for cloud storage and software updates.
Government and transportation command premium pricing tiers; residential subscriptions expand most quickly in volume terms.
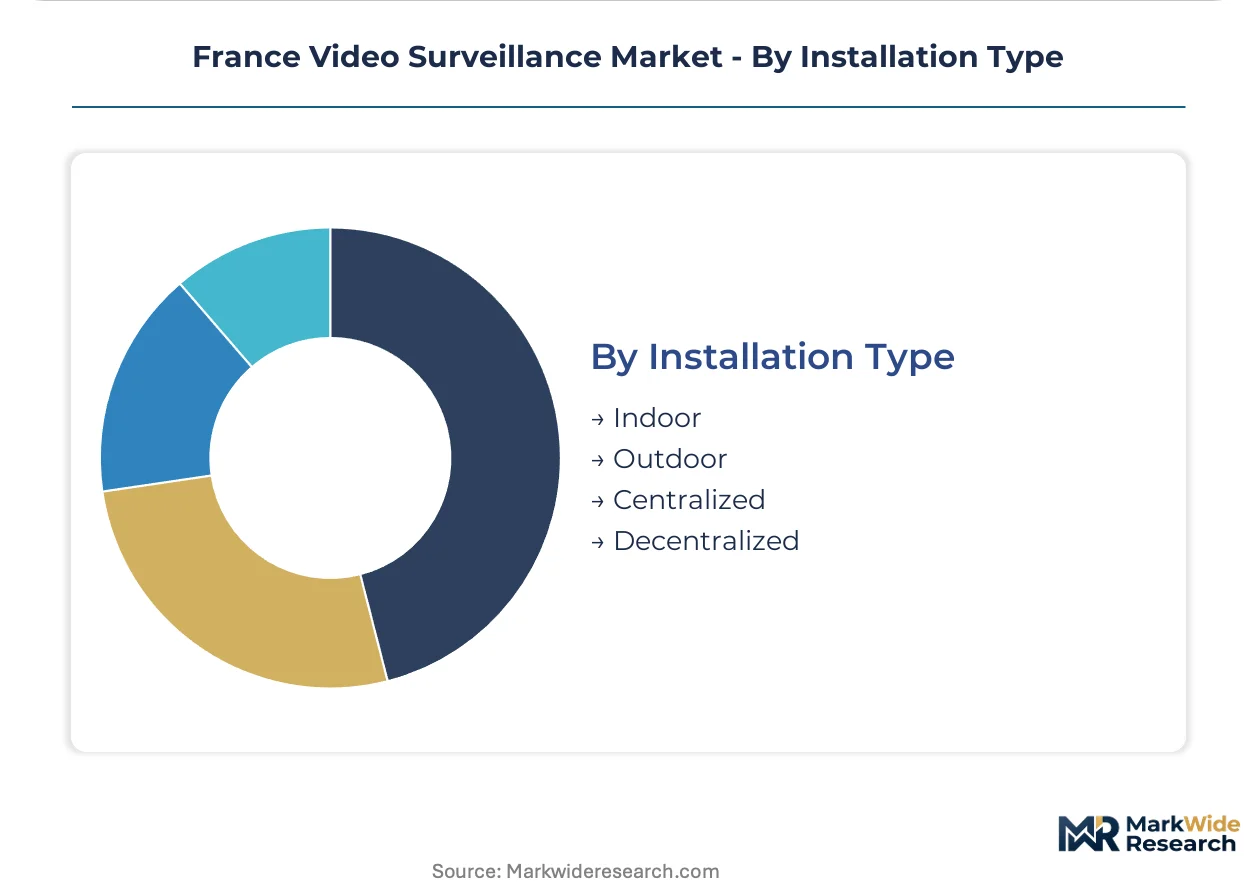
Installation Type:
Environmental exposure and network architecture choices determine hardware durability specifications and centralized versus distributed analytics processing.
- Outdoor:Weather-resistant housings and thermal management for perimeter security and public space coverage. French critical infrastructure operators specify hardened configurations meeting ANSSI certification.
- Indoor:Climate-controlled environments in retail, office, and transport concourse applications with lower IP-rating requirements.
- Centralized:Star-topology networks feeding dedicated control rooms with on-premise storage and analytics processing.
- Decentralized:Edge-based architectures with GPU-equipped gateways processing facial recognition within 50 meters of camera clusters, compressing bandwidth requirements by 60-70 percent.
Centralized architectures retain installed base dominance; decentralized edge deployments gain share fastest in new municipal tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Île-de-France transport nodes while secondary French regions operate under tighter municipal budget constraints that fragment procurement timelines.
Île-de-France
RATP and SNCF operators at Gare du Nord and Châtelet-Les Halles deploy facial recognition-capable camera clusters under LOPPSI 2 security mandates. CNIL data-protection rulings compel automatic blurring features in public space deployments. Parisian transport density creates reference architectures for biometric video analytics that secondary cities replicate.
Auvergne-Rhône-Alpes
Lyon-Saint-Exupéry Airport and Grenoble's cable-car infrastructure drive demand for edge-computing gateways with ANSSI cybersecurity certification. The region's semiconductor fabrication heritage supports local integration partnerships for GPU-equipped analytics hardware. Clermont-Ferrand's municipal police pilot hybrid analog-digital configurations where coaxial replacement exceeds security budgets.
Provence-Alpes-Côte d'Azur
Marseille port authority procurement emphasizes supply-chain provenance documentation for encrypted video streams under critical infrastructure protection rules. Nice Côte d'Azur Airport tests cloud-native AI analytics from French software developers against legacy on-premise storage. Cannes' hospitality sector adopts subscription-based video analytics for loss prevention constrained by CNIL biometric rulings.
Hauts-de-France
Lille-Europe rail hub operators specify hardened outdoor camera configurations meeting ANSSI certification tiers for perimeter security. The region's manufacturing legacy sustains demand for building-management system integration where Schneider Electric extends electrical infrastructure relationships. Dunkirk port operators face lead-time volatility from East Asian image sensor supply concentration.
Nouvelle-Aquitaine
Bordeaux tram network deployments favor decentralized edge architectures processing analytics within 50 meters of camera clusters. The region's wine estate security applications drive residential subscription growth for cloud storage and software updates. Toulouse-Blagnac Airport procurement specifications filter to pre-certified EU AI Act suppliers for biometric components.
France Video Surveillance Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized security technology developers rather than pure-play hardware fabricators. The vendor base spans three distinct tiers: multinational electrical infrastructure groups with building-management convergence capabilities, open-platform camera specialists sustaining developer ecosystems, and cloud-native AI analytics disruptors decomposing traditional storage architectures. Competitive moves center on strategic partnerships between software developers and municipal integrators, plus portfolio diversification into cybersecurity-certified hardware configurations.
Among diversified industrial groups, Schneider Electric SE exemplifies building-management convergence strategies that bundle security procurement with existing electrical infrastructure relationships. Axis Communications AB occupies a position within the open-platform camera tier, sustaining developer ecosystem loyalty through API accessibility in large municipal deployments. Veesion represents the cloud-native disruptor archetype, anchoring the shift from on-premise NVR hardware toward software subscription models in French retail and transport applications.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Johnson Controls |
| Axis Communications AB |
| ANAVEO |
| Genetec |
| Bosch Security Systems |
| Schneider Electric SE |
| Veesion |
| Honeywell Security Group |
| Others |
Pricing and Supply Chain Analysis
Long-term subscription contracts with RATP and SNCF operators lock in both supply access for cloud-native analytics vendors and predictable revenue visibility across the Île-de-France transport corridor. These multi-year service agreements bundle software updates, edge hardware refresh cycles, and cybersecurity patches into fixed monthly-per-camera rates that insulate municipal buyers from capital expenditure volatility.
Pricing Analysis
The customization-premium spread separates ANSSI-certified hardened configurations from standard commercial-grade hardware in French municipal procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, encryption capability, and supply-chain provenance documentation depth. Pricing pressure stems from cloud-native software subscriptions displacing traditional NVR hardware margins. Government and transportation segments show lowest price sensitivity due to regulatory compliance mandates; residential and small retail buyers exhibit highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate among French system integrators managing edge-computing gateway deployments, though strategic stockpiling persists for image sensors given lead-time volatility. Image sensor fabrication concentrates in Taiwan, South Korea, and China, exposing French integrators to customs documentation complexity. GPU-equipped analytics hardware draws from specialized semiconductor foundries in Taiwan and USA. Single-source vulnerability in East Asian sensor supply creates procurement risk. Distribution runs through authorized security integrators with ANSSI-certified installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France video surveillance sits in early-cycle expansion as LOPPSI 2 security mandates accelerate biometric analytics adoption across transport infrastructure ahead of full EU AI Act enforcement.
For Market Incumbents: Consolidate developer ecosystem loyalty around open-platform camera architectures while deepening backward integration into edge-computing hardware production. Cloud-native disruptors like Veesion threaten traditional NVR-centric margin pools; certification investment in ANSSI and EU AI Act conformity creates defendable positioning. For New Entrants and Emerging Players: EU AI Act conformity fast-track offers entry pathway into biometric video analytics procurement previously locked to established vendors. White-space concentrates in secondary French cities replicating Parisian reference architectures at Châtelet-Les Halles, plus Bordeaux-Nouvelle-Aquitaine decentralized edge deployments. Channel partnership with Schneider Electric's building-management integrators provides credible go-to-market acceleration. For Investors and Strategic Acquirers: Cloud-native AI analytics specialists with pre-certified biometric components represent the most compelling acquisition target archetype. Long-term viability hinges on recurring revenue predictability under subscription models and regulatory moat durability across the projection horizon. Signal to watch is French implementing decree timing on algorithmic bias liability thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| ANSSI Certification Fast-Track | Pre-cleared suppliers capture municipal RFP preference under critical infrastructure protection rules. |
| Edge Hardware Backward Integration | In-house GPU gateway production insulates margins from semiconductor supply volatility. |
| Building Management Convergence | Schneider Electric extends electrical infrastructure relationships into bundled security procurement cycles. |
| EU AI Act Conformity Investment | CE-marked biometric components filter procurement pools before implementing decrees tighten. |
| Secondary City Reference Replication | Lyon-Saint-Exupéry and Bordeaux tram networks adopt Parisian facial recognition architectures. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal security procurement officers, systems integrators, and transport authority technology directors; and secondary validation against ANSSI certification databases, CNIL enforcement rulings, and EU AI Act implementation timelines. Bottom-up triangulation across camera shipment volumes, software subscription registrations, and edge gateway deployments reconciled with top-down market sizing from customs records and municipal tender documentation.
The forecasting boundary spans the full analysis window from base year through terminal projection. Segmentation dimensions modeled include product type, technology migration stage, end-user regulatory exposure, and installation architecture choice. CAGRs derive from logistic diffusion curves fitted to IP technology replacement rates and cloud-native analytics penetration patterns. Industry-specific inputs incorporate LOPPSI 2 procurement mandate schedules and CNIL enforcement intensity indices.
Decision-makers should treat outputs as directional under assumptions of sustained LOPPSI 2 funding continuity and stable East Asian semiconductor supply; material deviation would warrant model refresh. Revision becomes warranted when EU AI Act implementing decree timing or algorithmic bias liability thresholds cross regulatory certainty thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Commercial Aircraft Video Surveillance Systems Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Farm Video Surveillance System Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market