
 China Surveillance Storage Market | 2026-2036
China Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
China Surveillance Storage Market Insights
Market Context
The domestic distribution channel for surveillance storage is fragmenting as provincial integrators bypass traditional tier-one distributors to source directly from manufacturers. Hangzhou Hikvision Digital Technology Co Ltd anchors the hardware-integrated storage segment through captive production of NVR and DVR systems. Dahua Technology Co Ltd competes on edge-computing storage bundles that reduce bandwidth costs for municipal buyers. Seagate Technology Holding PLC leverages its HDD specialization to supply high-capacity drives optimized for 24/7 video workloads.
Technical Definition and Segment Structure
China surveillance storage encompasses the specialized data retention infrastructure—comprising magnetic hard disk drives, solid-state arrays, network video recorders, and cloud-tier architectures—engineered to ingest, index, and preserve continuous video streams from multi-camera deployments, typically operating at 4K resolution with retention mandates of 30 to 90 days. The technology dimension shows cloud storage gaining share as MIIT pushes data-localization policies requiring domestic cloud nodes for government video archives. Edge computing storage differentiates fastest in traffic management applications where real-time analytics must process feeds before upstream transmission. HDD remains the volume workhorse in public safety deployments due to cost-per-terabyte economics, while SSD penetration climbs in retail security for rapid incident retrieval.
Regulatory Frame and Outlook
SAMR enforces cybersecurity review rules on surveillance equipment with data-processing capabilities, compelling vendors to certify storage subsystems for encryption and access logging. GB standards issued under NMPA-aligned quality frameworks specify environmental resilience thresholds for storage hardware deployed in outdoor infrastructure monitoring. China's dual carbon goals from MEE are pressuring data center operators to improve power usage effectiveness in video storage farms. Stakeholders must monitor how forthcoming data-sovereignty interpretations affect cross-border cloud replication architectures for multinational security operators.
Market Dynamics
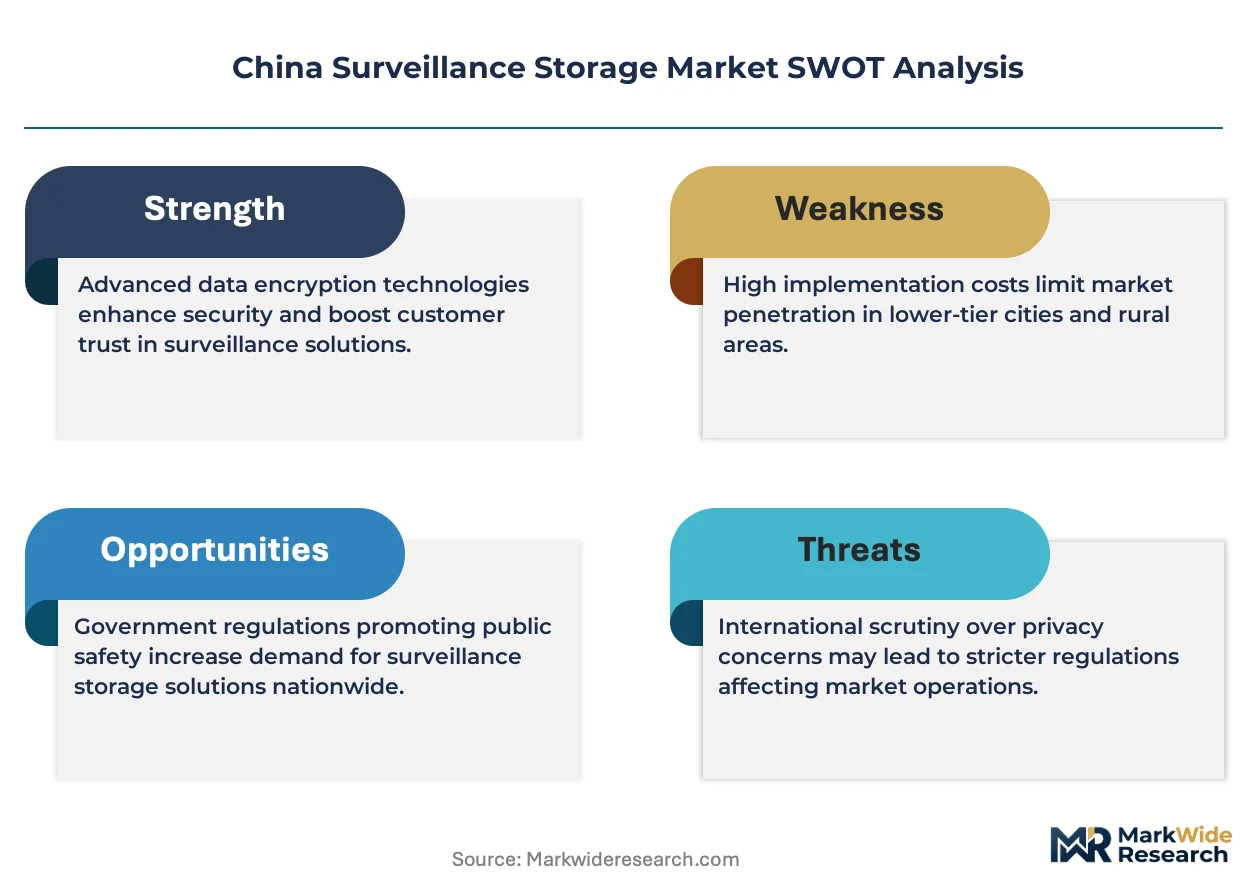
Provincial integrators in Guangdong and Jiangsu are bypassing tier-one distributors to source storage hardware directly from manufacturers, compressing channel margins and forcing vendors to rebuild go-to-market structures around municipal procurement offices rather than traditional distribution networks.
Growth Catalysts
- Smart city mandates:Guangdong province traffic management systems are expanding camera density per intersection, driving petabyte-scale storage tenders for real-time video analytics infrastructure.
- GB encryption standards:SAMR-mandated cybersecurity review rules for data-processing equipment are compelling municipal buyers to replace legacy storage with certified encrypted subsystems.
- Edge computing bundles:Municipal traffic authorities are procuring edge-storage servers that preprocess video feeds before cloud transmission, reducing bandwidth expenditure.
Market Restraints
- HDD supply concentration:High-capacity drive production concentrates among three global manufacturers, exposing Chinese system integrators to allocation risk during component shortages.
- Power density limits:MEE dual carbon goals enforce strict power usage effectiveness thresholds on video storage farms, constraining rack-scale expansion in existing data centers.
- Silicon cost volatility:NAND flash price swings compress margin predictability for SSD-integrated NVR vendors serving retail security segments.
Strategic Opportunities
- Western province penetration:Sichuan and Shaanxi smart city budgets remain underallocated for surveillance storage relative to coastal provinces, creating whitespace for vendors with localized service networks.
- AI-video convergence:Object-recognition algorithms require low-latency storage architectures, opening demand for NVMe-over-Fabric arrays in public safety command centers.
- MIIT data localization:Government cloud archive mandates are forcing multinational security operators to deploy domestic cloud nodes, requiring compliant storage infrastructure partnerships.
Industry Challenges
- Firmware certification timelines:SAMR encryption and access-logging requirements extend product validation cycles by six to nine months, delaying revenue recognition for new subsystem launches.
- Legacy NVR integration:Municipal buyers face technical debt when retrofitting ONVIF-compliant storage onto decade-old analog-to-digital transition infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Surveillance Storage Market |
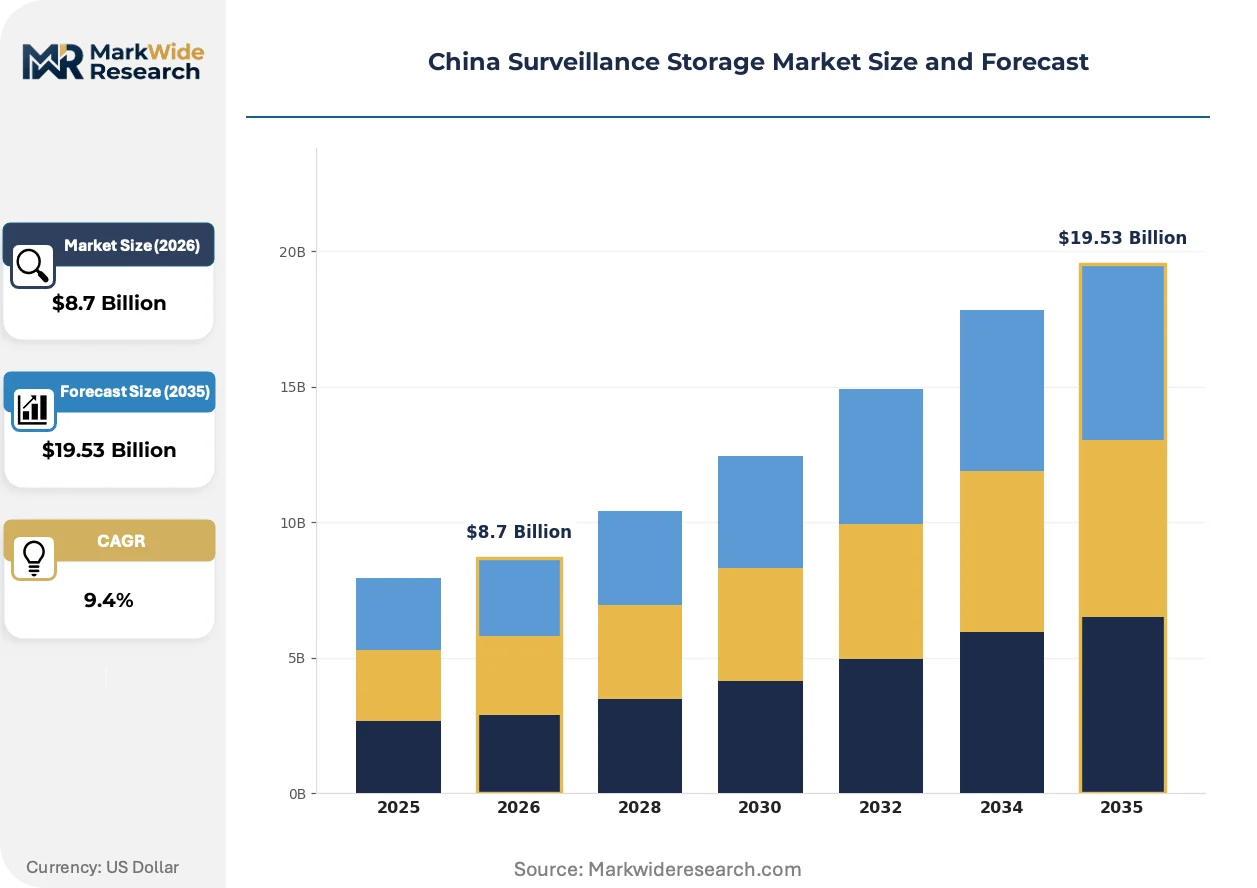
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DVR, NVR, HDD, SSD Technology: Cloud Storage, Edge Computing, RAID, Video Analytics Application: Public Safety, Retail Security, Infrastructure Monitoring, Traffic Management End User: Government, Retailers, Transportation Sector, Healthcare Facilities |
| Companies Covered | Hangzhou Hikvision Digital Technology Co Ltd, Dahua Technology Co Ltd, Zhejiang Uniview Technologies Co Ltd, Seagate Technology Holding PLC, Dell Technologies, Cisco Systems, Huawei Technologies, Inspur Group, Axis Communications AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Surveillance Storage Market Trends and Innovations
Storage architectures for continuous video workloads are fragmenting across three simultaneous vectors: media type diversification, regulatory compliance layering, and procurement channel restructuring. These shifts are compressing vendor margin structures while opening specialized niches.
Object storage software is migrating from public cloud abstraction layers into on-premise video surveillance deployments. Large-scale traffic management authorities in Shenzhen and Hangzhou are adopting S3-compatible interfaces for petabyte-scale retention pools. This migration from file-system hierarchies to flat-address object stores is enabling seamless tiering between hot SSD caches and cold HDD archives without application rewrites.
GB standards issued under NMPA-aligned quality frameworks now specify environmental resilience thresholds for outdoor infrastructure monitoring hardware. Storage subsystems must certify operating temperature ranges, vibration tolerance, and ingress protection for roadside cabinet deployments. Traffic management integrators in coastal provinces are selecting vendors based on pre-certified subsystem documentation rather than conducting custom validation.
Municipal procurement offices are consolidating storage tenders into multi-year framework agreements with single-source accountability clauses. Traditional tier-one distributors lose position as provincial integrators establish direct manufacturer relationships. This consolidation is most visible in Jiangsu manufacturing clusters where surveillance equipment production and cloud infrastructure procurement overlap within the same buyer organizations.
China Surveillance Storage Market Segmentation
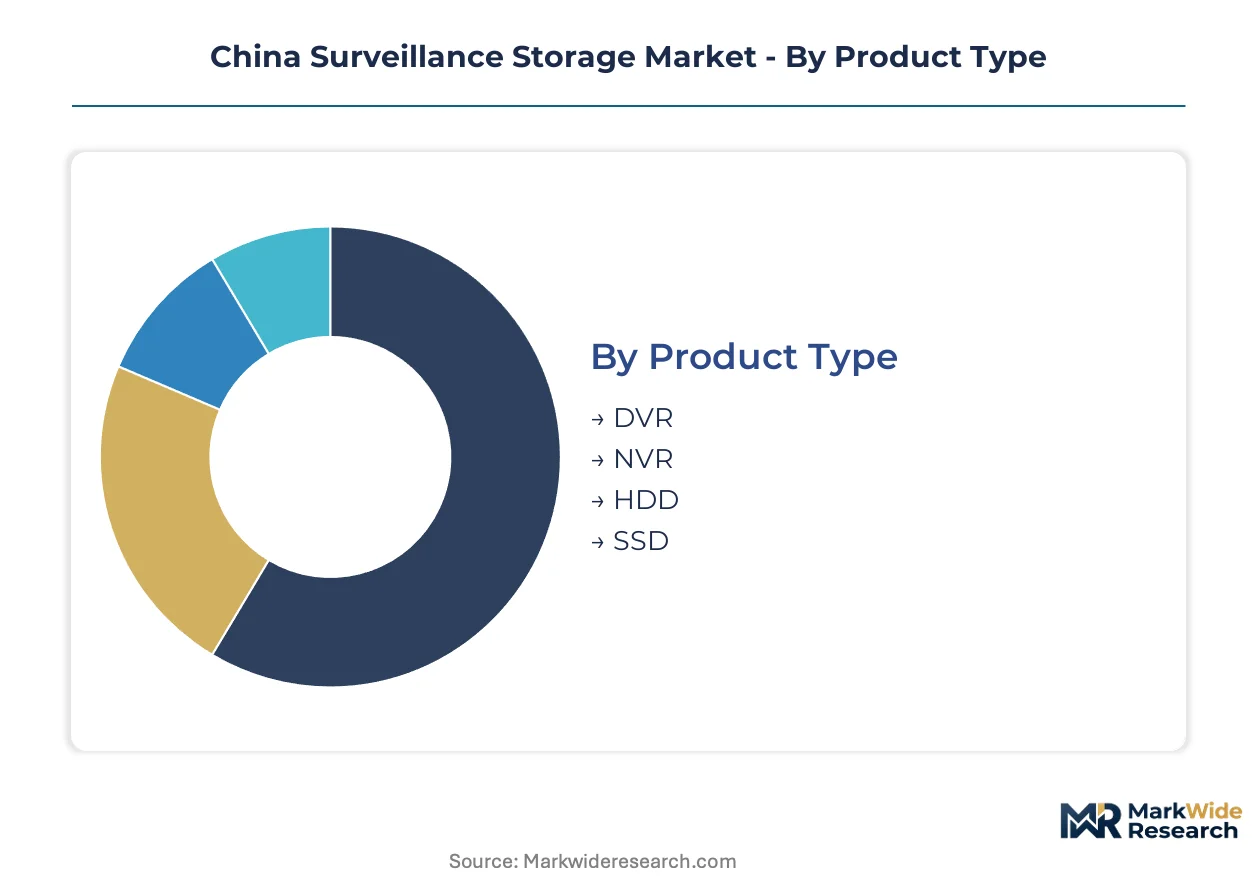
Segmentation in surveillance storage reveals how procurement patterns diverge across hardware form factors, deployment architectures, and compliance requirements. Understanding these splits exposes where margin pools concentrate and which technology transitions are commercially mature versus emergent.
Product Type:
After-sales-service intensity varies sharply across hardware categories, with field-replaceable components demanding localized technician networks while sealed units shift liability to manufacturers.
- DVR:Analog-to-digital recording systems with embedded compression chipsets serve legacy municipal infrastructure. Demand concentrates in tier-three cities completing analog transition programs under constrained budgets. Replacement cycles extend to seven years, compressing recurring revenue opportunities for integrators.
- NVR:Network-attached appliances with IP camera integration dominate new procurement in Guangdong smart city deployments. IP-based architectures enable remote firmware updates, reducing truck-roll costs for provincial integrators managing distributed camera estates.
- HDD:Magnetic drives optimized for 24/7 sequential write workloads remain the cost-per-terabyte standard for 90-day retention mandates. Western Digital and Seagate supply high-capacity helium-filled models to NVR manufacturers in Hangzhou manufacturing clusters.
- SSD:Flash-based storage enables sub-second incident retrieval in retail security applications. NAND cost volatility constrains deployment scale beyond premium command-center installations.
HDD holds the largest share; momentum sits with NVR as IP camera penetration climbs.
Technology:
Cost tier differentiation separates commodity hardware from value-added software layers, with premium pricing attaching to orchestration platforms rather than raw storage media.
- Cloud Storage:MIIT-mandated data localization requires domestic cloud nodes for government video archives. Operators like Alibaba Cloud and Huawei Cloud have built sovereign video storage regions to capture public sector tenders previously served by on-premise infrastructure.
- Edge Computing:Preprocessing servers deployed at traffic intersections reduce upstream bandwidth costs by 60-70% through local analytics. Shenzhen municipal authorities specify edge-storage bundles in current procurement frameworks to manage 4K camera density expansion.
- RAID:Redundant array configurations remain standard for NVR failover in critical infrastructure monitoring. GB standards now specify minimum RAID levels for public safety deployments.
- Video Analytics:AI-enabled storage tiers that tag and index footage for rapid search command 40-50% price premiums over passive retention systems. Object-recognition workloads are expanding fastest in railway station security networks.
Cloud Storage captures the dominant procurement volume; Video Analytics is expanding most quickly as AI integration matures.
Application:
Volume concentration tracks government budget allocation cycles, with municipal procurement offices consolidating multi-year framework agreements that favor vendors with certified subsystem documentation.
- Public Safety:Police and emergency response command centers require 30-90 day retention with sub-second retrieval SLAs. HDD-based NVR systems dominate due to petabyte-scale economics and established SAMR certification pathways.
- Retail Security:Loss prevention and liability documentation drive demand for rapid incident retrieval. SSD penetration climbs here as franchise operators prioritize retrieval speed over cost-per-terabyte optimization.
- Infrastructure Monitoring:Power grid and telecommunications tower surveillance demands environmental resilience for outdoor cabinet deployment. NMPA-aligned GB standards specify vibration tolerance and ingress protection thresholds.
- Traffic Management:Real-time analytics requirements favor edge-computing storage architectures. Guangdong province camera density expansion is driving petabyte-scale tenders with preprocessing specifications.
Public Safety holds the largest share; momentum sits with Traffic Management as smart city budgets expand.
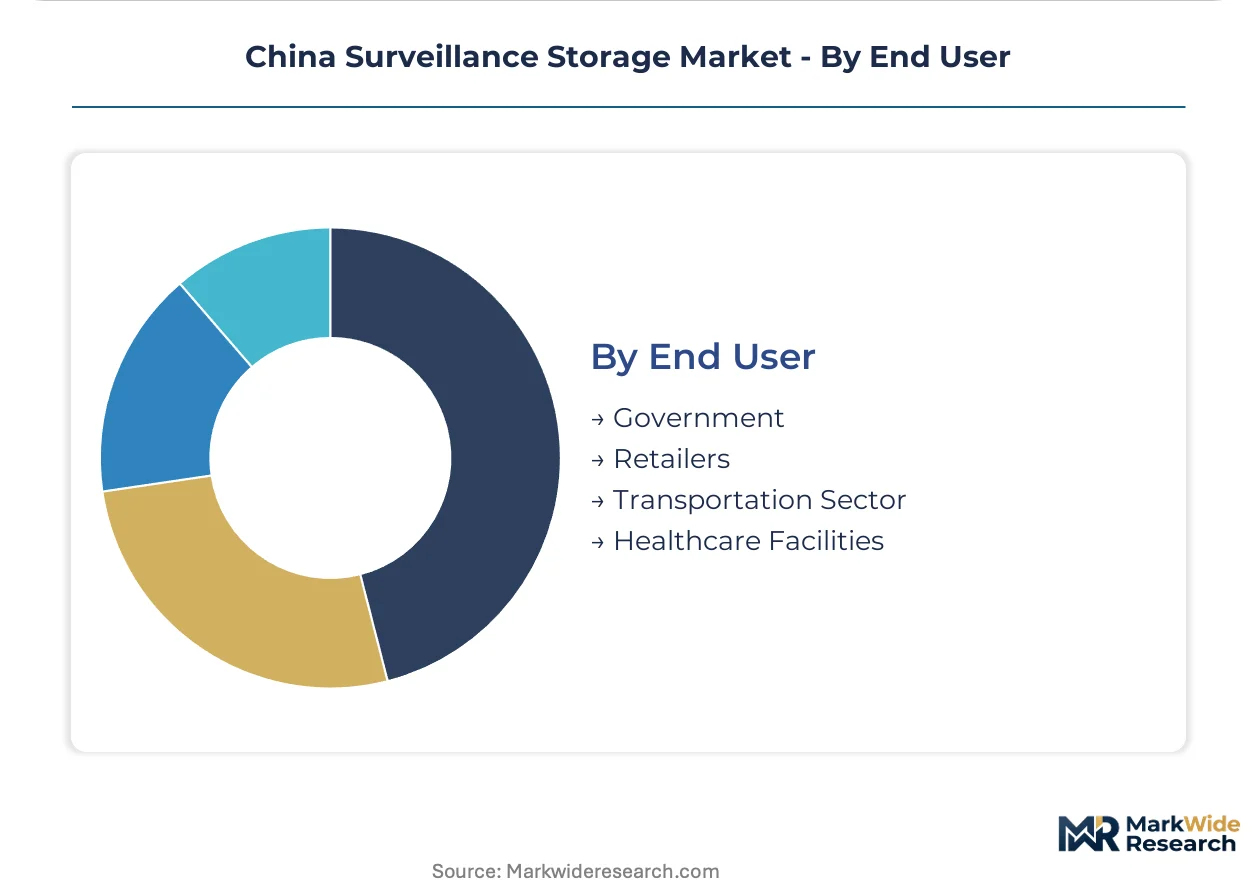
End User:
Customer type determines procurement channel access, with government buyers requiring SAMR cybersecurity certification while commercial segments prioritize total cost of ownership.
- Government:Municipal procurement offices specify encrypted subsystems with access logging under SAMR cybersecurity review rules. Direct manufacturer relationships are displacing tier-one distributors in Jiangsu and Guangdong.
- Retailers:Franchise operators and shopping mall managers prioritize rapid incident retrieval for liability protection. Cloud-tier adoption is climbing as MIIT localization requirements clarify compliance boundaries for multinational chains.
- Transportation Sector:Railway and airport authorities combine edge preprocessing with centralized retention for regulatory compliance. Dual carbon goals from MEE constrain data center expansion for video storage farms.
- Healthcare Facilities:Patient privacy requirements under data security law create specialized demand for encrypted storage with audit trails. Deployment scale remains limited compared to public safety budgets.
Government holds the largest share; momentum sits with Retailers as cloud localization frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eastern coastal provinces command pricing premiums of 15-20% over western regions due to integrated manufacturing clusters and direct procurement relationships. Provincial integrators in Jiangsu and Guangdong bypass traditional distribution tiers entirely. Municipal procurement offices in tier-one cities consolidate multi-year framework agreements that compress margins for channel-dependent vendors.
Guangdong Province
Shenzhen and Guangzhou traffic management authorities drive petabyte-scale storage tenders for 4K camera density expansion at urban intersections. MIIT data-localization mandates require domestic cloud nodes for government video archives, compelling municipal buyers to source from certified sovereign storage regions. The Pearl River Delta manufacturing corridor anchors NVR and edge-computing server production for nationwide distribution.
Jiangsu Province
Nanjing and Suzhou smart city budgets concentrate demand for encrypted subsystems with SAMR-mandated access logging capabilities. Provincial integrators establish direct manufacturer relationships, displacing tier-one distributors from public safety procurement workflows. The Yangtze River Delta cluster overlaps surveillance equipment production with cloud infrastructure procurement within unified buyer organizations.
Zhejiang Province
Hangzhou municipal authorities specify edge-storage bundles with preprocessing capabilities to manage bandwidth costs from real-time video analytics workloads. GB standards under NMPA-aligned frameworks enforce environmental resilience certification for outdoor infrastructure monitoring deployments. The province's manufacturing base supplies high-capacity helium-filled HDD models to system integrators nationwide.
Sichuan Province
Chengdu smart city budgets remain underallocated for surveillance storage relative to coastal provinces, creating whitespace for vendors with localized service networks. MEE dual carbon goals constrain data center expansion for video storage farms in the region. Western China procurement offices prioritize total cost of ownership over premium-tier feature sets in current tender evaluations.
Beijing-Tianjin-Hebei
Capital region public safety command centers require sub-second retrieval SLAs for 30-90 day retention mandates in police and emergency response applications. SAMR cybersecurity review rules compel municipal buyers to replace legacy storage with certified encrypted subsystems. The northern cluster concentrates AI-video convergence demand where object-recognition algorithms require low-latency storage architectures.
China Surveillance Storage Market Competitive Landscape
Hardware-integrated specialists and component-scale suppliers split the market along the value chain boundary. Captive production of NVR and DVR systems anchors the integrated segment, while dedicated drive manufacturers supply high-capacity media optimized for 24/7 sequential write workloads. Two strategic archetypes dominate: vertically integrated security equipment vendors with in-house storage subsystems, and pure-play storage media suppliers with specialized firmware for video workloads. Competitive moves concentrate on direct procurement channel establishment and edge-computing bundle development.
Among China-based security equipment vendors, Hangzhou Hikvision Digital Technology Co Ltd and Dahua Technology Co Ltd occupy positions as hardware-integrated storage segment anchors through captive production capabilities. Seagate Technology Holding PLC represents the component-scale supplier archetype with HDD specialization for continuous video workloads. These three entities exemplify the structural division between integrated system vendors and dedicated media suppliers that defines competitive positioning in municipal procurement frameworks.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co Ltd |
| Dahua Technology Co Ltd |
| Zhejiang Uniview Technologies Co Ltd |
| Seagate Technology Holding PLC |
| Dell Technologies |
| Cisco Systems |
| Huawei Technologies |
| Inspur Group |
| Axis Communications AB |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on high-capacity HDD manufacturing determines both the premium spread for certified encrypted subsystems and the channel structure compressing distributor margins. SAMR-mandated cybersecurity review rules extend validation cycles, forcing municipal buyers to absorb customization premiums while provincial integrators bypass traditional tiers to source directly from manufacturers.
Pricing Analysis
Configured-to-order pricing for SAMR-certified encrypted subsystems commands substantial premiums over standard NVR configurations lacking access-logging capabilities. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in economy-tier DVR segments is intensifying because analog-transition budgets in tier-three cities constrain procurement flexibility. Municipal government buyers exhibit the lowest price sensitivity due to compliance mandates, while retail franchise operators prioritize total cost of ownership over premium retrieval speeds.
Supply Chain Analysis
Extended payment terms from provincial integrators to HDD manufacturers have become standard practice as municipal procurement offices consolidate multi-year framework agreements. Component supply draws from Thailand, Malaysia, and China for high-capacity helium-filled drive assembly, with NAND flash sourcing resting on South Korean and Taiwanese foundry output. Single-source vulnerability concentrates in precision spindle motor manufacturing, exposing integrators to allocation risk during component shortages. Distribution runs through direct manufacturer relationships with municipal procurement offices rather than traditional tier-one distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of firmware engineers capable of navigating SAMR encryption certification timelines creates bottlenecks that advantage vendors with established regulatory affairs capabilities over pure hardware specialists.
For Market Incumbents: Pre-empt margin erosion from direct procurement channel restructuring by establishing captive service networks in Sichuan and Shaanxi before competitors localize. Invest in backward integration into edge-computing server assembly to capture preprocessing bundle premiums that municipal traffic authorities now specify. Defend against pure-play HDD suppliers by embedding storage subsystems within comprehensive NVR platforms with remote firmware update capabilities. For New Entrants and Emerging Players: Western province underpenetration relative to coastal smart city budgets offers whitespace for vendors willing to build localized technician networks for field-replaceable component service. Target retail security segments where SSD penetration remains constrained by NAND cost volatility, offering hybrid tiering architectures that balance retrieval speed with cost-per-terabyte economics. Establish go-to-market positioning through cloud infrastructure partnerships that satisfy MIIT data-localization mandates for multinational security operators. For Investors and Strategic Acquirers: SAMR's forthcoming data-sovereignty interpretations reshape the acquisition landscape by forcing multinational operators to deploy domestic cloud nodes, creating demand for compliant storage infrastructure partnerships. Long-term viability across the analysis window hinges on regulatory navigation capabilities rather than raw manufacturing scale. Acquisition target archetypes include provincial integrators with established municipal procurement office relationships. Monitor GB standards evolution under NMPA-aligned frameworks as the signal indicating which environmental resilience certifications will become mandatory for outdoor infrastructure deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Bundle Development | Shenzhen municipal authorities specify preprocessing servers to manage 4K camera density expansion bandwidth costs. |
| SAMR Certification Investment | Encryption and access-logging compliance extends product validation cycles, delaying revenue recognition for uncertified launches. |
| Direct Procurement Channel Establishment | Provincial integrators in Jiangsu and Guangdong bypass tier-one distributors, compressing traditional channel margins. |
| Western Province Service Localization | Sichuan and Shaanxi smart city budgets remain underallocated, creating whitespace for vendors with technician networks. |
| Cloud Infrastructure Partnership | MIIT data-localization mandates force multinational security operators to deploy domestic sovereign storage regions. |
Research Methodology
Desk research of customs trade records, MIIT policy circulars, and municipal procurement tender databases preceded structured interviews with provincial system integrators, NVR product managers at security equipment vendors, and data center operators managing video storage farms. Primary fieldwork with SAMR certification consultants and edge-computing server engineers validated secondary findings on firmware validation timelines. Bottom-up demand modeling from camera deployment statistics triangulated against top-down market sizing from HDD shipment data.
Assumption sets held MIIT data-localization policy enforcement and SAMR cybersecurity review rule scope fixed across the projection horizon, while NAND flash price volatility and provincial smart city budget allocation cycles varied stochastically. Segmentation dimensions modeled include product type, deployment architecture, compliance requirement tier, and end-user procurement channel access. CAGRs derived from logistic diffusion curves fitted to historical IP camera penetration rates and cloud storage adoption patterns in government archives.
Macroeconomic conditions sit as an overlay; deviation in provincial fiscal transfer flows or MEE dual carbon goal enforcement stringency would shift the trajectory. Forecasts reflect documented assumptions regarding GB standards implementation timelines and HDD manufacturer capacity expansion plans. Regulatory reinterpretation of data-sovereignty requirements, technological disruption from AI-video convergence architectures, or supply chain restructuring from geopolitical friction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
China Surveillance IP Camera Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
France Surveillance Camera Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
Global Trade Surveillance Systems Market
Video Surveillance Systems
India Surveillance IP Cameras Market