
 Video Surveillance Software Market | 2026-2036
Video Surveillance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Video Surveillance Software Market Insights
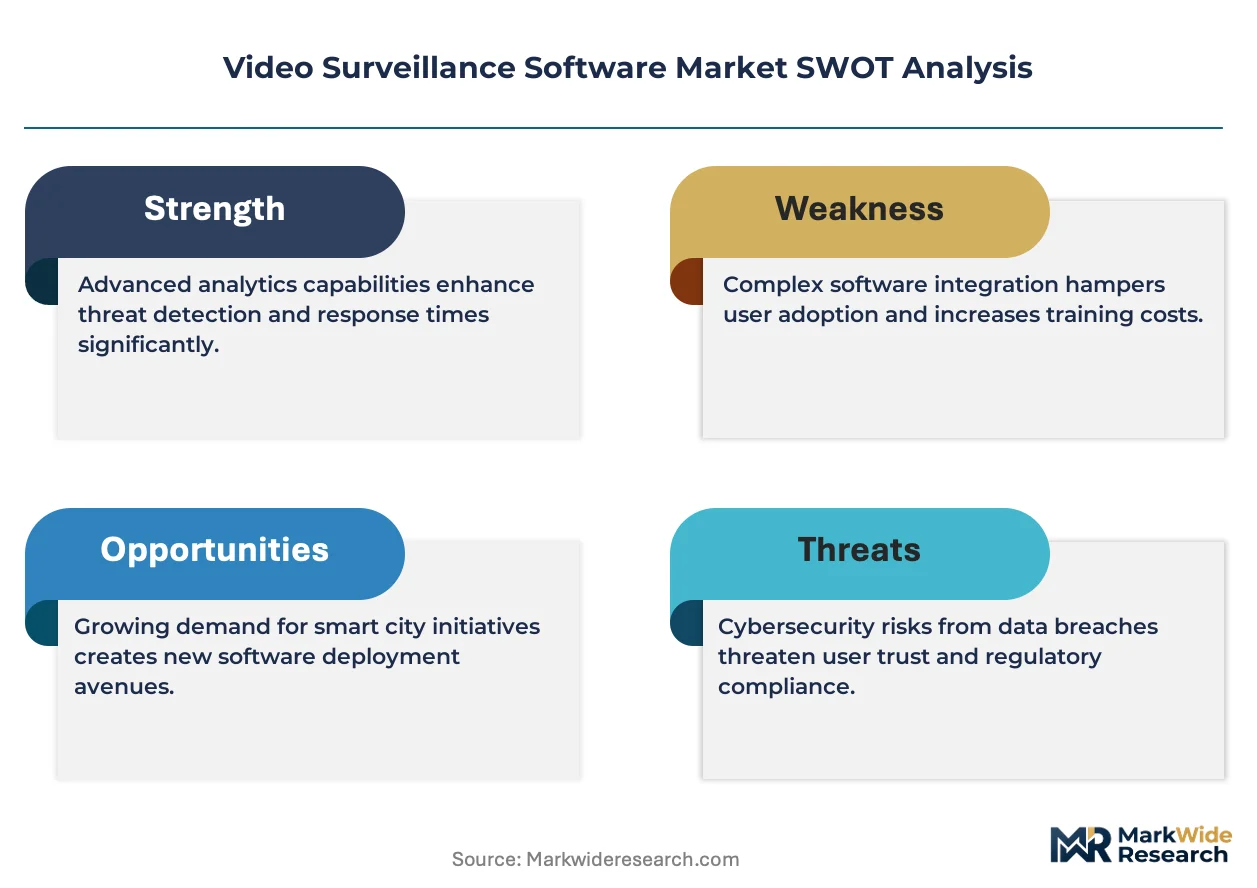
Edge-to-cloud orchestration is rewriting how video surveillance software architectures are engineered and deployed across enterprise environments. Hangzhou Hikvision Digital Technology Co., Ltd. leverages deep vertical integration from camera silicon to analytics layers, sustaining cost advantages in hardware-software bundles. Axis Communications AB anchors its position through open-platform VMS partnerships, while Genetec Inc. differentiates via unified security platform architecture spanning access control and video management.
Video surveillance software encompasses applications that ingest, process, store, and analyze video streams from IP cameras and edge devices, typically operating at frame rates of 15-30 fps with H.265 compression to optimize bandwidth and storage utilization. Its primary commercial purpose centers on real-time threat detection, forensic investigation, and operational intelligence extraction for physical security and business optimization. Cloud-based software deployments are capturing disproportionate growth momentum as organizations prioritize remote accessibility and elastic storage scaling over capital-intensive on-premises infrastructure. Video analytics segments command premium positioning due to embedded computer vision workloads requiring GPU acceleration, whereas mobile surveillance remains nascent but strategically significant for field operations and distributed workforce monitoring.
FCC guidelines on communications infrastructure intersect with NIST cybersecurity frameworks to shape product certification requirements for networked surveillance systems in the United States. GDPR data localization mandates in Europe and China's SAMR oversight of algorithmic recommendation systems collectively constrain how facial recognition and behavioral analytics modules are deployed across jurisdictions. Stakeholders must weigh regulatory fragmentation against the operational efficiencies of unified global software platforms when architecting multi-region deployments.
Market Dynamics
AI-powered video analytics at the edge is compressing latency requirements and forcing software vendors to re-architect deployment models around distributed inference rather than centralized processing.
Growth Catalysts
- Federal security spending in the United States:Congressional appropriations for critical infrastructure protection are accelerating procurement cycles for municipal and transportation authorities seeking unified threat detection platforms.
- GDPR Article 17 compliance frameworks:European data localization mandates are creating specialized demand for on-premises video management systems with automated retention and deletion workflows.
- GPU acceleration for computer vision workloads:Embedded neural processing units in edge cameras are enabling real-time behavioral analytics without backhaul dependency, opening new deployment scenarios in bandwidth-constrained environments.
Market Restraints
- Silicon supply concentration in Taiwan:Dependence on TSMC fabrication for high-performance AI accelerators creates vulnerability in camera SoC availability and pricing volatility.
- Cross-border data friction under China's GB standards:Facial recognition algorithm registration requirements with SAMR impose compliance overhead that fragments multinational software architectures.
- On-premises storage cost structures:Capital-intensive server farms with RAID redundancy requirements disadvantage smaller security integrators against cloud-native competitors.
Strategic Opportunities
- India's Smart Cities Mission:Municipal digitization programs in 100 urban centers are creating tender pipelines for integrated video analytics with traffic management and public safety fusion.
- EU AI Act risk classification:Biometric identification systems designated as high-risk will require conformity assessments, creating service revenue streams for compliance-certified software vendors.
- 5G private network convergence:Ultra-reliable low-latency connectivity is enabling mobile surveillance deployments for event security and temporary perimeter protection previously served by fixed infrastructure.
Industry Challenges
- Computer vision engineering talent scarcity:Shortage of specialists in edge optimization and model quantization is constraining product development velocity across mid-tier vendors.
- Interoperability certification delays:ONVIF Profile T and S compliance testing backlogs are extending time-to-market for new camera integrations.
- Legacy analog migration complexity:Hybrid VMS architectures supporting coaxial and IP streams simultaneously are inflating support costs and degrading user experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Surveillance Software Market |
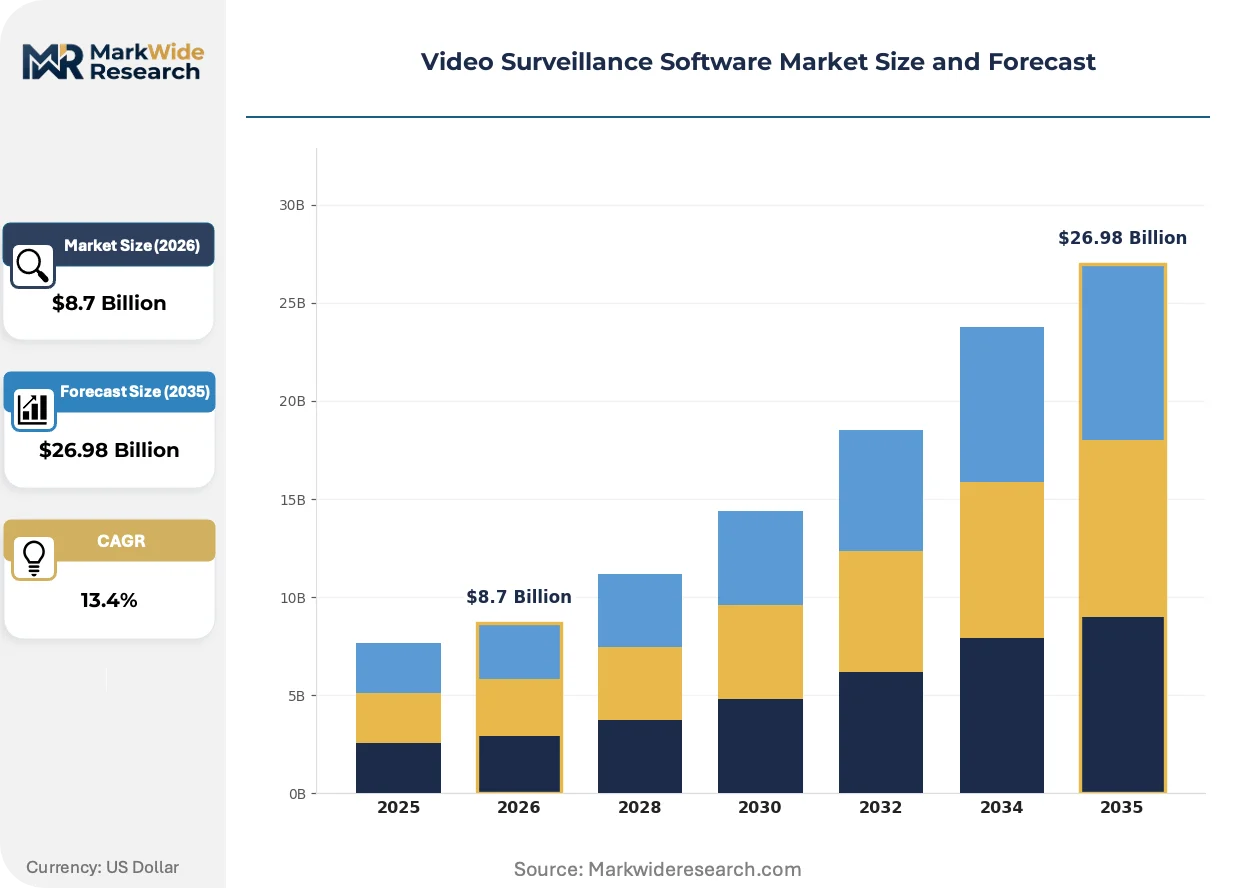
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Video Analytics, Central Management Software, Cloud-based Software, Mobile Surveillance Deployment Model: On-premises, Cloud, Hybrid, Edge Computing End User: Retail, Transportation, Healthcare, Government Integration Level: Standalone, Integrated, API-enabled, Cloud-connected |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Axis Communications AB, Genetec Inc., Milestone Systems, Verkada, Avigilon, Honeywell International Inc., Eagle Eye Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Surveillance Software Market Trends and Innovations
Containerized microservices architectures are fragmenting monolithic video management platforms into composable inference pipelines that can deploy across heterogeneous edge-cloud environments.
Edge-native AI inference engines with TensorRT optimization are rendering obsolete centralized GPU farms for object classification and anomaly detection workloads. Large retail chains and logistics hubs in Germany and the Netherlands are deploying these systems at 500+ camera scale. The shift is compressing total cost of ownership by eliminating redundant encoding and storage of raw video streams.
GDPR's automated decision-making restrictions under Article 22 are forcing European deployments to implement human-in-the-loop review workflows for behavioral analytics alerts. Airport operators and railway authorities in France and Italy are retrofitting existing VMS installations with manual verification queues. This regulatory friction is bifurcating product roadmaps between privacy-preserving European variants and permissive configurations for other markets.
Subscription-based SaaS pricing is displacing perpetual license models among mid-market commercial buyers seeking predictable operational expenditure profiles. Security integrators in the United Kingdom are repositioning as managed service providers with recurring revenue streams. The transition is most visible in multi-site retail and hospitality verticals where centralized monitoring across distributed locations is operationally critical.
Video Surveillance Software Market Segmentation
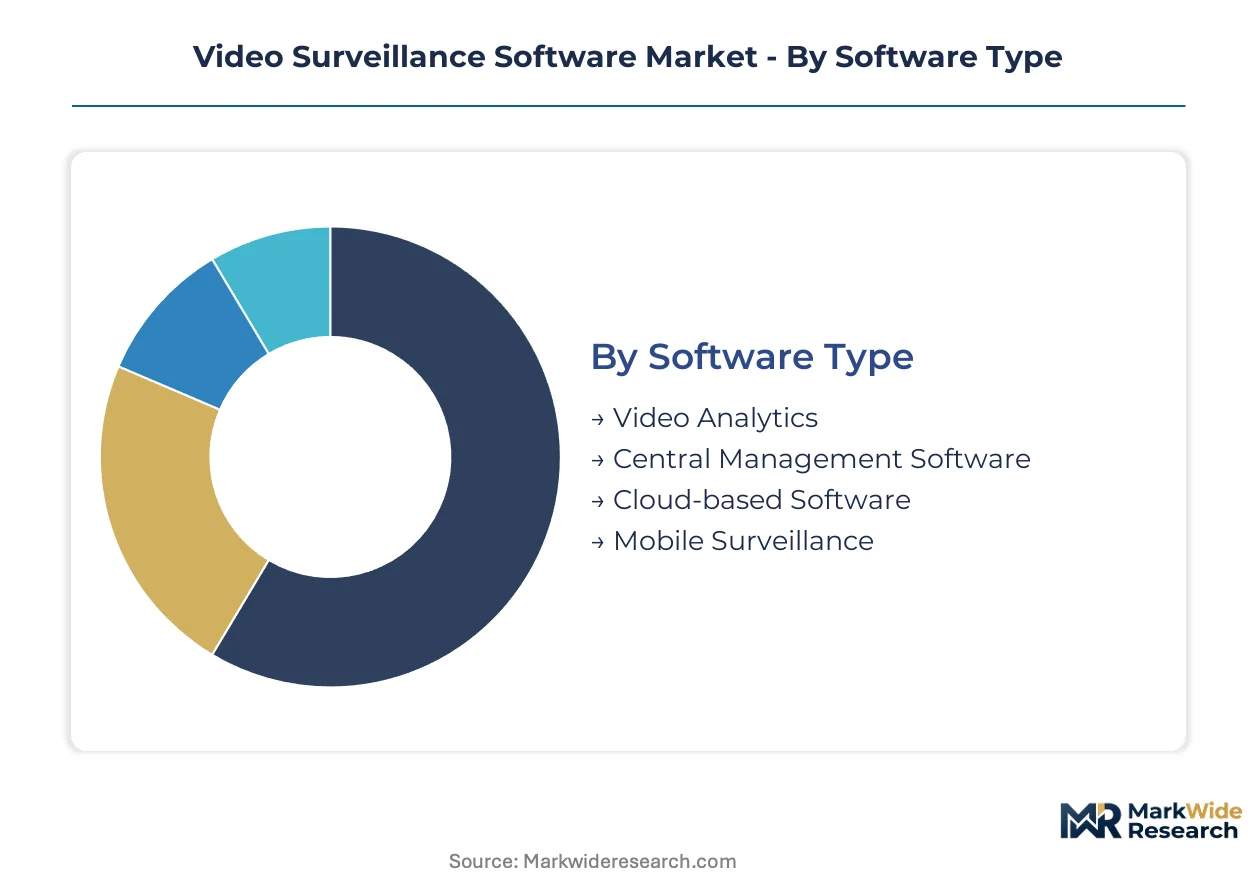
Video surveillance software segmentation reveals divergent refresh cycles across deployment architectures, with cloud-native solutions turning over every 18-24 months while on-premises installations persist for 5-7 years. Understanding these temporal patterns helps vendors align R&D roadmaps with replacement windows and customer upgrade appetites.
Software Type:
Video analytics platforms refresh fastest as AI model architectures evolve quarterly, while central management software maintains the longest deployment tenure due to integration complexity and operator retraining costs.
- Video Analytics:Computer vision modules process streams at 15-30 fps with H.265 compression, embedding neural inference for object classification and anomaly detection. Demand concentrates in German logistics hubs and Dutch retail chains deploying 500+ camera edge-native systems to eliminate redundant storage. GPU acceleration requirements and quarterly model updates compress replacement cycles to 12-18 months.
- Cloud-based Software:SaaS architectures deliver elastic storage scaling and remote accessibility through browser-based interfaces. United Kingdom security integrators are repositioning as managed service providers with recurring revenue streams, particularly across multi-site hospitality and retail verticals where centralized monitoring is operationally critical. Subscription pricing displaces perpetual licenses among mid-market buyers.
- Central Management Software:Monolithic VMS platforms aggregate multi-vendor camera feeds with unified operator interfaces.
- Mobile Surveillance:Field-deployable applications support distributed workforce monitoring and temporary perimeter scenarios.
Central management software dominates installed base. Cloud-based software is where expansion concentrates.
Deployment Model:
Cost tiering separates capital-intensive on-premises infrastructure from operational expenditure cloud models, with hybrid architectures capturing mid-budget customers seeking staged migration paths.
- On-premises:Server farms with RAID redundancy requirements demand substantial upfront capital and dedicated IT support. Smaller security integrators face displacement pressure from cloud-native competitors as storage cost structures disadvantage localized deployments. GDPR Article 17 compliance frameworks in Europe create specialized demand for automated retention and deletion workflows.
- Cloud:Multi-tenant architectures abstract infrastructure management while delivering geographic redundancy and automatic security patching. United States federal security spending accelerates municipal and transportation authority procurement of unified threat detection platforms with remote accessibility. Elastic scaling eliminates overprovisioning penalties during demand spikes.
- Hybrid:Architectures preserve sensitive footage on local servers while archiving aged content to cloud tiers.
- Edge Computing:Distributed inference pipelines deploy TensorRT-optimized models directly on camera SoCs.
On-premises deployments retain the largest footprint. Edge computing is climbing the fastest as latency requirements compress.
End User:
Application criticality varies sharply across verticals, with transportation authorities demanding 99.999% uptime while retail tolerates brief outages during non-peak hours.
- Government:Municipal smart city infrastructure projects accelerate procurement of AI-powered video analytics platforms for public safety fusion and traffic management integration. India's Smart Cities Mission creates tender pipelines across 100 urban centers for integrated systems. Congressional appropriations for critical infrastructure protection compress procurement cycles for unified threat detection.
- Transportation:Airport operators and railway authorities in France and Italy retrofit VMS installations with human-in-the-loop review workflows to satisfy GDPR Article 22 restrictions on automated decision-making. Ultra-reliable low-latency 5G private networks enable mobile surveillance deployments for event security previously served by fixed infrastructure.
- Retail:Loss prevention and customer flow analytics drive adoption across multi-site chains.
- Healthcare:Patient safety monitoring and access control integration create specialized compliance requirements.
Government verticals command the highest contract values. Retail represents the broadest addressable base.
Integration Level:
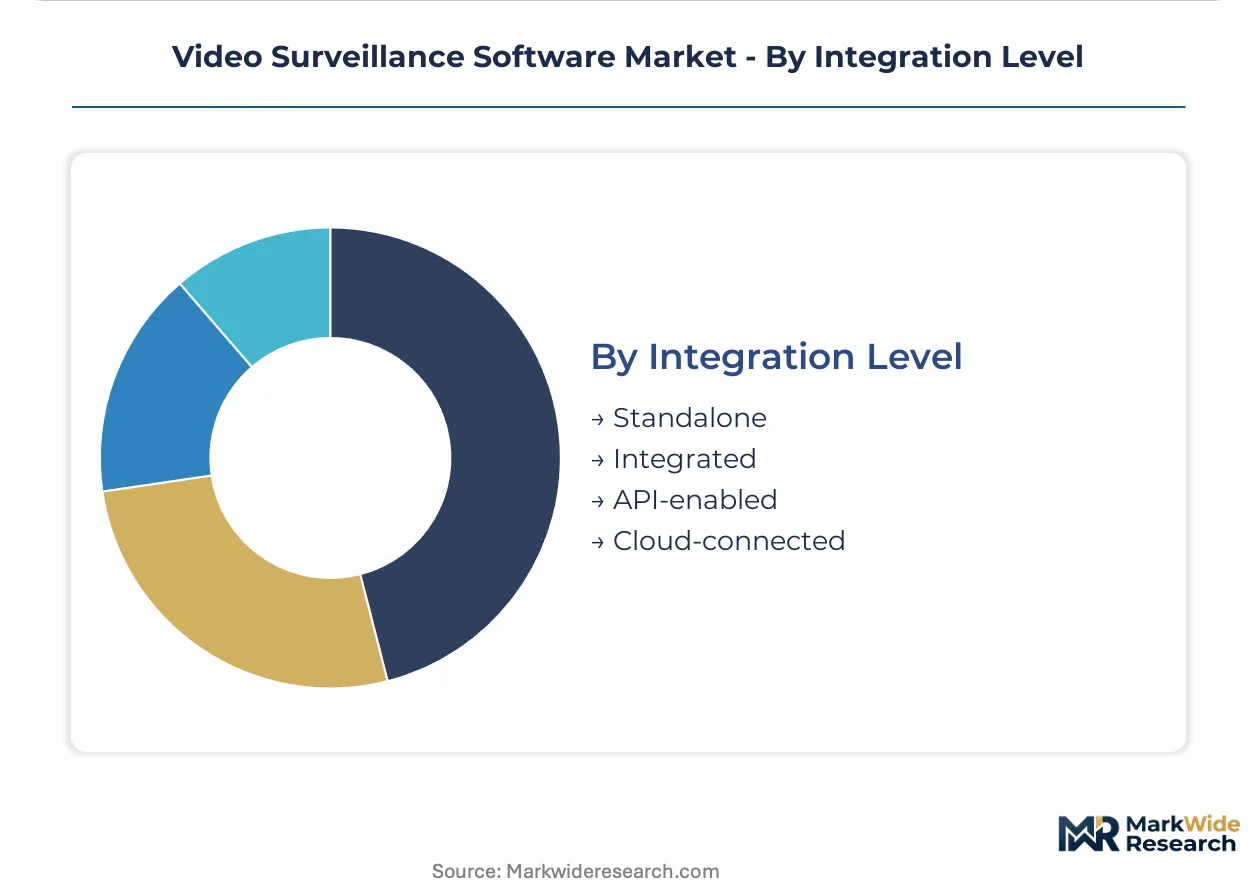
Customer technical sophistication determines integration appetite, with enterprise security teams demanding API extensibility while small operators prefer turnkey standalone deployments.
- API-enabled:RESTful interfaces and webhook architectures permit custom workflow automation and third-party system interconnection. ONVIF Profile T and S compliance testing backlogs extend time-to-market for new camera integrations, constraining product development velocity. Containerized microservices fragment monolithic platforms into composable inference pipelines deployable across heterogeneous environments.
- Integrated:Unified security platforms spanning access control and video management reduce operator training burden and incident response latency. Genetec differentiates through this architecture, consolidating physical security silos into single-pane-of-glass operations. Legacy analog migration complexity inflates support costs for hybrid VMS architectures supporting coaxial and IP streams simultaneously.
- Standalone:Self-contained installations minimize deployment complexity for single-site operators.
- Cloud-connected:Persistent internet links enable remote firmware updates and centralized policy management.
Integrated systems anchor enterprise deployments. API-enabled configurations are gaining share fastest among technically sophisticated buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese video surveillance software exports flow primarily to Southeast Asian smart city projects and Middle Eastern critical infrastructure deployments, establishing a dominant trade corridor that shapes regional competitive dynamics.
United States
Federal security appropriations and municipal cloud migration are compressing procurement cycles for unified threat detection platforms. FCC guidelines intersect with NIST cybersecurity frameworks to mandate communications infrastructure certification for networked surveillance systems. Security integrators across Texas and California are repositioning as managed service providers with recurring revenue streams.
Germany
Logistics hubs and retail chains are deploying 500-plus camera edge-native systems to eliminate redundant storage and encoding costs. GDPR Article 17 compliance frameworks create specialized demand for on-premises video management with automated retention workflows. Industrial clusters in North Rhine-Westphalia are retrofitting existing VMS installations with human-in-the-loop review processes.
China
Smart city infrastructure projects in municipal governments are accelerating procurement of AI-powered video analytics platforms. SAMR oversight of algorithmic recommendation systems and GB standards on facial recognition impose registration requirements that fragment multinational software architectures. Yangtze River Delta municipalities are integrating traffic management with public safety fusion systems.
India
Municipal digitization programs across 100 urban centers are creating tender pipelines for integrated video analytics. The Smart Cities Mission directs central government funding toward surveillance-integrated traffic management and public safety infrastructure. Technology deployment concentrates in Maharashtra and Karnataka where state-level procurement frameworks favor domestic system integrators.
United Kingdom
Mid-market commercial buyers are displacing perpetual license models with subscription-based SaaS pricing for predictable operational expenditure. Multi-site hospitality and retail verticals demand centralized monitoring across distributed locations. London-based security integrators are capturing recurring revenue by repositioning as managed service providers.
Video Surveillance Software Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct tiers: full-stack hardware-software bundles, open-platform software specialists, and cloud-native challengers. Strategic archetypes include vertically integrated camera-to-analytics providers, API-first platform vendors, and subscription-based SaaS operators. Dominant competitive moves span backward integration into silicon design and strategic partnerships with systems integrators for managed service delivery.
Within the full-stack tier, Hangzhou Hikvision Digital Technology Co., Ltd. exemplifies upstream control from camera silicon through analytics layers. Axis Communications AB and Genetec Inc. occupy positions on the open-platform vector, with the former anchoring partnerships across video management system ecosystems and the latter representing unified security platform architecture spanning access control and video management.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Genetec Inc. |
| Milestone Systems |
| Verkada |
| Avigilon |
| Honeywell International Inc. |
| Eagle Eye Networks |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Taiwanese semiconductor fabrication is compressing margins for AI accelerator suppliers while simultaneously lowering entry barriers for camera SoC vendors, creating divergent pricing power across hardware tiers.
Pricing Analysis
Current-generation edge-native inference engines command substantial premiums over prior-generation centralized GPU farm architectures, while next-generation neuromorphic silicon remains pre-commercial. Three-tier pricing structure across premium, standard, and economy levels separates GPU-accelerated analytics suites from CPU-based management platforms from basic recording software. Cost compression in the mid-tier is intensifying because cloud-native SaaS operators are absorbing infrastructure overhead into subscription bundles. Small security integrators exhibit highest price sensitivity as capital-intensive on-premises RAID deployments face displacement.
Supply Chain Analysis
Upstream feedstock for high-performance camera SoCs draws from Taiwan, South Korea, and the United States, with TSMC fabrication anchoring neural processing unit availability. Critical inputs include silicon wafers, H.265 encoding chipsets, and specialized image sensors. Single-source vulnerability concentrates in advanced node fabrication, where geopolitical friction threatens supply continuity. Distribution runs through systems integrators and managed service providers rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-powered video analytics at the edge constitutes a high-growth disruption, with GDPR Article 22 compliance mandates forcing human-in-the-loop retrofits that bifurcate product roadmaps.
For Market Incumbents: Harden platform architectures against cloud-native challengers by deepening backward integration into edge silicon design and securing ONVIF certification ahead of testing backlogs. Channel control through managed service provider partnerships offers defensive positioning against subscription-based SaaS entrants. For New Entrants and Emerging Players: India's Smart Cities Mission tender pipeline represents the most penetrable geography, with 100 urban centers digitizing public safety infrastructure. Field-deployable mobile surveillance for 5G private networks offers white-space targeting. Go-to-market through domestic system integrators in Maharashtra and Karnataka bypasses incumbent channel lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native SaaS sub-segments as multi-tenant architectures eliminate server farm provisioning. Long-term viability favors API-first platform vendors with recurring revenue streams over perpetual-license legacy operators. The signal to monitor is federal security appropriation velocity in the United States.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native AI Inference Deployment | TensorRT optimization eliminates redundant storage costs for German logistics hubs operating 500-plus camera systems. |
| GDPR Compliance Certification Investment | Article 17 automated retention workflows create service revenue moats for European on-premises vendors. |
| Managed Service Provider Repositioning | United Kingdom security integrators capture recurring revenue through centralized multi-site monitoring subscriptions. |
| 5G Private Network Integration | Ultra-reliable low-latency connectivity enables mobile surveillance for temporary event security deployments. |
| Backward Integration into Silicon Design | In-house neural processing unit development insulates against TSMC capacity volatility and pricing pressure. |
Research Methodology
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and channel partners anchored the qualitative base. Primary interview insights combined with secondary validation against SEC filings, hyperscaler capex disclosures, customs records, and ONVIF compliance registries. Bottom-up deployment model sizing and top-down vertical spend analysis were triangulated to constrain estimate variance.
Scenario-bracketing framed demand trajectories across the projection horizon, with segmentation dimensions spanning deployment architecture, organization size, vertical application, integration complexity, and regional regulatory cluster. CAGRs derived from modeled replacement cycles and upgrade velocity curves, with edge computing adoption curves and federal appropriation patterns serving as industry-specific sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated camera-to-analytics providers would shift outcomes. Cross-checking against municipal procurement database filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
Japan Surveillance IP Cameras Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market