
 France Surveillance Analog Camera Market | 2026-2036
France Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
France Surveillance Analog Camera Market Insights
Market Context with Strategic Players
CE marking under the EU Radio Equipment Directive is reorganizing vendor eligibility for public-sector tenders across France. Hanwha Vision leverages its European certification pipeline to sustain access to French government building contracts. Bosch Sicherheitssysteme GmbH anchors its position through manufacturing scale and channel control in the dome camera segment.
Technical Definition and Structural Segments
France surveillance analog cameras capture continuous video signals through coaxial cable transmission without digital encoding, typically operating at 720x576 resolution (PAL standard) for real-time monitoring with minimal latency. These devices serve commercial and institutional security managers requiring backward-compatible upgrades without full infrastructure replacement. Dome cameras dominate indoor retail installations where discreet positioning matters, while bullet cameras lead outdoor corporate and municipal deployments for their weather-resistant housings and directional range. PTZ cameras represent the fastest-growing product type among educational institutions seeking perimeter coverage flexibility.
Regulatory Framework and Outlook
CNIL guidelines on video surveillance data retention, combined with GDPR biometric-data restrictions and France's internal security code provisions, constrain product feature sets and deployment protocols for analog systems. The EU AI Act's pending implementation for remote biometric identification will further tighten compliance requirements for camera vendors serving French public buildings. Stakeholders must monitor regulatory divergence between national security exemptions and data-protection mandates when evaluating analog versus hybrid migration paths.
Market Dynamics
France's surveillance analog camera market faces structural pressure from the EU AI Act's pending biometric identification restrictions, which force municipal buyers to reassess hardware procurement timelines and feature specifications ahead of compliance deadlines.
Growth Catalysts
- Legacy infrastructure retrofit demand:Aging coaxial cable networks in Île-de-France transport hubs require backward-compatible camera replacements without full digital overhauls.
- CNIL enforcement consistency:France's data protection authority provides predictable compliance frameworks that reduce procurement uncertainty for institutional security managers.
- Municipal budget constraints:Lyon and Marseille police departments prioritize cost-effective analog units over hybrid system investments during fiscal consolidation periods.
Market Restraints
- Copper cable input volatility:Fluctuating raw material costs for coaxial infrastructure components compress margin predictability for installation contractors.
- GDPR biometric-data friction:Facial recognition capability restrictions limit product feature differentiation and constrain premium pricing for hardware vendors.
- IP camera substitution threat:Network-based surveillance systems with Power-over-Ethernet deployment are capturing greenfield municipal contracts previously reserved for analog specifications.
Strategic Opportunities
- Educational institution perimeter expansion:PTZ camera deployments across university campuses in Provence-Alpes-Côte d'Azur create specialized application demand.
- CE marking regulatory tailwind:EU Radio Equipment Directive certification requirements filter non-compliant competitors from public-sector tender pools.
- Hybrid convergence architecture:Analog-to-digital encoder integration enables staged infrastructure modernization without immediate full replacement capex.
Industry Challenges
- Coaxial technician skill scarcity:Specialized installation expertise for PAL-standard signal termination is diminishing as training programs pivot toward IP networking curricula.
- Legacy system integration complexity:DVR compatibility testing across multi-vendor installed bases extends deployment timelines and elevates project risk for systems integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Surveillance Analog Camera Market |
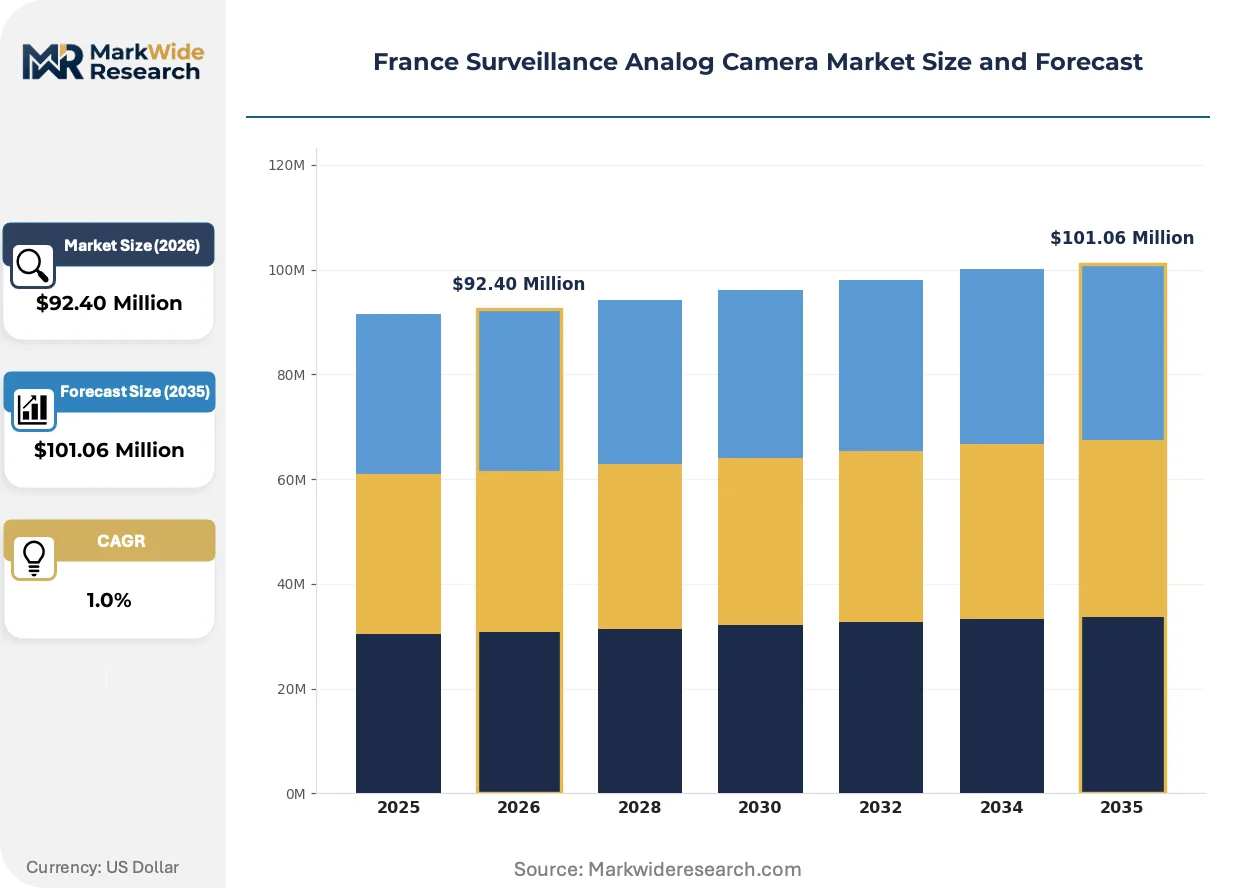
| Market Size in 2026 | $92.40 Million |
| Market Size in 2035 | $101.06 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Box Cameras, Dome Cameras, Bullet Cameras, PTZ Cameras End User: Retail Stores, Corporate Offices, Educational Institutions, Government Buildings Installation Type: Indoor, Outdoor, Hybrid, Portable Connectivity: CCTV, IP Network, Analog, Wireless |
| Companies Covered | Hanwha Vision, Zhejiang Uniview Technologies Co Ltd, Teledyne FLIR LLC, Honeywell International Inc, IDIS Ltd, Hangzhou Hikvision Digital Technology Co., Ltd., Zosi Technology Ltd., Axis Communications AB, Bosch Sicherheitssysteme GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Surveillance Analog Camera Market Trends and Innovations
Technological substitution and regulatory tightening are compressing the operational lifespan of pure analog architectures while opening transitional pathways for vendors capable of bridging legacy and digital surveillance ecosystems.
High-definition analog-over-coax technologies including HD-TVI and HD-CVI formats are supplanting standard-definition PAL installations in French retail security environments. Large-format supermarket chains in the Grand Est region are adopting these intermediate-resolution formats to extend existing cable infrastructure. The transition is compressing demand for legacy 720x576 equipment while delaying full IP migration decisions.
France's internal security code provisions are tightening data retention specifications for public-space surveillance systems. Municipal operators must now demonstrate automated deletion protocols and access logging capabilities that analog-native architectures struggle to satisfy. The CNIL is conducting sector-specific compliance audits that elevate documentation burdens for dome and bullet camera deployments in Lyon transport networks.
Security managers are unbundling hardware procurement from installation and maintenance contracts. French institutional buyers now separate camera supply from systems integration services, compressing vendor margins while elevating specialized contractor influence. This disintermediation is most visible in Marseille municipal tenders, where technical specification authority has shifted from product vendors to engineering consultancies.
France Surveillance Analog Camera Market Segmentation
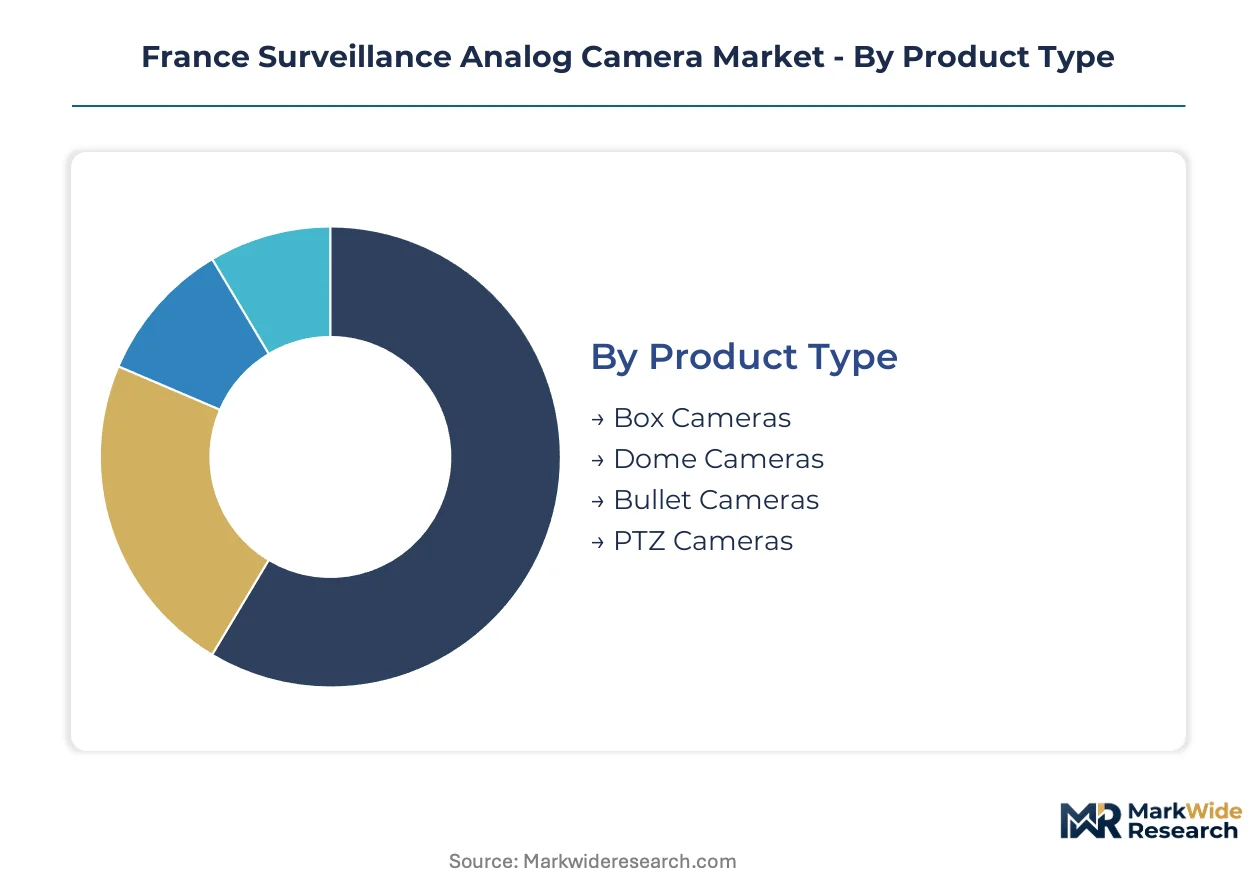
Segmentation reveals how substitution pressure from IP-based systems concentrates differently across hardware form factors, end-use environments, and deployment architectures. Understanding these fault lines helps vendors calibrate product roadmaps between legacy analog maintenance and hybrid transition strategies.
Product Type:
Dome and bullet cameras face divergent substitution timelines as indoor retail environments accelerate toward IP migration while outdoor municipal installations extend coaxial infrastructure lifecycles.
- Dome Cameras:Enclosed hemispherical housings with vandal-resistant polycarbonate domes serve discrete indoor surveillance requirements. French retail chains in Lyon shopping districts prioritize these units for ceiling-mounted loss prevention, though HD-TVI format conversions are displacing standard-definition PAL inventory.
- Bullet Cameras:Cylindrical weather-sealed housings with integrated IR illumination dominate perimeter applications. Marseille municipal police specify these for outdoor transport hub coverage where coaxial cable burial costs deter full IP overhauls.
- Box Cameras:Modular lens-interchangeable bodies for specialized focal length requirements.
- PTZ Cameras:Pan-tilt-zoom motorized assemblies with joystick-controlled positioning.
Dome cameras retain volume leadership; PTZ cameras hold the steepest expansion curve.
End User:
Budget compression and regulatory exposure create distinct procurement patterns across institutional buyers, with educational institutions outpacing other sectors in perimeter expansion spending.
- Educational Institutions:Universities and secondary schools deploy PTZ configurations for campus boundary monitoring. Provence-Alpes-Côte d'Azur regional campuses are expanding analog-digital hybrid architectures to satisfy CNIL audit requirements without immediate full replacement.
- Government Buildings:Municipal and national administrative facilities operate under strict internal security code data retention mandates. Île-de-France prefecture buildings balance legacy DVR compatibility against impending EU AI Act biometric identification restrictions.
- Retail Stores:Supermarket and hypermarket chains across Grand Est.
- Corporate Offices:Private sector commercial property security managers.
Government buildings dominate installed base volume; educational institutions are climbing the fastest.
Installation Type:
Environmental protection ratings and mounting flexibility determine how each category absorbs infrastructure modernization costs without triggering full system replacement.
- Outdoor:IP66-rated housings with integrated heater-blower assemblies withstand temperature cycling and precipitation exposure. Bullet camera dominance in this category reflects weather-resistant design priorities for Marseille port authority and Lyon transit authority specifications.
- Indoor:Climate-controlled environments permit lighter enclosure specifications and lower power consumption. Dome cameras concentrate here due to aesthetic discretion requirements in Parisian retail banking branches.
- Hybrid:Dual-environment deployments with adaptive housing configurations.
- Portable:Temporary installation configurations for event security and construction site monitoring.
Outdoor installations command the largest addressable base; hybrid configurations are gaining share fastest.
Connectivity:
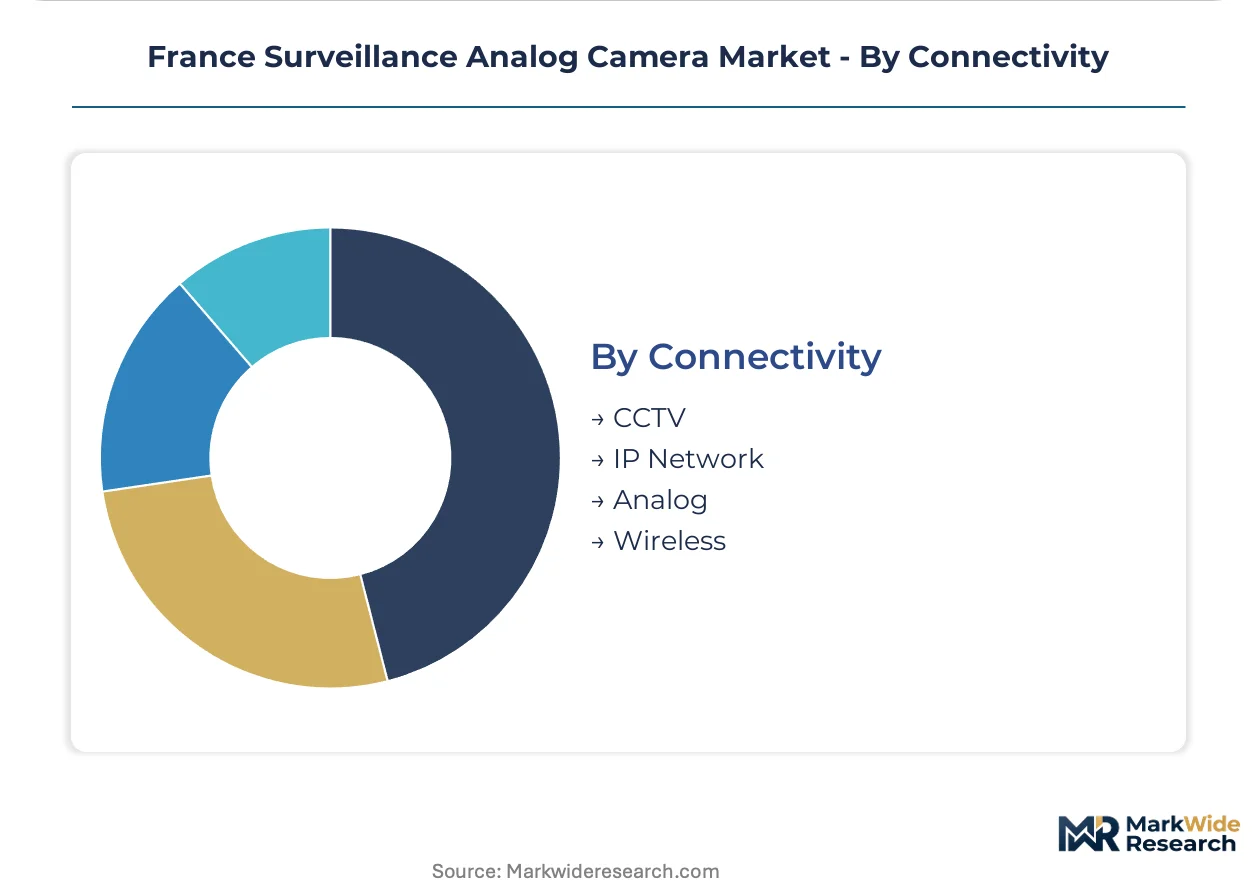
Signal transmission architecture defines the boundary between pure analog legacy systems and transitional formats that bridge coaxial infrastructure toward digital endpoints.
- CCTV:Closed-circuit coaxial transmission without network addressing remains the technical definition of analog surveillance. French municipal tender specifications in Lyon and Marseille continue referencing CCTV architecture for backward-compatible procurement.
- Analog:Baseband video signal transmission over copper coaxial cable at PAL resolution standards. Aging Île-de-France transport infrastructure maintains this connectivity type to avoid tunnel and viaduct cable replacement costs.
- IP Network:Packet-switched digital transmission with Power-over-Ethernet capability.
- Wireless:Radio-frequency transmission for cable-inaccessible deployment scenarios.
CCTV connectivity retains the dominant installed position; IP network configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's CNIL data-protection enforcement and municipal retrofit incentives are reshaping procurement patterns across sub-regional surveillance infrastructure markets. The analysis window tracks divergence between Île-de-France's aging transport networks and southern perimeter expansion projects.
Île-de-France
Paris Metro and RATP transit authorities maintain coaxial infrastructure across tunnel networks where full IP replacement costs are prohibitive. CNIL audit protocols for public-space data retention are forcing staged encoder deployments rather than immediate digital overhauls. Aging DVR compatibility requirements in Saint-Denis and Nanterre municipal buildings sustain backward-compatible tender specifications.
Auvergne-Rhône-Alpes
Lyon municipal police departments source dome cameras for indoor retail surveillance under fiscal consolidation constraints. The region's Grand Lyon Métropole security code provisions mandate automated deletion protocols that analog-native architectures struggle to satisfy. Shopping districts in Lyon 2nd and 3rd arrondissements are converting to HD-TVI formats to extend existing cable lifecycles.
Provence-Alpes-Côte d'Azur
University campuses in Aix-Marseille are expanding PTZ perimeter configurations for boundary monitoring flexibility. France's internal security code biometric-data restrictions are compressing facial-recognition hardware specifications ahead of EU AI Act implementation. Marseille port authority specifications favor bullet cameras with weather-resistant housings for outdoor transport hub coverage.
Hauts-de-France
Lille metropolitan transport operators prioritize cost-effective analog unit replacement over hybrid system investments during budget review cycles. CE marking under the EU Radio Equipment Directive filters non-compliant vendors from public building tenders. Calais port infrastructure maintains CCTV architecture to avoid cross-border cable replacement coordination with Belgian counterparts.
Nouvelle-Aquitaine
Bordeaux municipal security managers are unbundling hardware procurement from installation contracts, elevating engineering consultancy influence. GDPR biometric-data friction limits premium pricing for facial-recognition-capable hardware vendors. Large-format retail chains in the Gironde are adopting HD-CVI intermediate formats to delay full IP migration decisions.
France Surveillance Analog Camera Market Competitive Landscape
Player mix skews toward diversified security conglomerates with European certification pipelines and specialized dome/bullet fabricators with channel control in municipal segments. Market structure shows moderate concentration around vendors capable of bridging legacy analog and hybrid digital architectures. Two strategic archetypes dominate: scale-driven manufacturers with CE marking compliance infrastructure, and regional specialists with installation contractor relationships. Competitive moves center on encoder technology licensing for staged modernization and strategic partnerships with systems integrators facing coaxial technician scarcity.
Among Asia-Pacific-based technology conglomerates, Hangzhou Hikvision Digital Technology Co., Ltd. and Zhejiang Uniview Technologies Co Ltd occupy positions exemplifying scale-driven certification infrastructure. Hanwha Vision, with its Korean corporate structure, represents the diversified security archetype leveraging European regulatory pipelines. Bosch Sicherheitssysteme GmbH anchors the German-engineered tier with manufacturing presence serving French government building specifications. These three entities collectively illustrate the competitive tension between cost-efficient Asian production and compliance-heavy European public-sector access.
| Leading Market Players |
|---|
| Hanwha Vision |
| Zhejiang Uniview Technologies Co Ltd |
| Teledyne FLIR LLC |
| Honeywell International Inc |
| IDIS Ltd |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Zosi Technology Ltd. |
| Axis Communications AB |
| Bosch Sicherheitssysteme GmbH |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day lead times for CE-certified encoder modules concentrate procurement leverage among Hanwha Vision and Bosch Sicherheitssysteme GmbH, compressing margin flexibility for smaller dome and bullet fabricators serving French municipal tenders.
Pricing Analysis
Certification level under the EU Radio Equipment Directive creates the primary spread between premium and standard tiers. Project-based pricing dominates municipal procurement in Lyon and Marseille, with CE marking compliance commanding substantial premiums over non-certified alternatives. Cost compression in standard-definition PAL equipment intensifies as HD-TVI and HD-CVI formats displace legacy 720x576 inventory. Educational institutions exhibit highest price sensitivity due to perimeter expansion budgets, while Île-de-France transport authorities prioritize backward compatibility over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes strain inbound logistics for Korean and Chinese camera manufacturers serving French distributors. Component sourcing draws from Taiwan for image sensors, South Korea for DSP chipsets, and Germany for precision optics. Single-source vulnerability concentrates in PAL-standard signal processors as training programs pivot toward IP networking curricula. Distribution runs through specialized security systems integrators with coaxial technician expertise rather than direct vendor-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's surveillance analog camera market sits in early-cycle expansion as HD-over-coax adoption accelerates retrofit demand without triggering immediate full IP replacement decisions.
For Market Incumbents: Secure encoder technology licensing partnerships to bridge legacy DVR compatibility toward hybrid architectures. Invest in CE marking compliance infrastructure ahead of EU AI Act biometric identification restrictions. Channel control through systems integrator relationships defends against IP camera substitution in greenfield municipal contracts. For New Entrants and Emerging Players: Post-installation technical support gaps in Provence-Alpes-Côte d'Azur university campuses offer white-space entry points. Target educational institution perimeter expansion with PTZ camera configurations bundled with CNIL audit documentation services. Partner with regional engineering consultancies to bypass established vendor-distributor relationships in Marseille municipal tenders. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because CE marking barriers filter non-compliant competitors while coaxial technician scarcity elevates specialized contractor value. Acquisition targets should demonstrate hybrid encoder integration capabilities and established French public-sector tender access. Monitor EU AI Act implementation timelines as the critical inflection signal for analog-to-digital migration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Encoder Technology Licensing | Enables staged infrastructure modernization without immediate full replacement capex for Île-de-France transport authorities. |
| CE Marking Certification Investment | Maintains public-sector tender eligibility under EU Radio Equipment Directive requirements across French government buildings. |
| Systems Integrator Partnership | Addresses coaxial technician scarcity while capturing unbundled procurement contracts in Marseille municipal security. |
| Hybrid Architecture Product Launch | Extends existing coaxial cable lifecycles for Lyon retail districts converting from standard-definition PAL formats. |
| CNIL Compliance Service Bundling | Differentiates offerings for educational institutions facing automated deletion protocol mandates under France's internal security code. |
Research Methodology
A spread of perspectives from municipal procurement officers, security systems integrators, CNIL compliance consultants, and coaxial installation contractors converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation through EU Radio Equipment Directive certification databases, French public tender documentation, and customs records for surveillance equipment imports. Bottom-up unit demand estimates triangulated against top-down infrastructure replacement cycle analysis across the analysis window.
Segmentation dimensions modeled include product type, end user, installation environment, and connectivity architecture across the projection horizon. CAGRs derived from replacement rate assumptions for aging coaxial networks, regulatory compliance timelines, and municipal budget cycle patterns. Industry-specific forecast inputs incorporated CNIL audit frequency trends and EU AI Act implementation trajectory assessments.
Material uncertainties — regulatory divergence between national security exemptions and data-protection mandates, copper cable input volatility, and IP camera substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about infrastructure modernization pacing and certification timeline adherence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
China Video Surveillance Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
North America Pedestrian Detection Systems Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Rugged Thermal Cameras Market
Video Surveillance Systems
Europe Video Surveillance Systems Market