
 Europe Surveillance Camera Market | 2026-2036
Europe Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Surveillance Camera Market Insights
A shift from single-source hardware contracts toward multi-source ecosystem partnerships is recalibrating procurement strategies across European security integrators. Axis Communications AB leverages its open-platform architecture to sustain developer loyalty across VMS partners. Bosch Security Systems GmbH anchors its competitive stance through in-house sensor manufacturing and German engineering credentials. Hanwha Vision Co Ltd competes aggressively on price-performance ratios in the mid-tier commercial segment.
Europe surveillance cameras encompass fixed and pan-tilt-zoom imaging devices capturing visible-light or thermal radiation for automated scene analysis, typically operating across IP networks with Power-over-Ethernet supply and ONVIF protocol interoperability for security command centers. IP Cameras now dominate volume shipments as analog infrastructure reaches end-of-life replacement cycles across legacy municipal installations. AI Systems within the technology dimension command premium positioning as edge-based analytics reduce bandwidth loads and enable real-time threat classification without centralized server dependency. The Retail end user segment presents concentrated margin pools where loss prevention teams demand integrated video analytics tied to point-of-sale exception reporting.
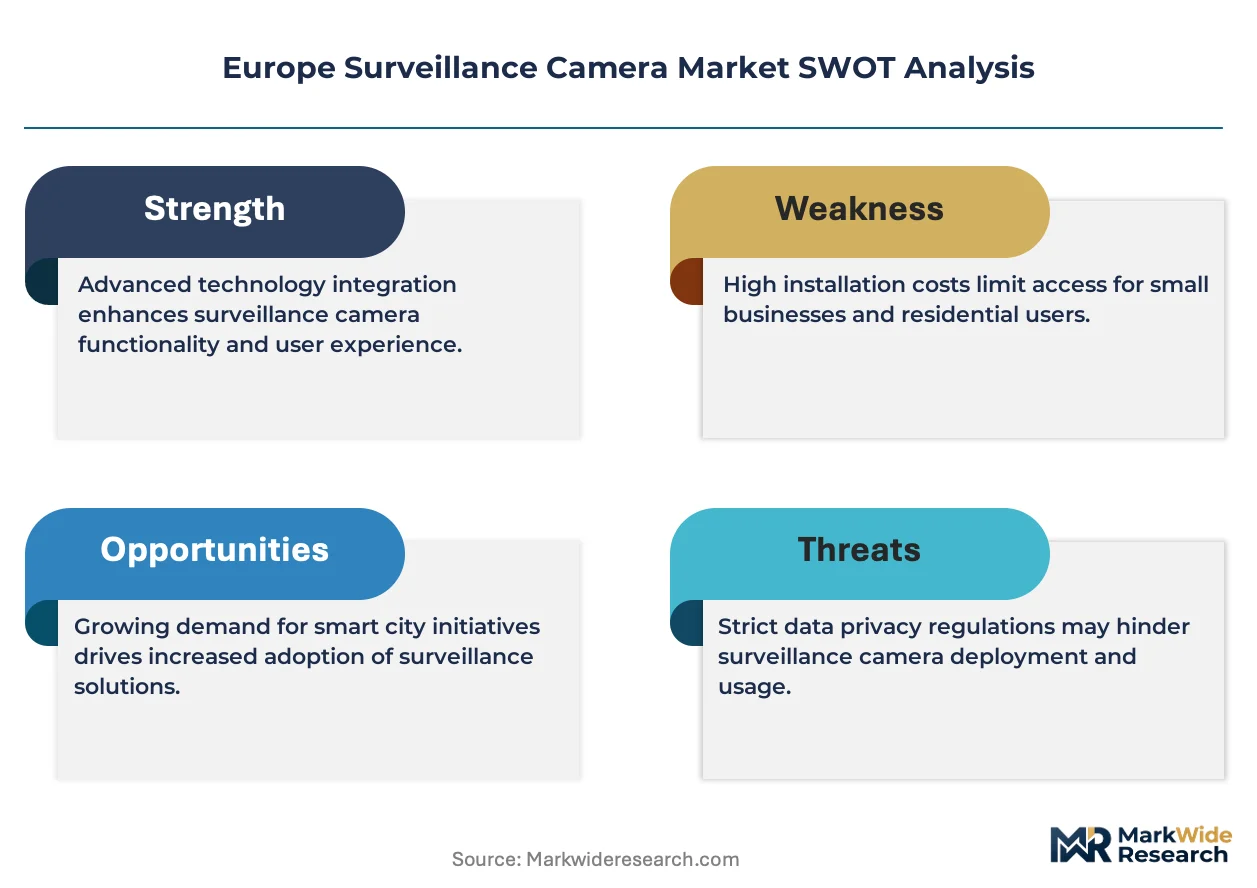
GDPR constraints from European data protection authorities and the EU AI Act's biometric surveillance prohibitions are tightening product design specifications and limiting facial recognition deployment in public spaces. CE marking under the EU's Radio Equipment Directive and ETSI cybersecurity standards govern network resilience requirements for connected camera deployments. Stakeholders must monitor evolving national implementation timelines for AI Act enforcement thresholds to calibrate R&D investment between analytics capability and regulatory compliance boundaries.
Market Dynamics
The EU AI Act's risk-based classification system is forcing camera manufacturers to bifurcate R&D roadmaps between compliant non-biometric products and high-risk biometric systems requiring conformity assessments. This regulatory pressure is compressing product development cycles while expanding compliance budgets across the value chain.
Growth Catalysts
- Smart city infrastructure mandates:Germany's municipal digitalization programs are accelerating procurement of networked video systems for urban traffic management and public safety monitoring.
- GDPR-compliant edge analytics:On-device processing architectures enable real-time threat detection without transmitting personal data to centralized servers, satisfying data minimization requirements.
- Rail operator safety investments:France's SNCF and peer operators across Spain and Italy are deploying IP-based platform monitoring to reduce passenger incidents and liability exposure.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication depends on TSMC and Samsung foundry capacity in Taiwan and South Korea, creating geographic vulnerability for European integrators.
- GDPR enforcement escalation:National data protection authorities in France, Germany, and Italy are imposing seven-figure fines for unlawful biometric data processing, chilling public sector deployment.
- Cloud storage substitution:Enterprise IT departments are evaluating software-defined surveillance platforms that displace dedicated NVR hardware with hyperscaler infrastructure.
Strategic Opportunities
- Eastern European municipal modernization:Poland, Romania, and Czech Republic lag Western Europe in analog-to-IP replacement cycles, creating volume opportunities for mid-tier equipment.
- EU Cybersecurity Act certification:The emerging European cybersecurity certification scheme for ICT products will create preferred vendor status for early-compliant manufacturers.
- Retail loss prevention convergence:Integration of video analytics with POS exception reporting and inventory management systems is opening unified platform contracts.
Industry Challenges
- Edge AI engineering scarcity:Firmware development for neural network inference on resource-constrained camera SoCs requires specialized embedded systems talent that European vendors struggle to recruit.
- Legacy analog integration friction:Hybrid deployments combining existing coaxial infrastructure with IP endpoints demand complex signal conversion and VMS configuration, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Surveillance Camera Market |
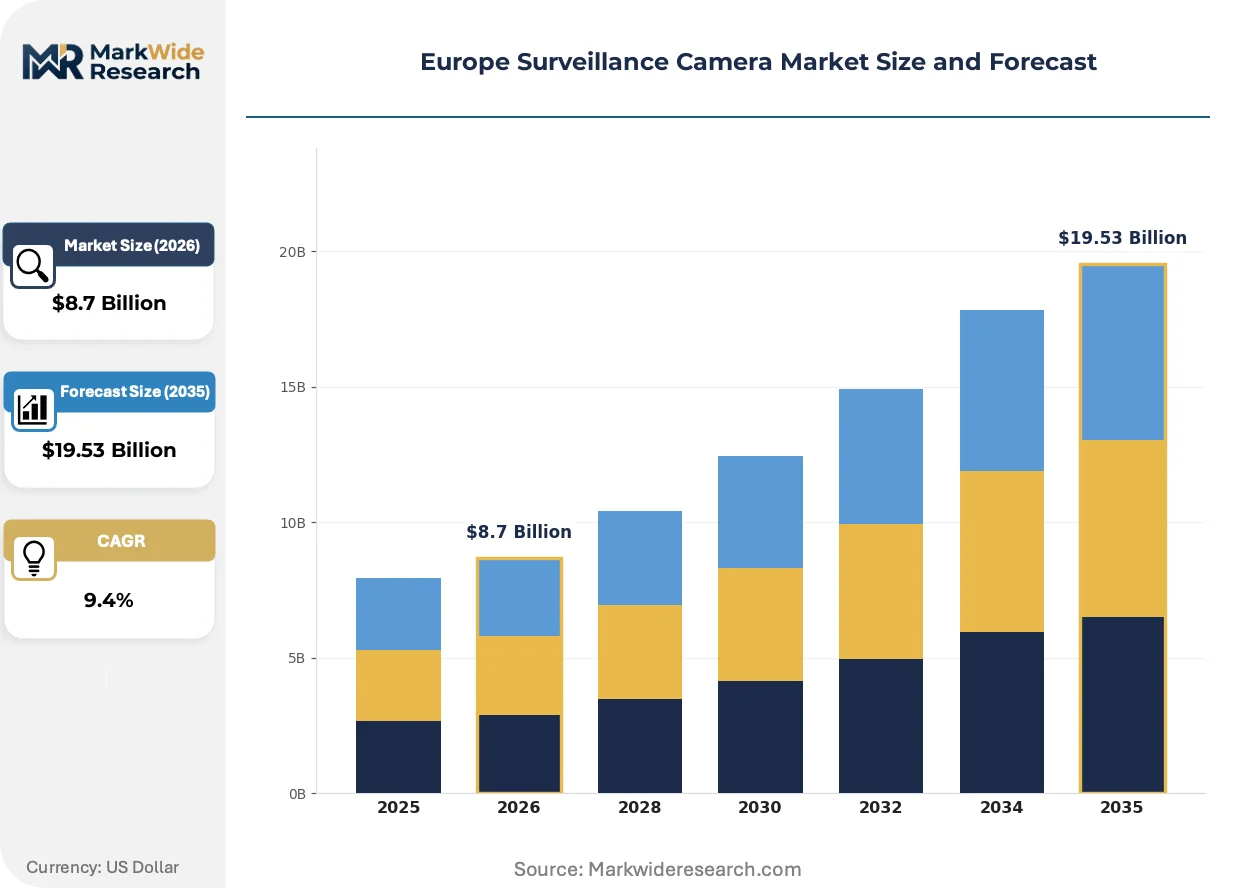
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Cameras, IP Cameras, PTZ Cameras, Thermal Cameras End User: Retail, Transportation, Government, Residential Technology: Digital Video Recorders, Cloud-Based Solutions, Video Analytics, AI Systems Application: Security Surveillance, Traffic Monitoring, Event Management, Public Safety |
| Companies Covered | Mobotix AG, Hanwha Vision Co Ltd, Bosch Security Systems GmbH, Milestone Systems, Eagle Eye Networks, Axis Communications AB, Dahua Technology, Vivotek Inc, Hangzhou Hikvision Digital Technology Co Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Surveillance Camera Market Trends and Innovations
Edge-based intelligence is redistributing computational workloads from centralized servers to camera endpoints, altering hardware specifications and software licensing models simultaneously. This architectural shift is compressing bandwidth requirements while enabling sub-second response times for critical security events.
Multi-spectral imaging fusion is automating detection accuracy across challenging illumination conditions. Transportation hubs in France and Germany are deploying visible-light and thermal sensor combinations for platform monitoring. The technology is automating classification of genuine threats from environmental noise, reducing false alarm rates that previously burdened security operations centers.
The EU AI Act's prohibition on real-time remote biometric identification in publicly accessible spaces is redirecting manufacturer roadmaps toward attribute-based analytics. Product teams are prioritizing gait analysis, crowd density estimation, and abandoned object detection over facial recognition. German engineering departments are accelerating development of privacy-preserving alternatives to maintain market access.
Systems integration contracts are displacing standalone hardware purchases as the dominant procurement mode. French retail chains and Belgian logistics operators are demanding bundled installation, configuration, and multi-year maintenance from single vendors. This consolidation is squeezing pure-play equipment distributors while rewarding full-service security integrators with recurring revenue streams.
Europe Surveillance Camera Market Segmentation
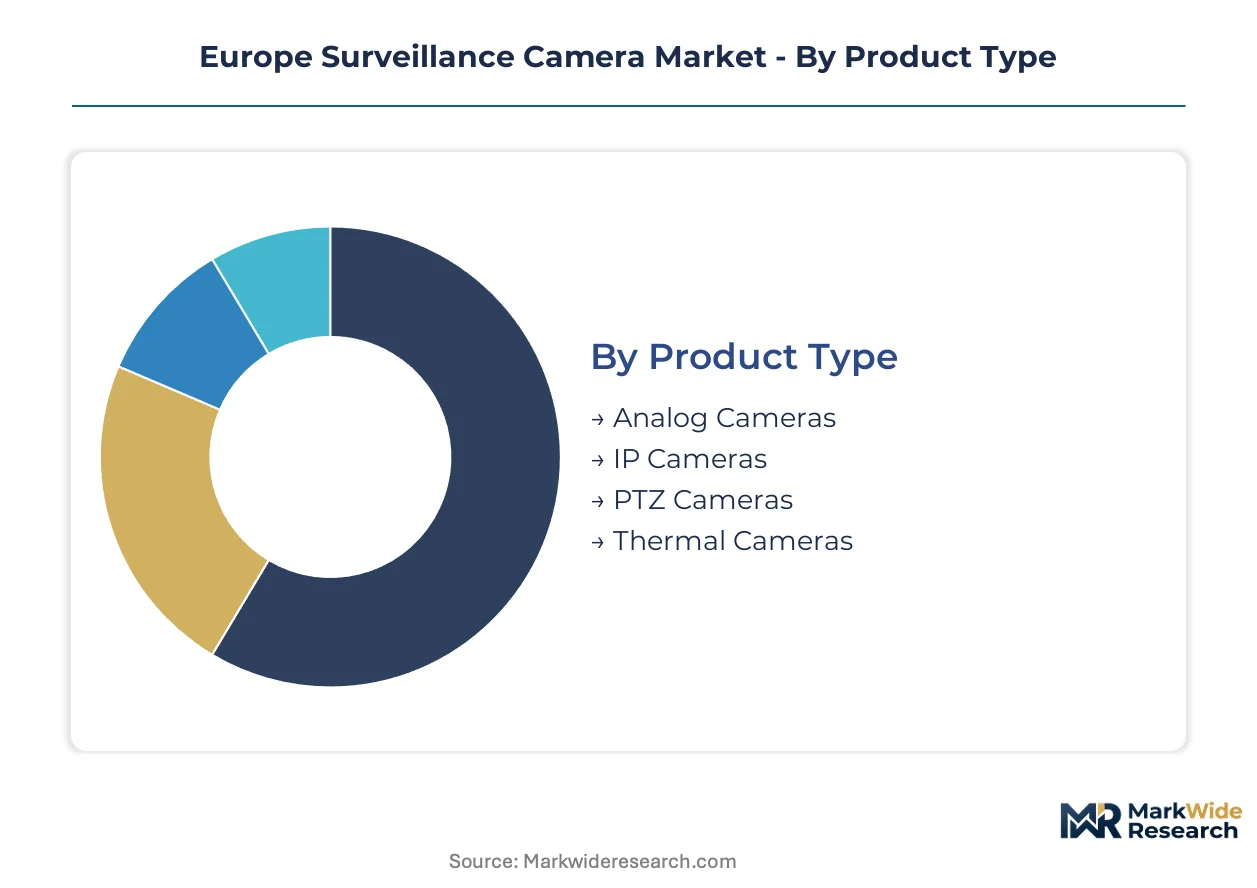
Segmentation in the Europe surveillance camera market reveals how procurement priorities diverge across installation contexts. Municipal buyers prioritize network resilience and regulatory compliance, while commercial operators weigh integration depth against total cost of ownership.
Product Type:
Standalone imaging hardware dominates legacy refresh cycles, whereas embedded smart cameras are capturing new-build specifications across EU infrastructure programs.
- IP Cameras:Network-addressable devices transmit compressed video streams over Ethernet infrastructure with ONVIF protocol interoperability. German municipal digitalization programs and French rail operator safety mandates are concentrating procurement volume here, driven by Power-over-Ethernet deployment simplicity and centralized VMS manageability. GDPR-compliant edge architectures further accelerate analog-to-IP replacement timelines.
- Thermal Cameras:Uncooled microbolometer sensors detect infrared radiation independent of visible illumination, enabling detection through obscurants and absolute darkness. French transportation hubs and German logistics corridors deploy these for perimeter breach detection and platform safety monitoring, where lighting infrastructure proves impractical or passenger privacy concerns restrict visible-light capture.
- Analog Cameras:Coaxial-cable devices with CVBS signal output persist in Eastern European municipal installations where complete infrastructure replacement exceeds budget cycles.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with programmable preset positions serve active monitoring roles in large-area coverage applications.
Volume placements concentrate in IP Cameras; the faster expansion belongs to Thermal Cameras.
End User:
Cost-tier stratification separates high-specification government tenders from price-sensitive residential deployments, with commercial segments occupying intermediate positions on capability-versus-budget tradeoffs.
- Government:National and municipal security agencies specify hardened enclosures, cybersecurity certification, and multi-year maintenance bundling. GDPR enforcement escalation and EU AI Act biometric prohibitions are tightening technical requirements while extending procurement cycles across French, German, and Italian public authorities.
- Transportation:Rail operators, airports, and port authorities demand mission-critical availability with sub-second failover redundancy. SNCF platform monitoring deployments and Spanish rail network expansions are concentrating demand for multi-spectral imaging fusion and real-time crowd analytics.
- Retail:Loss prevention teams seek video-to-POS integration with exception-based alerting for shrinkage reduction.
- Residential:Smart home integrators and consumer direct channels emphasize app-based remote access with subscription cloud storage.
Government contracts anchor average selling prices; Retail is gaining share fastest through unified platform convergence.
Technology:
Maturity gradients separate established recording infrastructure from emerging analytics layers, with AI capability now determining competitive differentiation in premium tenders.
- AI Systems:Edge-based neural network inference enables real-time threat classification without centralized server dependency. German engineering departments are prioritizing privacy-preserving alternatives—gait analysis, crowd density estimation, abandoned object detection—to maintain market access under EU AI Act biometric prohibitions.
- Video Analytics:Rules-based and machine-learning algorithms automate scene interpretation for operator workload reduction. French retail chains and Belgian logistics operators are demanding bundled analytics configuration with multi-year algorithm refinement services.
- Cloud-Based Solutions:Hyperscaler-hosted storage and processing displace on-premise NVR hardware in enterprise IT evaluations.
- Digital Video Recorders:Local recording appliances with RAID redundancy persist in bandwidth-constrained or data-sovereignty-sensitive deployments.
Digital Video Recorders retain installed base dominance; AI Systems are climbing the fastest on R&D investment intensity.
Application:
Customer type segmentation maps to distinct operational workflows, from reactive incident response through predictive risk management.
- Security Surveillance:Perimeter protection, intrusion detection, and access control monitoring constitute the foundational use case. German municipal programs and French commercial property managers are standardizing on IP platforms with centralized command center integration.
- Traffic Monitoring:Automated license plate recognition, incident detection, and congestion analytics support urban mobility management. Italian and Spanish smart city infrastructure investments are expanding camera networks for real-time signal optimization and enforcement automation.
- Public Safety:Crowd management, emergency response coordination, and critical infrastructure protection serve government agency mandates.
- Event Management:Temporary deployment for sporting venues, concerts, and political gatherings emphasizes rapid installation and mobile command post connectivity.
Security Surveillance commands the largest installed footprint; Traffic Monitoring shows the steepest expansion trajectory on smart city funding allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon image sensors from TSMC foundries in Taiwan and Samsung fabs in South Korea supply the optical cores anchoring European camera assembly. Component availability shapes deployment timelines across municipal procurement cycles.
Germany
Municipal digitalization programs in Berlin and Hamburg accelerate networked video procurement for urban traffic management. The EU AI Act's biometric prohibitions force engineering departments toward gait analysis and crowd density estimation. Bavarian manufacturing clusters around Munich supply precision-engineered sensor housings for rail operator specifications.
France
SNCF platform safety mandates concentrate demand for multi-spectral imaging fusion across Paris Gare du Nord and Lyon Part-Dieu terminals. CNIL enforcement actions impose seven-figure penalties for unlawful facial recognition processing. The Île-de-France region hosts system integrators bundling installation with multi-year maintenance contracts.
United Kingdom
Transport for London's station modernization drives IP camera replacement of legacy analog infrastructure. The Information Commissioner's Office scrutinizes biometric data processing under UK GDPR derivative rules. Greater Manchester's smart city pilot deploys edge-based analytics for congestion monitoring without centralized personal data transmission.
Italy
Autostrade per l'Italia and municipal operators in Milan expand camera networks for automated license plate recognition and incident detection. CE marking under the Radio Equipment Directive governs network resilience for connected deployments. The Veneto region concentrates mid-tier equipment distributors serving Eastern European export channels.
Poland
Warsaw municipal authorities lag Western European analog-to-IP replacement cycles, creating volume opportunities for cost-optimized equipment. National data protection authority guidance aligns with EU AI Act implementation timelines. The Silesian industrial corridor deploys thermal cameras for perimeter protection of logistics facilities.
Europe Surveillance Camera Market Competitive Landscape
Global majors compete with regional champions across engineering credentials and compliance expertise. The vendor base separates into three tiers: premium German engineering houses, mid-tier Asian price-performance specialists, and cloud-native software platforms. Strategic archetypes include open-platform ecosystem orchestrators, vertically integrated sensor manufacturers, and subscription-based video-management-as-a-service providers. Dominant competitive moves center on multi-source ecosystem partnerships displacing single-source hardware contracts, and early compliance certification under emerging EU cybersecurity schemes.
Among Germany-based engineering houses, Bosch Security Systems GmbH anchors the premium tier through in-house sensor manufacturing credentials. Axis Communications AB exemplifies the open-platform ecosystem model sustaining developer loyalty across video management software partners. Hanwha Vision Co Ltd occupies the mid-tier commercial segment competing aggressively on price-performance ratios. These three archetypes represent the structural segmentation governing procurement decisions across European security integrators.
| Leading Market Players |
|---|
| Mobotix AG |
| Hanwha Vision Co Ltd |
| Bosch Security Systems GmbH |
| Milestone Systems |
| Eagle Eye Networks |
| Axis Communications AB |
| Dahua Technology |
| Vivotek Inc |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Edge-based AI processing architectures are redistributing computational workloads from centralized servers to camera endpoints, simultaneously compressing hardware bill-of-materials costs and concentrating premium pricing power among firmware-capable vendors. This architectural shift rewards manufacturers with embedded systems engineering depth while eroding margins for pure-play hardware assemblers.
Pricing Analysis
Warranty and multi-year maintenance bundling separate premium German engineering houses from unbundled mid-tier Asian competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU Cybersecurity Act frameworks and CE marking tiers. Cost compression in the economy tier is intensifying because Eastern European municipal buyers prioritize per-unit acquisition costs over lifecycle service contracts. Retail loss prevention teams exhibit lowest price sensitivity due to unified platform convergence with POS integration requirements.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany operate hub-and-spoke patterns serving security integrators across Western and Eastern Europe. Image sensor fabrication draws from TSMC foundries in Taiwan and Samsung fabs in South Korea, creating geographic concentration risk for European assembly operations. Supply chain vulnerability centers on single-source dependency for advanced CMOS sensors and memory components. Distribution runs through authorized dealer networks and direct enterprise contracts, with cloud-native platforms bypassing traditional hardware distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-capable full-service integrators, with EU AI Act enforcement timelines forcing weaker pure-play distributors toward exit or acquisition.
For Market Incumbents: Cement market position through early EU Cybersecurity Act certification investment and backward integration into edge AI firmware development. Cloud-native software platforms threaten hardware-centric revenue streams; counter through multi-year maintenance bundling and VMS ecosystem lock-in. Prioritize German municipal and French rail operator relationships where procurement cycles favor incumbents with established compliance track records. For New Entrants and Emerging Players: Begin with Eastern European municipal modernization opportunities in Poland and Romania where analog-to-IP replacement cycles lag Western Europe. Mid-tier commercial segments present lower certification barriers than government tenders. Pursue white-label partnerships with established system integrators rather than direct brand building, leveraging price-performance advantages against premium incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to full-service security integrators seeking geographic or technology capability expansion. Five-to-ten year viability favors vendors with edge AI engineering teams and existing EU regulatory compliance infrastructure. Monitor CNIL and German data protection authority enforcement patterns as inflection indicators for biometric analytics market access restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| EU Cybersecurity Act Certification | Early compliance creates preferred vendor status for German municipal tenders. |
| Edge AI Firmware Development | In-house neural network inference capability reduces dependency on centralized server architectures. |
| Multi-Source Ecosystem Partnerships | Open-platform VMS integration displaces single-source hardware procurement across French integrators. |
| Eastern European Distribution Expansion | Polish and Romanian channel partnerships capture analog-to-IP replacement volume. |
| Privacy-Preserving Analytics R&D | Gait analysis and crowd density estimation maintain market access under EU AI Act biometric prohibitions. |
Research Methodology
Trade association filings, customs import records, and regulatory enforcement databases formed the secondary backbone, supplemented by primary interviews with municipal procurement officers, security systems integrators, VMS platform engineers, and data protection compliance consultants. Bottom-up and top-down triangulation validated shipment estimates against public sector budget disclosures and enterprise IT capex surveys.
Analytical lens combined bottom-up channel checks with top-down macroeconomic scaling across the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, technology layer, and application context, with regional regulatory clusters treated as distinct adoption envelopes. CAGRs were derived from curve-fitting historical replacement cycles against smart city infrastructure funding allocations and EU AI Act implementation timelines.
Underlying measurement precision varies by segment; government and transportation verticals carry tighter precision than residential channels due to public procurement transparency requirements. Forecasts reflect assumptions regarding semiconductor supply normalization and EU member state enforcement harmonization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
Farm Video Surveillance System Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Commercial Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
Security Camera Software Market