
 Smart Outdoor Cameras Market | 2026-2036
Smart Outdoor Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Outdoor Cameras Market Insights
CE marking under the EU Radio Equipment Directive is bifurcating the competitive landscape between vendors with in-house compliance labs and those dependent on third-party certification. Hangzhou Hikvision Digital Technology leverages its integrated manufacturing footprint to accelerate testing cycles and reduce time-to-market for European shipments. Amazon Ring sustains brand dominance through deep channel control across North American retail and direct-to-consumer platforms.
Smart outdoor cameras are weather-resistant video surveillance devices engineered with IP65+ ingress protection, infrared night vision, and edge-based AI inference for real-time motion classification and facial recognition. These systems serve commercial and residential end users by delivering autonomous perimeter monitoring with cloud-native evidence management. Bullet cameras dominate unit shipments for perimeter hardening applications, while solar-powered installation types represent the fastest-expanding configuration as remote-site deployments reduce trenching and cabling costs. PoE segments anchor margin pools in enterprise and government verticals where centralized power and data integration justify premium hardware spend.
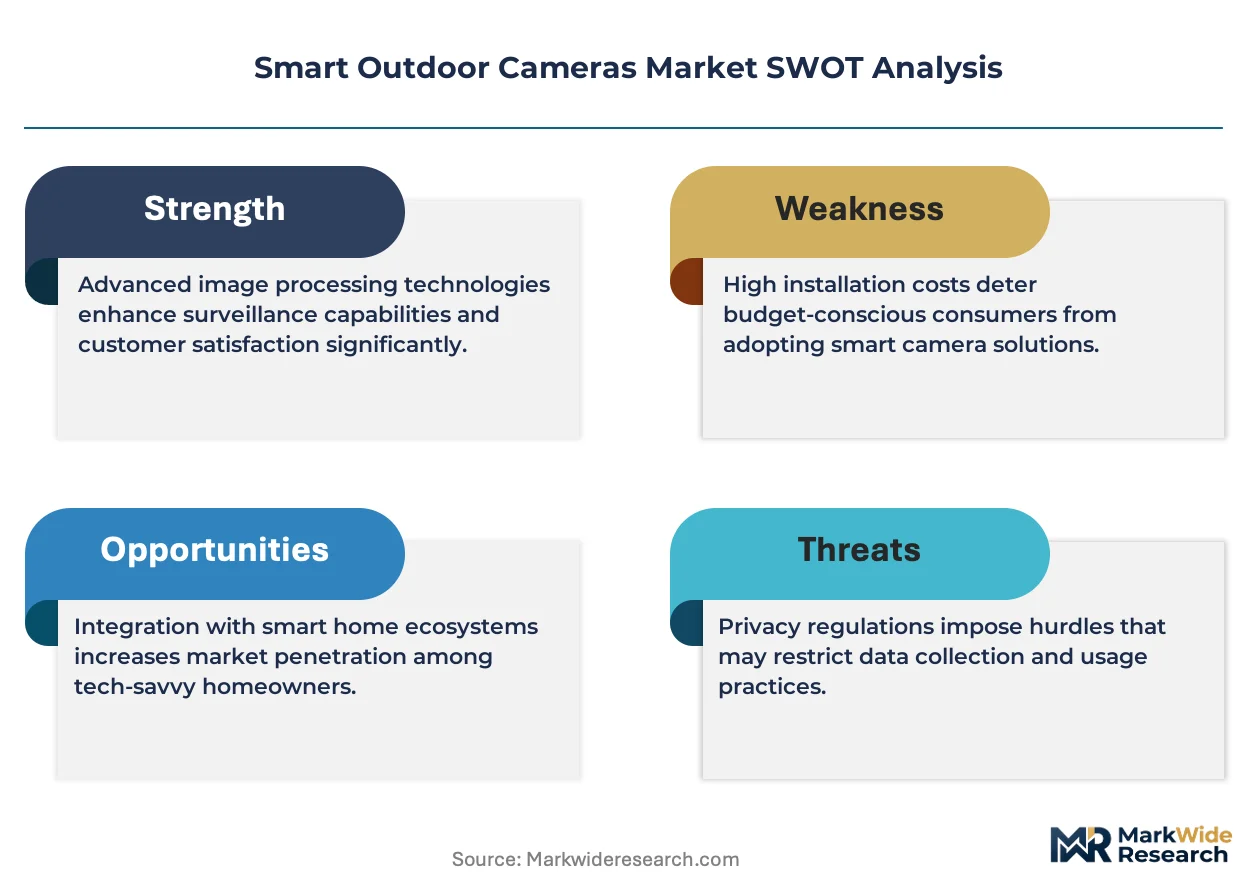
FCC Part 15 emissions rules govern radio-frequency authorization for Wi-Fi and cellular connectivity modules in the United States, while GDPR and the EU AI Act impose data residency and algorithmic transparency obligations on facial recognition features sold across European member states. Product liability exposure rises where edge AI generates false positives triggering law enforcement dispatch. Stakeholders must monitor evolving biometric consent requirements and battery chemistry regulations as solar and wireless configurations expand deployment into environmentally sensitive jurisdictions.
Market Dynamics
Edge-based AI inference is compressing hardware refresh cycles as on-device processing reduces cloud dependency and latency for real-time threat classification. FCC Part 15 emissions testing and EU cybersecurity certification are extending product development timelines, forcing vendors to front-load compliance investment.
Growth Catalysts
- EU AI Act facial recognition rules:Algorithmic transparency mandates are creating tiered product lines where vendors with pre-certified inference engines capture premium positioning in European member states.
- Remote-site solar deployments:Trenching cost avoidance is accelerating adoption of solar-powered configurations in agricultural perimeter monitoring and off-grid utility substations.
- PoE integration in enterprise verticals:Centralized power and data infrastructure is anchoring margin pools in government and commercial installations where cable consolidation justifies hardware premiums.
Market Restraints
- Lithium battery chemistry regulations:UN 38.3 transportation testing and emerging state-level disposal mandates are inflating logistics costs for solar and wireless configurations.
- Image sensor supply concentration:CMOS sensor fabrication clusters in Taiwan and South Korea create single-source vulnerability for mid-tier vendors lacking multi-year foundry contracts.
- Wi-Fi spectrum congestion:2.4 GHz interference density in urban residential deployments is degrading real-time streaming reliability and driving support cost inflation.
Strategic Opportunities
- India smart city infrastructure:Municipal surveillance tenders under the Ministry of Housing and Urban Affairs are creating volume pipelines for weather-hardened bullet cameras with localized data residency.
- Insurance-premium-linked installations:Homeowners policy discounts for AI-verified perimeter monitoring are converting price-sensitive residential buyers in United States coastal markets.
- 5G RedCap module convergence:Reduced-capability cellular radios are enabling battery-optimized cellular backup in hybrid connectivity cameras for rural commercial sites.
Industry Challenges
- Edge AI firmware validation:False positive rates in motion classification algorithms trigger liability exposure when law enforcement dispatch results from erroneous alerts.
- GDPR biometric consent workflows:Facial recognition feature deployment requires granular user opt-in interfaces that fragment product roadmaps across EU member state interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Outdoor Cameras Market |
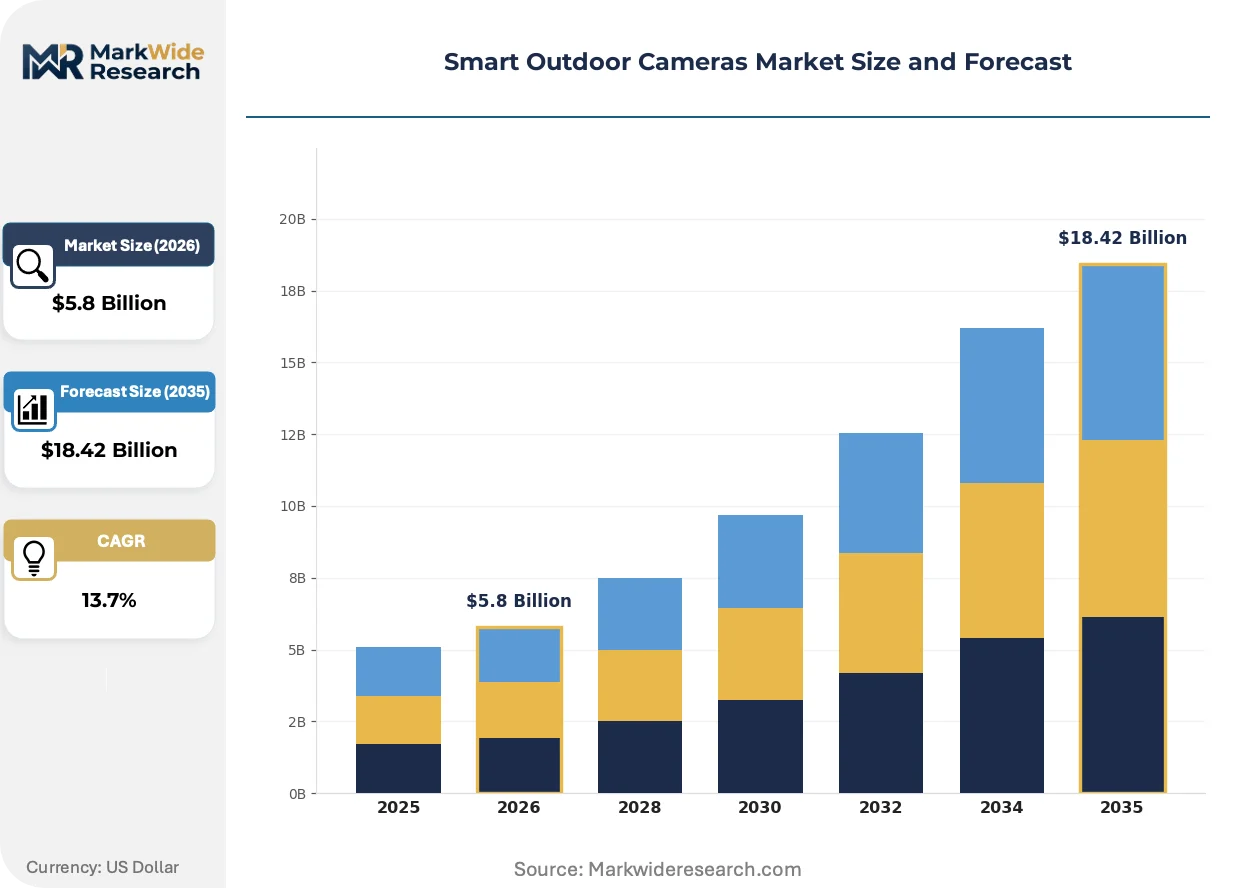
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $18.42 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bullet Cameras, Dome Cameras, PTZ Cameras, Hidden Cameras Installation Type: Wired, Wireless, PoE, Solar Powered End User: Residential, Commercial, Government, Industrial Connectivity Technology: Wi-Fi, Ethernet, Cellular, Bluetooth |
| Companies Covered | Hangzhou Hikvision Digital Technology, Amazon Ring, Google Nest, Arlo Technologies, SimpliSafe, ADT, Wyze Lab, Eufy (Anker Innovations), TP-Link, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Outdoor Cameras Market Trends and Innovations
Computational photography and on-device neural processing are collapsing the performance gap between consumer and professional-grade surveillance hardware. Vendors are reconfiguring R&D allocation toward inference optimization rather than sensor specification.
On-device transformer-based motion models are supplanting traditional convolutional neural networks for object classification. Enterprise security teams in logistics and critical infrastructure are piloting these architectures for reduced cloud egress costs. The shift is compressing subscription revenue dependency and forcing vendors toward hardware-margin recovery models.
GDPR Article 35 data protection impact assessments are mandating algorithmic documentation for facial recognition features sold across European member states. Vendors must maintain audit trails for training data provenance and model versioning. Product liability insurers are requiring DPIA completion certificates before underwriting biometric-enabled deployments in Germany and France.
Subscription unbundling is fragmenting the residential buyer journey. Hardware-only purchases through big-box retail are displacing bundled cloud storage contracts in United States price-sensitive segments. Vendors are responding with tiered firmware feature gates that reserve AI classification for recurring payment activation.
Smart Outdoor Cameras Market Segmentation
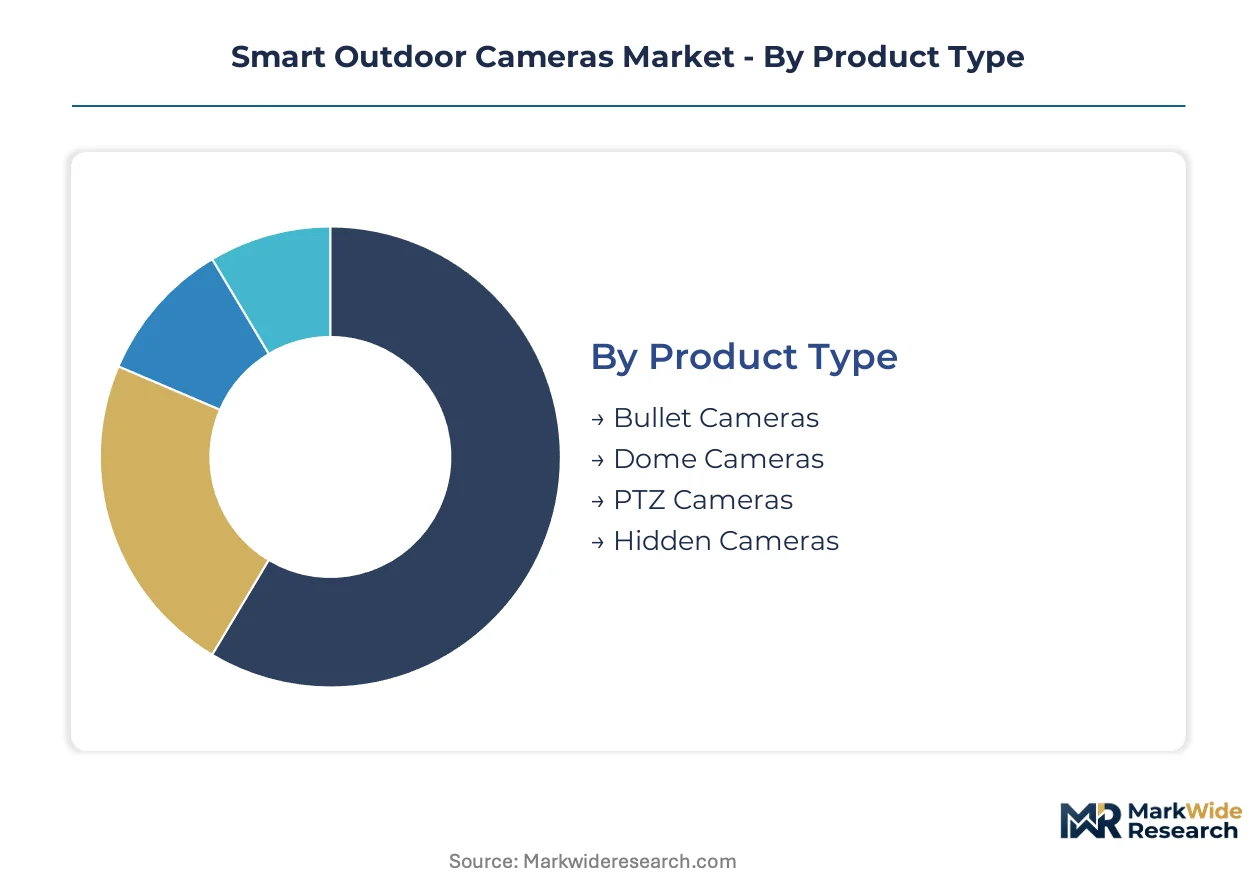
Segmentation in smart outdoor cameras reveals how hardware specifications, infrastructure requirements, and end-use risk profiles create divergent margin structures. Vendors configure product lines around installation constraints and connectivity availability rather than pursuing universal designs.
Product Type:
Margin pools concentrate in form factors that balance weather hardening with optical performance for perimeter applications.
- Bullet Cameras:Cylindrical housings with IP65+ seals and varifocal lenses deliver directional surveillance for fence-line monitoring. Demand clusters in United States residential perimeter hardening where visible deterrence shapes purchase decisions.
- Dome Cameras:Vandal-resistant hemispherical enclosures with 360-degree coverage suit commercial parking structures and transit hubs. European retail and logistics facilities favor these for discrete positioning and tamper-proofing.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms enable operator-controlled tracking across wide areas.
- Hidden Cameras:Disguised housings blend into outdoor fixtures for covert surveillance applications.
The dominant share belongs to Bullet Cameras, while Dome Cameras is closing the gap fastest.
Installation Type:
Cost tier stratification separates premium integrated systems from budget retrofit configurations.
- PoE:Power-over-Ethernet combines data and electrical delivery through single cable runs, reducing trenching labor in enterprise deployments. Government and critical infrastructure sites in Germany and France specify PoE for centralized management and UPS backup integration.
- Solar Powered:Photovoltaic panels with lithium battery storage eliminate grid dependency for remote agricultural and utility substation monitoring. Trenching cost avoidance accelerates adoption across Australian cattle stations and Texas oilfield perimeters.
- Wired:Traditional AC-powered installations with coaxial or Ethernet backhaul anchor budget residential retrofits.
- Wireless:Battery-operated units with Wi-Fi or cellular modems suit rental properties and temporary construction site monitoring.
PoE commands the revenue concentration, yet Solar Powered is expanding most quickly.
End User:
Application urgency drives pricing power across risk-tolerance gradients.
- Government:Municipal and federal procurements mandate NDAA-compliant supply chains and FedRAMP-authorized cloud storage. United States smart city infrastructure programs and Indian Ministry of Housing and Urban Affairs tenders create volume pipelines for hardened bullet configurations.
- Commercial:Logistics warehouses, retail chains, and hospitality groups prioritize AI-verified perimeter monitoring for insurance premium reductions. Coastal United States markets convert fastest where hurricane exposure elevates risk transfer incentives.
- Residential:Homeowner associations and individual properties seek subscription-linked cloud evidence management.
- Industrial:Manufacturing plants and energy facilities require explosion-rated housings and integration with SCADA systems.
Government retains the largest committed spend, while Commercial is gaining share fastest.
Connectivity Technology:
Customer type and site infrastructure determine module selection and recurring revenue potential.
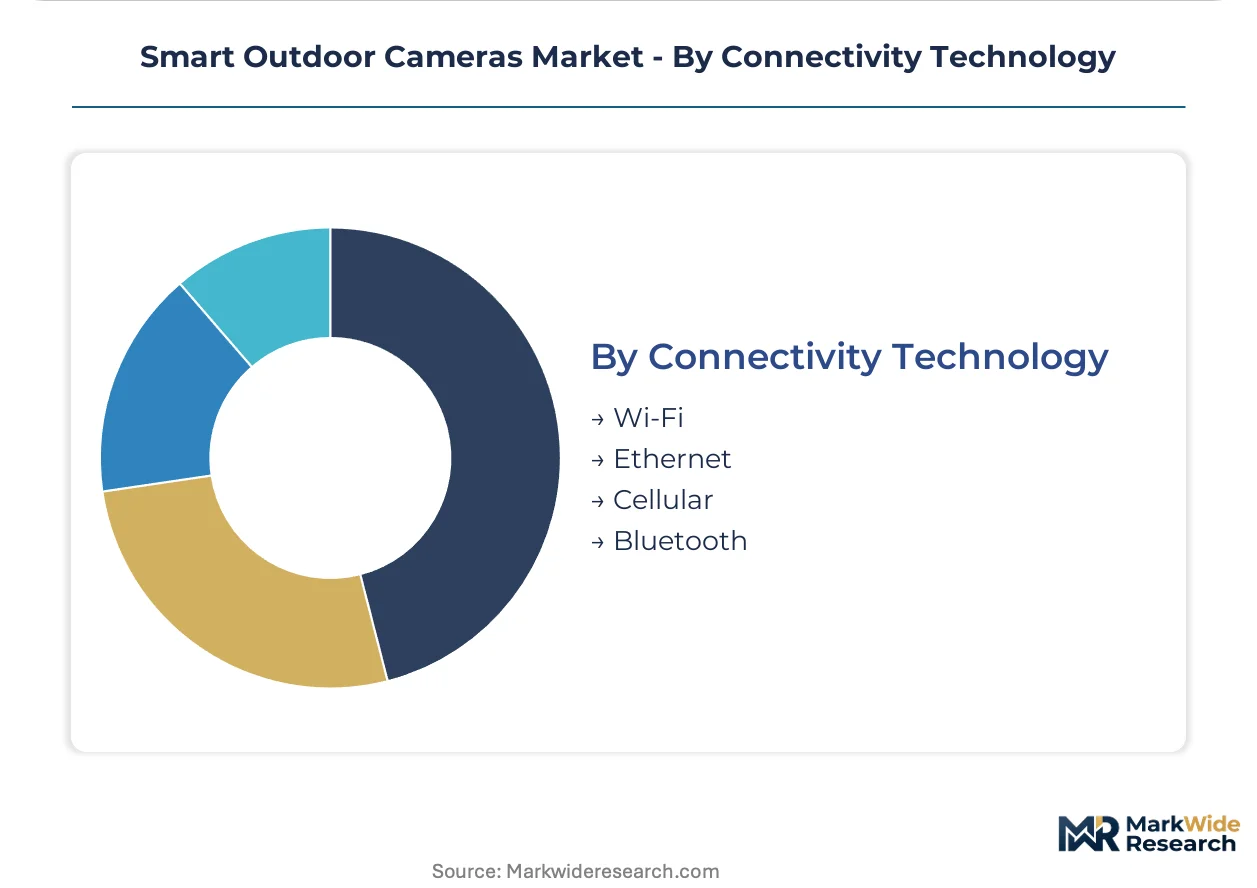
- Wi-Fi:2.4 GHz and 5 GHz radios dominate residential installations where broadband backhaul exists. Spectrum congestion in urban United States deployments degrades streaming reliability and inflates support costs for vendors.
- Cellular:LTE and emerging 5G RedCap modules enable battery-optimized backup for rural commercial sites lacking fixed infrastructure. Agricultural cooperatives in Brazil and mining camps in Canada specify cellular for off-grid autonomy.
- Ethernet:Hardwired connections anchor enterprise and government installations requiring guaranteed bandwidth.
- Bluetooth:Short-range pairing facilitates initial device provisioning and local sensor integration.
Wi-Fi holds the volume leadership, though Cellular is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 emissions rules and EU cybersecurity certification frameworks are redirecting vendor investment toward compliance-ready product architectures. Smart outdoor camera deployment patterns now track closely with regulatory maturity rather than pure demand density.
United States
Homeowner insurance premium discounts for AI-verified perimeter monitoring are converting price-sensitive buyers in Florida and Texas coastal markets. FCC device authorization requirements mandate pre-market testing for Wi-Fi and cellular connectivity modules. Silicon Valley hardware startups and Shenzhen manufacturing partners coordinate firmware development cycles to satisfy FedRAMP-authorized cloud storage mandates for federal procurement.
Germany
GDPR Article 35 data protection impact assessments are mandating algorithmic documentation for facial recognition features sold across German industrial zones. BSI technical guidelines for IoT cybersecurity are tightening certification thresholds for cross-border sales. Munich and Stuttgart industrial clusters anchor demand from logistics warehouses requiring PoE-integrated perimeter hardening with centralized UPS backup.
China
MIIT radio transmission equipment type approval rules govern Wi-Fi and cellular module certification for domestic and export-bound production. Smart city infrastructure tenders under municipal governments in Shenzhen and Hangzhou are creating volume pipelines for weather-hardened bullet cameras. Yangtze River Delta manufacturing clusters concentrate CMOS sensor fabrication and edge AI chip packaging for cost-optimized export configurations.
India
Municipal surveillance tenders under the Ministry of Housing and Urban Affairs are generating demand for localized data residency-compliant hardware. BIS certification requirements for electronic products are extending time-to-market for European and North American vendors. Bangalore and Hyderabad technology corridors host system integrators configuring solar-powered installations for agricultural perimeter monitoring in Karnataka and Telangana.
United Kingdom
Home Office surveillance camera code of practice guidelines are shaping procurement specifications for local government security deployments. UKCA marking requirements post-Brexit are bifurcating certification workflows from EU CE marking processes. London and Manchester metropolitan areas concentrate commercial demand from retail chains and hospitality groups prioritizing insurance-linked risk transfer incentives.
Smart Outdoor Cameras Market Competitive Landscape
Listed leaders compete with private specialists across compliance capability and channel control dimensions. The vendor base separates into tiered positions based on in-house certification lab ownership versus third-party dependency. Three archetypes dominate: integrated manufacturers with captive testing infrastructure, platform-anchored brands with direct-to-consumer distribution, and component-assembly specialists sourcing inference engines from external silicon vendors. Competitive moves concentrate on M&A for cybersecurity certification assets and backward integration into image sensor supply.
Within the integrated manufacturing tier, Hangzhou Hikvision Digital Technology exemplifies vertical control over testing cycles and European shipment logistics. Amazon Ring occupies a position representing platform-anchored channel dominance across North American retail and direct-to-consumer pathways. Among component-assembly specialists, Arlo Technologies and Wyze Lab sit within the tier dependent on external foundry contracts and third-party algorithm licensing for edge AI features.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology |
| Amazon Ring |
| Google Nest |
| Arlo Technologies |
| SimpliSafe |
| ADT |
| Wyze Lab |
| Eufy (Anker Innovations) |
| TP-Link |
| Others |
Pricing and Supply Chain Analysis
Ninety-day CMOS sensor lead times from Taiwan and South Korea concentrate upstream bargaining power among tier-one vendors, compressing margin recovery for assembly specialists while FCC and EU cybersecurity certification costs inflate landed pricing for cross-border shipments.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with CE-marked and FedRAMP-authorized configurations commanding hardware premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by inference engine capability and cloud storage bundling. Cost compression in the economy tier intensifies because subscription unbundling at big-box retail displaces recurring revenue attachment. Residential buyers in United States coastal markets show highest price sensitivity, while government and critical infrastructure procurement teams prioritize compliance over unit cost.
Supply Chain Analysis
Inventory cycles stretching to sixteen weeks for edge AI system-on-chip modules expose mid-tier vendors to demand volatility and working capital strain. Component sourcing draws from Taiwan and South Korea for CMOS sensors, China for lithium battery cells and photovoltaic panels, and the United States for cloud infrastructure software. Single-source vulnerability in image sensor fabrication clusters amplifies disruption risk from regional logistics chokepoints. Distribution runs through direct-to-consumer platforms, North American retail chains, and European system integrators serving government and enterprise verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud storage subscription attach rates are expanding faster than hardware unit economics, converting transactional camera sales into recurring revenue platforms with superior lifetime value capture.
For Market Incumbents: Fortify compliance infrastructure by bringing FCC Part 15 and EU cybersecurity testing in-house, reducing time-to-market for European shipments while insulating margin pools from third-party certification cost inflation. Deepen backward integration into image sensor supply through multi-year foundry contracts with Taiwan and South Korea fabrication clusters, neutralizing single-source vulnerability that threatens production continuity. For New Entrants and Emerging Players: Lead with solar-powered configurations targeting agricultural perimeter monitoring in Australian cattle stations and Texas oilfield deployments, where trenching cost avoidance justifies premium positioning against wired alternatives. Capture white-space in Indian municipal surveillance tenders by pre-configuring localized data residency compliance for Ministry of Housing and Urban Affairs procurement specifications. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant IoT security divisions possessing captive cybersecurity certification labs and European channel relationships. Five-to-ten year viability hinges on subscription revenue conversion rates; monitor insurance-premium-linked installation penetration in United States coastal markets as inflection indicator for hardware-margin recovery models displacing cloud-dependent architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Lab Acquisition | Accelerates CE marking and FedRAMP authorization timelines for European and federal procurement eligibility. |
| 5G RedCap Module Integration | Enables battery-optimized cellular backup for rural commercial sites lacking fixed broadband infrastructure. |
| Subscription Unbundling Response | Tiered firmware feature gates reserve AI classification for recurring payment activation in price-sensitive segments. |
| Solar Configuration Expansion | Trenching cost avoidance penetrates agricultural and utility substation monitoring in remote-site deployments. |
| GDPR DPIA Documentation Investment | Algorithmic audit trails satisfy Article 35 requirements and insurer underwriting for biometric-enabled deployments. |
Research Methodology
Initial hypotheses were tested against primary input from security system integrators, municipal procurement officers, cloud platform engineers, and insurance risk assessors and refined through secondary validation against FCC device authorization filings, EU cybersecurity certification registries, SEC 10-K hardware disclosures, and hyperscaler IoT capex data. Bottom-up unit economics modeling triangulated with top-down market sizing across product type, installation configuration, end-user vertical, and connectivity technology segments.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within installation type and end-user categories. Segmentation dimensions modeled include form factor specifications, power infrastructure requirements, application risk tolerance, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating AI inference adoption rates, solar configuration penetration trajectories, and compliance cost pass-through assumptions.
The analysis sits within stated boundaries; outcomes outside sustained lithium battery chemistry regulatory stability or Wi-Fi spectrum allocation continuity would require recalibration. Forecasts reflect documented assumptions regarding insurance-premium linkage adoption and municipal tender pipeline conversion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Japan Surveillance IP Cameras Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market